
 Tin Fluoborate Market | 2026-2036
Tin Fluoborate Market Size, Share, and Industry Trends Forecast 2026-2036
Tin Fluoborate Market Analytics
Buyer concentration across the metal finishing sector is expanding as tier-one electroplating houses consolidate procurement volumes for tin fluoborate solutions. Kuntz Electroplating Inc. anchors North American demand through captive consumption across automotive and industrial plating lines. Transpek-Silox Industry Ltd. dominates Indian supply channels with backward integration into fluoroborate chemistry. Muby Chemicals sustains export competitiveness through specialized crystalline grade production.
Tin fluoborate (Sn(BF4)2) is an inorganic salt typically supplied as a 50% aqueous solution, functioning primarily as an electrolyte in tin electroplating baths and as a fluxing agent in soldering applications. The compound dissolves metallic oxides at low temperatures, enabling uniform tin deposition onto copper, brass, and steel substrates without residual chloride contamination. Liquid formulations command the largest volume share due to handling convenience in continuous plating operations, while crystalline grades capture premium pricing from analytical reagent and specialty catalyst buyers. Flame retardant applications represent the fastest-expanding segment as tin-based synergists displace antimony trioxide in halogen-free polymer systems. Bulk packaging dominates chemical distributor channels, though drum formats prevail in electronics industry direct procurement.
EPA effluent guidelines under the Clean Water Act restrict boron and fluoride discharge from plating facilities, forcing end-users toward closed-loop bath management and higher-purity tin fluoborate inputs. REACH registration requirements in Europe mandate full substance characterization, elevating compliance costs for non-EU suppliers while creating market access barriers for unregistered imports. Stakeholders must monitor evolving RoHS exemptions for tin-lead alternatives and assess captive fluoboric acid production as a hedge against feedstock volatility.
Market Dynamics
Semiconductor packaging miniaturization is compressing plating bath tolerances, forcing tin fluoborate suppliers to tighten impurity specifications below 10 ppm for advanced flip-chip interconnects.
Growth Catalysts
- RoHS exemption phase-outs:European ECHA reviews of tin-lead solder alternatives are accelerating tin fluoborate adoption in high-reliability electronics plating.
- Halogen-free flame retardant mandates:China's GB standards for consumer electronics are displacing antimony trioxide with tin-boron synergists in polymer formulations.
- Precision metal finishing clusters:German automotive suppliers in Baden-Württemberg are consolidating captive tin fluoborate consumption for sensor housing metallization.
Market Restraints
- Fluoboric acid feedstock volatility:Hydrofluoric acid price swings and Chinese export licensing for fluorochemical precursors create input cost instability.
- Boron discharge limits:EPA effluent guidelines under the Clean Water Act impose treatment capex burdens on plating facilities using tin fluoborate baths.
- Methanesulfonic acid substitution:Lower-toxicity tin plating electrolytes are capturing share in decorative applications with less stringent performance requirements.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for semiconductor assembly are creating fresh demand for high-purity tin fluoborate in Bengaluru and Chennai clusters.
- Closed-loop bath regeneration:Ion-exchange recovery systems are enabling service-based revenue models tied to plating chemical management rather than commodity sales.
- South Korean battery interconnects:Cylindrical cell tab welding flux requirements are opening specialty tin fluoborate grades for lithium-ion manufacturing.
Industry Challenges
- Analytical chemist scarcity:Boron and fluoride speciation testing for REACH dossiers requires specialized expertise that contract labs struggle to staff.
- Legacy chloride bath retrofit costs:Electroplating houses face line downtime and compatibility testing when converting existing infrastructure to fluoborate chemistry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tin Fluoborate Market |
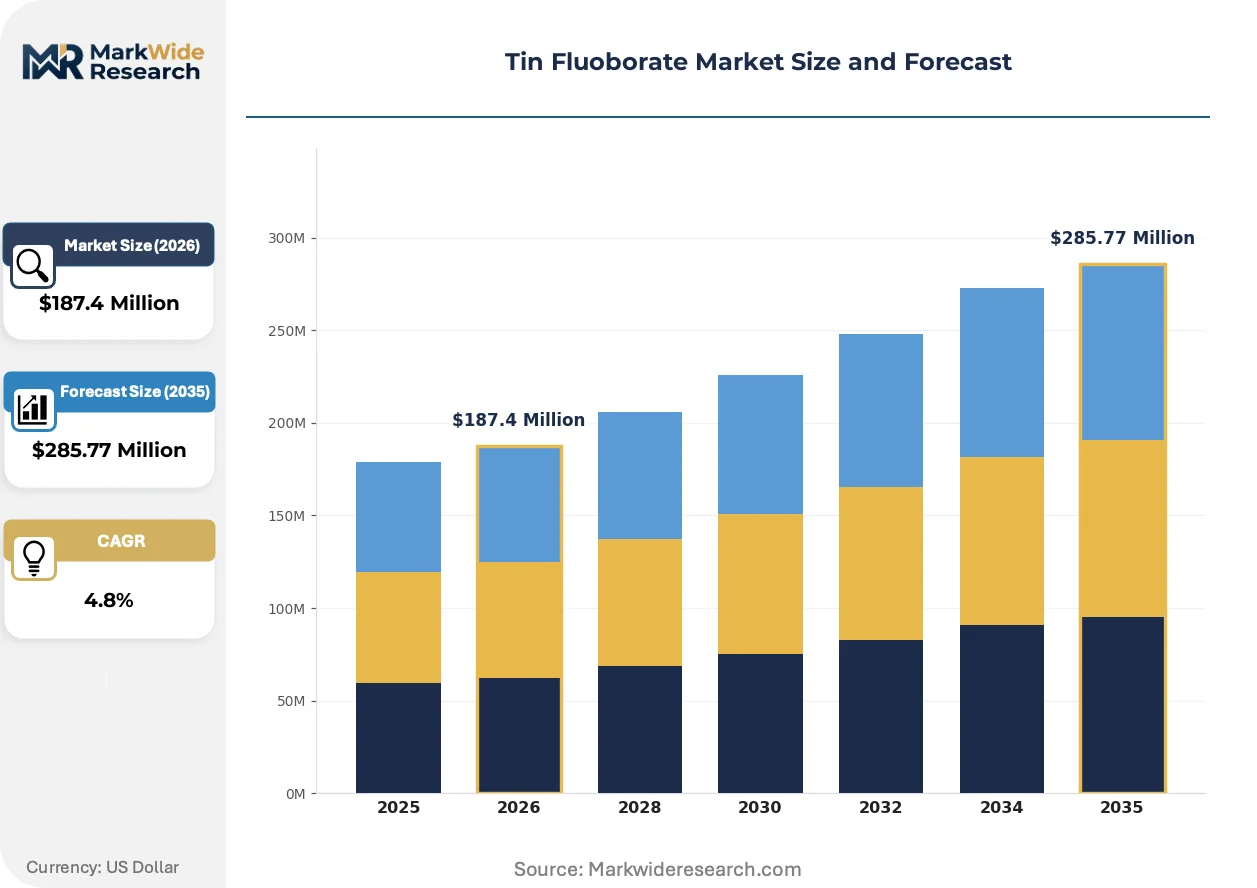
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Crystalline, Liquid End Use Industry: Chemicals, Electronics, Coatings, Metal Finishing Application: Flame Retardants, Corrosion Inhibitors, Fluxing Agents, Catalysts Packaging Type: Bags, Drums, Containers, Bulk Packaging |
| Companies Covered | Kuntz Electroplating Inc., Crest Chemicals, Muby Chemicals, Transpek-Silox Industry Ltd., Lincoln Chemical Corporation, Strem Chemicals, Sharretts Plating Company, SGR (India) Chemical, Harshil Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tin Fluoborate Market Evolving Landscape
Plating bath chemistry is fragmenting into application-specific formulations as end-users reject universal-grade tin fluoborate in favor of certified, traceable supply chains.
Continuous electrodeposition systems for wafer-level packaging are modularizing tin fluoborate delivery through automated dosing skids that integrate directly with fab chemical management infrastructure. Taiwan semiconductor foundries are piloting these units for copper pillar bump plating. The technology is compressing chemical consumption variance from 15% to under 3% per bath cycle.
REACH authorization requirements for boron compounds are forcing full substance characterization including impurity profiling down to 0.1% w/w. European electroplating houses must document supply chain transparency or face import restrictions. German automotive tier-one suppliers are now requiring batch-level certificates of analysis from tin fluoborate vendors.
Direct procurement contracts are displacing distributor intermediaries as electronics OEMs consolidate plating chemical purchasing under central supply chain functions. Foxconn and Pegatron have established qualified supplier lists with locked pricing for tin fluoborate across their Asian assembly networks. This concentration is most visible in Chinese coastal provinces where plating houses serve multiple contract manufacturers from shared facilities.
Tin Fluoborate Market Segmentation
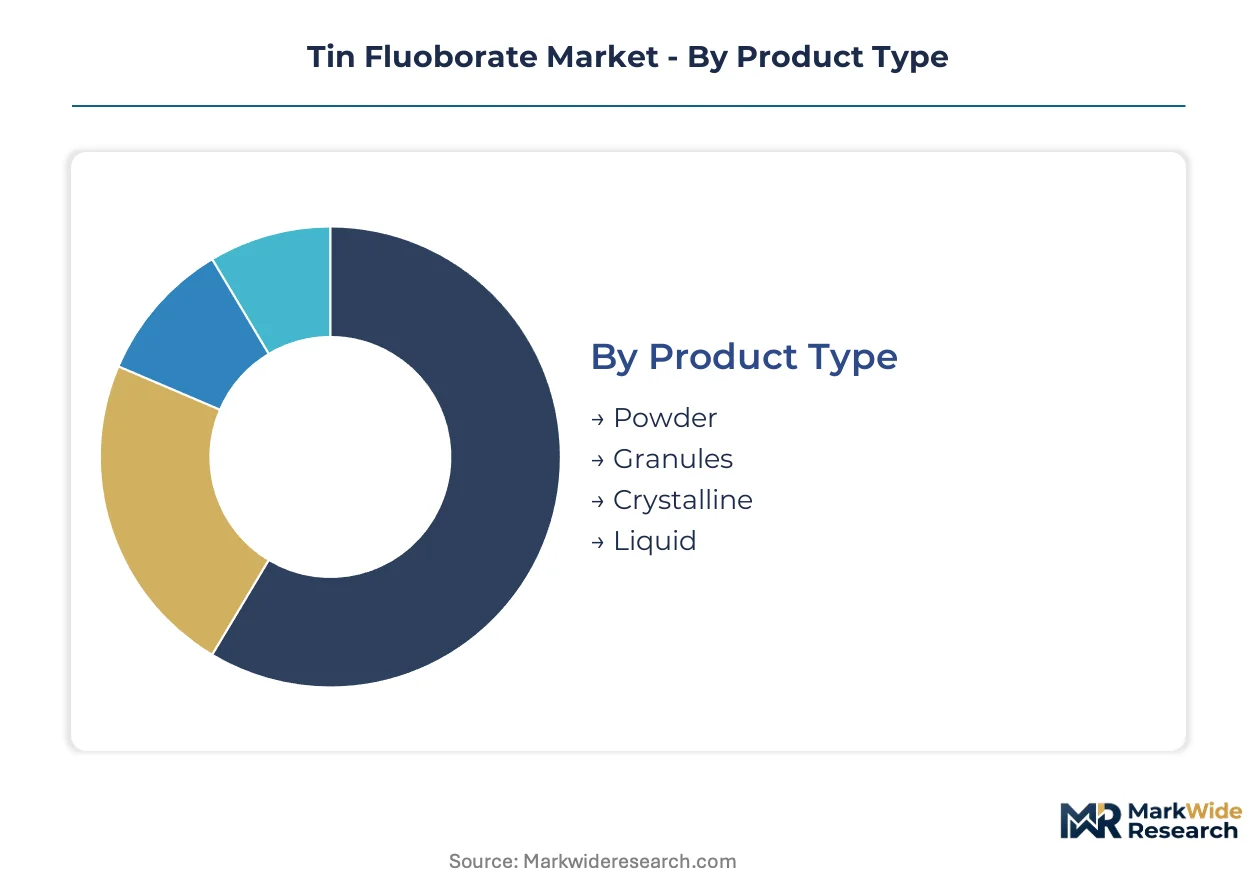
Tin fluoborate formulations diverge sharply in certification intensity across product grades, with semiconductor-facing segments demanding REACH dossier completeness while industrial grades navigate simpler EPA discharge compliance. Application-specific purity thresholds fragment procurement channels, creating non-overlapping supplier ecosystems between electronics plating and polymer additive buyers.
Product Type:
Liquid formulations carry the heaviest certification burden for electronics customers, requiring batch-level certificates of analysis documenting impurity profiles below 10 ppm for flip-chip interconnect applications. Crystalline and powder grades face lighter analytical requirements but must still satisfy REACH substance characterization down to 0.1% w/w for European chemical distribution.
- Liquid:Supplied as 50% aqueous solution optimized for continuous tin electroplating operations. Semiconductor packaging houses in Taiwan and South Korea specify sub-10 ppm impurity ceilings for advanced bump plating, compressing supplier qualification timelines. Closed-loop bath regeneration systems favor liquid handling infrastructure.
- Crystalline:High-purity solid form commanding premium positioning from analytical reagent and specialty catalyst buyers. German automotive tier-one suppliers mandate batch-level CoA documentation for sensor housing metallization workflows. REACH authorization requirements for boron compounds elevate European procurement friction for unregistered imports.
- Powder:Industrial-grade solid used in fluxing compound manufacturing and bulk chemical synthesis. Chinese plating chemical distributors favor powder for inland logistics cost efficiency over liquid freight.
- Granules:Intermediate physical form serving soldering flux premix operations and selected flame retardant masterbatch production. Handling characteristics suit mid-scale compounders without liquid storage infrastructure.
Liquid sits at the top of the volume ranking, with crystalline climbing the fastest.
End Use Industry:
Cost tier separation runs deepest across end-use industries, with electronics plating absorbing 40-60% price premiums for semiconductor-grade material against commodity chemical applications.
- Electronics:Wafer-level packaging and printed circuit board plating drive specifications tightest. Foxconn and Pegatron consolidated procurement functions now lock pricing through qualified supplier lists across Asian assembly networks. Miniaturization trends compress bath tolerance windows.
- Metal Finishing:Automotive sensor housings and industrial component metallization anchor steady demand. Baden-Württemberg precision clusters in Germany consolidate captive consumption for tin fluoborate solutions.
- Chemicals:Intermediate synthesis and specialty reagent production absorb standard-grade material with less stringent impurity ceilings. Indian fluoroborate chemistry specialists serve this tier through backward-integrated supply chains.
- Coatings:Protective and functional surface treatments for industrial equipment. Methanesulfonic acid substitution pressure concentrates in decorative coating segments with relaxed performance requirements.
Electronics dominates absolute volume, with metal finishing expanding most quickly on automotive electrification trends.
Application:
Application maturity determines margin structure, with established electroplating uses defending price stability against emerging flame retardant demand capturing volume growth.
- Flame Retardants:Tin-boron synergists displace antimony trioxide in halogen-free polymer systems under China's GB standards for consumer electronics. Polymer formulators represent the steepest expansion trajectory among application segments.
- Fluxing Agents:Low-temperature oxide dissolution enables uniform tin deposition onto copper, brass, and steel substrates. Cylindrical lithium-ion cell tab welding in South Korean battery manufacturing opens specialty grade requirements.
- Catalysts:Organic synthesis and petrochemical process applications. Crystalline grade specifications predominate with analytical reagent purity thresholds.
- Corrosion Inhibitors:Protective formulations for metal surface preservation. Industrial maintenance chemical distributors channel standard-grade liquid formulations.
Fluxing agents hold volume leadership, with flame retardants gaining share fastest on regulatory displacement mandates.
Packaging Type:
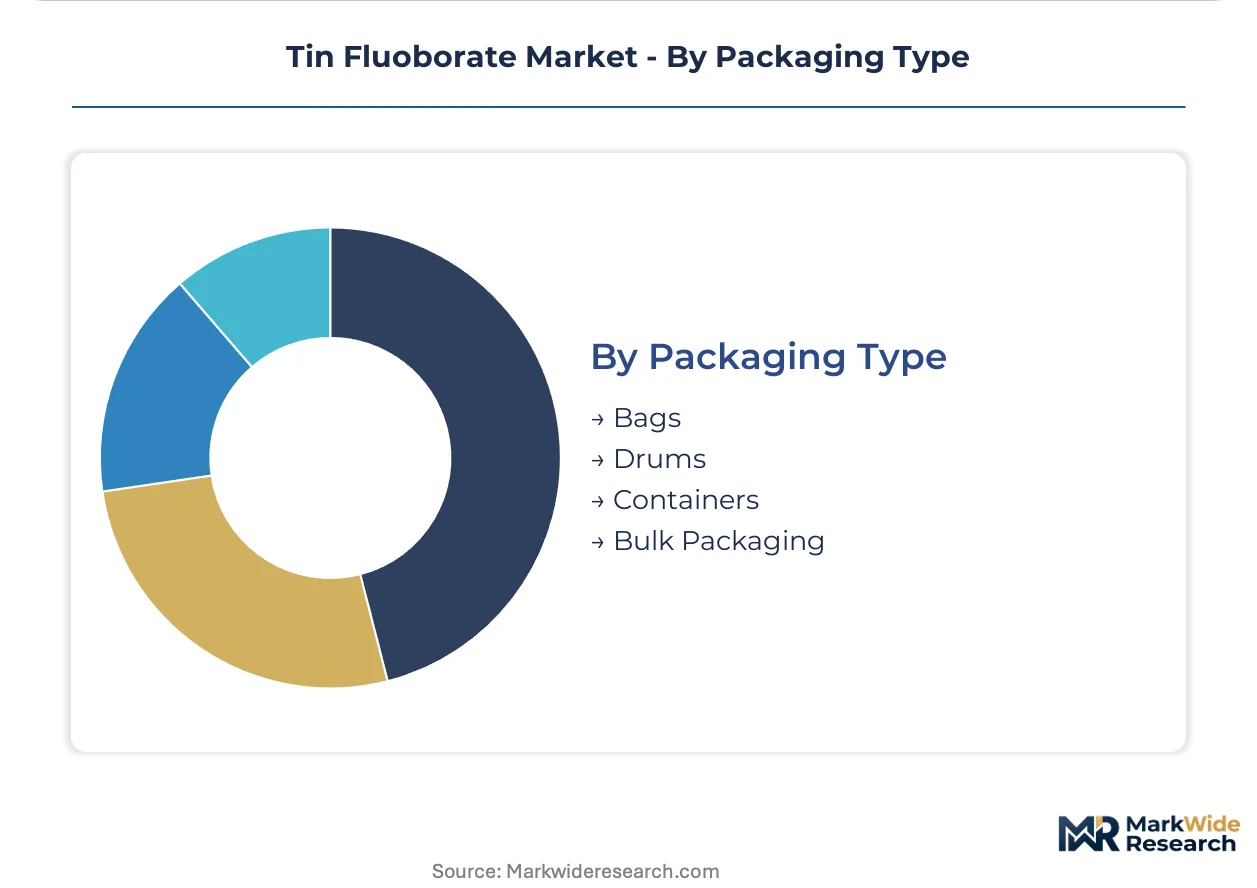
Customer type fragmentation separates packaging preferences, with electronics OEMs mandating drum formats for direct procurement while chemical distributors absorb bulk volumes for fragmented resale.
- Bulk Packaging:Tanker and tote configurations dominate chemical distributor channels serving fragmented metal finishing houses. Freight efficiency favors high-volume procurement from backward-integrated manufacturers.
- Drums:Standard 200-liter format prevailing in electronics industry direct procurement. Foxconn and Pegatron assembly networks specify drum delivery for qualified supplier integration.
- Containers:Intermediate volumes for specialty compounders and regional plating operations. Flexibility suits multi-product chemical management infrastructure.
- Bags:Powder and granule formats for flux premix and masterbatch compounders. Chinese inland logistics favor bagged solid forms over liquid freight cost structures.
Bulk packaging leads volume throughput, with drums expanding most quickly on electronics OEM procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the heaviest plating chemical throughput, while Germany enforces the tightest purity certification regimes for automotive electronics.
China
Semiconductor packaging expansion and consumer electronics assembly drive tin fluoborate consumption along the eastern seaboard. GB standards for halogen-free flame retardants accelerate tin-boron synergist substitution in polymer formulations. Yangtze River Delta plating clusters around Shanghai and Suzhou consolidate procurement volumes for Foxconn and Pegatron supplier networks.
Germany
Automotive sensor housing metallization and precision metal finishing anchor steady demand from tier-one suppliers. REACH authorization requirements for boron compounds mandate full substance characterization down to 0.1% w/w. Baden-Württemberg industrial clusters concentrate captive consumption for electroplating solutions serving Bosch and Continental supply chains.
United States
Defense electronics plating and industrial component finishing sustain demand despite methanesulfonic acid substitution pressure in decorative segments. EPA effluent guidelines under the Clean Water Act impose boron discharge limits requiring closed-loop bath management. Michigan and Ohio automotive plating corridors absorb standardized liquid formulations for powertrain component metallization.
South Korea
Wafer-level packaging miniaturization compresses plating bath tolerances for advanced flip-chip interconnects. MFDS chemical substance notification requirements align with REACH-equivalent transparency standards. Seoul Capital Area foundries and Busan-Ulsan battery manufacturing clusters drive specialty grade requirements for cylindrical cell tab welding flux.
India
PLI scheme incentives for semiconductor assembly and electronics manufacturing create fresh demand in Bengaluru and Chennai production hubs. BIS certification requirements for electroplating chemicals elevate import compliance friction for unregistered suppliers. Gujarat fluoroborate chemistry specialists leverage backward-integrated supply chains to serve domestic metal finishing houses.
Tin Fluoborate Market Competitive Landscape
Chinese producers anchor one tier; Indian specialists hold regional supply chain dominance through captive fluoboric acid production. The vendor base stratifies across three tiers: multinational electroplating houses with captive chemical consumption, regional fluoroborate manufacturers with backward-integrated feedstock control, and specialty distributors serving fragmented industrial end-users. Consolidation pressures concentrate procurement volumes among tier-one plating houses, while REACH compliance costs create market access barriers for unregistered imports. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers secure qualified supplier status with electronics OEMs.
Among North American electroplating houses, Kuntz Electroplating Inc. exemplifies the captive consumption archetype through integrated automotive and industrial plating lines. Indian specialists Transpek-Silox Industry Ltd. and Muby Chemicals occupy positions within the regional supply tier, with the former representing backward-integrated fluoroborate chemistry capabilities and the latter anchoring export competitiveness through crystalline grade specialization. These three companies illustrate the geographic and structural segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Kuntz Electroplating Inc. |
| Crest Chemicals |
| Muby Chemicals |
| Transpek-Silox Industry Ltd. |
| Lincoln Chemical Corporation |
| Strem Chemicals |
| Sharretts Plating Company |
| SGR (India) Chemical |
| Harshil Industries |
| Others |
Value Network & Pricing Analysis
Hydrofluoric acid feedstock costs cascade through tin fluoborate pricing tiers, with Chinese export licensing volatility for fluorochemical precursors compressing margins at the liquid formulation level while crystalline grade producers in Germany defend premiums through REACH dossier completeness.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade tin fluoborate as PLI scheme incentives attract electroplating chemical investments. Three-tier pricing structure across semiconductor-grade, automotive-certified, and industrial-standard levels separates Foxconn-qualified suppliers from commodity distributors. Cost compression in liquid formulations is intensifying because methanesulfonic acid substitution pressure concentrates in decorative coating segments. Electronics OEMs show least price sensitivity for sub-10 ppm impurity specifications, while inland Chinese plating houses absorb economy-tier powder grades.
Supply Chain Analysis
Dual-sourcing requirements from German automotive tier-one suppliers mandate multi-supplier qualification for REACH-registered boron compounds, fragmenting procurement across Chinese liquid producers and Indian crystalline specialists. Supply concentrates in China, Germany, and India for distinct grade tiers. Fluoboric acid, hydrofluoric acid, and metallic tin feedstocks draw from captive production in Gujarat and Yangtze River Delta clusters. Single-source vulnerability sits with Chinese export licensing for fluorochemical precursors. Distribution runs through qualified supplier lists for electronics OEMs and chemical distributor networks for fragmented metal finishing houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe elevate procurement friction against Indian backward-integrated supply chains serving price-sensitive Asian electronics assembly.
For Market Incumbents: Deepen captive fluoboric acid production in Gujarat and Yangtze River Delta hubs to hedge against hydrofluoric acid price volatility and Chinese export licensing restrictions. Secure qualified supplier status with Foxconn and Pegatron procurement functions before methanesulfonic acid substitution erodes decorative plating share. Invest in batch-level certificate of analysis infrastructure for German automotive tier-one documentation requirements. For New Entrants and Emerging Players: Begin with flame retardant polymer formulations under China's GB standards for halogen-free consumer electronics, where tin-boron synergist displacement of antimony trioxide creates specification-grade white space. Target Bengaluru and Chennai semiconductor assembly clusters where PLI scheme incentives compress supplier qualification timelines. Lead with closed-loop bath regeneration service models rather than commodity chemical sales. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration costs for boron compounds exceed $500,000 per substance, forcing unregistered Chinese exporters toward acquisition by EU-qualified holders. Mid-term viability hinges on qualified supplier list penetration with Taiwan and South Korean foundries. Watch for MFDS chemical substance notification alignment with REACH-equivalent standards as inflection signal for South Korean battery interconnect demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoboric Acid | Gujarat specialists anchor feedstock control against Chinese export licensing volatility. |
| REACH Dossier Completion | Full substance characterization down to 0.1% w/w unlocks German automotive tier-one supply chains. |
| Closed-Loop Bath Regeneration | Ion-exchange recovery systems enable service-based revenue models at Taiwan semiconductor foundries. |
| Long-term Supply Agreement | Locked pricing with Foxconn and Pegatron consolidates procurement across Asian assembly networks. |
| Joint Venture for Semiconductor Grade | Partnerships with Seoul Capital Area foundries capture cylindrical cell tab welding flux demand. |
Research Methodology
Coverage spans China, Germany, India, South Korea, and the United States, with primary inputs from each combining electroplating house procurement directors, fluoroborate plant managers, semiconductor packaging engineers, chemical distribution channel partners, and REACH regulatory consultants. Secondary validation draws from customs trade data, ECHA registration dossiers, EPA effluent guideline filings, and SEC 10-K disclosures from listed electroplating houses. Bottom-up demand modeling triangulates against top-down production capacity assessments.
Granularity extends to product type, end-use industry, application, and packaging format dimensions, with additional modeling for certification intensity tiers across REACH-registered versus standard-grade supply. Value projections across the analysis window compound annual growth rates derived from segment-level demand elasticity and input cost trajectory assumptions. Semiconductor packaging miniaturization trends and flame retardant regulatory displacement schedules feed directly into application-level forecasts.
Several conditions sit outside the modeled scope, including unscheduled RoHS exemption extensions for tin-lead solder alternatives and abrupt Chinese fluorochemical export license suspensions. Forecasts reflect assumptions about stable EPA effluent guideline enforcement and progressive REACH authorization timelines for boron compounds. Deviation in hydrofluoric acid feedstock availability or ECHA substance evaluation acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Furfural Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Europe Caustic Soda Market
Bulk Chemicals
Europe Ammonium Nitrate Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Castor Wax Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
2,6-Dichlorobenzaldehyde Market