
 Asia-Pacific Quicklime Market | 2026-2036
Asia-Pacific Quicklime Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Quicklime Market Outlook
Buyer concentration among Asia-Pacific steel producers is rebalancing as Chinese mills consolidate procurement while Southeast Asian mini-mills fragment supply relationships. Carmeuse extends its terminal network across coastal Vietnam and Indonesia to capture dispersed demand. Lhoist Group anchors production through captive limestone quarries in Malaysia and Thailand. Sichuan Golden Summit Group dominates high-calcium lime output for western China's chemical corridor.
Quicklime, or calcium oxide, is produced by calcining limestone at temperatures exceeding 900 degrees Celsius in vertical or rotary kilns, yielding a highly reactive alkaline material with typical calcium oxide content ranging from 90 to 95 percent. Its primary industrial purpose centers on pH modification, fluxing in metallurgical processes, and sulfur capture in environmental applications. Steel manufacturing applications command the largest volume share due to integrated mill demand across China and India, while environmental management segments are expanding fastest as flue gas desulfurization mandates tighten. High-calcium lime products carry premium positioning where chemical purity specifications are stringent.
China's MEE enforces emissions intensity caps on kiln operations, forcing upgrades to vertical shaft kilns or suspension preheater systems. India's CEA mandates limestone injection for thermal power sulfur control, directly lifting utility-sector quicklime procurement. BIS certification requirements for construction-grade lime create compliance barriers for unorganized producers. Stakeholders must monitor regulatory divergence between Chinese emissions trading schemes and India's sector-specific mandates to align capacity investments with enforceable standards.
Market Dynamics
Steelmakers across eastern China's industrial corridor are consolidating procurement contracts while kiln operators face MEE emissions intensity caps that mandate vertical shaft kiln upgrades or suspension preheater retrofits.
Growth Catalysts
- MEE emissions intensity caps:China's Ministry of Ecology and Environment mandates kiln technology upgrades, forcing capital deployment into cleaner calcination systems and expanding the addressable market for advanced refractory suppliers.
- Flue gas desulfurization mandates:India's Central Electricity Authority requires limestone injection for thermal power sulfur control, directly lifting utility-sector quicklime procurement volumes across coal-dependent states.
- Integrated steel mill clustering:Eastern China's concentration of blast furnace operations near Shandong and Hebei limestone deposits creates dense, logistics-efficient demand nodes for slag conditioning materials.
Market Restraints
- Dolomitic limestone supply concentration:High-purity dolomite reserves concentrate in specific Vietnamese and Malaysian mining districts, exposing processors to single-source geological risk and freight cost volatility.
- Natural gas price sensitivity:Rotary kiln operations remain exposed to LNG import price swings across Japan and South Korea, compressing margin stability for energy-intensive calcination.
- Hydrated lime substitution:Water treatment and construction applications in Australia's urban centers increasingly specify hydrated lime for handling safety, displacing quicklime in non-metallurgical segments.
Strategic Opportunities
- Indonesia's nickel processing expansion:HPAL-based battery precursor plants in Sulawesi and Halmahera require high-calcium lime for pH control, opening metallurgical-grade demand outside traditional steel applications.
- Carbon capture retrofits:Calcium looping systems for post-combustion CO2 capture are expanding into South Korean cement and power stacks, creating premium lime specifications for sorbent regeneration cycles.
- Port terminal networks:Coastal Vietnam and Indonesia lack dedicated quicklime bulk handling infrastructure, enabling first-mover logistics players to capture dispersed mini-mill demand through import substitution.
Industry Challenges
- Kiln refractory engineering expertise:Suspension preheater retrofits require specialized thermal design capabilities scarce outside established Chinese and Japanese equipment vendors.
- BIS certification timelines:India's Bureau of Indian Standards construction-grade lime approvals impose multi-month testing protocols that delay market entry for new Rajasthan and Gujarat producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Quicklime Market |
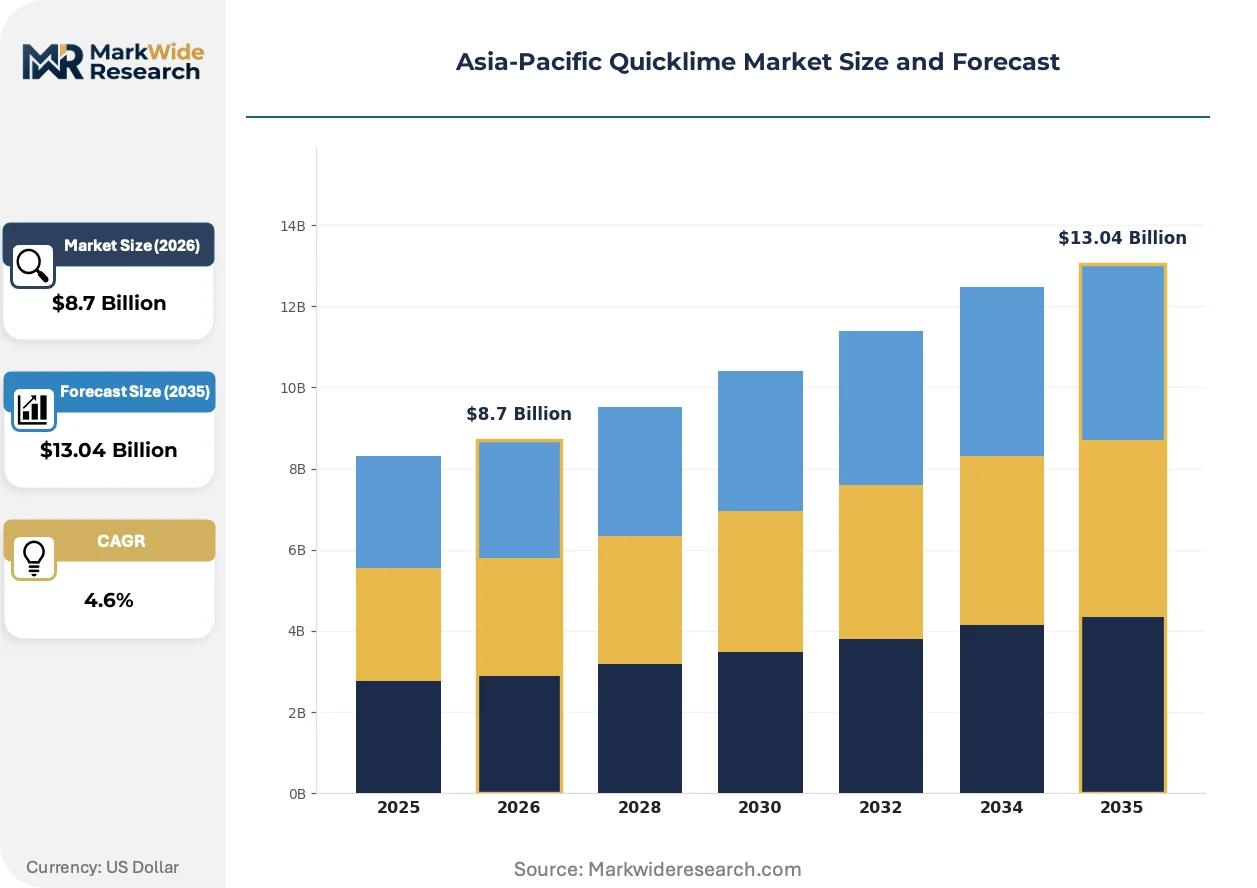
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Construction, Steel Manufacturing, Environmental Management, Water Treatment Product Type: Hydrated Lime, Calcined Lime, High-Calcium Lime, Dolomitic Lime End User: Chemical Industry, Paper Manufacturing, Agriculture, Mining Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | United States Lime & Minerals, Sichuan Golden Summit Group, Carmeuse, Pacific Lime and Cement, Hubei Zhongwei Calcium Industry Co. Ltd, Lhoist Group, Anhui Fengyang Mingdi Calcium Industry Co. Ltd, Sigma Minerals Ltd, Graymont Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Quicklime Market Strategic Shifts
Calcination technology is bifurcating between energy-efficient vertical shaft upgrades and digital kiln control systems, while regulatory pressure on emissions intensity accelerates capital rotation across the region's installed base.
Maerz parallel-flow regenerative kilns are expanding into Chinese and Vietnamese lime operations seeking thermal efficiency above 800 kcal per kilogram of lime. Steelmakers in Jiangsu and Zhejiang provinces specify PFR output for consistent reactivity in slag conditioning. The technology is compressing fuel cost differentials between coastal importers and inland captive producers.
China's MEE dual carbon implementation pathway tightens emissions monitoring through continuous emissions monitoring systems tied to provincial carbon trading registries. Kiln operators must install automated fuel-to-air ratio controls or face production quota penalties. Shandong and Hebei provinces are responding fastest, with state-owned limestone processors leading retrofit deployment.
Long-term offtake contracts are displacing spot procurement across Asia-Pacific steel procurement desks. Japanese integrated mills now structure three to five-year supply agreements with fixed-volume, indexed-price terms. This behavior concentrates supplier relationships around Carmeuse and Lhoist terminal networks while marginalizing unorganized Chinese traders in coastal markets.
Asia-Pacific Quicklime Market Segmentation
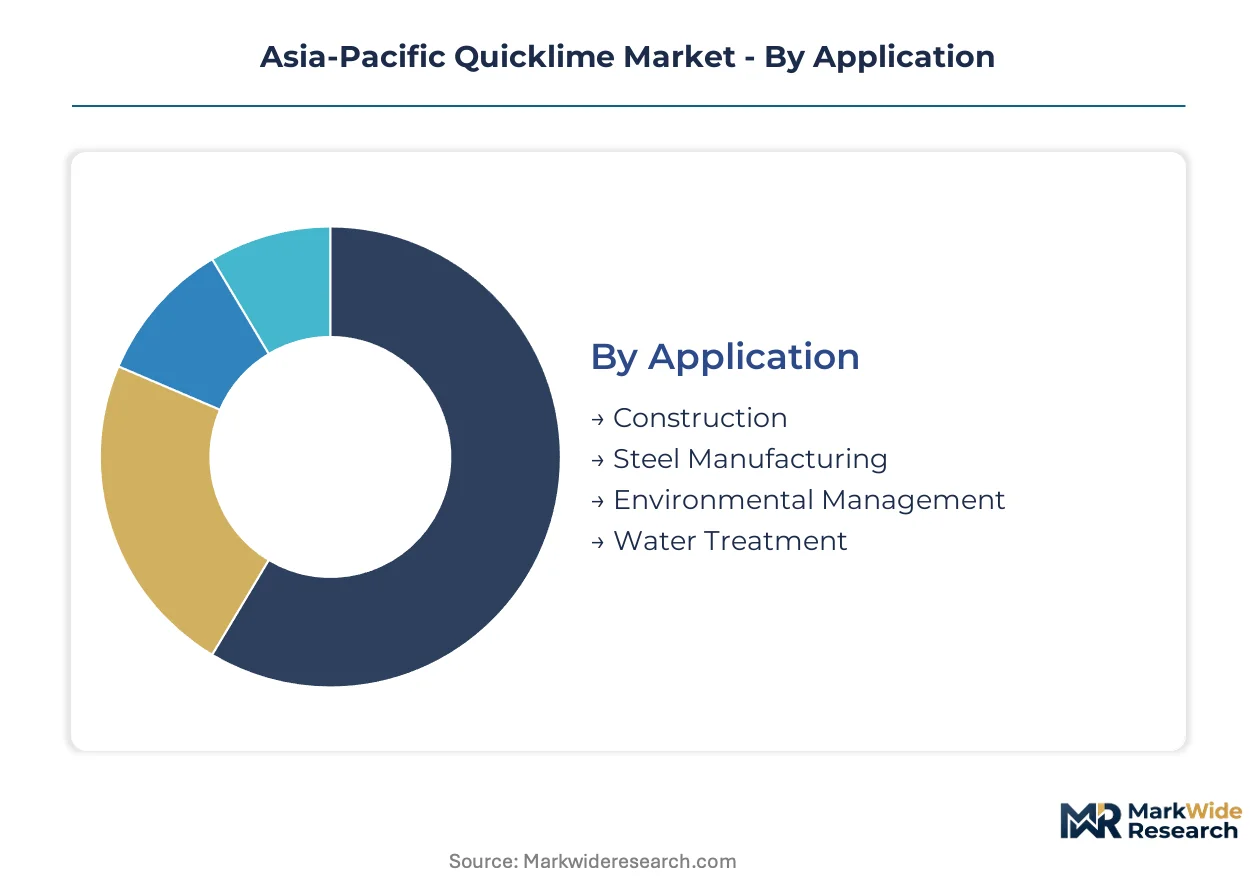
Quicklime procurement patterns diverge sharply across metallurgical, environmental, and construction verticals, with each application imposing distinct purity specifications and logistics requirements. Steel manufacturers dominate volume offtake while environmental compliance mandates reshape product mix toward high-calcium grades.
Application:
Supply concentration in eastern China's industrial corridor funnels the majority of metallurgical-grade output toward integrated steel complexes, while environmental applications fragment procurement across dispersed utility and municipal buyers.
- Steel Manufacturing:Slag conditioning and fluxing operations consume quicklime with 90-95% calcium oxide content for impurity removal during blast furnace and basic oxygen steelmaking. Procurement concentrates at Shandong and Hebei mills near captive limestone deposits, with MEE emissions caps forcing kiln technology upgrades that tighten supplier qualification criteria.
- Environmental Management:Flue gas desulfurization systems at coal-fired power plants and industrial stacks require high-reactivity lime for sulfur dioxide capture. India's CEA mandates drive procurement volume expansion across Maharashtra, Gujarat, and Tamil Nadu thermal corridors, though handling complexity limits supplier participation to terminal-equipped distributors.
- Construction:Soil stabilization and masonry applications specify construction-grade lime with moderate reactivity tolerances. BIS certification requirements screen out unorganized Rajasthan and Gujarat producers, consolidating supply around established regional processors.
- Water Treatment:pH adjustment and coagulation processes in municipal treatment plants favor hydrated lime for operational safety, displacing quicklime in urban Australian and Japanese utilities where labor regulations restrict caustic material handling.
Today's leader: Steel Manufacturing. Tomorrow's challenger: Environmental Management.
Product Type:
Cost tier differentiation separates premium high-calcium specifications from standard construction grades, with calcination technology investments determining competitive positioning across purity bands.
- High-Calcium Lime:Products exceeding 95% calcium oxide content command premium positioning for chemical and metallurgical applications where trace impurity tolerance is minimal. Sichuan Golden Summit Group anchors western China supply for the chemical corridor, while Maerz PFR kiln operators capture margin advantages through thermal efficiency above 800 kcal per kilogram.
- Calcined Lime:Standard metallurgical and construction grades produced in vertical shaft or rotary kilns at 900-1200°C calcination temperatures. Eastern Chinese steel mills specify consistent reactivity ranges for slag conditioning, with procurement consolidating around state-owned limestone processors in Shandong.
- Hydrated Lime:Calcium hydroxide formed through controlled slaking of quicklime, preferred for water treatment and construction applications where dust exposure and handling safety constrain quicklime adoption. Australian urban utilities increasingly mandate hydrated lime specifications.
- Dolomitic Lime:Magnesium-calcium oxide blends from dolomite limestone calcination, supplying specialized refractory and glass manufacturing applications. High-purity dolomite reserve concentration in Vietnamese and Malaysian mining districts exposes processors to single-source geological risk.
Premium positioning clusters at High-Calcium Lime. Volume scaling concentrates at Calcined Lime.
End User:
Customer type fragmentation spans integrated chemical complexes, dispersed agricultural operations, and capital-intensive mining ventures, each imposing distinct technical service and logistics requirements.
- Chemical Industry:Petrochemical and specialty chemical manufacturers require precise reactivity control for acetylene production, alkali manufacturing, and calcium carbide synthesis. Western China's Sichuan chemical corridor anchors concentrated demand for ultra-high-purity grades.
- Mining:Gold and copper heap leaching operations, plus nickel laterite processing in Indonesia's Sulawesi and Halmahera HPAL facilities, consume metallurgical-grade lime for pH control and metal recovery. Indonesia's nickel processing expansion opens demand outside traditional steel applications.
- Paper Manufacturing:Kraft pulping and effluent treatment applications specify controlled reactivity lime for causticizing and pH management. Japanese and South Korean integrated mills structure long-term offtake contracts with fixed-volume, indexed-price terms.
- Agriculture:Soil amendment and livestock sanitation applications fragment procurement across smallholder cooperatives and commercial farming operations, with seasonal demand patterns complicating inventory planning for regional distributors.
Chemical Industry holds margin leadership. Mining offers the steepest expansion trajectory.
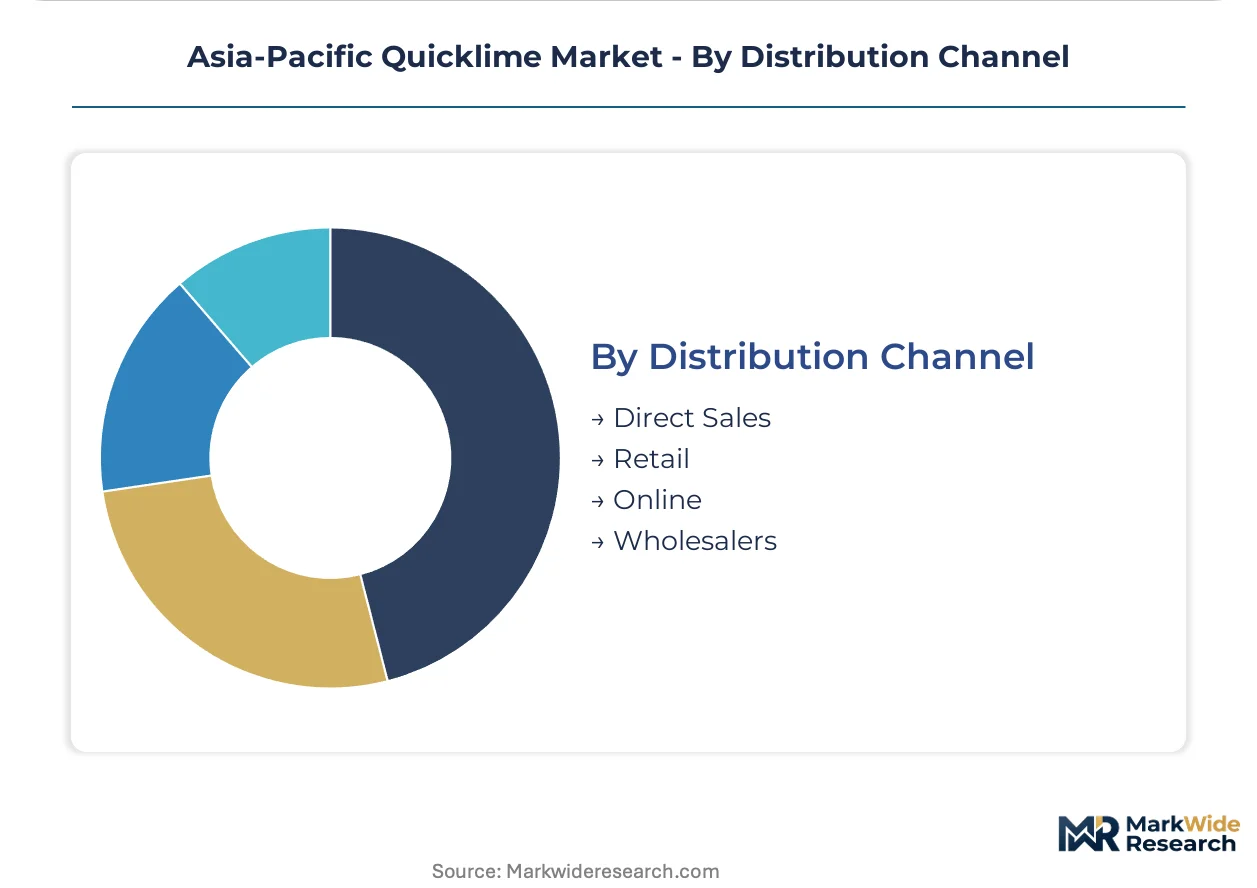
Distribution Channel:
Channel maturity reflects customer scale concentration, with direct sales dominating integrated industrial procurement while wholesalers capture fragmented agricultural and construction demand.
- Direct Sales:Long-term supply agreements between kiln operators and steel mills, chemical complexes, and power utilities eliminate intermediary margins. Japanese integrated mills now structure three to five-year contracts with Carmeuse and Lhoist terminal networks, displacing spot procurement.
- Wholesalers:Regional distributors aggregate construction-grade and agricultural lime volumes for dispersed mini-mill, contractor, and farming customers. Coastal Vietnam and Indonesia lack dedicated bulk handling infrastructure, enabling first-mover logistics players to capture import substitution opportunities.
- Retail:Bagged lime products for small-scale construction and agricultural applications flow through building material merchants and farm supply cooperatives, with BIS certification requirements filtering product availability in India.
- Online:Digital procurement platforms remain nascent for bulk industrial minerals, constrained by freight logistics complexity and quality verification requirements, though technical documentation portals support contract negotiation for standardized grades.
Direct Sales commands volume concentration. Wholesalers unlock geographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's integrated steel corridor generates quicklime demand volumes that dwarf India's fragmented utility procurement, yet both markets face tightening emissions frameworks that reshape calcination economics.
China
Shandong and Hebei provinces host dense clusters of blast furnace operations that consume metallurgical-grade quicklime for slag conditioning. MEE emissions intensity caps mandate vertical shaft kiln upgrades or suspension preheater retrofits across state-owned limestone processors. Qingdao and Tangshan terminals anchor coastal import substitution networks serving dispersed mini-mills.
India
Maharashtra, Gujarat, and Tamil Nadu thermal corridors drive utility-sector quicklime procurement under CEA-mandated limestone injection for sulfur control. BIS certification requirements for construction-grade lime screen out unorganized Rajasthan producers. Western India's chemical complexes anchor concentrated demand for high-calcium specifications.
Japan
Kansai and Chubu steel belts structure long-term offtake contracts with fixed-volume, indexed-price terms for slag conditioning materials. METI industrial efficiency standards accelerate digital kiln control adoption. Osaka-based integrated mills consolidate supplier relationships around terminal-equipped distributors.
Vietnam
High-purity dolomite reserves concentrate in specific mining districts that supply specialized refractory applications. Coastal terminals lack dedicated bulk handling infrastructure for quicklime import. Haiphong and Vung Tau ports enable first-mover logistics players to capture dispersed construction and steel demand.
Indonesia
Sulawesi and Halmahera HPAL-based battery precursor plants require high-calcium lime for pH control in nickel laterite processing. Mining sector demand now expands outside traditional steel applications. Jakarta and Surabaya distribution networks remain underdeveloped for metallurgical-grade specifications.
Asia-Pacific Quicklime Market Competitive Environment
Chinese producers anchor the volume tier; European specialists hold premium positioning through captive limestone assets. Market structure bifurcates between state-backed integrated processors with quarry-to-kiln control and independent traders serving spot construction demand. Strategic archetypes include terminal-network operators, PFR technology licensors, and regional quarry owners. Competitive moves concentrate on coastal logistics expansion and long-term steel mill offtake contracting.
Within the terminal-network tier, Carmeuse and Lhoist Group exemplify coastal infrastructure strategies that capture import-dependent demand across Vietnam and Indonesia. Sichuan Golden Summit Group occupies a position among western China's high-calcium specialists serving the chemical corridor. These three anchors represent distinct competitive vectors: maritime logistics integration, quarry-backed supply security, and purity-grade specialization.
| Leading Market Players |
|---|
| United States Lime & Minerals |
| Sichuan Golden Summit Group |
| Carmeuse |
| Pacific Lime and Cement |
| Hubei Zhongwei Calcium Industry Co. Ltd |
| Lhoist Group |
| Anhui Fengyang Mingdi Calcium Industry Co. Ltd |
| Sigma Minerals Ltd |
| Graymont Limited |
| Others |
Value Chain & Pricing Dynamics
Maerz parallel-flow regenerative kiln retrofits across Shandong and Hebei provinces simultaneously compress fuel costs below 800 kcal per kilogram and consolidate production around state-owned limestone processors with capital access. This technology transition concentrates supply-side pricing power while forcing smaller vertical shaft kiln operators toward margin compression or exit.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for metallurgical-grade quicklime as coastal terminal networks mature. Three-tier pricing structure across high-calcium premium, standard metallurgical, and construction economy levels reflects calcination technology investment and BIS certification status. Pricing pressure stems from MEE emissions compliance costs transferring to buyer contracts. Spot-dependent mini-mills in Southeast Asia exhibit highest price sensitivity; Japanese integrated mills with long-term offtake agreements show lowest.
Supply Chain Analysis
Kiln refractory refurbishment cycles and spent lime recovery flows remain underdeveloped across Asia-Pacific, limiting circular material pathways. Limestone extraction concentrates in China's Shandong-Hebei corridor, Vietnam's high-purity dolomite districts, and Malaysia's captive quarry networks. Thermal energy inputs draw from Australian metallurgical coal and Qatari LNG deliveries. Single-source vulnerability runs through Vietnamese dolomite reserves supplying specialized refractory applications. Distribution runs through coastal bulk terminals serving integrated steel mills and chemical complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific quicklime market functions as a stable compounder anchored by irreplaceable steel sector demand and tightening environmental compliance mandates that perpetuate procurement continuity.
For Market Incumbents: Anchor procurement relationships through captive limestone quarry acquisitions in Malaysia and Thailand, mirroring Lhoist Group's supply security model. Invest in Maerz PFR kiln technology to defend margin position against MEE emissions intensity penalties. Prioritize BIS certification pre-clearance for Indian construction-grade market access before Rajasthan and Gujarat capacity expansions materialize.
For New Entrants and Emerging Players: Dispersed mini-mills across coastal Vietnam and Indonesia represent the most penetrable buyer archetype currently underserved by dedicated bulk terminal infrastructure. Target HPAL-based nickel processing facilities in Sulawesi and Halmahera for metallurgical-grade lime supply outside traditional steel channels. Establish port logistics partnerships as the primary go-to-market mechanism rather than greenfield kiln construction.
For Investors and Strategic Acquirers: Roll-up economics work for regional quarry-to-kiln operators because BIS certification timelines and MEE compliance costs create insurmountable barriers for unorganized producers. Long-term viability centers on five-to-ten-year steel mill offtake contract visibility and environmental regulatory permanence. Monitor Indonesia's nickel processing capacity announcements as the inflection signal for metallurgical-grade demand displacement beyond steel applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Limestone Quarries | Secures feedstock supply security against Vietnamese dolomite reserve concentration risk. |
| Maerz PFR Kiln Technology Licensing | Delivers thermal efficiency below 800 kcal per kilogram for MEE compliance cost absorption. |
| Coastal Bulk Terminal Network Expansion | Captures dispersed mini-mill demand across Haiphong, Vung Tau, and Indonesian port corridors. |
| BIS Certification Pre-Investment | Accelerates market entry timelines for Rajasthan and Gujarat construction-grade supply. |
| Long-term Steel Mill Offtake Contracting | Structures three-to-five-year fixed-volume, indexed-price agreements displacing spot procurement. |
Study Parameters
Coverage spans China, India, Japan, Vietnam, and Indonesia, with primary inputs from each market's kiln operators, steel procurement directors, and environmental compliance officers. The analysis combines structured interviews with plant managers, technical R&D directors, and distribution channel partners with secondary validation through customs and trade data, MEE emissions disclosure filings, and CEA utility procurement records. Bottom-up capacity and consumption estimates triangulate against top-down macroeconomic drivers.
Granularity extends to product type differentiation by calcium oxide purity tier, application segmentation across steel manufacturing and environmental management verticals, and end-user disaggregation by chemical industry, mining, and paper manufacturing categories. CAGRs derive from production capacity expansion timelines, regulatory mandate implementation schedules, and substitution elasticity estimates across hydrated lime alternatives. Industry-specific inputs include MEE dual carbon pathway compliance costs and HPAL-based nickel processing capacity buildouts.
Inputs from Chinese provincial environmental registries and Indian BIS certification databases were available through the study window; gaps in Indonesian mining sector lime consumption reporting introduce uncertainty bands for Sulawesi and Halmahera demand projections. Forecasts reflect documented assumptions regarding MEE enforcement consistency and CEA mandate permanence. Practitioners should monitor Indonesia's battery precursor plant commissioning announcements and China's emissions trading scheme price discovery for early demand and cost signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Phosphorus Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Pivaloyl Chloride Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
Benzyl Chloroformate Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Tin Fluoborate Market
Bulk Chemicals
FT Wax Market