
 Optically Clear Resin Market | 2026-2036
Optically Clear Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Optically Clear Resin Market Outlook
ISO 10993 biocompatibility certification is collapsing the supplier pool for medical-grade optically clear resins, forcing material firms to rebuild testing pipelines. Dow Inc. leverages its silicone platform to dominate optical bonding applications in automotive HUD modules. Mitsui Chemicals, Inc. anchors Asian supply chains through specialized cyclo-olefin polymer grades with sub-1% haze specifications.
Optically clear resin denotes thermoset or radiation-curable polymer systems formulated to transmit visible light with minimal scattering, typically achieving haze values below 2% and refractive indices between 1.48 and 1.58 depending on base chemistry. These materials serve precision applications where optical clarity must coexist with structural adhesion, environmental sealing, or dimensional stability under thermal cycling. UV-curable formulations lead volume in electronics display lamination due to room-temperature processing and rapid line speeds, while thermosetting epoxies command margin pools in aerospace sensor encapsulation where outgassing limits are stringent. Medical device applications represent the fastest-growing end-use channel as manufacturers replace glass with sterilizable polymer optics in diagnostic imaging and surgical visualization systems.
REACH substance restrictions in Europe and FDA 21 CFR 175.105 food-contact adhesive standards constrain monomer selection and migration testing protocols for suppliers serving regulated end uses. China's GB standards for optical materials and NMPA medical device polymer registrations add parallel compliance layers for market access. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as fluorinated optical additives face phasedown timelines that could force formulation redesigns across premium product tiers.
Market Dynamics
ISO 10993 biocompatibility certification requirements are compressing the supplier pool for medical-grade optically clear resins, forcing material firms to rebuild testing pipelines and consolidate around validated manufacturing platforms.
Growth Catalysts
- Automotive HUD assembly:China domestic display panel production is pulling significant resin volumes for head-up display bonding applications in passenger vehicles.
- REACH substance restrictions:European purity mandates are accelerating R&D investment in low-migration monomer systems for regulated end uses.
- UV-curable formulation advances:Room-temperature processing capabilities are displacing thermal-cure systems in electronics display lamination lines.
Market Restraints
- Cyclo-olefin polymer supply concentration:Asian specialty resin production clusters face single-source dependency risks for sub-1% haze specification grades.
- Fluorinated additive phaseout timelines:Per- and polyfluoroalkyl substance restrictions across multiple jurisdictions force premium tier formulation redesigns.
- Epoxy outgassing limitations:Aerospace sensor encapsulation applications remain locked into thermosetting systems with stringent volatile emission ceilings.
Strategic Opportunities
- Surgical visualization systems:Medical device manufacturers are replacing glass with sterilizable polymer optics in diagnostic imaging equipment.
- GB standards alignment:China's optical materials certification pathways create first-mover advantages for compliant foreign suppliers.
- Silicone platform extension:Dow Inc. leverages existing automotive HUD module relationships to cross-sell optical bonding solutions.
Industry Challenges
- Biocompatibility testing pipeline reconstruction:Material firms face 18-24 month validation cycles for ISO 10993 certification renewal.
- Dual carbon compliance integration:China's MEE emission targets require concurrent process reengineering alongside product reformulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optically Clear Resin Market |
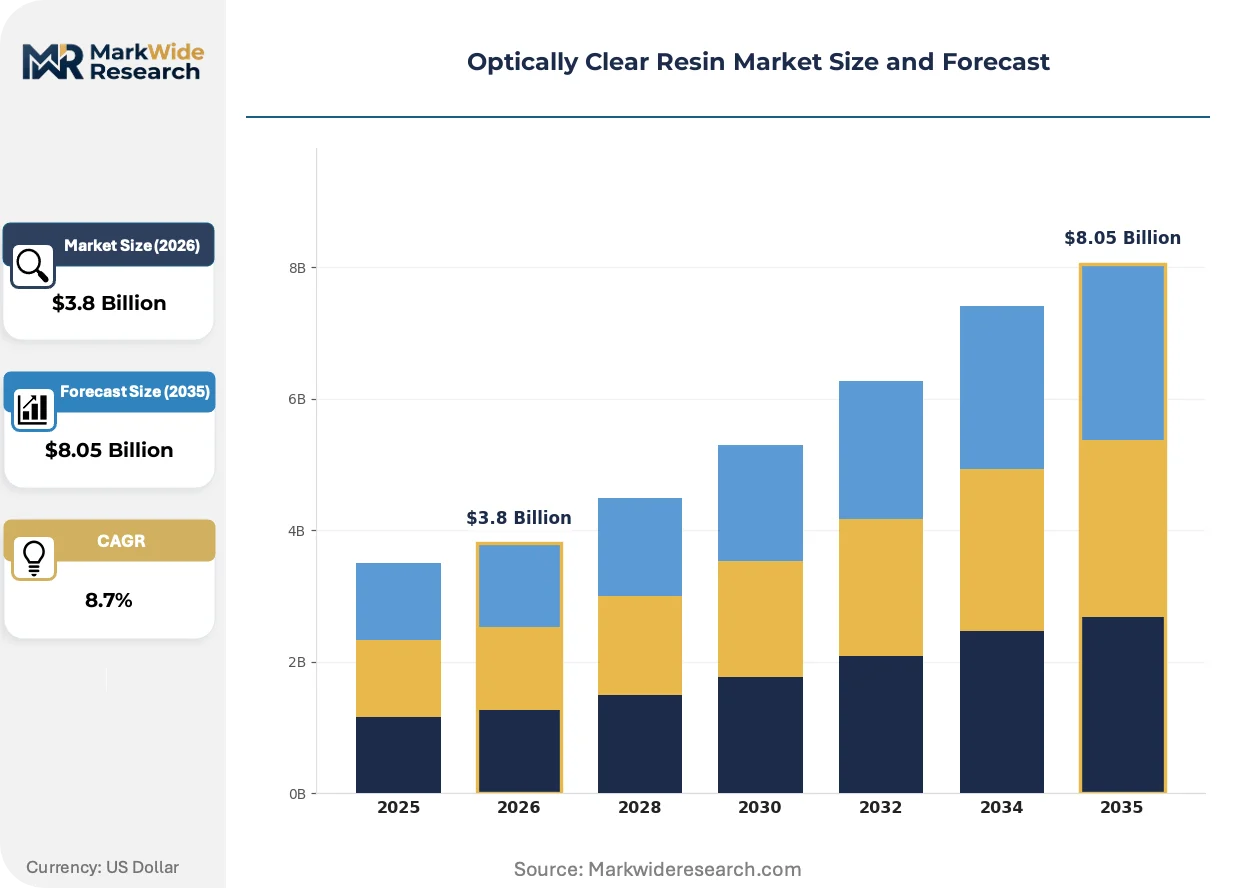
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Curable, Thermosetting, Epoxy, Polyurethane Application: Coatings, Adhesives, 3D Printing, Electronics End User: Automotive, Consumer Electronics, Medical Devices, Aerospace Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Dow Inc., Mitsui Chemicals, Inc., BASF SE, Shin-Etsu Chemical Co., Ltd., Eastman Chemical Company, 3M Company, Henkel AG & Co. KGaA, Covestro AG, LG Chem Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optically Clear Resin Market Strategic Shifts
Radiation-curable polymer systems are actively reshaping processing economics across display lamination, while regulatory substance restrictions force parallel reformulation investments.
UV-LED curable acrylate formulations are displacing mercury-lamp systems in high-volume display bonding operations. Electronics contract manufacturers in South Korea and Taiwan are retrofitting production lines to accommodate narrower wavelength emission spectra. This transition is displacing thermal-cure epoxies from mainstream consumer electronics applications where line speed dominates total cost.
ECHA's expanding REACH candidate list now targets specific optical monomers with reproductive toxicity classifications. European resin compounders are preemptively substituting bisphenol-A derived components in anticipation of authorization sunset dates. Medical device polymer registrations under China's NMPA are absorbing the most severe compliance burden as dual jurisdiction testing becomes mandatory for market access.
Diagnostic imaging OEMs now specify sterilization-cycle-resistant optical polymers in initial RFQ documentation rather than retrofitting glass alternatives. This specification shift compresses supplier qualification timelines and favors compounders with existing FDA 21 CFR 175.105 food-contact adhesive dossiers. The preference is most visible in Germany and Switzerland where surgical robotics manufacturers cluster.
Optically Clear Resin Market Segmentation
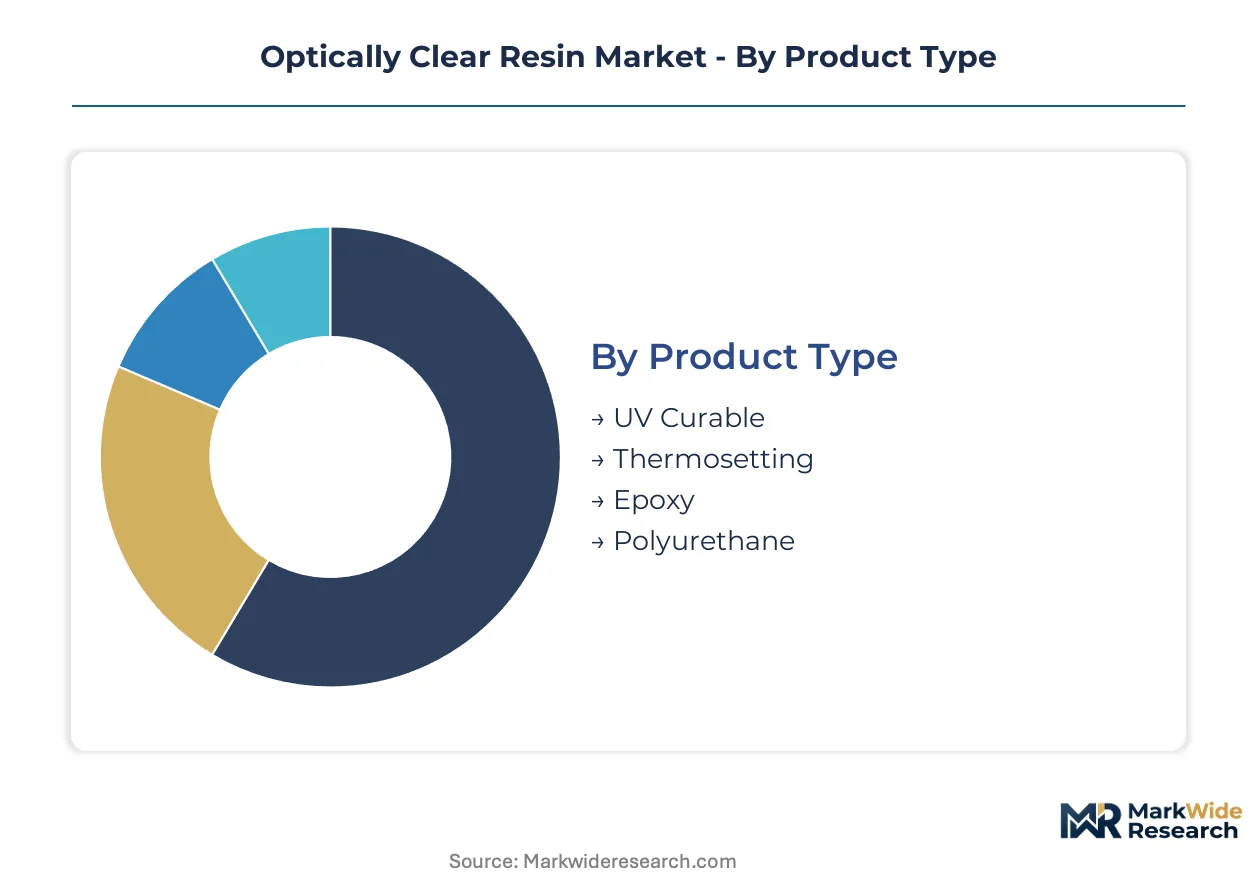
Optically clear resin specifications diverge sharply across end-use requirements, with medical-grade ISO 10993 certification and automotive HUD optical bonding imposing incompatible purity thresholds on shared polymer platforms. Segmentation clarity determines supplier qualification timelines and regional market access strategies.
Product Type:
UV-curable formulations dominate export flows to Asian electronics manufacturing clusters, while thermosetting grades serve domestic aerospace and medical device producers in North America and Europe.
- UV Curable:Acrylate-based systems cure at room temperature under UV-LED emission spectra, enabling line speeds above 50 meters per minute in South Korean and Taiwanese display lamination facilities. Mercury-lamp retrofits are accelerating as electronics contract manufacturers seek energy efficiency gains.
- Thermosetting:Heat-activated epoxy and silicone platforms deliver dimensional stability under thermal cycling for automotive HUD modules. Dow Inc. leverages existing silicone infrastructure to supply German and Chinese passenger vehicle assembly lines.
- Epoxy:Low-outgassing formulations meet NASA and ESA volatile emission limits for satellite sensor encapsulation.
- Polyurethane:Flexible optical grades penetrate impact-resistant lens applications in sports eyewear and industrial safety equipment.
UV-curable systems command the established base in volume terms. The steepest expansion runs through thermosetting grades as automotive HUD penetration deepens in Chinese domestic production.
Application:
Cost tiers separate commodity display lamination from premium medical device optics, with certification burden driving margin stratification.
- Coatings:Thin-film anti-reflective and anti-scratch layers protect polycarbonate and acrylic substrates in consumer electronics. Chinese GB standards for optical film durability are tightening qualification requirements for foreign compounders.
- Adhesives:Optical bonding adhesives eliminate air gaps between display panels and cover lenses, enhancing contrast in bright ambient conditions. REACH substance restrictions on specific acrylate monomers are forcing European reformulation investments.
- 3D Printing:Vat photopolymerization resins enable rapid prototyping of custom optical components with sub-100-micron feature resolution.
- Electronics:Encapsulation and underfill applications protect semiconductor packages from moisture and mechanical stress.
Adhesives anchor revenue concentration through automotive and electronics demand. 3D printing is climbing fastest as dental and audiology labs adopt custom optical prototyping workflows.
End User:
Customer procurement sophistication ranges from price-sensitive electronics contract manufacturers to medical device OEMs demanding 18-24 month validation cycles.
- Automotive:Head-up display bonding and LiDAR lens applications require thermal stability from -40°C to 85°C. NHTSA and KBA safety standards for optical clarity under vibration and temperature stress are tightening specification windows.
- Consumer Electronics:Smartphone and tablet display lamination consumes the largest resin volumes, with South Korean and Chinese panel producers driving formulation customization.
- Medical Devices:Surgical visualization and diagnostic imaging systems replace glass with sterilizable polymer optics. FDA 21 CFR 175.105 food-contact adhesive standards and ISO 10993 biocompatibility certification compress the qualified supplier pool.
- Aerospace:Satellite and aircraft sensor encapsulation demands outgassing limits below 1% total mass loss per ASTM E595.
Consumer electronics holds volume leadership. Medical devices are expanding most quickly as diagnostic imaging OEMs specify polymer optics in initial RFQ documentation.
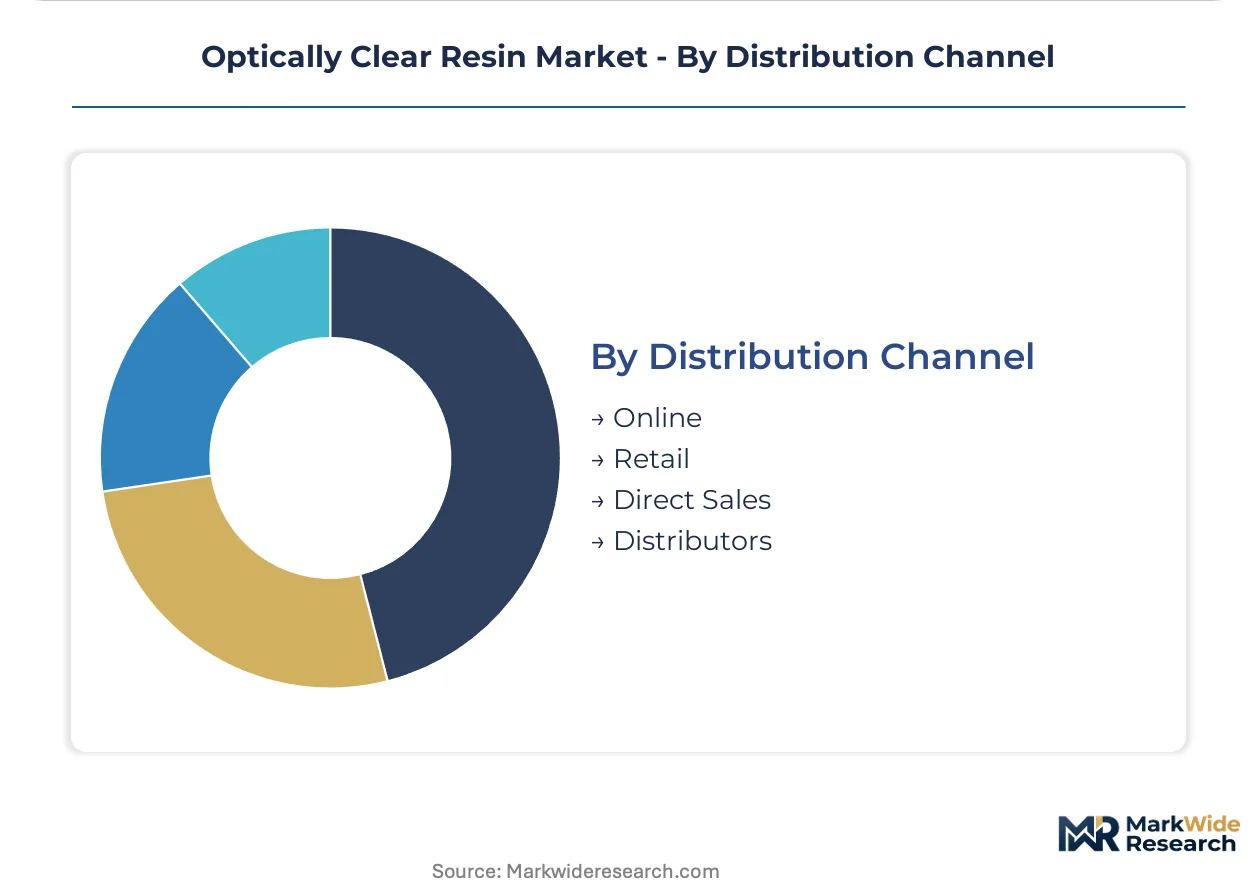
Distribution Channel:
Supply chain configuration separates bulk chemical distributors serving commodity electronics applications from direct technical sales teams supporting medical and aerospace qualification.
- Online:E-commerce platforms serve prototype quantities and small-batch 3D printing resins to research labs and hobbyist markets.
- Retail:Specialty chemical distributors stock standard UV-curable grades for immediate availability to mid-size electronics manufacturers.
- Direct Sales:Technical field engineers support automotive and medical OEMs through formulation co-development and regulatory dossier preparation.
- Distributors:Regional chemical distributors aggregate volumes across multiple resin categories, offering consolidated logistics for electronics contract manufacturers in Taiwan and Malaysia.
Direct sales captures the highest-margin relationships. Distributors are gaining share fastest as Asian electronics manufacturing clusters seek supply security through regional inventory positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement sophistication concentrates in automotive electronics clusters and medical device manufacturing corridors, with regulatory compliance thresholds determining supplier qualification timelines across major economies.
China
Domestic display panel production and automotive HUD assembly pull significant resin volumes through the Yangtze River Delta and Pearl River Delta manufacturing belts. NMPA medical device polymer registrations and GB standards for optical materials create dual compliance layers for market access. Suzhou and Shenzhen host the densest concentrations of optical bonding adhesive consumption for consumer electronics contract manufacturers.
Germany
Automotive HUD module production and surgical robotics manufacturing drive demand for thermosetting silicone and sterilizable polymer optics. KBA safety standards for optical clarity under vibration stress tighten specification windows for head-up display bonding applications. Stuttgart and Munich anchor the supplier qualification networks serving German passenger vehicle assembly lines.
United States
Aerospace sensor encapsulation and diagnostic imaging OEM procurement sustain demand for low-outgassing epoxy formulations. FDA 21 CFR 175.105 food-contact adhesive standards and ISO 10993 biocompatibility certification compress the qualified supplier pool for medical-grade applications. Greater Boston and Southern California concentrate surgical visualization system manufacturers specifying polymer optics in initial RFQ documentation.
South Korea
Electronics display lamination consumes the largest resin volumes, with panel producers driving UV-LED curable acrylate formulation customization. MFDS medical device regulations and industrial emission targets under the national green growth strategy reshape monomer selection protocols. Gyeonggi Province hosts the most intensive retrofitting of production lines from mercury-lamp to UV-LED curing systems.
Japan
Specialized cyclo-olefin polymer grades with sub-1% haze specifications anchor Asian supply chain positioning for precision optical applications. METI industrial standards and PMDA medical device polymer registrations govern market entry pathways for foreign compounders. Chubu and Kansai regions maintain concentrated production of radiation-curable formulations for electronics encapsulation.
Optically Clear Resin Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with existing silicone or acrylate platforms, compressing opportunities for standalone specialty resin entrants. Three archetypes dominate: integrated polymer producers leveraging feedstock advantages, medical-grade certification specialists absorbing 18-24 month validation cycles, and electronics-focused compounders optimizing for UV-LED line speed compatibility. Competitive moves concentrate on strategic partnerships with display panel manufacturers and portfolio diversification into sterilizable optical grades.
Within the diversified chemical conglomerate tier, Dow Inc., Mitsui Chemicals, Inc., and BASF SE exemplify distinct geographic anchoring strategies. Dow leverages North American silicone infrastructure to serve automotive HUD module relationships. Mitsui occupies a position in Asian specialty resin supply chains through cyclo-olefin polymer platforms. BASF represents European formulation expertise navigating REACH substance restrictions on optical monomers.
| Leading Market Players |
|---|
| Dow Inc. |
| Mitsui Chemicals, Inc. |
| BASF SE |
| Shin-Etsu Chemical Co., Ltd. |
| Eastman Chemical Company |
| 3M Company |
| Henkel AG & Co. KGaA |
| Covestro AG |
| LG Chem Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day raw material lead times for specialty acrylate monomers concentrate pricing power with Japanese and South Korean producers, compressing margin buffers for European compounders navigating REACH substance restrictions. This inventory-to-supply tightness rewards backward-integrated resin producers while forcing distributors to absorb working capital strain.
Pricing Analysis
Cost-plus contracts indexed to benzene and acrylic acid spot benchmarks dominate long-term supply agreements between Asian resin producers and electronics contract manufacturers. Price differentiation separates ISO 10993-certified medical grades from standard electronics lamination tiers, with certification burden adding substantial premiums. Pricing pressure stems from UV-LED curing equipment commoditization as South Korean panel producers squeeze adhesive suppliers. Electronics contract manufacturers exhibit highest price sensitivity, while surgical robotics OEMs accept premium positioning for validated sterilization-cycle performance.
Supply Chain Analysis
Strait of Malacca transit routes underpin cyclo-olefin polymer feedstock flows from Singapore refining hubs to Chinese optical resin compounders. Production concentrates in China, Japan, and South Korea, with specialized monomer synthesis drawing from naphtha crackers and phenol derivatives. Single-source vulnerability runs through Mitsui Chemicals' sub-1% haze specification grades for precision optics. Distribution runs through regional chemical distributors in Taiwan and Malaysia, consolidating logistics for mid-volume electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Chinese display panel producers consolidate procurement through Yangtze River Delta purchasing cooperatives, fragmenting supplier negotiation leverage across smaller compounders.
For Market Incumbents: Shield medical-grade certification franchises by accelerating ISO 10993 pipeline investments ahead of European authorization sunset dates for bisphenol-A derived components. Deepen backward integration into silicone intermediates to defend automotive HUD module relationships against Dow Inc.'s platform extension. Prioritize Suzhou technical center expansion to co-locate formulation development with Chinese OEM qualification teams. For New Entrants and Emerging Players: Anchor in 3D printing resin segments serving dental and audiology prototyping labs, where custom optical component demand outruns established supply. Target audiology device manufacturers in Germany and Switzerland specifying polymer optics in initial RFQ documentation. Pursue direct technical sales engagement with surgical visualization startups seeking sterilizable alternatives to glass. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-grade biocompatibility testing infrastructure, favoring acquisition of compounders with existing FDA 21 CFR 175.105 dossiers over greenfield certification investments. Long-term viability centers on dual-use platforms spanning electronics lamination and medical device optics. Target acquisition archetype: mid-cap European compounders with REACH-compliant monomer substitution capabilities. Signal to watch: NMPA registration timeline compression for foreign polymer suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Intermediates | Dow Inc. leverages captive siloxane supply to dominate automotive HUD optical bonding. |
| ISO 10993 Certification Pipeline Expansion | Medical-grade resin producers absorb 18-24 month validation cycles to compress qualified supplier pools. |
| UV-LED Curing Line Retrofit Partnership | South Korean electronics manufacturers retrofit mercury-lamp facilities to narrow emission spectra specifications. |
| REACH-Compliant Monomer Substitution Program | European compounders preemptively reformulate bisphenol-A derived components ahead of authorization deadlines. |
| NMPA Registration Fast-Track Investment | Foreign suppliers establish Shanghai technical centers to accelerate China's medical device polymer approval pathways. |
Study Parameters
Desk research of customs trade data, SEC chemical company filings, and ECHA REACH candidate list updates preceded structured interviews with optical resin plant managers, procurement leads at Chinese display panel manufacturers, distribution channel partners in Taiwan and Malaysia, and technical R&D directors at Japanese specialty resin producers. Primary fieldwork combined with secondary validation from ACC and Cefic industry reports, bottom-up volume modeling, and top-down market sizing triangulation.
Variance decomposition across product type, application, end user, and regional production hub dimensions informed analytical framework construction over the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit assumptions, with specific inputs including UV-LED curing equipment installation rates and automotive HUD penetration curves in Chinese passenger vehicles.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH substance restriction enforcement and continued Chinese domestic display panel production expansion; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as fluorinated additive phaseout timelines and NMPA registration pathway reforms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Middle East Polymer Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
Europe Polyurethane Market