
 Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market | 2026-2036
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market Size, Share, and Industry Trends Forecast 2026-2036
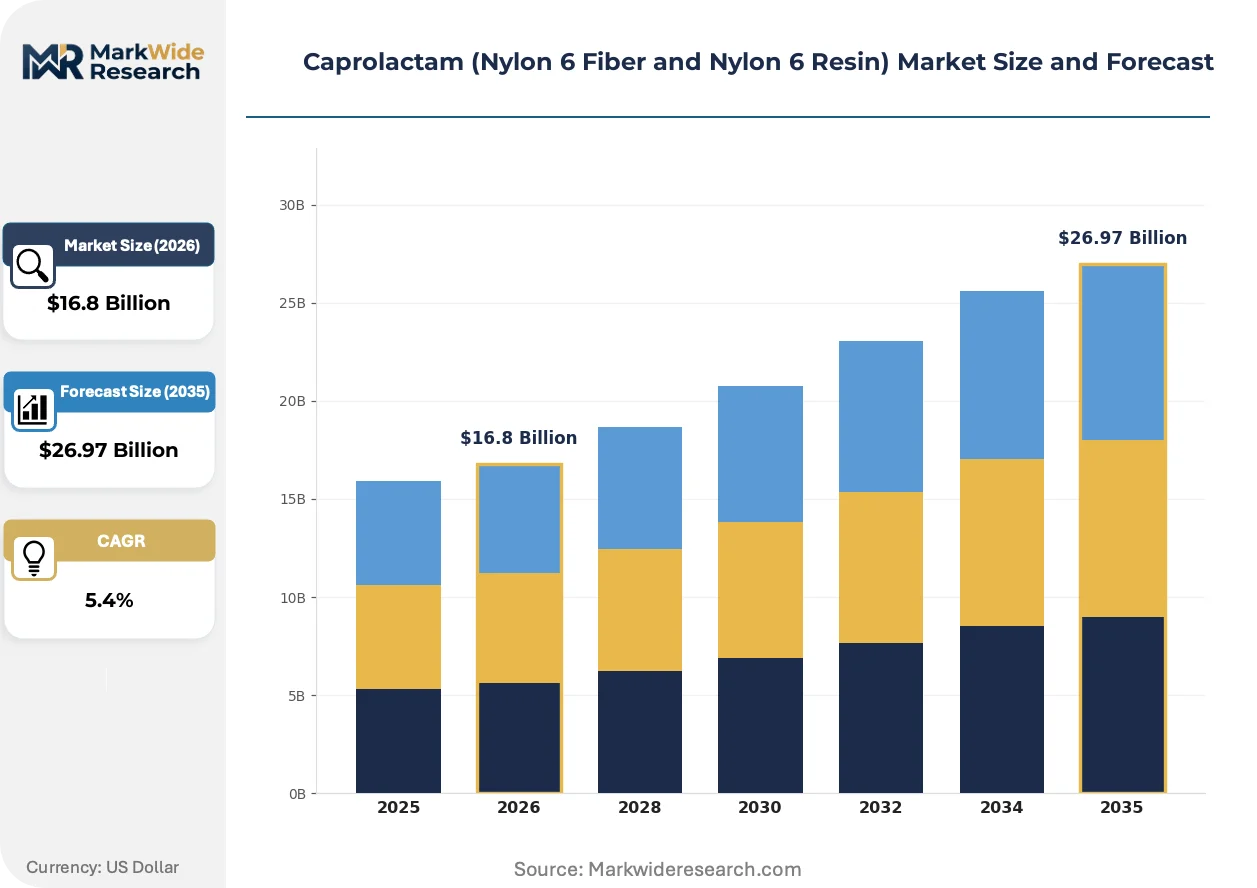
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market Outlook
Polyamide 66 is expanding its presence in automotive cooling systems and electrical connectors, pressuring caprolactam-based nylon 6 suppliers to defend cost positions. Lanxess AG leverages backward integration into adipic acid and caprolactam to sustain margin control across its engineering plastics portfolio. Sumitomo Chemical Co. Ltd. anchors its Asian operations through integrated caprolactam-to-fiber production in Japan and Thailand. BASF SE differentiates via specialty nylon 6 compounds for high-heat automotive applications, competing on specification breadth rather than commodity volume.
Caprolactam is a cyclic amide (C₆H₁₁NO) produced primarily through the Beckmann rearrangement of cyclohexanone oxime, serving as the monomeric feedstock for nylon 6 polymerization via ring-opening polymerization at 260–280°C. The resulting nylon 6 fiber and resin deliver tensile strengths of 70–85 MPa with melting points near 220°C, supporting applications from tire cord to injection-molded engine covers. Nylon 6 Resin commands the deepest margin pools in engineering plastics and automotive components, where specification certification cycles lock in multi-year supply agreements. Nylon 6 Fiber remains volume-dominant in textiles but faces margin compression from polyester substitution in apparel. Automotive Components as an application segment is outpacing packaging growth, driven by metal-to-plastic conversion in powertrain and thermal management parts.
REACH registration requirements in Europe and China's GB standards administered by SAMR enforce purity thresholds and emissions limits that filter smaller caprolactam producers from export-qualified supply chains. EPA regulations under the Toxic Substances Control Act shape product stewardship obligations for U.S.-based nylon 6 compounders importing monomer feedstock. Stakeholders must monitor regulatory divergence between EU chemical safety frameworks and China's evolving dual carbon compliance deadlines, as misaligned certification timelines will fragment qualified supplier lists and reshape procurement risk assessments.
Market Dynamics
Automotive lightweighting mandates and China's dual carbon enforcement are compressing caprolactam supply chains toward integrated petrochemical corridors, filtering non-compliant producers from qualified supplier pools.
Growth Catalysts
- REACH Phase-In Substances:ECHA registration deadlines for caprolactam derivatives are consolidating European supply toward certified polymer compounders with verified purity documentation.
- Metal-to-Plastic Conversion:Powertrain thermal management components are replacing aluminum with glass-filled nylon 6 resin to meet fleet efficiency targets.
- Yangtze River Delta Clustering:Integrated cyclohexanone-to-fiber production corridors in Jiangsu and Zhejiang provinces are capturing downstream textile and automotive demand within 200-kilometer radii.
Market Restraints
- Cyclohexane Feedstock Volatility:Benzene price swings transmit directly to caprolactam contract pricing, compressing spot margins for non-integrated producers.
- Polyamide 66 Substitution:Higher heat-deflection temperature in PA66 is displacing nylon 6 from automotive cooling module applications above 180°C continuous service.
- GB Standard 31571 Enforcement:China's SAMR-administered emissions caps on caprolactam effluent are raising compliance capital requirements for small-batch producers.
Strategic Opportunities
- India PLI Scheme for Textiles:Production-linked incentives for man-made fiber manufacturing are drawing caprolactam offtake agreements toward Gujarat and Tamil Nadu greenfield sites.
- Recycled Content Mandates:EU Green Deal packaging regulations are creating certified demand for post-industrial nylon 6 regrind in automotive and consumer goods.
- 3D Printing Filament Grade:Fused deposition modeling feedstock specifications are opening specialty margin pools for low-viscosity, color-stable caprolactam polymers.
Industry Challenges
- Automotive Specification Lock-In:OEM material qualification cycles spanning 24-36 months freeze supplier switches even when cost differentials emerge.
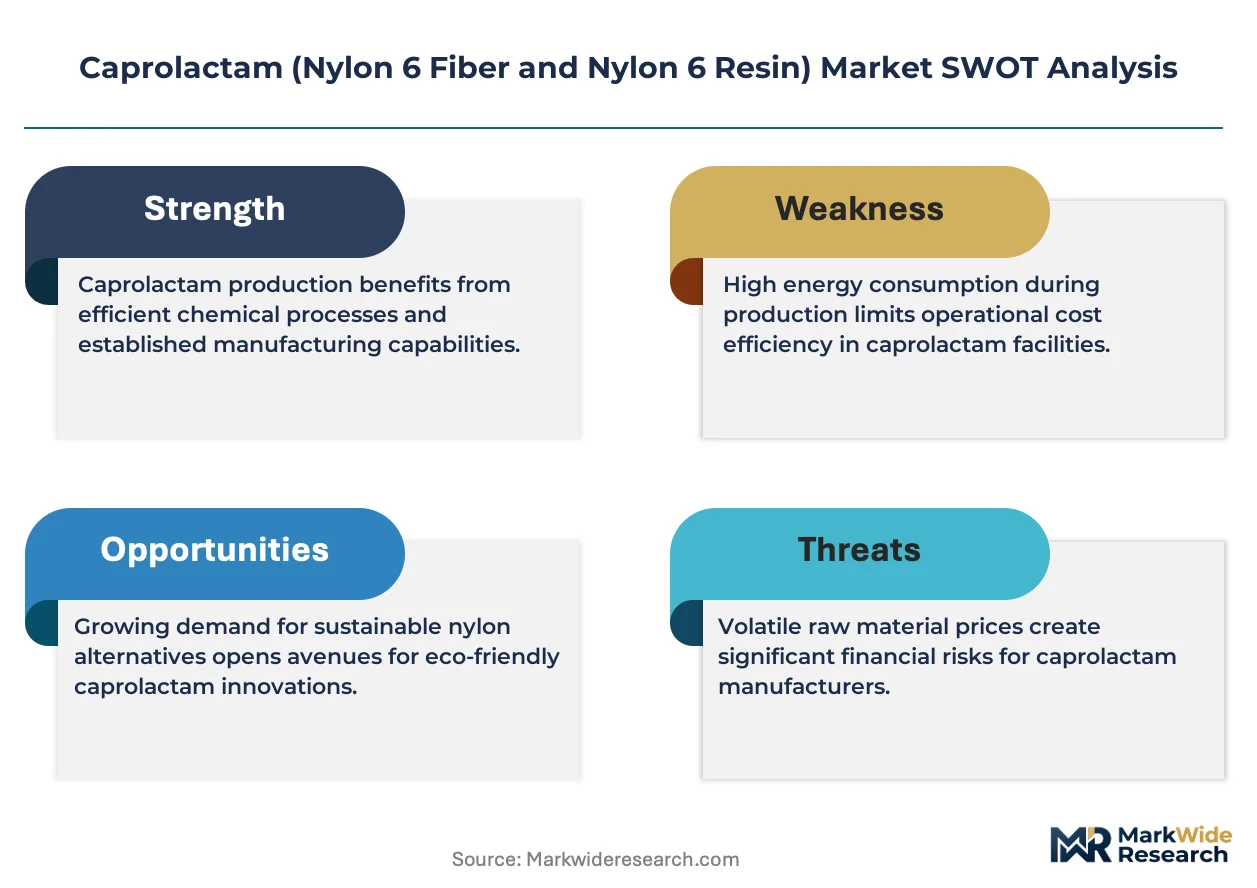
- Beckmann Rearrangement Energy Intensity:Fuming sulfuric acid consumption in conventional caprolactam synthesis faces carbon accounting scrutiny under Scope 3 disclosure rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon 6 Fiber, Nylon 6 Resin, Intermediates, Additives Application: Textiles, Automotive Components, Packaging, Engineering Plastics End User: Fashion Industry, Automotive Manufacturers, Electronics, Construction Sector Form: Granules, Filaments, Sheets, Compounds |
| Companies Covered | China Petrochemical Development Corporation, Lanxess AG, Sumitomo Chemical Co. Ltd., Fibrant, AdvanSix Inc., UBE Corporation, Capro Co., Toray Industries Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market Strategic Shifts
Process intensification and regulatory disclosure requirements are restructuring how caprolactam producers compete, shifting advantage toward integrated operators with verified carbon footprints and closed-loop solvent recovery.
Enzymatic Beckmann rearrangement using immobilized lipase catalysts is automating cyclohexanone oxime conversion at ambient temperature and pressure. Specialty chemical producers in Japan and Germany are piloting these biocatalytic routes to eliminate fuming sulfuric acid handling. The technology is automating compliance with EU Industrial Emissions Directive solvent recovery thresholds while reducing neutralization waste volumes.
REACH Article 33 SCIP database obligations are forcing full polymer supply chain disclosure for articles containing caprolactam above 0.1% w/w. Compounders serving automotive and electrical sectors must now document monomer origin through polymerization to molding. The regulation is compressing qualified supplier lists to integrated producers with batch-level traceability systems, disadvantaging traders and toll compounders.
Direct polymerization service contracts are replacing spot resin purchases among tier-one automotive suppliers seeking locked-in viscosity specifications. Buyers in Germany and the US are contracting dedicated extrusion lines at compounder facilities rather than accepting standard catalog grades. The shift is visible most acutely in under-hood component programs where lot-to-lot variation in molecular weight distribution causes molding defect rates above 500 ppm.
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market Segmentation
Segmentation in caprolactam markets reveals how specification requirements fragment procurement behavior. Automotive qualification cycles enforce material-grade fidelity, while textile buyers prioritize cost elasticity across fiber deniers.
Product Type:
Customization intensity spans from commodity fiber to certified engineering resin, with specification breadth determining margin capture and customer lock-in duration.
- Nylon 6 Resin:Semi-crystalline thermoplastic with 220°C melting point and 70–85 MPa tensile strength, formulated with glass fiber or mineral fillers for under-hood automotive components. Demand concentrates in Germany and China's Yangtze River Delta, where OEM thermal management programs require multi-year supply agreements with locked viscosity specifications.
- Nylon 6 Fiber:Ring-spun and filament yarn forms serving tire cord, industrial belting, and apparel applications. Textile demand clusters in China's Jiangsu province and India's Tamil Nadu, though polyester substitution in apparel is compressing staple fiber margins.
- Intermediates:Cyclohexanone oxime and aminocaproic acid precursors sold to integrated polymer producers.
- Additives:Heat stabilizers, UV inhibitors, and nucleating agents compounded for specialty performance grades.
Leading the category by volume: Nylon 6 Fiber. Growing fastest: Nylon 6 Resin.
Application:
End-use thermal and mechanical requirements stratify procurement across specification-tolerant and specification-critical tiers.
- Automotive Components:Engine covers, intake manifolds, and cooling module housings replacing aluminum in powertrain thermal management. Metal-to-plastic conversion programs in Germany and the US are driving glass-filled resin offtake as fleet efficiency targets tighten.
- Engineering Plastics:Injection-molded gears, bearings, and electrical connectors requiring dimensional stability across -40°C to 150°C service windows.
- Textiles:Carpet fiber, tire cord, and apparel yarn consuming the majority of caprolactam monomer volume.
- Packaging:Film and barrier layers for food and industrial applications, facing recycled content mandates under EU Green Deal regulations.
Dominant by revenue contribution: Automotive Components. Expanding most quickly: Engineering Plastics.
End User:
Customer scale and qualification burden separate multinational OEMs from dispersed downstream processors.
- Automotive Manufacturers:Tier-one suppliers and OEMs with 24–36 month material qualification cycles freezing supplier switches. Procurement concentrates among German and Japanese vehicle programs specifying lot-to-lot molecular weight control.
- Fashion Industry:Apparel brands and textile mills with high volume elasticity and rapid supplier switching.
- Electronics:Connector and housing producers requiring flame-retardant and high-CTI compound grades.
- Construction Sector:Geotextiles, scaffolding components, and cable jacketing applications.
Highest specification barriers: Automotive Manufacturers. Most price-sensitive volume: Fashion Industry.
Form:
Physical presentation determines handling infrastructure and downstream processing capital requirements.
- Granules:Standard pellet form for injection molding and extrusion, commanding the deepest specification certification pools in automotive supply chains.
- Filaments:Continuous fiber for textile processing and 3D printing feedstock, with low-viscosity grades opening specialty margin pools.
- Sheets:Extruded plate stock for thermoforming and machining applications.
- Compounds:Pre-formulated resin blends with fillers and additives for direct molding.
Widest application coverage: Granules. Steepest expansion trajectory: Filaments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate integrated caprolactam-to-textile production corridors. Germany's Ruhr industrial belt anchors European engineering resin demand. India's Gujarat Special Investment Region draws greenfield polymer capacity through production-linked incentives.
China
Jiangsu and Zhejiang provinces host cyclohexanone-to-fiber integrated complexes serving automotive and textile downstream within 200-kilometer radii. SAMR-administered GB standards enforce dual carbon compliance on caprolactam effluent emissions. The Ningbo-Zhoushan petrochemical cluster captures volume through captive benzene supply and dedicated polymerization lines.
Germany
OEM thermal management programs in Baden-Württemberg and Bavaria drive specification-locked nylon 6 resin offtake for under-hood components. ECHA REACH registration deadlines filter supply toward certified compounders with verified purity documentation. The Ludwigshafen chemical corridor sustains multi-year supply agreements through backward-integrated adipic acid and caprolactam production.
United States
EPA Toxic Substances Control Act obligations shape product stewardship for nylon 6 compounders importing monomer feedstock. The Gulf Coast petrochemical corridor leverages integrated cyclohexane supply for caprolactam production. Texas and Louisiana facilities serve automotive tier-one suppliers with dedicated extrusion lines locked to viscosity specifications.
India
Gujarat and Tamil Nadu greenfield sites attract caprolactam offtake agreements through the PLI scheme for man-made fiber manufacturing. BIS certification requirements enforce purity thresholds for textile-grade polymer imports. The Dahej and Mundra special economic zones cluster polymerization capacity near downstream carpet and tire cord processors.
Japan
METI industrial policy supports integrated caprolactam-to-fiber production for automotive and electronics applications. The Chubu and Kansai industrial regions maintain captive supply chains from cyclohexanone through engineered resin compounding. Nagoya-based automotive suppliers specify lot-to-lot molecular weight control for powertrain component programs.
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical groups controlling upstream monomer supply and independent compounders serving specification-critical automotive tiers. The vendor base concentrates around three strategic archetypes: backward-integrated chemical majors with captive cyclohexanone supply, fiber-forward Asian conglomerates with textile-to-resin diversification, and regional compounders with automotive qualification lock-in. Capacity expansion and direct polymerization service contracts represent the dominant competitive moves, as buyers replace spot resin purchases with dedicated extrusion lines.
Among integrated chemical majors, Lanxess AG and BASF SE anchor the European engineering plastics tier through in-house production of adipic acid and caprolactam feedstocks. Sumitomo Chemical Co. Ltd. occupies a position within the Asian fiber-forward archetype, with Japanese and Thai production bases supporting integrated caprolactam-to-fiber operations. These three entities exemplify how backward integration sustains margin control across specification-certified polymer portfolios.
| Leading Market Players |
|---|
| China Petrochemical Development Corporation |
| Lanxess AG |
| Sumitomo Chemical Co. Ltd. |
| Fibrant |
| AdvanSix Inc. |
| UBE Corporation |
| Capro Co. |
| Toray Industries Inc. |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Specification-grade divergence between automotive-certified resin and commodity textile fiber fragments pricing power across divergent supply chain architectures. Premium engineering resin commands locked contract structures through multi-year OEM qualification cycles, while fiber-grade spot markets absorb benzene volatility through cyclohexanone feedstock pass-through mechanics.
Pricing Analysis
Volume-mass fiber tiers trade on razor-thin spreads above raw material costs, whereas margin-rich automotive resin captures value through locked viscosity specifications and dedicated extrusion line contracts. Price differentiation hinges on REACH purity certification thresholds and glass-filled compound formulation complexity. Cost compression in staple fiber runs through polyester substitution pressure in apparel end-uses. Fashion industry buyers exhibit extreme price elasticity, while German OEM procurement teams prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
REACH Article 33 SCIP database obligations and automotive material qualification cycles enforce tiered supplier certification that filters non-integrated producers from qualified pools. Geographic concentration centers on China, Germany, and the United States, with Jiangsu province and the Ruhr belt anchoring integrated cyclohexanone-to-resin corridors. Raw material dependencies draw from captive benzene supply, fuming sulfuric acid, and cyclohexanone oxime intermediates. Single-source vulnerability persists in specialty additive compounding for high-heat automotive grades. Distribution feeds from direct polymerization service contracts toward tier-one automotive suppliers rather than spot resin trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Caprolactam markets are consolidating around backward integration races, with control over cyclohexanone feedstock and captive polymerization lines determining margin sustainability across specification-certified tiers.
For Market Incumbents: Extend qualification lock-in through dedicated extrusion line investments at compounder facilities serving German and Japanese OEM thermal management programs. Deepen upstream control over adipic acid and caprolactam production to defend margin positions against PA66 substitution in automotive cooling modules above 180°C service windows.
For New Entrants and Emerging Players: Launch via direct polymerization service contracts targeting India's Gujarat and Tamil Nadu greenfield sites under PLI scheme incentives for man-made fiber manufacturing. Penetrate the 3D printing filament grade segment through low-viscosity, color-stable polymer specifications where established compounders lack dedicated capacity.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated Asian producers possessing captive benzene supply and SAMR dual carbon compliance infrastructure given tightening emissions caps on small-batch caprolactam effluent. Monitor enzymatic Beckmann rearrangement pilot scale-up as the inflection signal for process technology disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive cyclohexanone supply insulates margin control against benzene price volatility in European corridors. |
| Capacity Expansion | Yangtze River Delta clustering captures downstream textile and automotive demand within 200-kilometer radii. |
| Green Manufacturing Transition | Enzymatic Beckmann rearrangement eliminates fuming sulfuric acid handling under EU Industrial Emissions Directive. |
| Long-term Supply Agreement | Locked viscosity specifications freeze supplier switches through 24-36 month OEM material qualification cycles. |
| Joint Venture | India PLI scheme partnerships accelerate greenfield polymerization capacity near Dahej carpet and tire cord processors. |
Study Parameters
Independent corroboration across primary interviews with caprolactam plant managers, automotive tier-one procurement leads, textile mill technical directors, and specialty chemical distribution partners underwrites the qualitative findings. Secondary validation draws from customs and trade flow data, Cefic industry reports, SEC 10-K filings of listed polymer compounders, and SAMR emissions disclosure records. Bottom-up segment sizing triangulates against top-down petrochemical capacity assessments across the analysis window.
Comparable historical reference periods spanning cyclohexanone feedstock volatility episodes and REACH implementation phases anchor the forecast window. The analytical framework models demand across product type, application thermal requirements, end-user qualification burden, and regional production hub clustering. CAGRs derive from elasticity-adjusted consumption trajectories incorporating benzene price correlation coefficients and metal-to-plastic conversion program adoption curves in automotive powertrain applications.
Feedstock price spikes, regulatory divergence between EU REACH and China's GB standard enforcement timelines, and PA66 technology substitution are the dominant revision risks. Forecasts embed assumptions regarding SAMR dual carbon compliance deadlines and ECHA SCIP database penetration rates. A model refresh is warranted upon material change in enzymatic Beckmann rearrangement commercialization timelines or automotive OEM thermal management material specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
Polycarbonate Diols Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Polyisoprene Latex Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
France Engineering Plastics Market