
 Europe Epoxy Resins Market | 2026-2036
Europe Epoxy Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Epoxy Resins Market Foresight
High-performance aerospace-grade formulations is unwinding legacy commoditization across the European supply base. BASF SE leverages its Ludwigshafen integrated complex to sustain captive bisphenol-A supply for specialty grades. Covestro AG anchors its competitive stance through differentiated polycarbonate-epoxy hybrid systems serving automotive OEMs.
Epoxy resins are thermosetting polymers formed by reacting epichlorohydrin with bisphenol-A or alternative curatives, yielding cross-linked networks with exceptional adhesion, chemical resistance, and mechanical strength above 150°C glass transition temperatures; they function primarily as matrix binders in fiber-reinforced composites, protective coatings, and structural adhesives. Liquid epoxy dominates volume flows into wind turbine blade manufacturing, where margin pools concentrate around vacuum infusion-compatible low-viscosity grades. Solid epoxy competes fiercely in powder coatings for automotive and appliance applications, while electrical encapsulation segments specializing in high-voltage transformer insulation command premium pricing through IEC 61215 certification requirements.
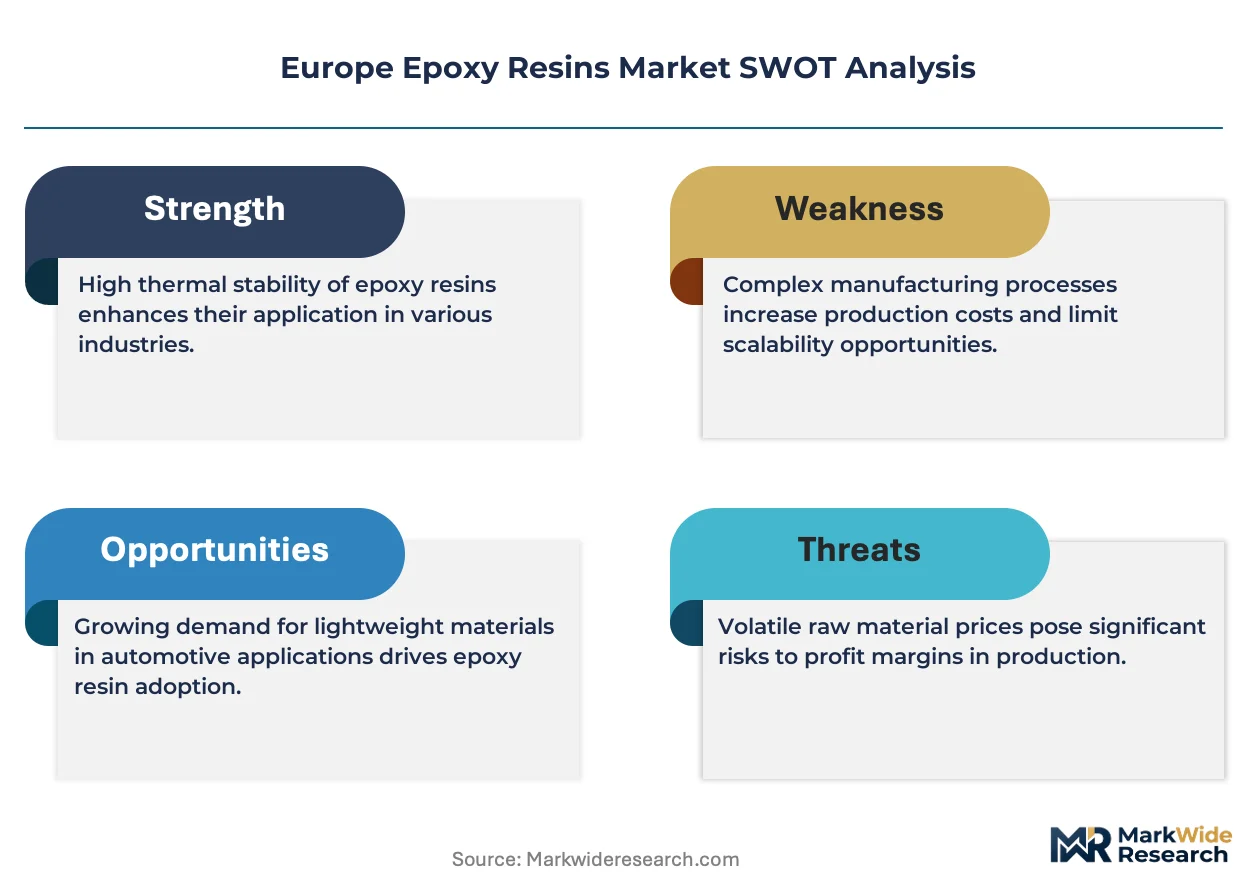
REACH registration mandates from ECHA govern monomer purity thresholds and restrict Substances of Very High Concern across the epoxy value chain, while the EU Green Deal's carbon border adjustments reshape raw material sourcing economics for imported epichlorohydrin. CE marking under the Construction Products Regulation enforces performance declarations for structural adhesive applications in civil engineering. Stakeholders must monitor bio-based epichlorohydrin scale-up timelines and anticipate how F-Gas Regulation phase-downs alter refrigeration coating demand patterns.
Market Dynamics
REACH compliance deadlines are compressing formulation timelines across European epoxy supply chains, forcing rapid substitution of Substances of Very High Concern in legacy bisphenol-A systems. Wind turbine OEMs in northern Europe are pulling volume toward bio-based epichlorohydrin feedstocks ahead of EU Green Deal carbon border adjustments.
Growth Catalysts
- EU Green Deal carbon border mechanisms:Imported epichlorohydrin faces escalating carbon cost exposure, accelerating captive bio-based production investments in Germany and the Netherlands.
- Offshore wind installation targets:Vacuum infusion-grade liquid epoxy consumption for blade manufacturing is climbing across North Sea port clusters in Denmark, Germany, and Belgium.
- REACH SVHC substitution mandates:ECHA restriction proposals on bisphenol-A derivatives are opening specification windows for alternative curative chemistries in electrical encapsulation.
Market Restraints
- Propylene-chlor-alkali feedstock volatility:Epichlorohydrin production economics swing with European natural gas pricing, compressing margin predictability for integrated resin producers.
- Asian import concentration:Solid epoxy resin supply for powder coatings remains dependent on Chinese and South Korean bulk imports, exposing buyers to tariff and logistics friction.
- Thermoplastic composite substitution:Polyetheretherketone and polyamide systems are displacing epoxy matrices in select aerospace interior applications where reparability outweighs modulus requirements.
Strategic Opportunities
- Poland and Baltic States fabrication hubs:Wind blade manufacturing capacity is migrating eastward from mature German and Danish bases, creating greenfield epoxy formulation demand.
- CE-marked structural adhesives:Construction Products Regulation compliance for civil engineering applications opens specification channels in bridge and building reinforcement segments.
- F-Gas Regulation phase-down alignment:Refrigeration coating reformulation toward lower-global-warming-potential systems creates demand for compatible epoxy barrier technologies.
Industry Challenges
- Vacuum infusion technician scarcity:Wind blade manufacturing scale-up outpaces trained composite laminator availability across North Sea industrial zones.
- IEC 61215 certification timelines:Electrical encapsulation qualification for high-voltage transformers extends 18-24 months, freezing supplier switching decisions.
- Legacy coating system integration:Automotive OEMs face revalidation burdens when substituting bio-based epoxy primers into existing cathodic electrocoat lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Epoxy Resins Market |
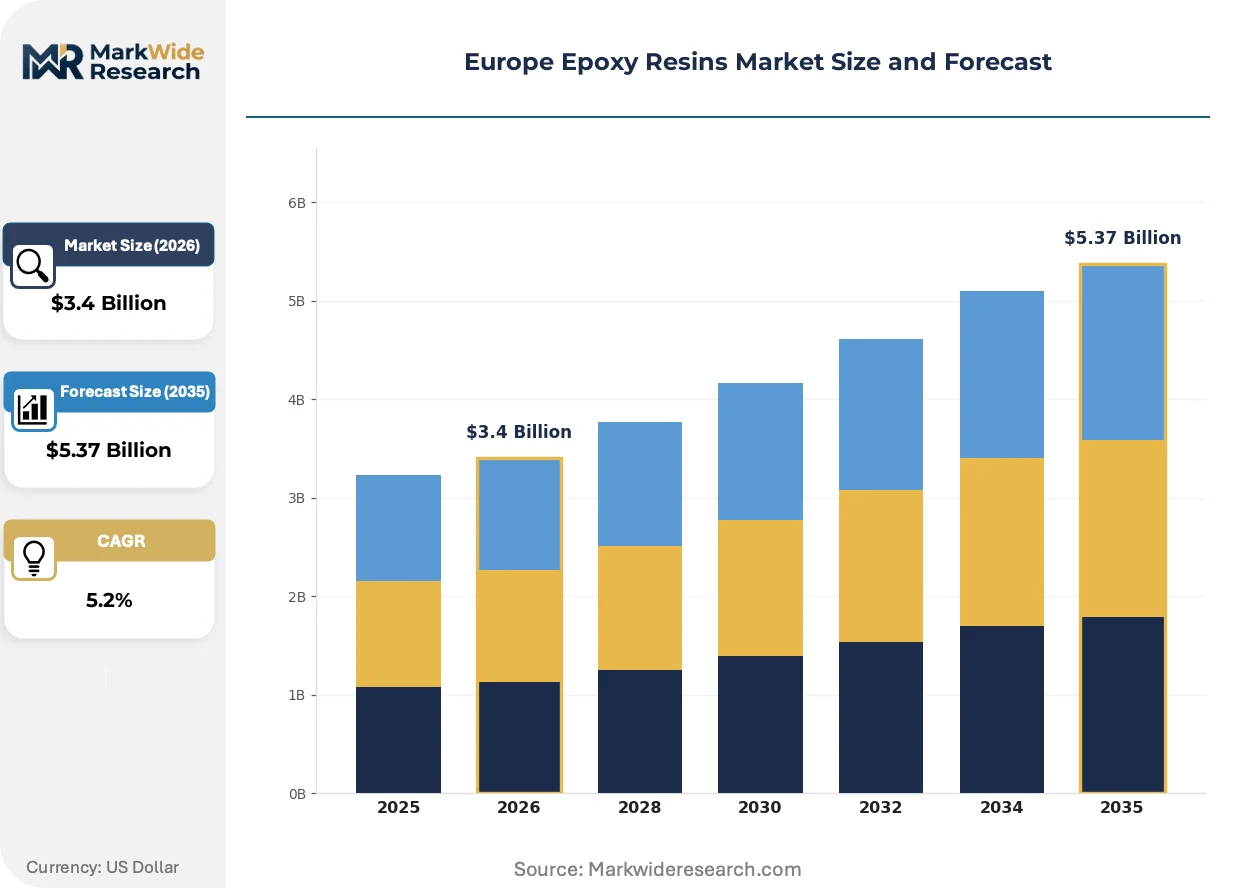
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Epoxy, Solid Epoxy, Powder Epoxy, Low-viscosity Epoxy Application: Adhesives, Coatings, Composites, Electrical Encapsulation End User: Aerospace, Construction, Automotive, Marine Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | BASF SE, Covestro AG, Arkema S.A., Evonik Industries AG, Huntsman International LLC, Olin Corporation, Solvay SA, Sika AG, 3M Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Epoxy Resins Market Shifts & Advancements
Bio-based feedstock chemistry is disrupting established petrochemical supply relationships across European epoxy value chains. Formulators are racing to secure certified sustainable epichlorohydrin volumes ahead of tightening EU Green Deal implementation timelines.
Low-viscosity anhydride curing systems are fragmenting traditional amine-cured formulations in wind blade manufacturing. Vestas and Siemens Gamesa specification engineers are specifying faster-cycling infusion chemistries for next-generation offshore platforms. This technology is fragmenting incumbent supplier relationships as turbine OEMs dual-source from specialty chemical partners with dedicated bio-based supply agreements.
REACH authorization requirements for bisphenol-A are tightening purity thresholds for epoxy monomers sold into consumer-facing applications. ECHA's 2024-2025 restriction roadmap is forcing reformulation investments across coating and adhesive segments. Electrical encapsulation suppliers serving transformer manufacturers are accelerating alternative curative qualification programs to preempt supply disruption.
Direct long-term contracting between wind farm developers and epoxy formulators is displacing traditional distributor-mediated procurement in blade manufacturing. Tier-1 turbine OEMs are consolidating supplier panels to capture volume pricing and secure bio-based feedstock allocation. This pattern is most visible in Danish and German offshore wind clusters where project finance requirements demand supply chain transparency documentation.
Europe Epoxy Resins Market Segmentation
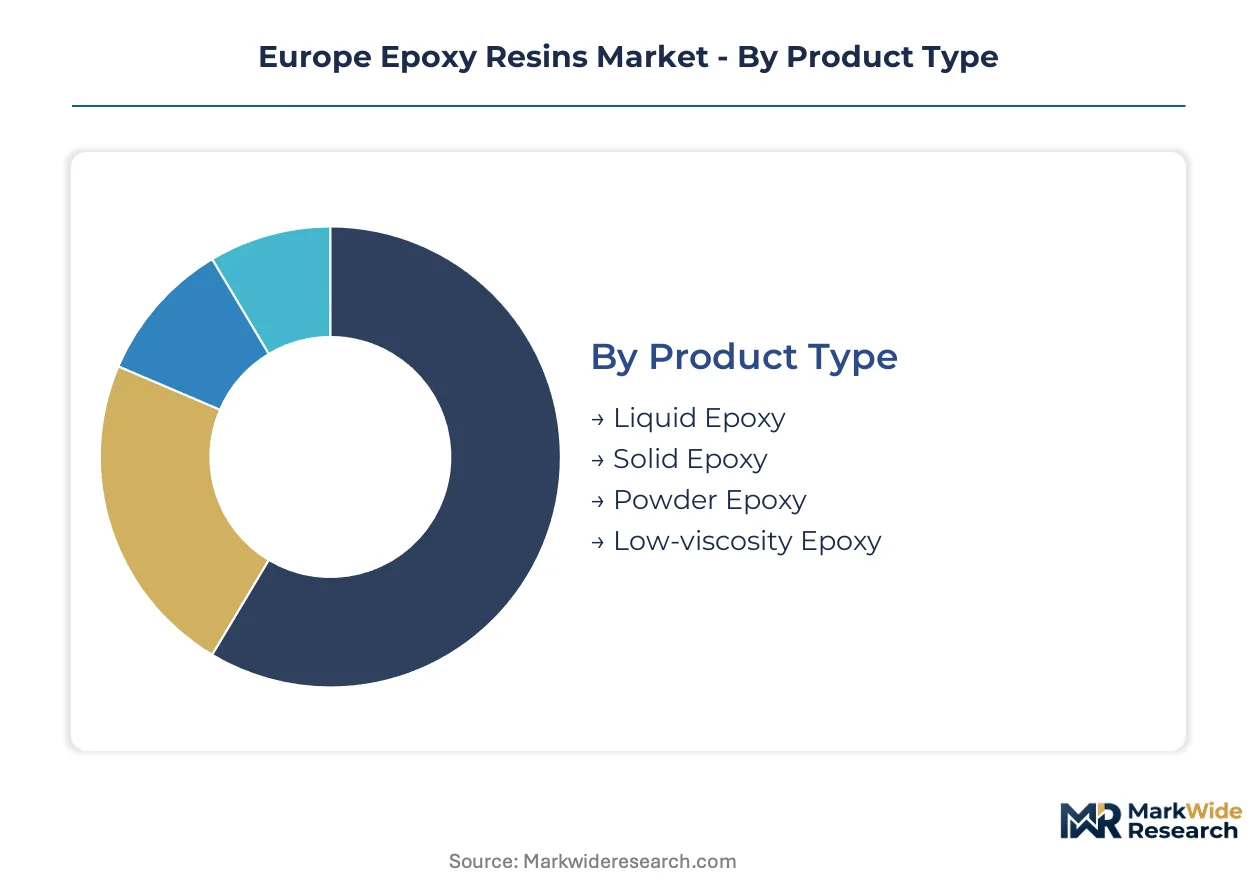
Epoxy resin formulations diverge sharply across European supply chains based on viscosity requirements and curing chemistry. Specification engineers at wind turbine OEMs and aerospace fabricators drive purchasing criteria that fragment procurement channels and margin structures.
Product Type:
Liquid grades flow predominantly through direct mill-to-fabricator contracts, while solid and powder variants rely more heavily on distributor networks serving fragmented coating applicators.
- Liquid Epoxy:Low-viscosity formulations designed for vacuum infusion processes in fiber-reinforced composite manufacturing. Demand concentrates across North Sea wind blade fabrication clusters in Denmark, Germany, and Belgium where Vestas and Siemens Gamesa specifications dominate procurement decisions.
- Solid Epoxy:Higher molecular weight resins requiring solvent or heat activation for film formation. Powder coating applicators in Germany's automotive supply base pull volumes through regional distributor networks serving cathodic electrocoat line operators.
- Powder Epoxy:Pre-cured particulate systems for electrostatic spray application. Appliance manufacturers in Poland and Italy represent primary offtake channels.
- Low-viscosity Epoxy:Modified aliphatic or cycloaliphatic systems for specialized infusion and casting applications. Marine repair yards in the Netherlands and France specify these grades for hull lamination work.
By volume, liquid epoxy leads. By growth pace, low-viscosity grades are climbing the fastest as offshore wind blade dimensions expand.
Application:
Margin capture varies dramatically across application segments, with electrical encapsulation commanding premium pricing through IEC certification requirements while coatings compete on throughput economics.
- Adhesives:Structural bonding systems for civil engineering and transportation assembly. CE marking under the Construction Products Regulation creates specification barriers for bridge reinforcement contractors in France and Germany.
- Coatings:Protective and decorative film-forming systems across industrial, marine, and automotive substrates. REACH SVHC restrictions on legacy bisphenol-A formulations are accelerating curative substitution programs among German automotive OEMs.
- Composites:Matrix binders for fiber-reinforced structures in wind energy, aerospace, and sporting goods. Vacuum infusion-grade demand clusters around Esbjerg, Cuxhaven, and Ostend port facilities serving North Sea offshore installation.
- Electrical Encapsulation:Insulating compounds for transformers, switchgear, and electronic components. IEC 61215 certification timelines extending 18-24 months freeze supplier relationships for high-voltage equipment manufacturers.
Composites absorb the largest volume share. Electrical encapsulation delivers the steepest expansion trajectory as grid infrastructure investment accelerates.
End User:
Customer concentration patterns reshape channel economics, with aerospace and wind energy consolidating procurement through direct long-term contracts while construction remains fragmented across distributor tiers.
- Aerospace:Primary structures and interior components for commercial and defense aircraft. Airbus supply chain requirements in Toulouse and Hamburg drive qualification protocols for prepreg and resin transfer molding systems.
- Construction:Structural adhesives, flooring systems, and concrete repair compounds. Infrastructure stimulus programs in Poland and the Baltic States are pulling Eastern European demand.
- Automotive:Lightweight structural composites and corrosion-resistant coatings. German OEM cathodic electrocoat lines specify epoxy primers with integrated bio-based feedstock documentation.
- Marine:Hull laminates, deck coatings, and underwater repair systems. Dutch and Italian yacht builders concentrate specification authority for premium marine grades.
Construction leads by volume absorption. Aerospace posts the most rapid specification evolution as thermoplastic substitution threats intensify.
Distribution Channel:
Channel structure reflects customer scale and technical service intensity, with bulk wind energy procurement bypassing traditional intermediaries entirely.
- Direct Sales:Mill-to-fabricator contracts for high-volume composite and coating applications. Vestas and Siemens Gamesa procurement teams negotiate multi-year supply agreements with bio-based allocation guarantees.
- Distributors:Regional stockholding intermediaries serving fragmented coating applicators and construction contractors. Brenntag and IMCD maintain pan-European warehouse networks for solid epoxy and curative blends.
- Online Sales:Digital procurement platforms for standard grades and small-laboratory quantities. Specialty chemical marketplaces are gaining traction among R&D formulators.
- Retail:Consumer-packaged systems for marine repair and hobbyist applications. French and Italian chandleries represent the primary retail channel for marine-grade epoxies.
Direct sales dominate value capture. Online channels are gaining share fastest among specialty grade purchasers seeking supply chain transparency documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's epoxy resins trade flows reflect a structural import dependency for solid grades alongside growing captive bio-based epichlorohydrin capacity in the northwest. Export competitiveness hinges on REACH-compliant specialty formulations rather than commodity volume.
Germany
Wind blade manufacturing at Cuxhaven and Bremerhaven drives vacuum infusion-grade consumption, while BASF SE's Ludwigshafen complex supplies captive bisphenol-A for aerospace-qualified systems. The EU Green Deal's carbon border adjustments accelerate bio-based feedstock investments across North Rhine-Westphalia chemical corridors.
France
Airbus procurement at Toulouse and Hamburg anchors prepreg demand for primary aircraft structures, with Arkema S.A. serving qualification protocols for resin transfer molding. REACH SVHC restrictions on legacy curatives force reformulation timelines at electrical encapsulation facilities serving high-voltage transformer manufacturers.
Netherlands
Marine repair yards in Rotterdam and yacht builders specify low-viscosity grades for hull lamination, while port infrastructure at Europoort clusters epoxy distribution for North Sea offshore wind installation. ECHA registration mandates govern monomer purity thresholds for formulations exported across EU member states.
Denmark
Vestas procurement teams negotiate multi-year supply agreements with bio-based allocation guarantees at Esbjerg blade fabrication facilities. Direct long-term contracting between wind farm developers and formulators displaces traditional distributor-mediated procurement across Danish offshore clusters.
Poland
Wind blade manufacturing capacity migrates eastward from mature German and Danish bases, creating greenfield formulation demand at emerging Baltic fabrication hubs. Infrastructure stimulus programs pull construction adhesive volumes for bridge reinforcement and concrete repair applications.
Europe Epoxy Resins Market Competitive Landscape
Listed leaders compete with private specialists across formulation complexity tiers, with integrated petrochemical majors commanding upstream feedstock security and mid-cap compounders dominating application-specific service. The vendor base separates into three archetypes: captive feedstock integrators, specialty formulation houses, and distributor-aligned blenders. Competitive moves center on bio-based supply chain partnerships and REACH-compliant portfolio restructuring ahead of ECHA restriction deadlines.
Within the captive feedstock tier, BASF SE and Covestro AG exemplify integrated positioning through Ludwigshafen and Leverkusen chemical complexes. Among specialty chemical houses, Arkema S.A. and Evonik Industries AG occupy formulation-intensive segments where qualification timelines freeze supplier relationships. Huntsman International LLC and Olin Corporation represent transatlantic scale players competing on volume pricing for wind energy procurement panels.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Arkema S.A. |
| Evonik Industries AG |
| Huntsman International LLC |
| Olin Corporation |
| Solvay SA |
| Sika AG |
| 3M Company |
| Others |
Supply & Pricing Matrix
Sixty-day epichlorohydrin inventory cycles at Rotterdam port terminals compress formulation margins for distributors while amplifying pricing leverage for integrated producers with captive bisphenol-A supply. REACH registration deadlines and EU Green Deal carbon border adjustments are tightening procurement timelines and reshaping supplier selection criteria across European epoxy value chains.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across wind energy and aerospace segments. Pricing stratifies across IEC-certified premium grades for electrical encapsulation, vacuum infusion-compatible mid-tier formulations for blade manufacturing, and economy-grade solid resins for powder coating applicators. Cost compression in standard-grade liquid epoxy intensifies as Asian import volumes compete with regional bio-based production. Wind turbine OEMs exhibit lowest price sensitivity due to specification lock-in and qualification timelines, while construction adhesive contractors face acute margin pressure from distributor markups.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes expose solid epoxy resin importers to extended lead times and inventory carrying cost inflation. Feedstock supply concentrates in Germany, the Netherlands, and Belgium for bio-based epichlorohydrin, while China and South Korea dominate solid resin bulk exports. Production rests on propylene-chlor-alkali chemistry for epichlorohydrin and bisphenol-A purity grades for specialty formulations. Single-source vulnerability pervades electrical encapsulation segments where IEC 61215 certification freezes supplier relationships. Distribution runs through direct mill-to-fabricator contracts for high-volume composite applications and regional distributor networks for fragmented coating segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epoxy resin procurement platforms are consolidating around bio-based feedstock certification and supply chain transparency documentation, with interoperability between turbine OEM specification systems and formulator compliance databases emerging as the critical ecosystem layer.
For Market Incumbents: Consolidate backward integration into bio-based epichlorohydrin production ahead of EU Green Deal carbon border enforcement. Secure REACH-compliant alternative curative supply agreements to preempt bisphenol-A restriction disruptions. Capacity concentration in North Sea port clusters amplifies logistics efficiency against Asian import competition. For New Entrants and Emerging Players: Technical service gaps in vacuum infusion process support for Baltic States wind blade fabricators open specification windows beyond incumbent distributor relationships. Target Poland and emerging Baltic fabrication hubs with localized formulation blending and on-site laminator training. Partner with ECHA-registered bio-based feedstock suppliers to bypass legacy petrochemical qualification barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-optimized epoxy specialty portfolios. Mid-term viability centers on formulators with captive bio-based supply agreements and electrical encapsulation certification depth. Monitor ECHA restriction proposal timelines as inflection signals for alternative curative chemistry valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstock | Captive epichlorohydrin supply insulates German producers from EU carbon border adjustment exposure. |
| Long-Term Supply Agreement | Vestas and Siemens Gamesa procurement panels consolidate around multi-year bio-based allocation contracts. |
| Joint Venture | Polish fabrication hub development attracts co-investment between epoxy formulators and turbine OEMs. |
| Green Manufacturing Transition | REACH-compliant alternative curative production lines qualify for EU Green Deal transition financing. |
| Capacity Expansion | Low-viscosity grade production scale-up serves next-generation offshore wind blade dimensions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA registration databases, Cefic industry statistics, customs trade flows, and SEC filings from listed chemical producers. Primary interviews engaged plant managers at integrated resin complexes, procurement leads at Vestas and Siemens Gamesa, distribution channel partners at Brenntag and IMCD, and technical R&D directors at specialty formulators. Bottom-up volume modeling triangulates against top-down value estimates from trade association aggregates and producer revenue disclosures.
Segmentation dimensions modeled include viscosity grade tier, application end-use, regional production hub concentration, and bio-based feedstock certification status. CAGRs derive from regression analysis of historical trade flows and projected capacity additions across the analysis window. Forecast inputs incorporate ECHA restriction proposal timelines, EU Green Deal implementation schedules, and offshore wind installation targets from national energy plans.
Material uncertainties — ECHA regulatory acceleration, natural gas price volatility affecting chlor-alkali economics, and thermoplastic composite substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding bio-based epichlorohydrin scale-up timelines and REACH compliance cost pass-through elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Acrylic Polymer Emulsion Market