
 Functional Safety Market | 2026-2036
Functional Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Safety Market Intelligence
The capability gap between providing fully integrated, certified safety systems and supplying individual components is bifurcating the market. Large, diversified firms like Siemens AG leverage extensive portfolios to deliver end-to-end solutions for complex process industries. In contrast, specialists such as Rockwell Automation Inc. dominate specific industrial automation control niches with targeted offerings. ABB Ltd. competes through its deep expertise in robotics and electrification safety systems across multiple end-user segments.
Functional safety refers to the active protection systems that automatically mitigate unacceptable risk of physical injury or damage to health. It ensures a control system correctly responds to inputs, with performance quantified by specific metrics like Safety Integrity Levels (SIL). The market for complete Safety Instrumented Systems remains a core revenue source for process industries. However, sales of individual safety sensors and controllers are accelerating, driven by adoption within the automotive OEM and consumer electronics verticals.
A stringent regulatory environment underpins market structure, guided by key international standards. The foundational IEC 61508 standard, along with derivatives like IEC 61511 for process industries and ISO 26262 for road vehicles, dictates design requirements. These frameworks mandate rigorous hazard analysis, compelling the use of certified systems. Vendor selection increasingly hinges on demonstrating auditable compliance with these evolving safety standards.
Market Dynamics
The central structural force shaping the market is the bifurcation between supplying individual safety components and providing fully integrated, certified systems. This divergence is driven by the increasing complexity of standards like ISO 26262, compelling end-users to seek single-source accountability.
Growth Catalysts
- Automotive Standards:The widespread adoption of the ISO 26262 standard for road vehicles, particularly for autonomous driving systems, compels OEMs to integrate certified safety components and software, driving volume demand.
- Industrial Automation:Proliferation of robotics and connected machinery in smart factories under Industry 4.0 initiatives necessitates robust safety systems compliant with IEC 61508 to protect human workers in collaborative environments.
- Process Industry Modernization:Aging infrastructure in oil and gas or chemical processing sectors requires upgrades to Safety Instrumented Systems (SIS) to meet current IEC 61511 standards and mitigate operational risks.
Market Restraints
- High Certification Costs:The significant expense and time required for system and component certification by accredited bodies act as a major barrier, particularly for smaller manufacturers or new market entrants.
- Integration Complexity:Integrating modern functional safety systems with legacy industrial control infrastructure that was not designed for such protocols presents significant technical and financial hurdles for asset owners.
- Design Rigidity:The rigorous, front-loaded design and validation processes mandated by safety standards can limit flexibility and slow down development cycles, conflicting with agile methodologies in software-heavy industries.
Strategic Opportunities
- Software-as-a-Service (SaaS):The emergence of cloud-based platforms for safety lifecycle management, including documentation, analysis, and verification, offers a scalable, recurring revenue model for service providers.
- Medical Devices:Applying functional safety principles and standards, adapted from IEC 61508, to active medical devices like infusion pumps and surgical robots presents a high-value adjacent market.
- Training and Certification Services:A growing capability gap creates demand for professional training and personnel certification programs, such as the Certified Functional Safety Expert (CFSE), for engineers and managers.
Industry Challenges
- Talent Scarcity:A persistent shortage of engineers possessing dual expertise in a specific application domain (e.g., automotive, chemical processing) and the intricacies of functional safety standards hinders project execution.
- Supply Chain Verification:Ensuring and documenting the safety integrity of components sourced from a multi-tiered global supply chain, including commercial-off-the-shelf (COTS) software, is a major compliance challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Safety Market |
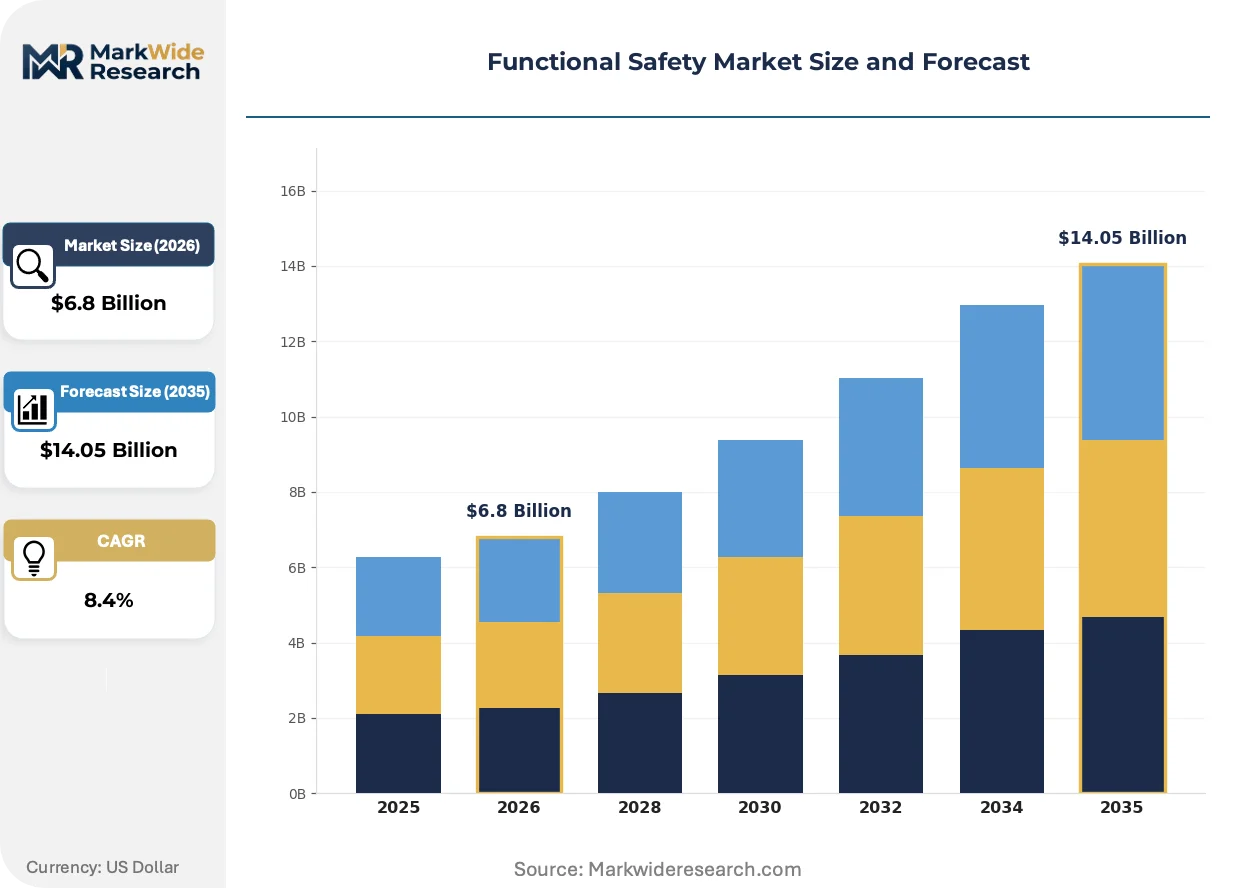
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Controllers, Safety Sensors, Safety Relays, Safety Instrumented Systems, Emergency Stop Devices Industry Vertical: Process Automation, Automotive OEMs, Aerospace, Consumer Electronics, Energy Production Technology: Fault Tolerant Systems, Redundancy Architectures, Diagnostic Coverage, SIL Certification, Risk Assessment Tools End User: Manufacturing Plants, Oil & Gas Facilities, Chemical Processing Units, Transportation Operators, Infrastructure Management |
| Companies Covered | Emerson Electric Co., Siemens AG, ABB Ltd., Omron Corporation, Yokogawa Electric Corporation, Honeywell International Inc., Schneider Electric SE, General Electric Company, Rockwell Automation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Safety Market Strategic Shifts & Innovations
The convergence of software-defined architectures with stringent international safety standards is fundamentally altering how safety is designed, validated, and deployed. This shift moves the focus from discrete hardware protection to a holistic, lifecycle-managed discipline, especially in highly automated systems.
Artificial intelligence and machine learning algorithms are being introduced for advanced diagnostic and predictive monitoring within safety systems. Automotive OEMs are early adopters, using these technologies to enhance the reliability of sensor fusion in ADAS. This software-centric approach is displacing traditional, purely hardware-based redundant logic controllers in certain non-critical monitoring functions.
Forthcoming regulations like the EU AI Act are set to formalize risk-based requirements for systems incorporating artificial intelligence. The regulation mandates rigorous conformity assessments and post-market monitoring for high-risk AI, including many safety-critical applications in robotics and autonomous vehicles. European machinery manufacturers are consequently embedding auditable data governance and safety frameworks into their design processes.
A notable behavioral change is the move from purchasing individual certified components to procuring pre-certified, integrated subsystems or software platforms. This disrupts the business model for component-level distributors, as end-users increasingly favor solution integrators who assume system-level responsibility. This procurement pattern is most visible within the industrial automation sector, particularly among machine builders in Germany and Italy.
Functional Safety Market Segmentation
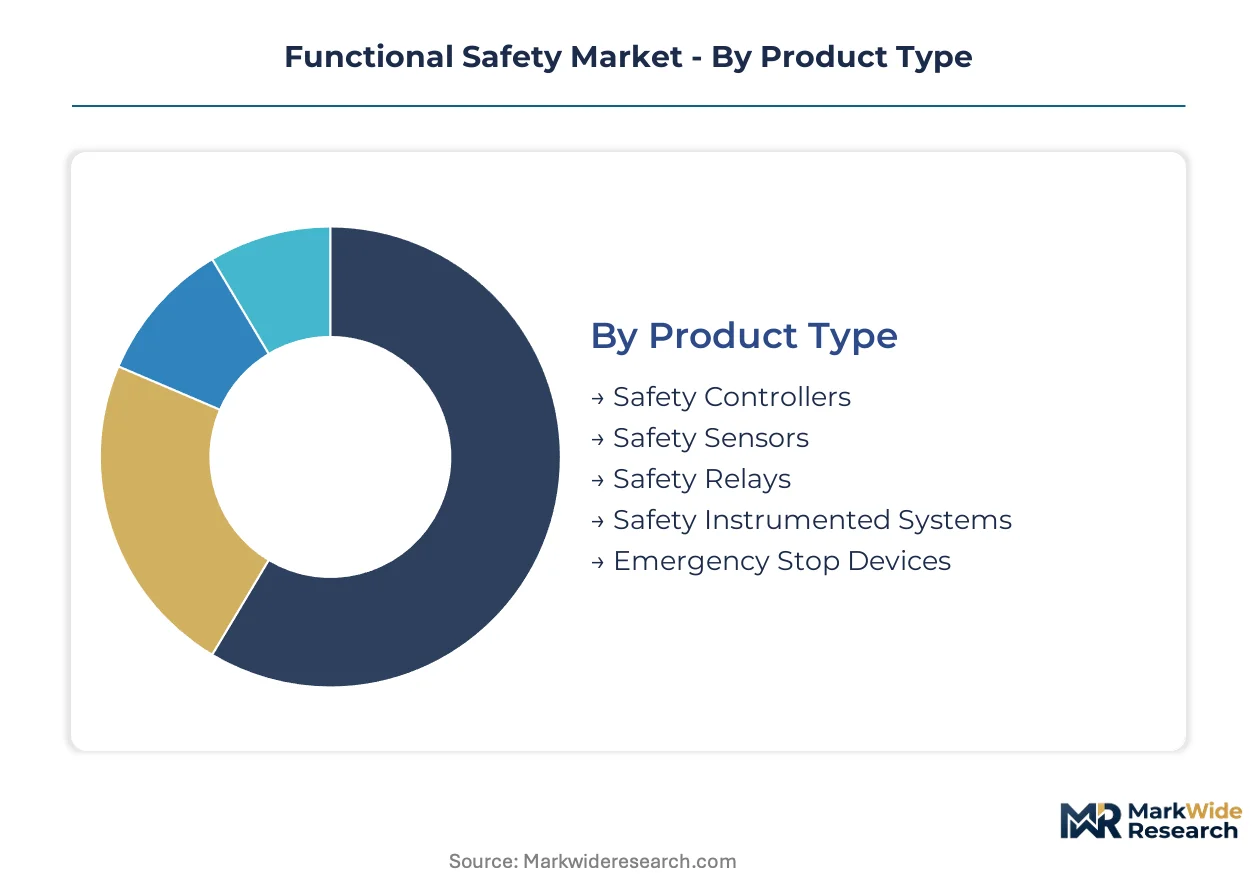
The functional safety market exhibits diverse requirements across industries, necessitating a granular understanding of product types, technologies, and end-user demands. Segmenting the market reveals distinct growth drivers and regulatory pressures. This breakdown highlights established revenue areas and emerging opportunities for safety solution providers.
Product Type:
The geographic spread of functional safety product types varies, with some components seeing high domestic integration in advanced manufacturing hubs, while others are widely exported for diverse applications. Demand for certified systems is particularly concentrated in specific regions.
- Safety Instrumented Systems:These comprehensive solutions integrate sensors, logic solvers, and final elements to achieve a specified Safety Integrity Level. Demand concentrates within Germany's process industries, driven by the need to upgrade aging infrastructure to meet IEC 61511 standards.
- Safety Sensors:These devices detect hazardous conditions, including proximity, pressure, and temperature, acting as the initial input for safety functions. Adoption is accelerating within automotive OEMs in Japan, integrating into advanced driver-assistance systems under ISO 26262 requirements.
- Safety Controllers:Programmable logic controllers (PLCs) or dedicated safety relays that execute safety functions based on sensor inputs.
- Safety Relays:Electromechanical or electronic devices designed to perform safety functions, ensuring machinery stops safely.
- Emergency Stop Devices:Manual actuators designed to initiate an immediate cessation of hazardous machine operation.
Safety Instrumented Systems command the established base. The steepest expansion runs through Safety Sensors.
Industry Vertical:
Application complexity significantly shapes the functional safety market across industry verticals, with highly regulated sectors demanding more intricate and integrated solutions compared to those with simpler safety requirements.
- Automotive OEMs:This segment requires advanced functional safety for autonomous driving features and electric vehicle systems. Germany's automotive manufacturers are at the forefront, integrating ISO 26262 compliant components into new vehicle platforms.
- Process Automation:Industries like oil and gas, chemicals, and pharmaceuticals rely on functional safety to prevent catastrophic incidents. Upgrades to Safety Instrumented Systems in the United States and Saudi Arabia are essential for operational continuity.
- Aerospace:Aviation manufacturers implement functional safety for flight control systems and ground support equipment.
- Consumer Electronics:This vertical sees increasing demand for functional safety in smart home devices and portable medical equipment.
- Energy Production:Power generation facilities, including nuclear and renewable energy plants, require robust safety systems for critical infrastructure.
Process Automation maintains a foundational position. Automotive OEMs are gaining share fastest.
Technology:
The maturity of functional safety technologies varies, with established methodologies like redundancy architectures coexisting with emerging advancements in diagnostic capabilities and risk assessment tools.
- SIL Certification:This process validates that a safety function or system meets a specified Safety Integrity Level, crucial for regulatory compliance. Demand for certified systems is high in Europe, particularly within machinery manufacturing and process industries.
- Diagnostic Coverage:This refers to the ability of a system to detect internal faults, vital for maintaining safety integrity in complex designs. Automotive applications in South Korea are increasingly leveraging advanced diagnostics for sensor fusion in ADAS.
- Fault Tolerant Systems:Designs that allow a system to continue operating correctly even in the presence of component failures.
- Redundancy Architectures:Employing multiple components in parallel to ensure system operation if one component fails.
- Risk Assessment Tools:Software and methodologies used to identify, analyze, and evaluate potential hazards in a system.
Fault Tolerant Systems form the core technological base. SIL Certification is climbing the fastest.
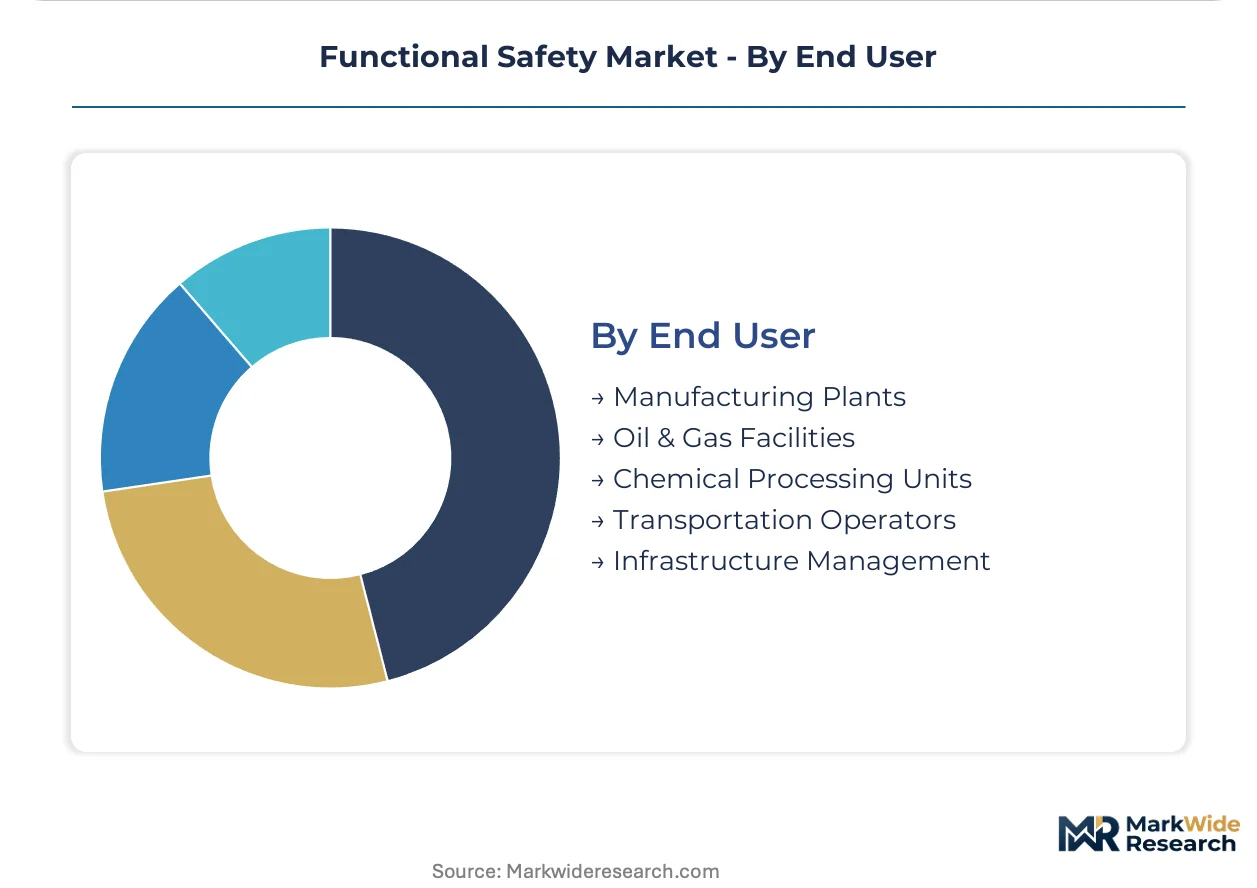
End User:
Customer type dictates the scale and specific requirements for functional safety solutions, ranging from large industrial operators needing extensive integrated systems to smaller entities seeking specialized components.
- Manufacturing Plants:These facilities integrate functional safety into robotics, automated assembly lines, and collaborative workspaces. Germany's advanced manufacturing sector drives demand for IEC 61508 compliant systems under Industry 4.0 initiatives.
- Oil & Gas Facilities:Functional safety is critical in upstream, midstream, and downstream operations to prevent explosions and environmental disasters. Operators in the United States and Canada require robust Safety Instrumented Systems for plant modernization.
- Chemical Processing Units:These units require precise control and safety interlocks to manage hazardous materials and reactions.
- Transportation Operators:Functional safety is essential for railway signaling, aerospace systems, and road vehicle control.
- Infrastructure Management:This includes safety systems for smart city applications, public utilities, and building automation.
Oil & Gas Facilities represent a significant established end-user segment. Manufacturing Plants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A significant pricing-power asymmetry exists between highly regulated markets like Germany and regions prioritizing cost-effective component integration such as parts of Asia. This divergence shapes procurement strategies across the functional safety market. End-users in mature economies often demand fully certified, integrated systems.
Germany
Demand for certified functional safety systems in Germany is driven by stringent automotive standards and advanced manufacturing initiatives. The KBA mandates rigorous safety assessments for vehicle components, compelling OEMs to integrate ISO 26262 compliant solutions. German automotive manufacturers in Bavaria and North Rhine-Westphalia are at the forefront of integrating these advanced safety technologies.
Japan
Japan's functional safety market sees accelerated adoption of safety sensors within its automotive OEMs for advanced driver-assistance systems. METI guidelines encourage robust safety standards across industrial sectors, impacting system design and implementation. Automotive hubs in Nagoya and Toyota City are key centers for developing and integrating ISO 26262 compliant components.
United States
The United States functional safety market is propelled by the modernization of process automation in oil and gas and chemical sectors. OSHA regulations necessitate continuous upgrades to Safety Instrumented Systems to prevent catastrophic incidents. Operators along the Gulf Coast, particularly in Houston, are investing heavily in robust SIS for plant operational continuity.
South Korea
South Korea's automotive industry is increasingly leveraging advanced diagnostics for sensor fusion in ADAS, driving demand for sophisticated functional safety solutions. The Korean Agency for Technology and Standards (KATS) promotes the adoption of international safety standards across diverse industries. The Seoul Capital Area is a hub for automotive R&D, focusing on advanced safety features and compliant systems.
China
China's industrial automation sector, particularly with the proliferation of robotics in smart factories, drives demand for robust functional safety systems. GB standards are increasingly aligning with international norms like IEC 61508, influencing safety design and certification. Manufacturing hubs in the Yangtze River Delta are rapidly adopting these safety technologies for collaborative environments.
Functional Safety Market Key Industry Players
Concentration sits with large, diversified industrial conglomerates offering end-to-end solutions across various sectors. The market also features specialized firms dominating specific industrial automation niches with targeted offerings. Competitive positioning is often achieved through portfolio diversification and strategic partnerships to address complex safety requirements.
Large, diversified firms like Siemens AG exemplify the archetype of an integrated solution provider, leveraging extensive portfolios to deliver complex process industry solutions. ABB Ltd. occupies a similar position, known for its deep expertise in robotics and electrification safety systems across multiple end-user segments. In contrast, Rockwell Automation Inc. represents a specialist approach, dominating specific industrial automation control niches with targeted offerings.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Siemens AG |
| ABB Ltd. |
| Omron Corporation |
| Yokogawa Electric Corporation |
| Honeywell International Inc. |
| Schneider Electric SE |
| General Electric Company |
| Rockwell Automation Inc. |
| Others |
Cost & Logistics Intelligence
Economies of scale in certified component manufacturing shape both supply concentration and price floors across the functional safety market. This dynamic influences procurement strategies for end-users seeking compliant solutions.
Pricing Analysis
Configured-to-order safety systems command a premium over standardized components, reflecting the customization-premium spread. The dominant pricing model for complex Safety Instrumented Systems remains project-based, while individual sensors and controllers are transactional. Price differentiation stems from the specific certification level required (e.g., ISO 26262, IEC 61508) and the degree of integration complexity. Pricing softness runs through commoditized safety components due to competitive pressures. Automotive OEMs in Germany, requiring highly integrated solutions, exhibit lower price sensitivity compared to smaller industrial machine builders.
Supply Chain Analysis
The specialized expertise required for functional safety certification creates a supply chokepoint for critical components. Supply concentration centers in Germany, Japan, and the United States, reflecting advanced manufacturing capabilities. The market relies on microcontrollers, specialized sensors, and certified software modules as key inputs. Single-source vulnerability for highly certified, application-specific components presents a structural supply chain risk. Distribution for integrated systems primarily runs through direct sales to large industrial operators and automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The functional safety market represents a defensive moat, primarily due to the deep regulatory entrenchment of standards like ISO 26262 and IEC 61508. This mandates rigorous compliance, creating high barriers to entry.
For Market Incumbents:
Compound existing advantages by investing heavily in continuous certification upgrades for both hardware and software. Acquire specialized software firms offering tools for safety lifecycle management to counter agile software-centric disruptors. Focus R&D on integrating AI/ML for advanced diagnostics, especially for ADAS applications. Control distribution channels through strategic partnerships with system integrators to maintain market share against talent scarcity.
For New Entrants and Emerging Players:
Anchor in niche applications where current solutions are fragmented or under-served, such as functional safety for active medical devices or specialized smart home components. Target specific industrial automation niches with cloud-native safety software as a service. Penetrate the consumer electronics vertical by focusing on software-defined safety features. A go-to-market angle emphasizing rapid deployment and simplified compliance documentation offers a distinct advantage.
For Investors and Strategic Acquirers:
Recurring-revenue conversion is highest among software-as-a-service providers offering safety lifecycle management platforms. The market exhibits long-term viability, driven by expanding automation and increasingly stringent global regulations. Target niche software firms with proprietary tools for hazard analysis or verification of specific safety standards (e.g., ISO 26262). The adoption rate of cloud-based safety platforms serves as a critical inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Certification Investment | Maintains compliance and competitive edge in regulated automotive and industrial sectors. |
| Software-Defined Safety R&D | Positions firms for future AI-driven diagnostic systems in ADAS and smart factories. |
| Integrated Solution Development | Addresses end-user demand for single-source accountability in complex safety systems. |
| Talent Development Programs | Mitigates critical talent scarcity for dual expertise in functional safety and application domains. |
| Adjacent Market Expansion | Captures new revenue streams in high-value sectors like medical devices and smart infrastructure. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings. Primary research involved discussions with functional safety engineers, compliance officers, automotive OEM R&D leads, and process industry plant managers. Secondary data sources included ISO/IEC standards documentation, KBA and OSHA regulatory reports, technical white papers, and company financial disclosures. This approach ensured both bottom-up and top-down triangulation of market insights.
Sensitivity analysis informed the quantitative modeling approach across the analysis window. The analytical framework integrated segmentation dimensions including product type, industry vertical, technology, end-user, and regional regulatory cluster. Compound annual growth rates were derived from historical data analysis and projected market growth drivers. Key industry-specific forecast inputs included autonomous driving penetration rates and Industry 4.0 investment trends.
Decision-makers should treat outputs as directional under assumptions of stable regulatory frameworks; material deviation would warrant model refresh. Forecasts reflect base assumptions regarding macroeconomic stability and consistent regulatory enforcement. Revision becomes warranted when key market drivers or regulatory landscapes cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Apparel Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Security System Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Alarm Management System Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market