
 Global Protective Face Mask Market | 2026-2036
Global Protective Face Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protective Face Mask Market Foresight
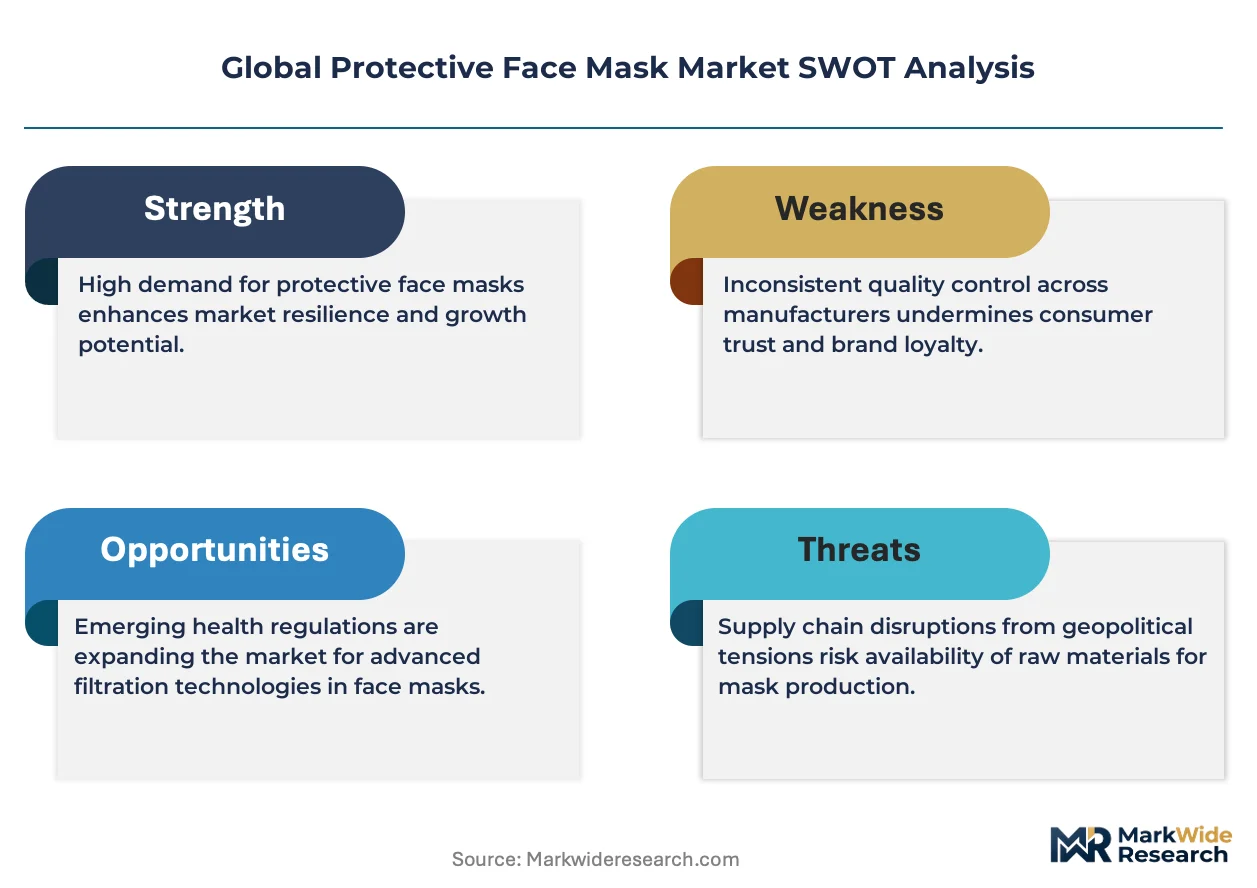
China is narrowing its cost advantage in melt-blown polypropylene output as Southeast Asian facilities scale. 3M Company leverages vertical integration across filtration media to sustain margin control. Honeywell International Inc. anchors North American industrial distribution through safety supply contracts.
Protective face masks are tight-fitting or loose-fitting barriers manufactured from multi-layer nonwoven fabrics, typically incorporating melt-blown polypropylene with bacterial filtration efficiency ratings exceeding 95 percent, designed to block aerosolized particles and droplet transmission in occupational and clinical environments. N95 respirators command premium positioning due to NIOSH certification requirements and limited qualified suppliers. Cloth masks occupy economy-tier channels through general public end-use, while surgical masks dominate hospital procurement volumes with standardized ASTM F2100 compliance.
FDA, NIOSH, and the EU Medical Device Regulation collectively determine market access through filtration efficiency testing, biocompatibility assessment, and post-market surveillance obligations. ASTM International and ISO 10993 standards further constrain material selection and manufacturing quality systems. Stakeholders must monitor evolving harmonization between FDA emergency use pathways and permanent device classification rules to anticipate compliance cost shifts.
Market Dynamics
Healthcare worker procurement is expanding across hospital systems, while the EU Medical Device Regulation tightens filtration performance thresholds and Southeast Asian facilities scale melt-blown polypropylene output to narrow China's cost dominance.
Growth Catalysts
- EU Medical Device Regulation:Tightened filtration performance thresholds are forcing manufacturers to upgrade quality systems and expand certified production capacity.
- Hospital systems:Healthcare worker procurement is expanding across acute care networks, driving volume commitments and multi-year supply agreements.
- Melt-blown polypropylene:Southeast Asian facilities are scaling output to narrow China's historical cost advantage in filtration media supply.
Market Restraints
- Input cost volatility:Polypropylene resin prices fluctuate with petrochemical feedstock markets, squeezing margin predictability for non-integrated manufacturers.
- Supply concentration risk:Qualified NIOSH-certified respirator suppliers remain limited, creating bottlenecks during demand surges.
- Substitution threat:Reusable elastomeric respirators are gaining traction in industrial settings, threatening disposable N95 volumes.
Strategic Opportunities
- India:Underpenetrated hospital supply chains and expanding CDSCO medical device frameworks create entry points for ASTM F2100-compliant manufacturers.
- Antimicrobial filtration:Convergence of copper-infused nonwovens with electrostatic charging technology opens premium positioning in surgical segments.
- E-commerce direct channels:Industrial safety distributors are building direct-to-facility platforms, bypassing traditional medical supply intermediaries.
Industry Challenges
- NIOSH certification timelines:Extended approval queues for new respirator designs delay product launches and tie up R&D capital.
- Legacy ERP integration:Hospital procurement systems require EDI compatibility and lot-level traceability, forcing middleware investments from smaller suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protective Face Mask Market |
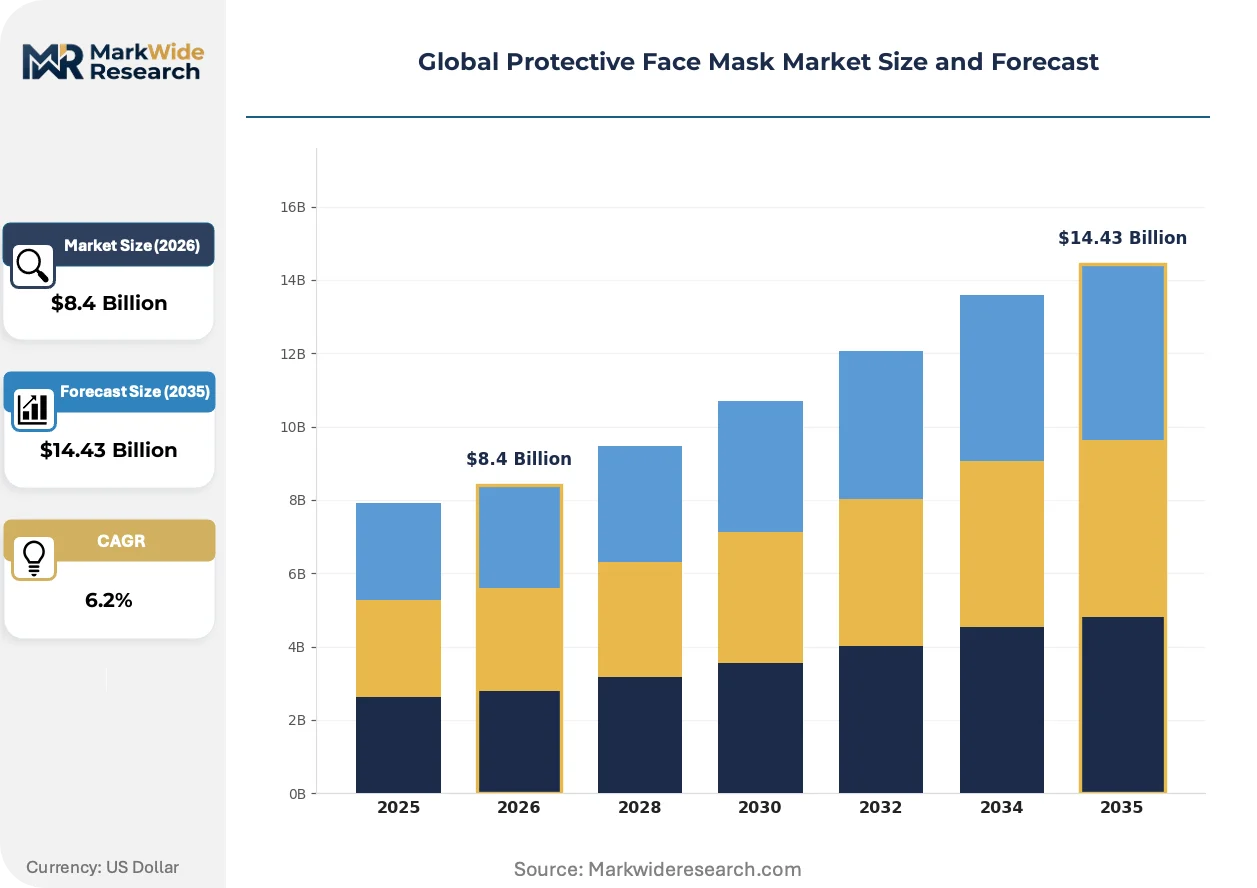
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Mask, N95 Respirator, Filtering Facepiece, Cloth Mask Material: Polypropylene, Cotton, Polyester, Nylon End User: Healthcare Workers, General Public, Industrial Workers, Travelers Distribution Channel: Online Retail, Pharmacies, Wholesale Distributors, Direct Sales |
| Companies Covered | 3M Company, Honeywell International Inc., Kimberly-Clark Corporation, Cardinal Health Inc., DuPont de Nemours Inc., Medline Industries Inc., Moldex-Metric Inc., MSA Safety Inc., Uvex Safety Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protective Face Mask Market Shifts & Advancements
Filtration media is undergoing material convergence, regulatory frameworks are hardening device classification rules, and procurement patterns are consolidating around certified supplier pools.
Electrospun nanofiber layers are hybridizing with conventional melt-blown substrates to achieve sub-micron capture without the breathing resistance penalties of denser media. Industrial hygiene managers in semiconductor cleanrooms are piloting these composite structures for extended-wear protocols. The technology is hybridizing product tiers, compressing the performance gap between surgical masks and respirators.
EU Medical Device Regulation post-market surveillance obligations are tightening adverse event reporting timelines and mandating periodic safety updates. Manufacturers must now maintain technical documentation across the full device lifecycle, not just pre-market submission. German hospital procurement consortia are responding by pre-qualifying suppliers with established quality management systems.
Hospital supply chains are consolidating vendor lists around dual-source certified manufacturers, replacing the fragmented spot-buying patterns of the emergency period. Group purchasing organizations are negotiating multi-year contracts with volume commitments and penalty clauses for non-delivery. This concentration is most visible in the United States, where health system mergers have reduced the number of independent contracting entities.
Global Protective Face Mask Market Segmentation
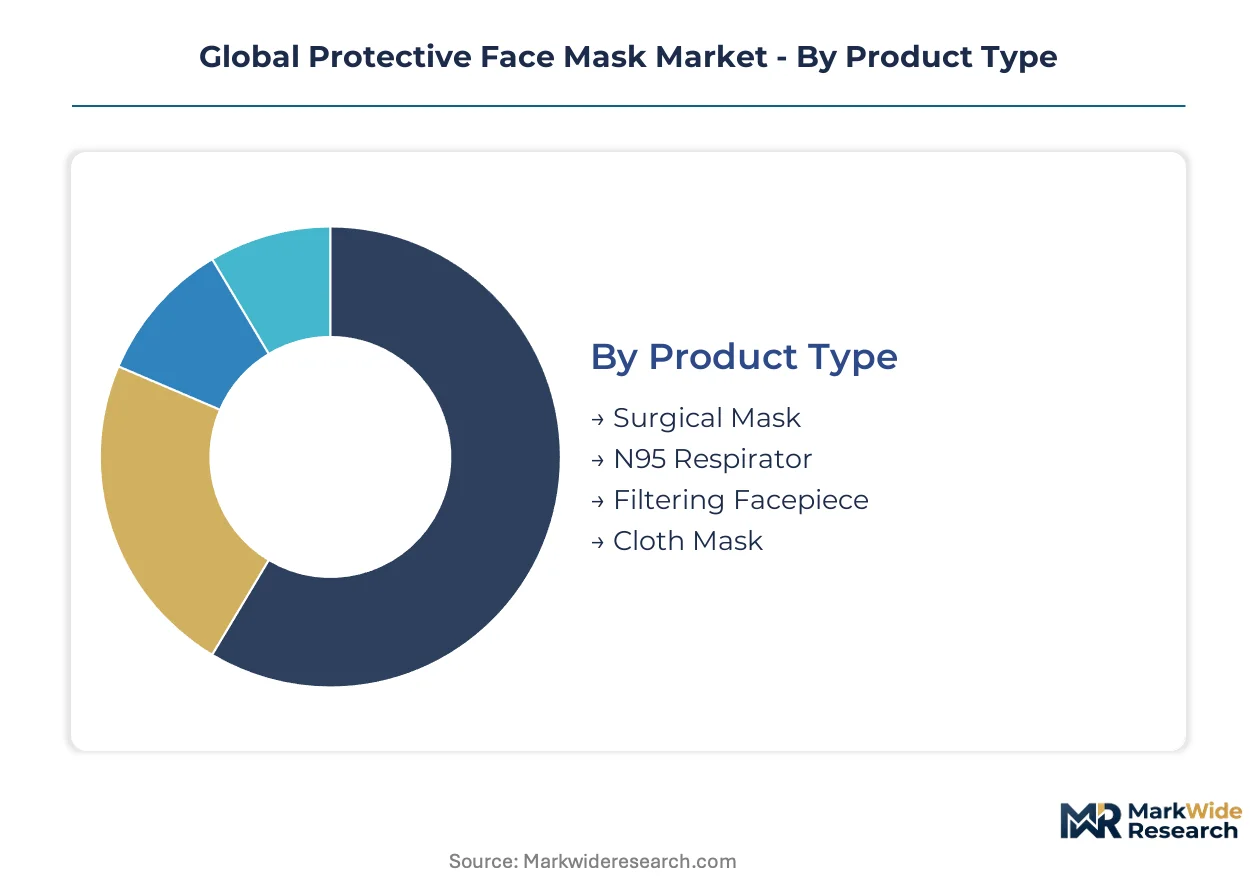
Protective face mask segmentation reveals how certification tiers, material science, and procurement channels create distinct commercial battlegrounds. Manufacturers must align product architecture with specific end-use liability profiles and distribution economics.
Product Type:
Maturity varies sharply across this category, with established hospital standards contrasting against emergent consumer formats.
- Surgical Mask:Multi-layer nonwoven construction meeting ASTM F2100 bacterial filtration efficiency thresholds dominates acute care procurement volumes. Hospital systems in Germany and the United States negotiate multi-year supply agreements with penalty clauses for non-delivery, consolidating vendor lists around dual-source certified manufacturers.
- N95 Respirator:NIOSH-certified tight-fitting filtration devices with electrostatic melt-blown media command premium positioning through limited qualified supplier pools. Extended approval queues for new designs delay product launches and tie up R&D capital, creating bottlenecks during demand surges.
- Filtering Facepiece:Disposable half-mask respirators bridge surgical and industrial applications with simplified fit testing protocols.
- Cloth Mask:Reusable fabric barriers occupy economy-tier channels through general public end-use with minimal regulatory oversight.
Surgical masks handle the majority of throughput; N95 respirators are climbing the fastest on margin contribution.
Material:
Cost tier alignment determines competitive positioning, from commodity synthetics to specialized filtration media.
- Polypropylene:Melt-blown grades with electrostatic charging properties form the functional core of medical-grade masks. Southeast Asian facilities are scaling output to narrow China's historical cost advantage in filtration media supply.
- Cotton:Natural fiber substrates serve reusable consumer masks with comfort-driven positioning and limited filtration performance claims.
- Polyester:Synthetic spunbond layers provide structural integrity in multi-ply constructions at intermediate cost points.
- Nylon:High-tenacity filaments reinforce ear loops and head straps in extended-wear industrial applications.
Polypropylene absorbs the dominant share of medical-grade volume; melt-blown grades are expanding most quickly on technical specification requirements.
End User:
Customer type fragmentation creates divergent liability and procurement patterns across occupational and civilian segments.
- Healthcare Workers:Hospital systems, clinics, and long-term care facilities drive ASTM F2100 and EN 14683 compliance requirements. Acute care networks are expanding procurement across integrated delivery systems with volume commitments and quality system audits.
- General Public:Consumer purchasing through retail and e-commerce channels emphasizes comfort, aesthetics, and price accessibility over standardized performance.
- Industrial Workers:Manufacturing, construction, and semiconductor cleanroom employers specify NIOSH or EN 149 respiratory protection with fit testing documentation.
- Travelers:Aviation and hospitality sector demand concentrates on disposable convenience formats with packaging suitable for carry-on logistics.
Healthcare workers anchor procurement volume stability; industrial workers are gaining share fastest on reusable elastomeric substitution threats.
Distribution Channel:
Supply concentration shapes margin capture, with direct contracts diverging from fragmented retail pathways.
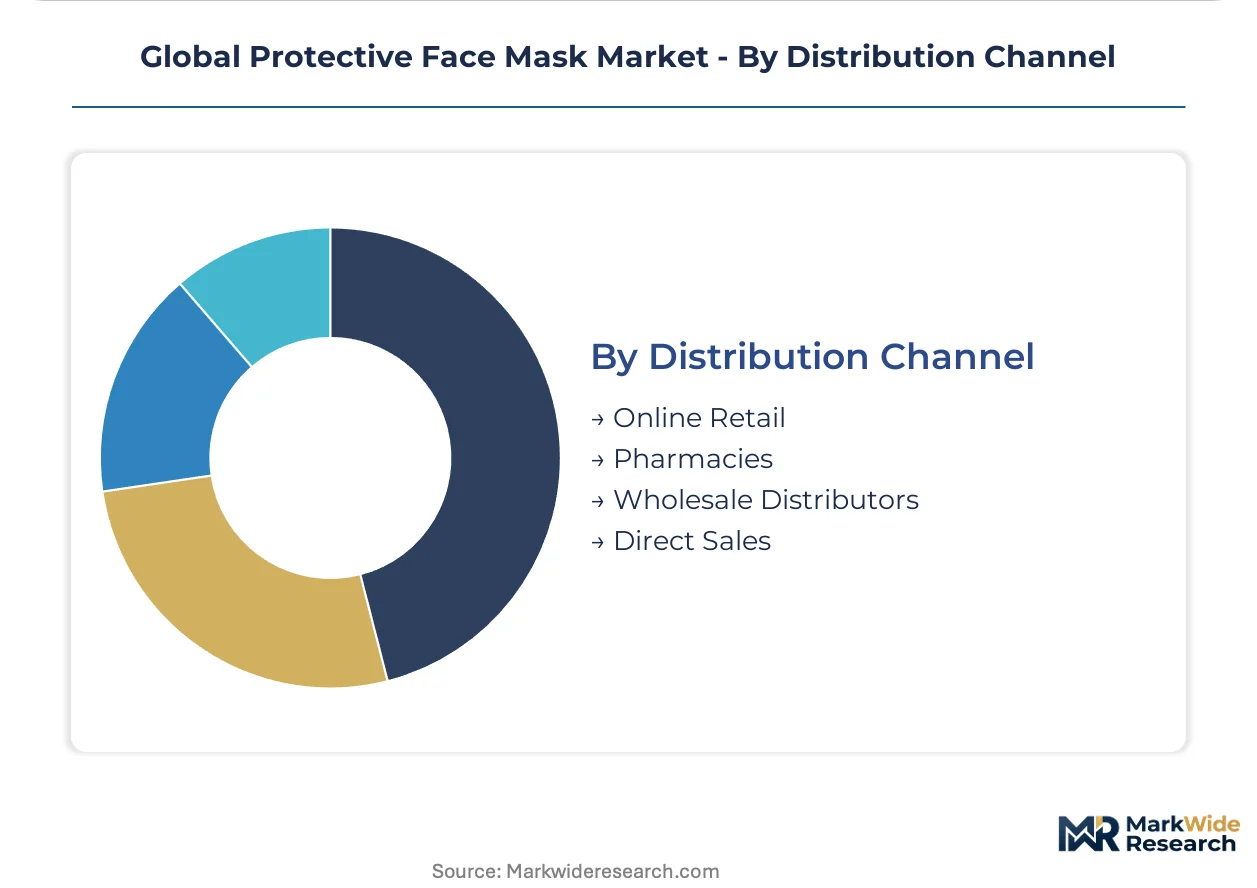
- Online Retail:Direct-to-consumer platforms and industrial safety marketplaces bypass traditional medical supply intermediaries. E-commerce channels are building direct-to-facility platforms with lot-level traceability and EDI compatibility for hospital procurement systems.
- Pharmacies:Brick-and-mortar retail networks serve emergency replenishment and consumer convenience purchasing with limited SKU depth.
- Wholesale Distributors:Medical supply and safety product intermediaries maintain inventory positions for spot-buying and contract fulfillment.
- Direct Sales:Manufacturer field organizations negotiate enterprise contracts with health systems and industrial accounts requiring technical support and training.
Wholesale distributors handle the majority of legacy hospital volume; online retail is expanding fastest on direct-to-facility platform investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement concentrates on ASTM F2100-compliant surgical masks, while US industrial buyers prioritize NIOSH-certified respirators for occupational liability coverage. Chinese manufacturing output dominates melt-blown polypropylene supply, though end-use consumption patterns diverge sharply across clinical, industrial, and civilian segments.
United States
Hospital system mergers have reduced independent contracting entities, consolidating vendor lists around dual-source certified manufacturers. FDA emergency use pathway harmonization with permanent device classification rules is forcing compliance cost recalculations. The Texas Medical Center in Houston anchors acute care procurement volume with multi-year supply agreements.
Germany
Hospital procurement consortia are pre-qualifying suppliers with established quality management systems under EU Medical Device Regulation post-market surveillance obligations. REACH compliance for filtration media biocompatibility assessment constrains material selection. The Rhine-Ruhr metropolitan region concentrates industrial safety distribution through specialized intermediaries.
China
Domestic manufacturers are scaling electrospun nanofiber hybridization for sub-micron capture applications in semiconductor cleanrooms. NMPA medical device registration requirements are tightening adverse event reporting timelines. The Yangtze River Delta cluster around Shanghai dominates melt-blown polypropylene output capacity expansion.
India
Underpenetrated hospital supply chains are expanding CDSCO medical device frameworks for ASTM F2100-compliant manufacturers. BIS certification for filtration efficiency testing creates entry barriers for imported products. Maharashtra's Mumbai-Pune industrial corridor anchors domestic nonwoven fabric production scaling.
Japan
Industrial hygiene managers in electronics manufacturing are piloting extended-wear protocols with composite filtration structures. METI standards for occupational respiratory protection mandate fit testing documentation. The Kanto region around Tokyo concentrates premium-tier procurement through integrated safety supply contracts.
Global Protective Face Mask Market Competitive Landscape
Capability concentration sits with vertically integrated filtration media specialists; scale advantage sits with diversified safety conglomerates. The vendor base separates into three tiers: premium NIOSH-certified respirator suppliers, mid-tier ASTM F2100 surgical mask fabricators, and economy-tier consumer mask assemblers. Strategic moves center on backward integration into melt-blown polypropylene production and multi-year hospital supply contract negotiations with penalty clauses.
Within the premium-tier NIOSH certification vector, 3M Company and Honeywell International Inc. occupy positions sustained by limited qualified supplier pools. Moldex-Metric Inc. represents the mid-tier specialist archetype focused on industrial distribution channels. Kimberly-Clark Corporation anchors the diversified health products conglomerate model with hospital procurement system integration capabilities.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| Kimberly-Clark Corporation |
| Cardinal Health Inc. |
| DuPont de Nemours Inc. |
| Medline Industries Inc. |
| Moldex-Metric Inc. |
| MSA Safety Inc. |
| Uvex Safety Group |
| Others |
Supply & Pricing Matrix
Melt-blown polypropylene capacity concentration in China's Yangtze River Delta anchors cost structures downstream, with margin pools accumulating at NIOSH-certified respirator suppliers who command premium positioning through limited qualified production lines. Polypropylene resin price volatility transmits directly to non-integrated surgical mask fabricators, compressing their operating leverage against hospital procurement consortia.
Pricing Analysis
Long-term offtake contracts with multi-year volume commitments dominate hospital system procurement, displacing the fragmented spot-buying patterns of emergency purchasing periods. Pricing stratifies across NIOSH-certified premium tiers, ASTM F2100 standard medical grades, and unregulated economy consumer channels. Cost compression in surgical mask tiers is intensifying because Southeast Asian melt-blown facilities are eroding China's historical feedstock advantage. Industrial buyers exhibit the lowest price sensitivity due to occupational liability coverage requirements, while general public consumers drive volume at margin-thin economy price points.
Supply Chain Analysis
Contract manufacturing concentration sits with vertically integrated filtration media specialists in China, Vietnam, and Malaysia who control electrostatic charging equipment and melt-blown extrusion lines. Finished mask assembly draws from polypropylene resin, spunbond structural layers, and aluminum nose strips as critical inputs. Single-source vulnerability concentrates in NIOSH-certified respirator qualified supplier pools, where extended approval timelines create bottlenecks during demand surges. Distribution runs through wholesale medical supply intermediaries for legacy hospital volume, with direct-to-facility e-commerce platforms gaining fastest on industrial safety procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified NIOSH production lines and certified quality management systems represent scarce, defensible capabilities that separate premium-tier suppliers from commodity assemblers. The gap between certified respirator manufacturers and economy-tier mask producers is widening as regulatory frameworks harden device classification rules.
For Market Incumbents: Harden defensive positions by deepening backward integration into melt-blown polypropylene production to insulate margin structures from petrochemical feedstock volatility. Secure dual-source hospital supply agreements with penalty clauses for non-delivery to lock out emerging competitors from acute care procurement networks. Reusable elastomeric respirator substitution in industrial settings threatens disposable N95 volumes; counter with extended-wear protocol development for semiconductor cleanroom applications. For New Entrants and Emerging Players: India's underpenetrated hospital supply chains offer the most penetrable entry point, where expanding CDSCO medical device frameworks create regulatory pathways for ASTM F2100-compliant manufacturers. Target Maharashtra's Mumbai-Pune industrial corridor for domestic nonwoven fabric production partnerships that satisfy BIS certification requirements. Build direct-to-facility e-commerce platforms with EDI compatibility and lot-level traceability to bypass entrenched wholesale distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier surgical mask fabricators lacking NIOSH certification but possessing established hospital procurement system integrations. Long-term viability hinges on regulatory compliance capabilities rather than scale alone, favoring targets with quality management system investments across the full device lifecycle. Watch NIOSH approval queue lengths as the inflection signal—shortening timelines would accelerate new entrant capacity and compress premium-tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| NIOSH Certification Investment | Unlocks premium hospital and industrial pricing tiers through limited qualified supplier pools. |
| Backward Integration into Melt-Blown Media | Captures margin from polypropylene resin conversion and insulates against feedstock volatility. |
| Hospital System Partnership | Secures multi-year volume commitments with penalty clauses under group purchasing organization contracts. |
| Direct-to-Facility E-Commerce Platform | Bypasses wholesale intermediaries with EDI-compatible lot-level traceability for procurement systems. |
| Antimicrobial Filtration Development | Opens premium surgical positioning through copper-infused nonwovens with electrostatic charging convergence. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and industrial hygiene directors; and secondary validation against FDA 510(k) filings, NIOSH certified equipment lists, EU MDR technical documentation databases, and hospital supply chain procurement records. Bottom-up volume estimates by product tier and end-use segment were triangulated against top-down market sizing from trade flow data and manufacturer capacity disclosures.
Forecast inputs considered certification tier penetration rates, hospital system merger consolidation patterns, and melt-blown polypropylene capacity expansion timelines across the analysis window. Segmentation modeling captured product type, material grade, end-user liability profile, and distribution channel economics. CAGRs were derived from volume trajectory analysis adjusted for regulatory compliance cost shifts and substitution dynamics from reusable elastomeric respirators.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Southeast Asian contract manufacturers or accelerated NIOSH approval streamlining would shift outcomes beyond modeled ranges. Quarterly review of certification queue lengths, hospital procurement contract renewal rates, and polypropylene resin price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Wearable Airbag Belt Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market