
 Luxury Vinyl Tile (LVT) Flooring Market | 2026-2036
Luxury Vinyl Tile (LVT) Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Vinyl Tile (LVT) Flooring Market Foresight
EU Green Deal building renovation targets is broadening specification pipelines for low-carbon flooring across commercial retrofit programs. Mohawk Industries leverages captive resin compounding to stabilize input costs across rigid-core formulations. Tarkett anchors European project pipelines through Cradle to Cradle-certified product lines. Shaw Industries Group dominates North American distribution through dedicated specification sales teams serving multi-family developers.
Luxury Vinyl Tile comprises multi-layer synthetic flooring with a PVC or SPC core, a printed decorative film, and a wear-layer measured in mils, engineered to replicate natural materials while delivering water resistance and dimensional stability. Click-lock rigid-core planks now lead residential replacement cycles due to faster install times and reduced subfloor prep. Wood-look designs occupy the largest share of specification value, though stone-look variants command premium positioning in hospitality lobbies and retail environments.
EPA TSCA Title VI formaldehyde standards, California Air Resources Board VOC limits, and EU REACH SVHC restrictions collectively determine adhesive chemistry and core composition eligibility for market access. Compliance documentation now functions as a pre-qualification filter in commercial bidding processes, particularly for healthcare and education sectors. Stakeholders must monitor evolving state-level chemical disclosure mandates and third-party certification proliferation as procurement criteria harden.
Market Dynamics
REACH SVHC restrictions and California's VOC emissions protocols are compressing formulation choices for adhesive and core-layer chemistry, forcing manufacturers to requalify supply chains while tier-one cities in China and India absorb specification volumes for waterproof, high-traffic surfaces.
Growth Catalysts
- EU Green Deal building renovation targets:Commercial retrofit programs across European member states are broadening specification pipelines for low-carbon flooring materials certified under Cradle to Cradle protocols.
- Click-lock rigid-core planks:Faster install times and reduced subfloor preparation requirements are accelerating residential replacement cycles in multi-family housing developments.
- Hospitality renovation cycles:Waterproof, high-traffic surface specifications are expanding volumes across hotel and resort property refreshes in China's tier-one cities and India's metropolitan commercial construction corridors.
Market Restraints
- Resin cost volatility:PVC and SPC core material input prices fluctuate with petrochemical feedstock markets, compressing margin stability for manufacturers without captive compounding capabilities.
- Formaldehyde compliance documentation:EPA TSCA Title VI standards function as pre-qualification filters in commercial bidding, creating friction for smaller producers lacking testing infrastructure.
- Natural material substitutes:Engineered hardwood and ceramic tile retain specification share in premium residential segments where authenticity signaling outweighs water resistance priorities.
Strategic Opportunities
- Healthcare sector penetration:Antimicrobial wear-layer formulations address infection control requirements in hospital and clinic environments where sheet vinyl currently dominates.
- Stone-look premium positioning:Hospitality lobbies and retail flagships in Dubai, Singapore, and London command elevated margins for large-format tile aesthetics replicating marble and travertine.
- Third-party certification proliferation:FloorScore, GREENGUARD, and BREEAM alignment opens specification access to public-sector procurement frameworks mandating chemical transparency.
Industry Challenges
- Installation technician certification:Click-lock and glue-down methods require distinct skill sets, creating bottlenecks as product mix shifts toward floating floor systems.
- State-level chemical disclosure mandates:Evolving reporting requirements across California, New York, and Washington force continuous reformulation and documentation updates.
- Multi-layer integration complexity:Decorative film registration, wear-layer adhesion, and core dimensional stability must synchronize across suppliers, amplifying quality control overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Vinyl Tile (LVT) Flooring Market |
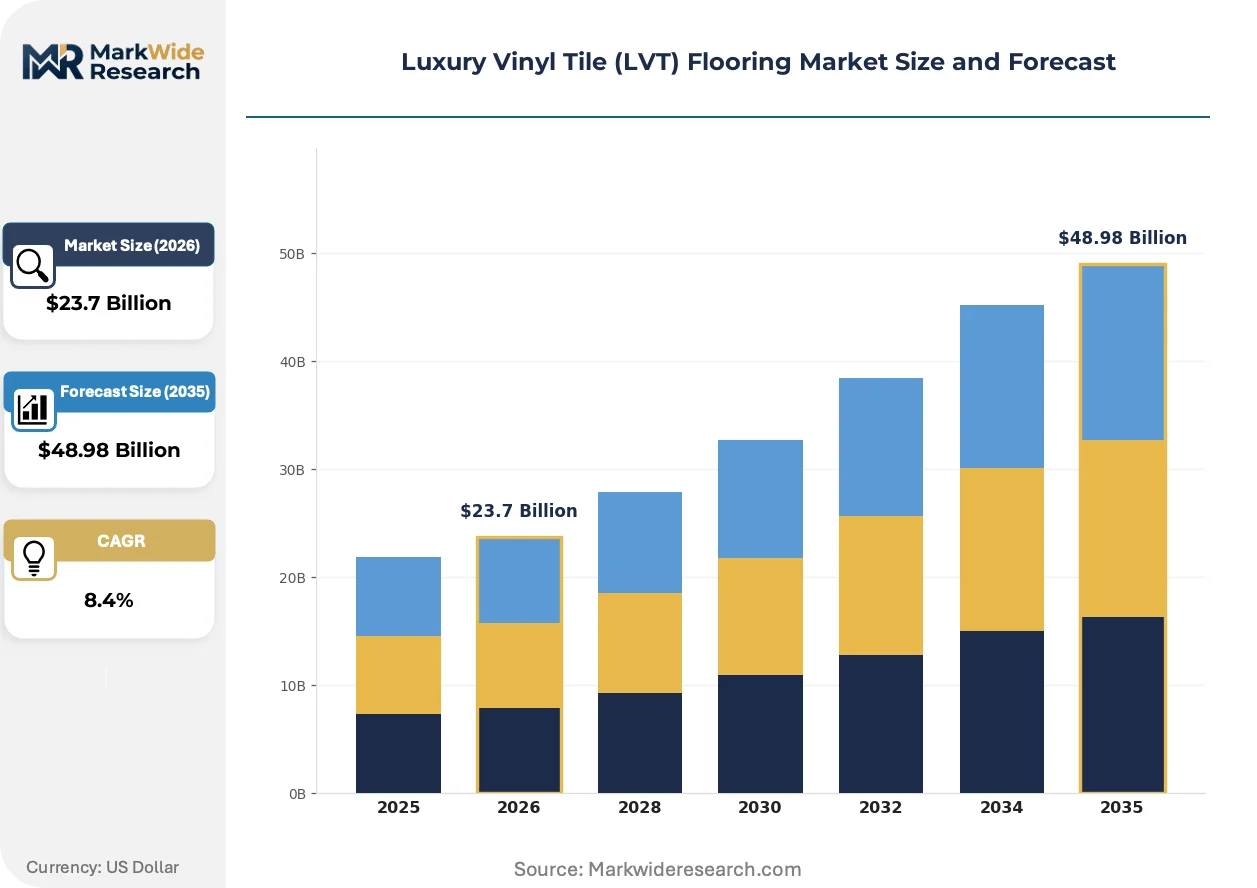
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glue-down, Floating, Click-lock, Loose-lay End User: Residential, Commercial, Industrial, Hospitality Design Style: Wood-look, Stone-look, Abstract, Vintage Thickness: 2mm, 4mm, 5mm, 6mm |
| Companies Covered | Shaw Industries Group, Gerflor, Mohawk Industries, Interface, Forbo Holding, Tarkett, Mannington Mills, LG Hausys, Armstrong Flooring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Vinyl Tile (LVT) Flooring Market Shifts & Advancements
Digital printing advancements and rigid-core material science are compressing the performance gap between synthetic flooring and natural materials, while regulatory chemical restrictions and procurement digitization are reshaping how specifications flow from architect to installer.
Digital decorative film technology is decentralizing design authority away from traditional material suppliers. Print-to-order capabilities allow regional distributors to stock unprinted core inventory and apply wood-grain or stone-look patterns on demand. Hospitality and retail specifiers in North America and Western Europe are adopting this model to compress lead times for custom color matching. The technology is decentralizing inventory concentration from manufacturer hubs to regional distribution nodes.
EU REACH SVHC candidate list expansions are tightening adhesive chemistry eligibility for market access. Industrial consequences include accelerated phase-out of phthalate plasticizers and isocyanate-based bonding agents in favor of waterborne acrylic and bio-based polyurethane alternatives. Healthcare and education sectors in Germany, France, and the Netherlands are responding by embedding ECHA compliance documentation into pre-qualification questionnaires.
Specification sales team deployment is consolidating influence over multi-family developer procurement decisions. Dedicated technical representatives now accompany product samples through design development and value engineering phases, displacing traditional distributor-led selling in volume residential projects. This pattern is most visible across the Sun Belt metropolitan corridors of the United States where build-to-rent construction is concentrating.
Luxury Vinyl Tile (LVT) Flooring Market Segmentation
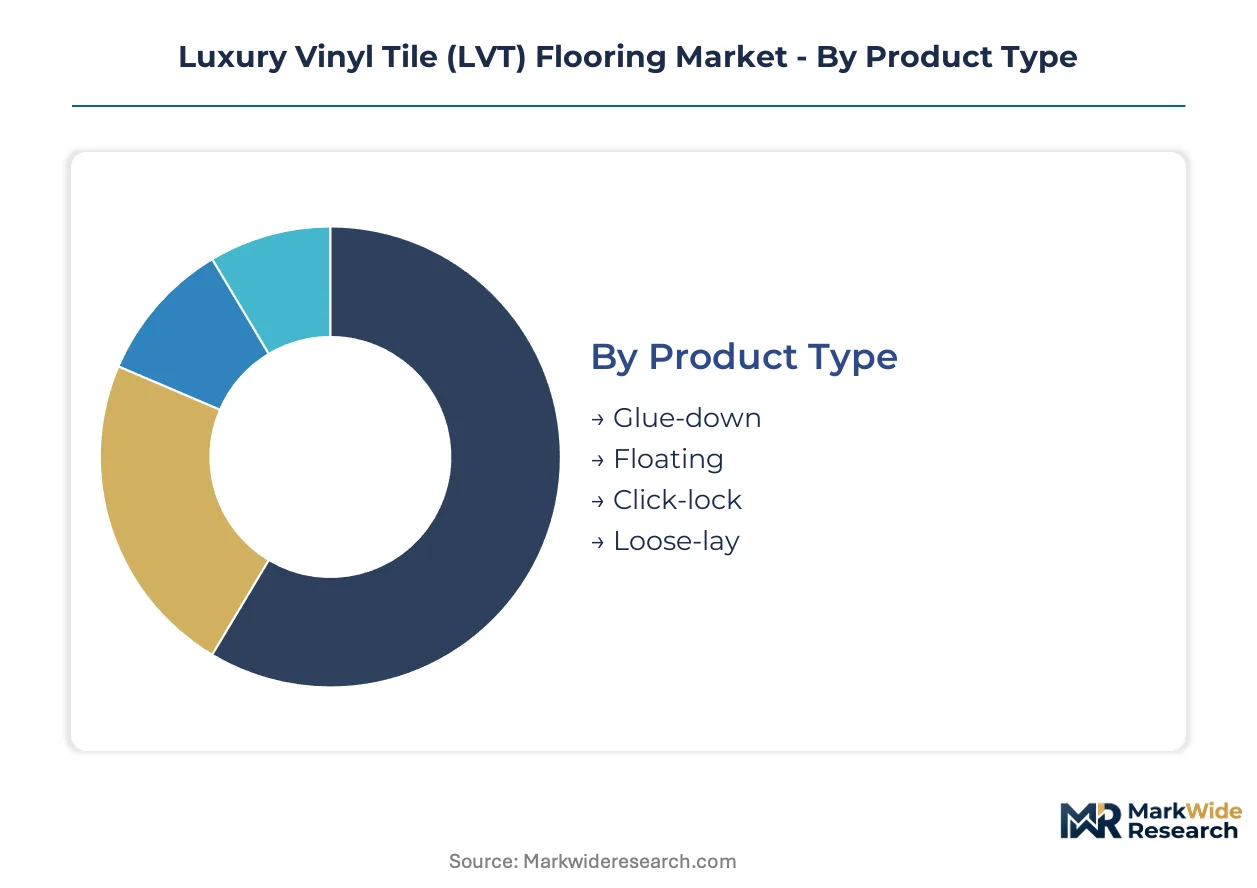
LVT purchasing decisions cascade through multiple technical and aesthetic filters. Installers prioritize locking mechanisms and subfloor tolerance. Architects weigh wear-layer performance against visual authenticity. Facility managers balance lifecycle cost with regulatory compliance documentation.
Product Type:
Installation labor cost and subfloor condition drive product selection more than material price.
- Click-lock:Rigid-core planks with integrated tongue-and-groove edges eliminate adhesive requirements. Demand concentrates in US multi-family residential developments where speed-to-lease compresses construction schedules and floating floors accommodate imperfect concrete slabs.
- Glue-down:Direct-adhesion sheets and tiles deliver maximum dimensional stability in high-traffic commercial corridors. Healthcare and education sectors in Germany and France specify these for heavy rolling loads where seam integrity is non-negotiable.
- Floating:Interlocking systems without adhesive suit renovation projects over existing flooring. Basement and below-grade residential applications in the Netherlands favor these for moisture tolerance.
- Loose-lay:Friction-backed planks rely on perimeter weight and dimensional stability for retention. Temporary retail installations and pop-up hospitality concepts in London and Dubai specify these for rapid deployment and removal.
Click-lock leads on scale; loose-lay leads on momentum.
End User:
Procurement authority and specification complexity vary sharply across buyer categories.
- Commercial:Office, healthcare, and education facilities prioritize FloorScore certification and 20-mil wear-layers for 15-year lifecycle guarantees. Public-sector procurement frameworks in California and New York mandate chemical disclosure documentation.
- Residential:Single-family and multi-family developers drive volume through specification sales relationships. Wood-look rigid-core dominates replacement cycles in US Sun Belt metropolitan corridors.
- Hospitality:Hotel and resort renovation cycles demand waterproof, stain-resistant surfaces with premium stone aesthetics. Dubai, Singapore, and Shanghai luxury properties specify large-format tiles for lobby and ballroom applications.
- Industrial:Manufacturing and warehouse facilities require static-dissipative properties and extreme wear resistance. Food processing plants in the US specify welded seam sheet installations for hygiene compliance.
Commercial leads on scale; hospitality leads on momentum.
Design Style:
Visual authenticity commands price premiums that often exceed material cost differentials.
- Wood-look:Oak, walnut, and hickory grain patterns printed on decorative film layers capture the largest specification volume. Residential replacement cycles across the US, UK, and Australia favor 7-inch plank widths for perceived authenticity.
- Stone-look:Marble, travertine, and slate replications target premium hospitality and retail flagships. Large-format 18x36 inch tiles in matte finishes command elevated margins in Dubai and London commercial developments.
- Abstract:Geometric patterns and solid colors serve contemporary commercial interiors and branded retail environments. Corporate headquarters in Frankfurt and Amsterdam specify these for wayfinding and zone differentiation.
- Vintage:Distressed, hand-scraped, and reclaimed wood aesthetics target residential renovation markets seeking character marks. Farmhouse and industrial interior trends in the US Midwest and UK regions sustain demand.
Wood-look leads on scale; stone-look leads on momentum.
Thickness:
Core dimension directly determines subfloor tolerance, acoustic performance, and installation method compatibility.
- 5mm:Rigid-core SPC construction balances impact resistance with click-lock profile integrity. This specification dominates US residential replacement and new multi-family construction for its compatibility with minor subfloor irregularities.
- 4mm:Glue-down and loose-lay products in this range optimize material efficiency for commercial volume projects. Retail rollouts across European markets specify these for cost-controlled refresh programs.
- 6mm:Enhanced acoustic underlayment integration targets multi-story residential and hospitality applications. German and Austrian building codes for impact sound transmission drive specification in these markets.
- 2mm:Thin glue-down sheets serve budget renovation and light commercial applications where existing floor removal is prohibitive. UK social housing programs specify these for rapid unit turnovers.
5mm leads on scale; 6mm leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized installation technicians and specification sales professionals concentrate in metropolitan construction corridors across four major economies. These workforce clusters anchor demand generation and technical support infrastructure for waterproof flooring systems.
United States
Multi-family developers in Dallas, Atlanta, and Phoenix drive click-lock rigid-core specifications for build-to-rent projects. EPA TSCA Title VI compliance documentation functions as a bidding pre-qualifier in California and New York public-sector procurement. The Sun Belt corridor from Florida to Arizona absorbs the largest residential replacement volumes.
Germany
Healthcare and education facilities in Berlin, Munich, and Hamburg specify glue-down installations for heavy rolling load corridors. ECHA REACH SVHC restrictions accelerate phthalate plasticizer phase-out in adhesive formulations. The Rhine-Ruhr industrial region concentrates technical specification authority for commercial retrofit programs.
China
Hotel and resort renovation cycles in Shanghai, Beijing, and Shenzhen expand demand for waterproof stone-look surfaces. MIIT industrial standards and GB building codes govern core-layer composition and VOC emissions. The Yangtze River Delta manufacturing belt supplies decorative film and wear-layer components.
India
Metropolitan commercial construction in Mumbai, Delhi-NCR, and Bangalore absorbs specification volumes for high-traffic hospitality surfaces. BIS certification requirements and state-level environmental clearances shape product eligibility. Western India's Gujarat corridor hosts emerging rigid-core compounding capacity.
United Kingdom
Social housing programs and retail refresh cycles in London, Manchester, and Birmingham specify thin glue-down sheets for rapid unit turnovers. FloorScore and BREEAM alignment opens public-sector procurement access. The Midlands distribution hub concentrates inventory for European re-export.
Luxury Vinyl Tile (LVT) Flooring Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation, printing, and distribution functions. The vendor base stratifies into three tiers: integrated resin compounders with captive core production, regional fabricators sourcing decorative films externally, and specification-focused brands outsourcing manufacturing entirely. Dominant competitive moves include backward integration into resin compounding to stabilize input costs, and deployment of dedicated technical sales teams to displace distributor-led selling in volume residential projects.
Among North American integrated manufacturers, Shaw Industries Group and Mohawk Industries exemplify the capital-intensive archetype with in-house resin operations. Tarkett anchors European project pipelines through third-party certification alignment. These three entities represent distinct strategic postures: domestic manufacturing scale, chemical integration depth, and sustainability credentialing respectively.
| Leading Market Players |
|---|
| Shaw Industries Group |
| Gerflor |
| Mohawk Industries |
| Interface |
| Forbo Holding |
| Tarkett |
| Mannington Mills |
| LG Hausys |
| Armstrong Flooring |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up flooring specialists have consolidated regional distribution networks across the US Sun Belt and China's Yangtze River Delta, compressing procurement leverage for independent fabricators while tightening price discipline on standardized rigid-core formulations. This ownership concentration funnels margin pressure downstream to resin-dependent producers lacking captive compounding capabilities.
Pricing Analysis
The bundled-vs-unbundled service split separates project-based specification sales from transactional distributor pricing. Three-tier pricing structure across premium, standard, and economy levels tracks wear-layer thickness and certification grade, with FloorScore-certified products commanding measurable premiums in California public-sector procurement. Cost compression in economy-tier glue-down sheets is intensifying because petrochemical feedstock volatility transmits directly to PVC core material costs. Multi-family developers exhibit highest price sensitivity, while hospitality specifiers in Dubai and Singapore prioritize stone-look aesthetics over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from US and German healthcare facility managers mandate multi-supplier qualification for adhesive and wear-layer components, preventing single-source dependency even at higher procurement overhead. Geographic supply concentration centers on China for decorative film and SPC core production, South Korea for specialized wear-layer resins, and the United States for rigid-core compounding equipment. Raw material dependencies draw from PVC resin, calcium carbonate fillers, and digital printing inks. Tariff exposure on Chinese decorative film imports constitutes the primary structural risk. Distribution runs through manufacturer-direct specification teams for commercial volume, bypassing traditional distributor markup in multi-family residential projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through captive resin compounding adoption and premium-tier stone-look specification growth in Middle East hospitality developments.
For Market Incumbents: Acquire regional distribution networks with specification sales capabilities. Consolidate backward into SPC resin compounding to insulate margin stability from petrochemical volatility. Defend against emerging Asian fabricators by embedding FloorScore and GREENGUARD certification into pre-qualification questionnaires for California and New York public-sector bidding. For New Entrants and Emerging Players: The price-point gap between premium stone-look hospitality specifications and economy-tier residential glue-down products offers entry latitude. Target India's metropolitan commercial construction corridors where BIS certification requirements create qualification barriers for unestablished imports. Pursue digital print-to-order partnerships with regional distributors to compress lead times for custom color matching in North American retail refresh cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators lacking captive resin operations but holding specification relationships with Sun Belt multi-family developers. Long-term viability hinges on regulatory compliance infrastructure as REACH SVHC expansions and state-level chemical disclosure mandates proliferate. Watch for inflection where EPA TSCA Title VI documentation requirements extend beyond California and New York to additional state procurement frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Mohawk Industries stabilizes input costs across rigid-core formulations through captive PVC operations. |
| Cradle to Cradle Certification Alignment | Tarkett anchors European healthcare and education specifications through third-party sustainability credentialing. |
| Specification Sales Team Deployment | Shaw Industries displaces distributor-led selling in US multi-family build-to-rent corridors. |
| Digital Print-to-Order Capability | Regional distributors stock unprinted core inventory for on-demand wood-grain and stone-look pattern application. |
| Antimicrobial Wear-Layer Development | Healthcare sector penetration targets hospital and clinic environments where sheet vinyl currently dominates. |
Research Methodology
Multiple input streams — primary interviews with flooring specification sales directors, resin compounding plant managers, and multi-family developer procurement leads; secondary validation through customs trade data, EPA TSCA filing databases, and ECHA REACH registration records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured installation labor cost structures and subfloor preparation requirements across US metropolitan construction corridors. Secondary sources included SEC 10-K disclosures from integrated manufacturers, FloorScore certification registries, and hospitality renovation pipeline tracking from Dubai, Singapore, and Shanghai development authorities.
Data-stream reconciliation anchored volume projections to segmented modeling across product type, end-use sector, design style, and core thickness dimensions. The analytical framework applied penetration rate analysis for click-lock rigid-core in residential replacement cycles and specification capture rates in commercial retrofit programs. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH compliance cost pass-through and petrochemical feedstock price scenarios. Industry-specific forecast inputs included hospitality renovation cycle timing in China's tier-one cities and multi-family housing starts concentration across US Sun Belt metropolitan statistical areas.
Caveats apply where resin cost volatility, REACH SVHC list expansions, or state-level chemical disclosure mandate proliferation could materially shift the outlook. Deviation in US multi-family housing starts or EU Green Deal building renovation funding allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Europe Floor Covering Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Carpet Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market