
 Resilient Flooring Market | 2026-2036
Resilient Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Resilient Flooring Market Analysis
Floor covering distribution through specification-driven architectural channels is reconfiguring as design-build contracts consolidate procurement decisions. Mohawk Industries leverages captive resin compounding to control raw material cost volatility across its LVT portfolio. Tarkett S.A. anchors European healthcare and education specification channels through phthalate-free formulation leadership. Shaw Industries Group competes on domestic manufacturing scale, sustaining shorter lead times for large commercial rollouts in North America.
Resilient flooring comprises polymer- or elastomer-based surfacing materials engineered for dimensional stability under foot traffic, moisture exposure, and rolling loads, typically manufactured through calendering, extrusion, or hot-press lamination of PVC, linseed oil composites, or synthetic rubber compounds. Vinyl products dominate volume throughput due to cost-performance ratios in high-traffic commercial environments, while rubber segments command premium positioning in healthcare and athletic applications where slip resistance and acoustic dampening are specified. Installation method selection increasingly stratifies between glue-down systems for permanent commercial anchoring and floating click-lock formats targeting residential renovation speed and subfloor tolerance.
The EPA oversees VOC emissions through FloorScore and GREENGUARD certification pathways, while the EU REACH framework restricts legacy plasticizer chemistries in imported vinyl products. California's Department of Public Health maintains Section 01350 testing protocols that de facto govern specification eligibility across US public building projects. Stakeholders must monitor evolving biogenic content thresholds and per- and polyfluoroalkyl substance screening rules that are rewriting qualification criteria for institutional flooring contracts.
Market Dynamics
Formulation chemistry migration away from legacy plasticizers is compressing product development cycles and forcing specification-grade manufacturers to requalify entire product lines under stricter biogenic content thresholds.
Growth Catalysts
- Healthcare facility renovation:United States hospital systems are accelerating vinyl sheet purchases through consolidated design-build contracts that bundle flooring with broader infrastructure upgrades.
- REACH plasticizer restrictions:ECHA's accelerating timeline for phthalate substitution is redirecting R&D investment toward bio-based alternatives across European formulation labs.
- Tier-one city retrofit cycles:Shanghai and Beijing commercial real estate operators are shortening replacement intervals for high-traffic surfaces in mixed-use developments.
Market Restraints
- Resin cost volatility:PVC feedstock price swings tied to chlor-alkali capacity constraints in Gulf Coast petrochemical corridors squeeze margin predictability for calendering operations.
- Concentrated plasticizer supply:European specialty chemical producers control disproportionate shares of compliant bio-based plasticizer output, creating qualification bottlenecks for second-tier flooring manufacturers.
- Linoleum substitution ceiling:Natural fiber composite flooring faces inherent dimensional stability limitations under sustained rolling loads in acute care environments.
Strategic Opportunities
- India commercial construction:BIS certification harmonization with ISO 10874 performance standards is opening specification channels for imported LVT in Mumbai and Bangalore office developments.
- Acoustic underlay integration:Converging click-lock floating floor systems with pre-attached sound-dampening layers targets multi-family residential retrofit demand in Germany.
- GREENGUARD Gold tailwind:EPA-aligned VOC thresholds are becoming mandatory in US public school procurement, favoring manufacturers with pre-certified product libraries.
Industry Challenges
- Formulation chemist scarcity:Cross-functional expertise spanning polymer science and regulatory toxicology is concentrating among a shrinking pool of specialists in Basel and Rotterdam corridor labs.
- FloorScore recertification timelines:California Department of Public Health Section 01350 protocol updates are forcing 18-month requalification cycles that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resilient Flooring Market |
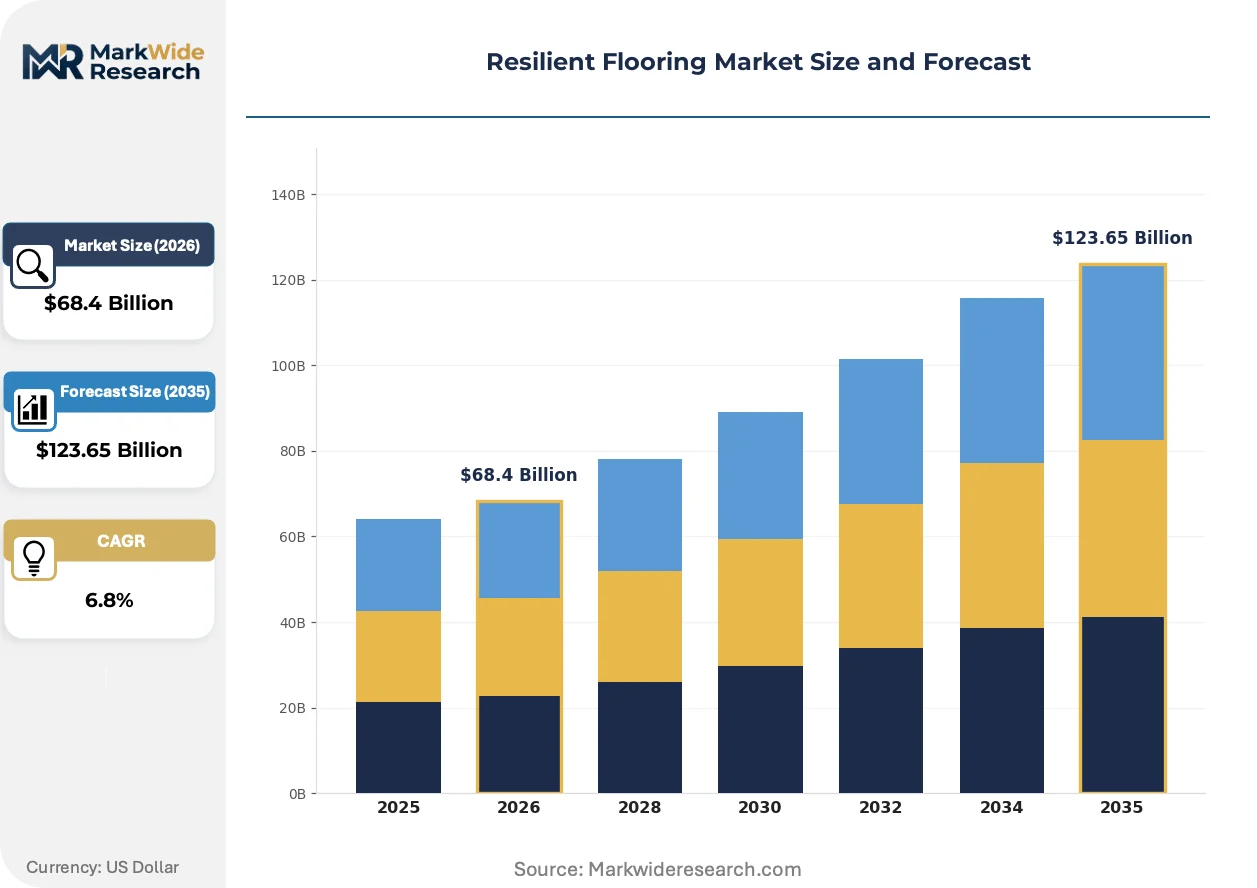
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Linoleum, Rubber, Cork Installation Method: Glue-down, Floating, Loose lay, Interlocking End User: Residential, Commercial, Industrial, Educational Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | Mohawk Industries, Tarkett S.A., Shaw Industries Group, Armstrong Flooring, Mannington Mills, Forbo Flooring Systems, Gerflor, Interface, Beaulieu International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resilient Flooring Market Emerging Trajectories
Digital printing and in-line embossing technologies are collapsing the cost gap between commodity vinyl and premium aesthetic tiers, while regulatory chemistry mandates are rewriting formulation priorities across manufacturing footprints.
Digital ceramic-replica surface technologies are achieving photorealistic stone and wood grain fidelity through multi-layer UV-cured ink deposition. Healthcare and hospitality specifiers are adopting these surfaces at accelerating pace for renovation projects where natural material procurement faces extended lead times. The technology is rendering obsolete traditional rotary-screen printing lines that required dedicated cylinders per pattern and constrained minimum order quantities.
ECHA's REACH Annex XVII restrictions on ortho-phthalate plasticizers are tightening enforcement timelines for imported vinyl products. Flooring manufacturers serving European healthcare and education channels are reformulating entire product families around citrate and epoxidized vegetable oil alternatives. German specification architects are now disqualifying products lacking phthalate-free certification from public tender eligibility.
Consolidated procurement through design-build engineering firms is compressing traditional distributor networks. Large commercial rollout contracts in United States urban cores are bypassing regional flooring wholesalers in favor of direct manufacturer relationships with national contractors. This channel restructuring is most visible in Atlanta and Dallas-Fort Worth healthcare campus developments where single-source accountability clauses dominate contract language.
Resilient Flooring Market Segmentation
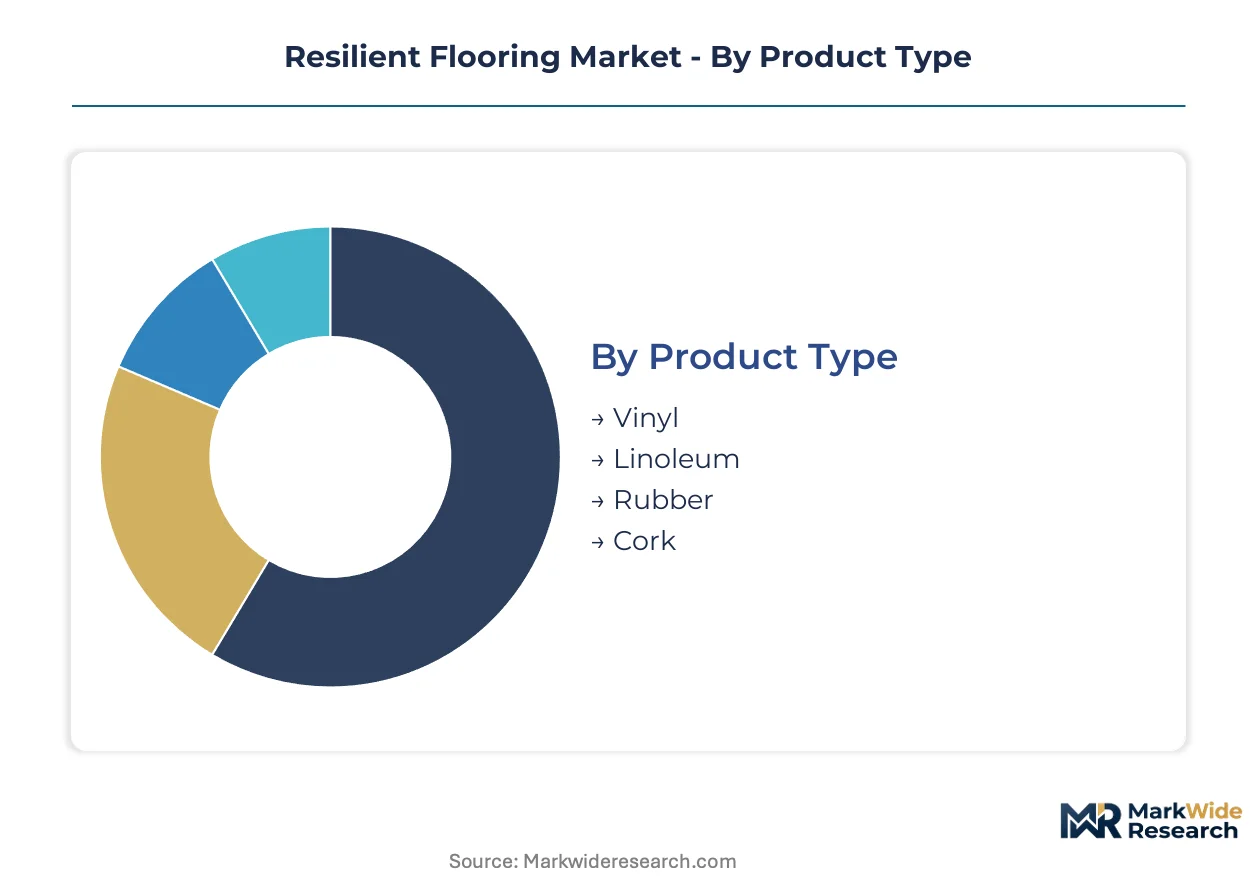
Resilient flooring procurement stratifies sharply across product chemistry and installation logistics, with specification-grade segments commanding extended qualification cycles while residential renovation formats turn inventory faster. Understanding these velocity differentials helps manufacturers allocate R&D and distribution resources against contract timelines.
Product Type:
Vinyl sheet and tile formats turn inventory fastest in commercial retrofit channels, while rubber and cork segments linger longer in specification pipelines due to performance testing requirements.
- Vinyl:Polymer-based surfacing manufactured through calendering or extrusion of PVC compounds, available in sheet, tile, and luxury vinyl plank formats. Hospital systems in the United States are accelerating specification-grade vinyl sheet purchases through consolidated design-build contracts that compress traditional distributor involvement. Vinyl dominates installed base. Rubber is where expansion concentrates.
- Linoleum:Natural fiber composite flooring composed of linseed oil, wood flour, and jute backing, valued for biogenic content in sustainability-focused specifications. German specification architects now disqualify products lacking phthalate-free certification from public tender eligibility, compressing linoleum's addressable market against reformulated vinyl alternatives.
- Rubber:Slip-resistant elastomer surfacing engineered for acoustic dampening and rolling load tolerance in healthcare and athletic environments. Demand concentrates in acute care corridors where sustained gurney traffic exceeds linoleum's dimensional stability limits.
- Cork:Harvested bark composite flooring prized for thermal insulation and renewable sourcing credentials. Portuguese and Spanish supply chains serve premium residential segments in Northern European markets.
Vinyl commands the largest installed footprint across commercial and residential applications. Rubber is climbing the fastest in healthcare specification channels.
Installation Method:
Cost tier stratification separates permanent anchoring systems from speed-oriented floating formats, with labor intensity and subfloor tolerance requirements driving specification decisions.
- Glue-down:Permanent adhesive anchoring required for high-traffic commercial environments and rolling load applications. Glue-down systems dominate healthcare and education specifications where dimensional stability under sustained traffic is mandatory.
- Floating:Click-lock plank systems that install over existing subfloors without adhesive, targeting residential renovation speed. German multi-family residential retrofits are converging floating floor systems with pre-attached acoustic underlay to meet stringent sound transmission codes.
- Loose lay:Friction-fit installation relying on dimensional stability and perimeter anchoring, suited for temporary commercial deployments and rapid turnaround spaces.
- Interlocking:Mechanical connection systems bridging glue-down permanence with floating speed, common in modular commercial carpet tile replacements and athletic flooring.
Glue-down retains the specification-grade premium tier. Floating formats are gaining share fastest in residential renovation channels.
End User:
Volume concentration varies dramatically by contract scale, with institutional segments demanding extended qualification cycles and residential channels rewarding inventory velocity.
- Residential:Single-family and multi-family dwelling applications where aesthetic flexibility and installation speed drive selection. China's tier-one cities are shortening replacement intervals for high-traffic surfaces in mixed-use residential-commercial developments.
- Commercial:Office, retail, and hospitality environments where durability and maintenance efficiency outweigh first cost. Commercial contracts concentrate procurement decisions through design-build engineering firms that bypass traditional regional distributors.
- Industrial:Manufacturing and warehousing facilities requiring chemical resistance and static control properties. Industrial specifications lag commercial and residential segments in digital printing adoption due to functional prioritization over aesthetics.
- Educational:K-12 and higher education facilities where GREENGUARD Gold VOC thresholds are becoming mandatory in United States public school procurement. Educational end-use is expanding most quickly among institutional segments as bond-funded renovation cycles accelerate.
Commercial commands the largest contract value pool. Educational is where specification volume is expanding most rapidly.
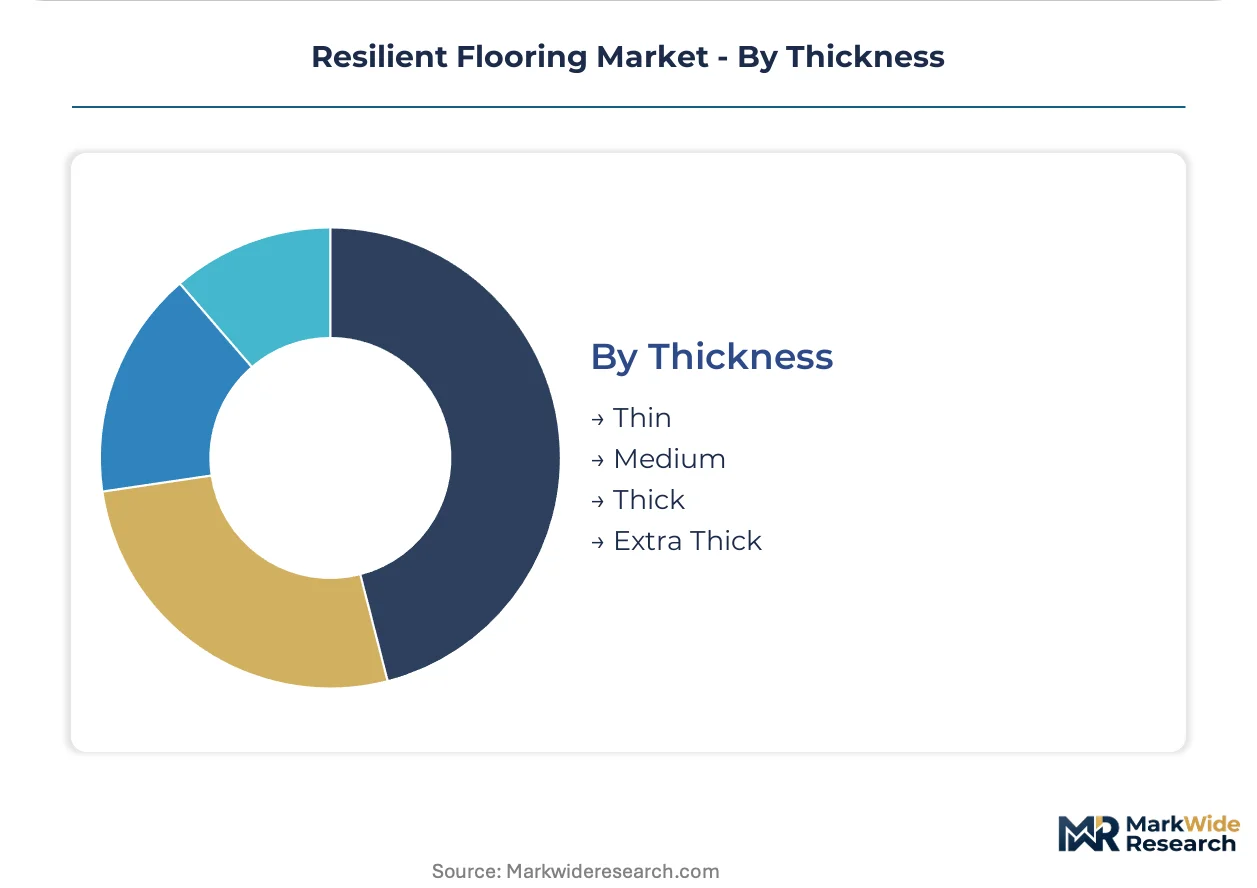
Thickness:
Performance tier and acoustic specification requirements stratify demand across thickness grades, with premium segments attaching specialized underlay systems.
- Thin:Economy-grade surfacing for light residential and temporary commercial applications where subfloor quality permits minimal build height.
- Medium:Standard commercial specification balancing durability with transition compatibility to adjacent flooring materials.
- Thick:Premium residential and commercial segments where embossing depth and wear layer protection justify material cost. Thick profiles dominate luxury vinyl plank specifications in United States urban core mixed-use developments.
- Extra Thick:Acoustic-dampening systems for multi-family and healthcare applications requiring impact sound isolation without separate underlay. Extra thick configurations are gaining specification traction fastest in German residential retrofit codes.
Medium thickness dominates standard commercial specifications. Extra thick is where premium acoustic segmentation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical throughput infrastructure underwrites European formulation chemistry leadership, while the Yangtze River Delta manufacturing corridor anchors Asia-Pacific vinyl compounding capacity.
United States
Hospital renovation programs and consolidated design-build contracts are accelerating specification-grade vinyl sheet procurement. The EPA's FloorScore certification pathway governs VOC eligibility for public building projects. Atlanta and Dallas-Fort Worth healthcare campuses concentrate large commercial rollout contracts that bypass traditional regional distributors.
Germany
Multi-family residential retrofit demand and stringent sound transmission codes are converging floating floor systems with pre-attached acoustic underlay. ECHA's REACH Annex XVII restrictions on ortho-phthalate plasticizers are tightening enforcement timelines for imported vinyl products. German specification architects in Berlin and Hamburg now disqualify products lacking phthalate-free certification from public tender eligibility.
China
Shanghai and Beijing commercial real estate operators are shortening replacement intervals for high-traffic surfaces in mixed-use developments. The country's dual carbon goals are pressuring manufacturing facilities toward cleaner production benchmarks. The Yangtze River Delta industrial corridor hosts the majority of domestic calendering and extrusion capacity serving tier-one city demand.
India
Mumbai and Bangalore office developments are opening specification channels for imported LVT as commercial construction accelerates. BIS certification harmonization with ISO 10874 performance standards is reducing technical barriers for foreign manufacturers. Western India manufacturing clusters are emerging as domestic compounding hubs to serve subcontinent distribution networks.
Resilient Flooring Market Vendor Landscape
On the supply side, the industry is consolidating around specification-grade manufacturers with captive resin compounding capabilities and established healthcare certification libraries. The competitive terrain stratifies between multinational flooring conglomerates with integrated polymer operations and regional specialists focused on niche acoustic or bio-based segments. Three archetypes dominate: vertically integrated resin-to-retail operators, formulation-focused specification leaders, and agile renovation-channel specialists. Capacity expansion in Gulf Coast petrochemical corridors and strategic partnerships with European specialty chemical producers represent the dominant competitive moves.
Within the integrated multinational tier, Mohawk Industries exemplifies captive supply chain control through in-house resin compounding operations that buffer raw material cost volatility. Tarkett S.A. occupies a position as the European formulation leader, anchoring phthalate-free specification channels across healthcare and education markets. Shaw Industries Group represents the domestic manufacturing scale archetype, leveraging shorter lead times for large North American commercial rollouts.
| Leading Market Players |
|---|
| Mohawk Industries |
| Tarkett S.A. |
| Shaw Industries Group |
| Armstrong Flooring |
| Mannington Mills |
| Forbo Flooring Systems |
| Gerflor |
| Interface |
| Beaulieu International Group |
| Others |
Supply Flow & Price Mechanics
Gulf Coast chlor-alkali capacity underutilization is compressing PVC resin contract pricing, forcing calendering operations to absorb volatility through inventory carry strategies while specification-grade manufacturers leverage long-term offtake agreements to lock input costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specification-grade healthcare vinyl with FloorScore certification from commercial LVT and residential click-lock alternatives. Price differentiation hinges on certification grade and volume scale, with hospital systems commanding steepest discounts through consolidated design-build procurement. Cost compression in economy-tier residential LVT is intensifying because digital printing technology collapses minimum order thresholds. Residential renovation channels exhibit highest price sensitivity, while acute care specifications tolerate premium positioning for rolling-load performance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for vinyl flooring importers serving North American specification channels. Manufacturing concentrates in China, Germany, and the United States, with the Yangtze River Delta anchoring calendering capacity and the Port of Rotterdam underwriting European formulation chemistry. Raw material dependencies rest on PVC resin, bio-based plasticizers, and digital printing inks. Single-source vulnerability concentrates in European specialty chemical producers controlling compliant plasticizer output. Distribution runs through consolidated design-build engineering firms that bypass traditional regional wholesalers for large commercial rollouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-grade fragmentation is creating niche opportunities as healthcare procurement consolidates around phthalate-free certification libraries, enabling mid-tier manufacturers to capture share through targeted compliance investment rather than scale competition.
For Market Incumbents: Insulate specification-grade margins by securing captive bio-based plasticizer supply agreements with Rotterdam corridor specialty chemical producers, and accelerate FloorScore recertification cycles to outpace California Section 01350 protocol updates. Threat of REACH-aligned plasticizer restrictions spreading to North American jurisdictions demands preemptive formulation migration. Certification investment is the priority lever for defending hospital system contract eligibility. For New Entrants and Emerging Players: Pursue acoustic underlay integration for German multi-family residential retrofit codes, where pre-attached sound-dampening layers command specification premium. India's BIS-ISO harmonization presents the most penetrable geography for imported LVT qualification. Direct manufacturer relationships with Mumbai and Bangalore design-build contractors offer the cleanest go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across phthalate-free formulation lines as R&D cycles compress and requalification timelines extend. Long-term viability favors vertically integrated resin-to-retail operators with established healthcare certification libraries over pure-play distributors. Acquisition target archetype: European formulation specialists with REACH-compliant product families and established architect specification relationships. Signal to watch: ECHA enforcement timeline acceleration for ortho-phthalate substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Mohawk Industries leverages captive PVC production to buffer Gulf Coast feedstock volatility across LVT portfolios. |
| Phthalate-Free Formulation Migration | Tarkett S.A. anchors European healthcare specification channels through REACH-compliant chemistry leadership. |
| Acoustic Underlay Integration | German multi-family retrofit codes are converging click-lock systems with pre-attached sound-dampening layers. |
| Design-Build Channel Direct Access | Atlanta and Dallas-Fort Worth healthcare campuses bypass regional distributors for single-source accountability. |
| GREENGUARD Gold Pre-Certification | EPA-aligned VOC thresholds are becoming mandatory in United States public school procurement cycles. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across specification architects, hospital procurement directors, flooring contractors, resin compounding plant managers, and regulatory affairs specialists at formulation labs. Primary interview insights were validated against customs and trade data, SEC 10-K filings, EPA FloorScore certification databases, ECHA REACH registration dossiers, and California Department of Public Health Section 01350 test reports. Bottom-up channel volume estimates were triangulated with top-down construction spending allocation models.
Calibration against historical volume elasticities and input cost pass-through coefficients anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry, installation method, end-use sector, thickness grade, and regional regulatory cluster. CAGRs were derived from slope-consistent growth trajectory fitting rather than endpoint anchoring. Industry-specific forecast inputs incorporated chlor-alkali capacity utilization rates and commercial real estate retrofit cycle frequencies.
Macroeconomic conditions sit as an overlay; deviation in construction spending, interest rate environments, or petrochemical feedstock pricing would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement timelines and certification adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market