
 Area Rugs Market | 2026-2036
Area Rugs Market Size, Share, and Industry Trends Forecast 2026-2036
Area Rugs Market Analysis
Recycled PET fiber is rebalancing cost structures across mid-tier collections as virgin wool prices fluctuate. Mohawk Industries leverages captive polymer recycling to stabilize input costs. Shaw Industries Group anchors its domestic manufacturing through advanced dye-house water recovery. Safavieh competes on design velocity, compressing trend-to-shelf cycles for e-commerce channels.
Area rugs are textile floor coverings typically ranging from 2x3 feet to 10x14 feet, constructed through hand-knotting, hand-tufting, machine-woven, or flatweave processes using pile heights from 0.25 to 1.5 inches for acoustic dampening and thermal insulation. Wool and synthetic fiber segments split the value pool, with wool commanding margin premiums in traditional and Oriental styles while synthetic fiber scales volume in modern and shag collections for residential end users. Rectangle shapes dominate commercial and hospitality procurement due to standardized spatial planning, whereas round and runner formats sustain specialty growth in boutique residential segments.
EPA TSCA Title VI governs composite wood product formaldehyde emissions in US-sourced rug substrates, while REACH restricts azo dyes and heavy metals in European imports. India's BIS certification for textile labeling and fiber content disclosure shapes export eligibility from Bhadohi cluster manufacturers. Stakeholders must monitor tightening chemical disclosure rules across multiple jurisdictions to avoid supply chain disruption.
Market Dynamics
Residential renovation cycles in North American suburbs are compressing reorder lead times, forcing manufacturers to hold larger finished-goods positions near distribution nodes. This inventory pressure intersects with California's Proposition 65 enforcement to reshape sourcing toward certified low-VOC suppliers.
Growth Catalysts
- Hand-knotted artisan capacity:India's Bhadohi and Mirzapur weaving belt anchors premium positioning through generational skill retention. Export demand from US and European collectors sustains above-market pricing power for certified workshops.
- EPA TSCA Title VI compliance:Formaldehyde emission limits on composite wood substrates filter procurement toward certified substrate mills. Rug assemblers with pre-qualified supply chains capture hospitality and multi-family housing contracts.
- Recycled PET fiber maturation:Captive polymer recycling stabilizes input cost volatility against virgin wool price swings. Mid-tier collections achieve margin resilience previously concentrated in synthetic-only portfolios.
Market Restraints
- Wool price volatility:New Zealand and Australian auction floor prices fluctuate with drought cycles and flock reductions. Hand-knotted producers face margin compression when hedging instruments are unavailable.
- Bhadohi cluster concentration:Premium hand-knotted capacity concentrates in a 40-kilometer corridor vulnerable to monsoon flooding and labor migration. Single-source dependency creates fulfillment risk for heritage collections.
- REACH azo dye restrictions:European import barriers on heavy metal and restricted dye formulations require reformulation of traditional color palettes. Small-batch dyehouses face compliance cost barriers.
Strategic Opportunities
- Water recovery technology convergence:Advanced dye-house closed-loop systems meet ZDHC wastewater standards while reducing municipal discharge fees. Shaw Industries Group's domestic manufacturing anchors demonstrate scalable deployment.
- E-commerce design velocity:Compressed trend-to-shelf cycles enable rapid-response collections for direct-to-consumer channels. Digital-native buyers reward 8-week turnaround on trend-informed patterns.
- India BIS certification expansion:Mandatory fiber content disclosure creates export eligibility moats for compliant Bhadohi manufacturers. First-movers capture European and North American private-label contracts.
Industry Challenges
- Master weaver succession gaps:Generational transition in Bhadohi's artisan households reduces available loom hours for complex knot densities. Training programs struggle to match historical apprenticeship duration.
- Multi-jurisdiction chemical disclosure:Divergent California Proposition 65, REACH, and emerging state-level requirements fragment compliance documentation. SKU proliferation strains testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Area Rugs Market |
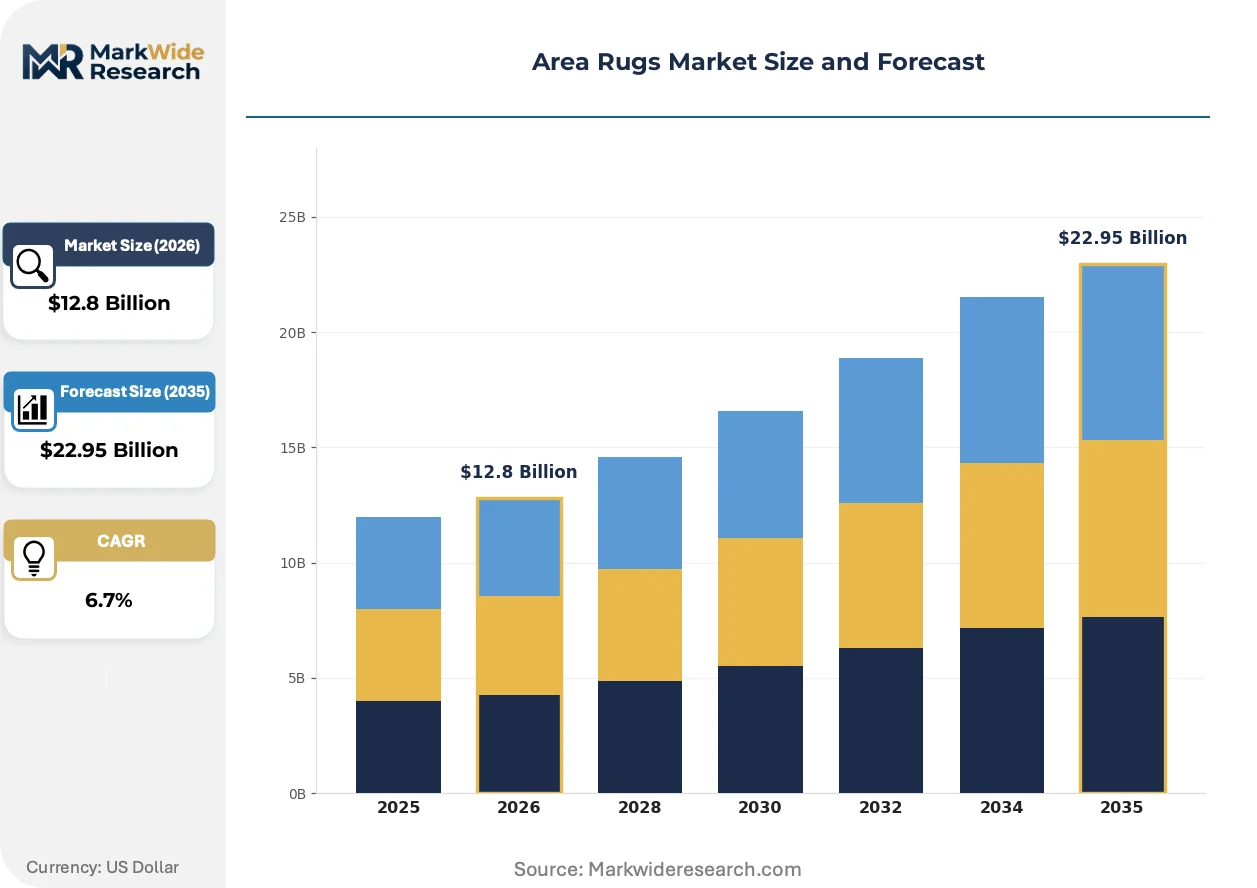
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wool, Synthetic Fiber, Natural Fiber, Nylon Style: Traditional, Modern, Shag, Oriental Shape: Rectangle, Round, Runner, Square End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | Mohawk Industries, Shaw Industries Group, Tarkett Group, Interface Inc., The Dixie Group, Milliken & Company, Oriental Weavers Carpet Co., Tai Ping Carpets International Limited, Safavieh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Area Rugs Market Emerging Trajectories
Material substitution and regulatory disclosure requirements are compressing traditional competitive advantages while opening margin pools for technology-enabled producers. Three developments warrant particular attention.
Recycled PET fiber is overtaking virgin nylon in mid-tier machine-woven collections through superior stain resistance and price stability. Multi-family housing developers specify recycled content for LEED contribution points, accelerating specification velocity. This shift compresses the premium previously attached to solution-dyed nylon while expanding addressable volume.
REACH restrictions on azo dyes and heavy metals are forcing reformulation of traditional Oriental color palettes ahead of 2025 enforcement deadlines. German and French importers now require third-party testing documentation for every container. Heritage-style producers in Mirzapur are investing in vegetable dye research to maintain European market access.
Direct-to-consumer channels are fragmenting wholesale-dominated distribution for standard-size residential rugs. Boutique buyers now expect 48-hour sample delivery and 30-day no-fault returns previously reserved for mass-market players. This service compression is most visible in US coastal metro markets where digital-native brands capture share from traditional furniture store channels.
Area Rugs Market Segmentation
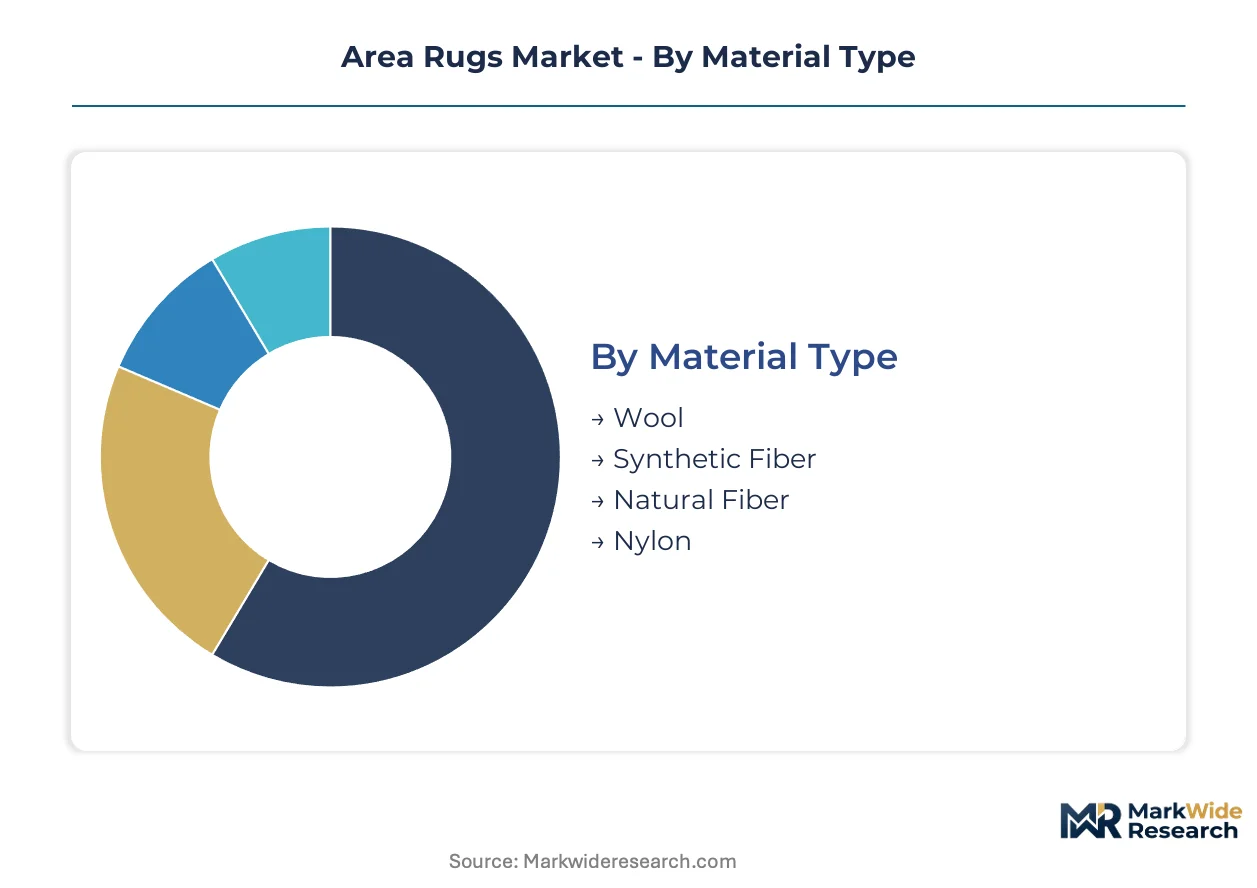
Material composition and construction technique determine margin profiles, supply chain complexity, and regulatory exposure across the area rugs value chain. Segment-specific capital requirements shape competitive entry barriers and consolidation trajectories differently across wool, synthetic, and natural fiber categories.
Material Type:
Wool and synthetic fiber segments demand the heaviest upfront investment in dye-house infrastructure, inventory carrying costs, and certification compliance. Natural fiber and nylon variants offer lower capital thresholds but expose producers to raw material price volatility.
- Wool:Premium protein fiber sourced from New Zealand and Australian auction floors commands margin premiums in hand-knotted and hand-tufted constructions. Demand concentrates in US coastal metros and European collector markets where heritage aesthetics and formaldehyde-free substrates justify price positioning. Drought-driven flock reductions and auction price spikes compress margins when hedging instruments are unavailable.
- Synthetic Fiber:Solution-dyed polyester and polypropylene dominate machine-woven volume through colorfastness and stain resistance specifications. Multi-family housing developers in US Sun Belt suburbs specify recycled PET content for LEED contribution points, accelerating specification velocity. Captive polymer recycling at major mills stabilizes input cost structures against virgin fiber volatility.
- Natural Fiber:Jute, sisal, and seagrass constructions serve coastal and eco-conscious residential segments with minimal chemical processing. California Proposition 65 enforcement filters procurement toward certified low-VOC suppliers for substrate adhesives.
- Nylon:Solution-dyed BCF nylon retains commercial hospitality share through crush resistance and bleach-cleanability specifications. REACH azo dye restrictions in Europe require reformulation of traditional color palettes for export eligibility.
Mature deployment sits with wool. Newer deployment is concentrated in synthetic fiber.
Style:
Style segmentation maps directly to distribution channel economics and design velocity requirements. Traditional and Oriental styles anchor wholesale and specialty retail, while Modern and Shag collections compress trend-to-shelf cycles for e-commerce.
- Traditional:Classic patterns derived from Persian and European design archives sustain above-market pricing in certified workshops. India's Bhadohi and Mirzapur weaving belt anchors production through generational skill retention. Export demand from US and European collectors maintains premium positioning despite master weaver succession gaps.
- Modern:Abstract and geometric patterns serve digital-native buyers through direct-to-consumer channels with 8-week turnaround expectations. Boutique buyers in US coastal metros demand 48-hour sample delivery and 30-day no-fault returns.
- Shag:High-pile constructions in synthetic fiber target residential acoustic dampening and thermal insulation applications. Machine-tufted production enables volume scaling with lower labor intensity than hand-knotted alternatives.
- Oriental:Authentic hand-knotted designs with specified knot densities face REACH azo dye restrictions requiring vegetable dye research investments. German and French importers mandate third-party testing documentation for every container.
Traditional styling retains the steepest price premiums. Modern styling is expanding most quickly through digital channels.
Shape:
Shape determines manufacturing equipment utilization, shipping cube efficiency, and spatial planning integration for end users. Rectangle formats maximize loom throughput and container loading density.
- Rectangle:Standardized dimensions from 5x7 to 10x14 feet dominate commercial and hospitality procurement through spatial planning predictability. Machine-woven production achieves highest equipment utilization rates with minimal cutting waste.
- Round:Specialty formats sustain boutique residential growth in dining and foyer applications. Custom cutting from rectangular blanks increases material waste factors versus dedicated circular loom setups.
- Runner:Corridor and hallway formats command per-square-foot premiums through specialized narrow-width loom configurations. Staircase installation specifications require reinforced backing for safety compliance.
- Square:Niche dimensions serve specific room geometries and modular furniture arrangements. Lower volume throughput limits supplier participation to flexible manufacturing operations.
Rectangle shapes anchor commercial procurement. Round and runner formats are gaining share fastest in residential specialty segments.
End User:
End user segmentation separates specification authority, replacement cycle length, and service requirements. Residential buyers prioritize design velocity and return policies; commercial and institutional buyers emphasize durability certifications and total cost of ownership.
- Residential:Renovation-driven demand in North American suburbs compresses reorder lead times, forcing manufacturers to hold larger finished-goods positions near distribution nodes. Digital-native buyers reward rapid-response collections with compressed trend-to-shelf cycles.
- Commercial:Office and retail specifications require Class I flammability ratings and wear warranties exceeding residential standards. EPA TSCA Title VI compliance on composite wood substrates filters procurement toward certified substrate mills.
- Hospitality:Hotel and resort procurement demands bleach-cleanability, stain resistance, and rapid replacement availability for damage-prone guest rooms. Pre-qualified supply chains capture multi-property contract rollouts.
- Institutional:Healthcare and educational facilities specify antimicrobial treatments and slip-resistant backing for safety compliance. Extended replacement cycles and budget approval processes elongate sales cycles versus commercial segments.
Residential renovation cycles drive volume velocity. Hospitality and institutional segments are climbing the fastest through specification standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential renovation spending concentrates demand in suburban United States markets, while artisan weaving clusters in India and regulatory enforcement in California reshape sourcing geography across the value chain.
United States
Suburban renovation cycles in Texas, Florida, and Arizona drive unit volume velocity for mid-tier synthetic collections. EPA TSCA Title VI compliance filters hospitality and multi-family housing procurement toward certified substrate mills. Georgia and North Carolina distribution nodes hold elevated finished-goods positions to compress reorder lead times.
India
Export demand from US and European collectors sustains above-market pricing for heritage hand-knotted workshops. BIS certification for fiber content disclosure creates export eligibility moats for compliant manufacturers. The Bhadohi-Mirzapur corridor anchors premium artisan capacity through generational skill retention despite monsoon flooding risks.
Germany
REACH azo dye and heavy metal restrictions filter import procurement toward reformulated color palettes. Third-party testing documentation requirements for every container elongate supplier qualification timelines. Frankfurt and Hamburg logistics hubs consolidate distribution for Central European contract furniture channels.
United Kingdom
London and Southeast England residential markets reward rapid-response collections through direct-to-consumer channels. Building Regulations Part B flammability standards shape commercial specification authority. Manchester and Yorkshire distribution centers serve boutique retail networks with compressed sample delivery expectations.
China
Yangtze River Delta manufacturing bases supply machine-woven volume for global mid-tier private-label contracts. Dual carbon goals accelerate water recovery technology adoption in dye-house operations. Zhejiang and Jiangsu provinces concentrate synthetic fiber processing capacity for export markets.
Area Rugs Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit dye-houses with closed-loop water recovery systems and add regional distribution nodes to compress lead times. The vendor base organizes around three archetypes: integrated polymer recyclers stabilizing input costs, artisan workshop networks commanding heritage premiums, and digital-native brands compressing trend-to-shelf cycles. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players extending from wholesale into direct-to-consumer channels and from residential into hospitality specification.
Among North American integrated manufacturers, Mohawk Industries and Shaw Industries Group exemplify the polymer-recycling archetype, while Safavieh occupies a position within the design-velocity tier serving digital-native buyers. These three anchors demonstrate how scale-driven and agility-focused strategies coexist without direct overlap in customer segments or channel economics.
| Leading Market Players |
|---|
| Mohawk Industries |
| Shaw Industries Group |
| Tarkett Group |
| Interface Inc. |
| The Dixie Group |
| Milliken & Company |
| Oriental Weavers Carpet Co. |
| Tai Ping Carpets International Limited |
| Safavieh |
| Others |
Supply Flow & Price Mechanics
Captive polymer recycling at major integrated mills anchors both supply security and margin stability across mid-tier synthetic collections. This backward integration into recycled PET feedstock insulates producers from virgin wool auction volatility while compressing the premium previously attached to solution-dyed nylon.
Pricing Analysis
Volume-versus-margin splits stratify across premium hand-knotted, standard machine-woven, and economy flatweave tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade for formaldehyde-free substrates and generational artisan skill density. Cost compression in synthetic fiber collections is intensifying because recycled PET maturation erodes legacy nylon differentiation. Multi-family housing developers exhibit highest price sensitivity through LEED point arbitrage, while European collectors of Bhadohi heritage pieces show lowest sensitivity to knot-density premiums.
Supply Chain Analysis
California Proposition 65 enforcement and EPA TSCA Title VI compliance reshape sourcing toward certified low-VOC substrate mills in Georgia and North Carolina. Raw material dependencies center on New Zealand and Australian wool auction floors, Indian hand-knotted artisan capacity, and Yangtze River Delta synthetic fiber processing. Single-source vulnerability concentrates in the 40-kilometer Bhadohi-Mirzapur corridor exposed to monsoon flooding. Distribution runs through regional nodes in Texas, Florida, and Arizona suburbs compressing reorder lead times for renovation-driven demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recycled PET fiber technology is displacing virgin nylon and wool blends in mid-tier collections, forcing legacy producers to retool dye-houses and reformulate fiber mixes to maintain specification relevance.
For Market Incumbents: Deploy closed-loop water recovery systems to meet ZDHC wastewater standards while reducing municipal discharge fees. Add regional distribution nodes near Sun Belt renovation corridors to compress lead times against digital-native challengers. This counters Safavieh's design-velocity advantage in direct-to-consumer channels.
For New Entrants and Emerging Players: Enter via rapid-response digital collections targeting coastal metro residential buyers with 8-week trend-to-shelf cycles. White-space sits in certified low-VOC private-label contracts for hospitality multi-property rollouts. Go-to-market leverage: 48-hour sample delivery and 30-day no-fault returns.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated polymer recyclers with captive PET supply and artisan workshop networks commanding heritage premiums. Long-term viability favors technology-enabled producers over pure wholesale distributors. Signal to watch: BIS certification expansion among Bhadohi manufacturers creating export eligibility moats.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polymer Recycling Expansion | Mohawk Industries stabilizes input costs against virgin wool auction volatility. |
| Closed-Loop Dye-House Retrofit | Shaw Industries Group meets ZDHC standards while cutting discharge fees. |
| Direct-to-Consumer Channel Launch | Safavieh compresses trend-to-shelf cycles for digital-native coastal buyers. |
| BIS Certification Investment | Compliant Bhadohi manufacturers capture European private-label contracts. |
| Regional Distribution Node Addition | Georgia and North Carolina hubs hold finished-goods positions for Sun Belt demand. |
Methodological Framework
Multi-period observation of residential renovation cycles, wool auction price trajectories, and EPA enforcement patterns anchored the trend analysis, supplemented by interviews with dye-house operations managers, hospitality procurement directors, Bhadohi master weavers, and multi-family housing developers. Secondary validation drew from EPA TSCA filings, California Proposition 65 enforcement records, India BIS certification databases, and REACH restriction updates. Bottom-up triangulation across material type, construction technique, and end-user segment converged with top-down value pool analysis.
Segment-weighting across wool, synthetic fiber, natural fiber, and nylon material types combined with construction technique and end-user splits informed the analytical framework. Modeled dimensions included residential versus commercial specification authority, hand-knotted versus machine-woven labor intensity, and regional regulatory cluster exposure. CAGRs derived from unit volume trajectory analysis intersecting with average selling price evolution across the projection horizon. Industry-specific inputs incorporated drought-driven flock reduction patterns and LEED specification velocity in Sun Belt suburbs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under monsoon disruption in the Bhadohi corridor or accelerated REACH azo dye enforcement. Assumptions reflect current regulatory trajectories and artisan succession rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
Europe Floor Covering Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
Egypt Floor Covering Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market