
 Fully Autonomous Driving Market | 2026-2036
Fully Autonomous Driving Market Size, Share, and Industry Trends Forecast 2026-2036
Fully Autonomous Driving Market Insights
Project finance tied to per-mile revenue guarantees is narrowing the field of credible competitors. Waymo leverages its vertically integrated sensor stack to sustain unit economics across large-scale deployments. Tesla anchors its position through camera-first architectures that slash hardware costs. Aurora Innovation competes on long-haul freight partnerships that extend its addressable market beyond passenger mobility.
Fully autonomous driving denotes vehicular operation without human intervention across all traffic conditions, relying on fused inputs from lidar, radar, camera systems, and ultrasonic sensors processed through neural networks to generate real-time navigation decisions. Camera systems dominate unit shipments due to lower per-sensor costs, while lidar commands premium positioning in urban robotaxi fleets where centimeter-level ranging accuracy proves essential. Among vehicle types, heavy-duty trucks attract concentrated R&D investment as highway-fixed-route scenarios reduce edge-case complexity and accelerate regulatory approval timelines.
The National Highway Traffic Safety Administration shapes crashworthiness standards and defect investigation protocols that determine market access timelines for US deployments, while the Federal Communications Commission governs spectrum allocation for vehicle-to-everything communication links. The California Department of Motor Vehicles operates the nation's most permissive autonomous vehicle testing framework, creating a regulatory gravity well that concentrates development activity in that state. Stakeholders must monitor how fragmented state-level liability frameworks evolve against emerging federal preemption proposals that could standardize or disrupt current patchwork governance.
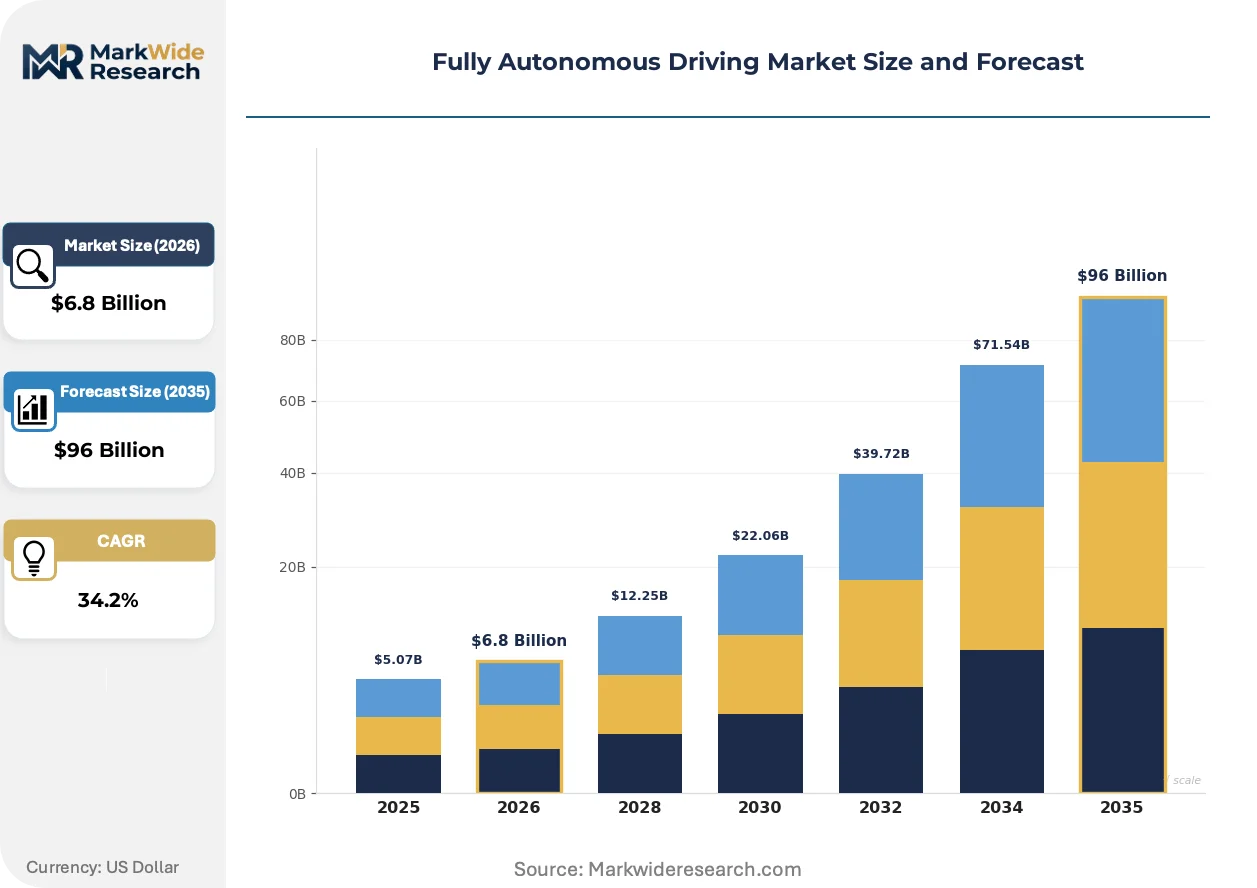
Market Dynamics
Per-mile revenue guarantees from fleet operators are compressing development timelines and forcing capital discipline across the autonomous driving sector, privileging players with captive sensor production and proven safety records over venture-stage entrants.
Growth Catalysts
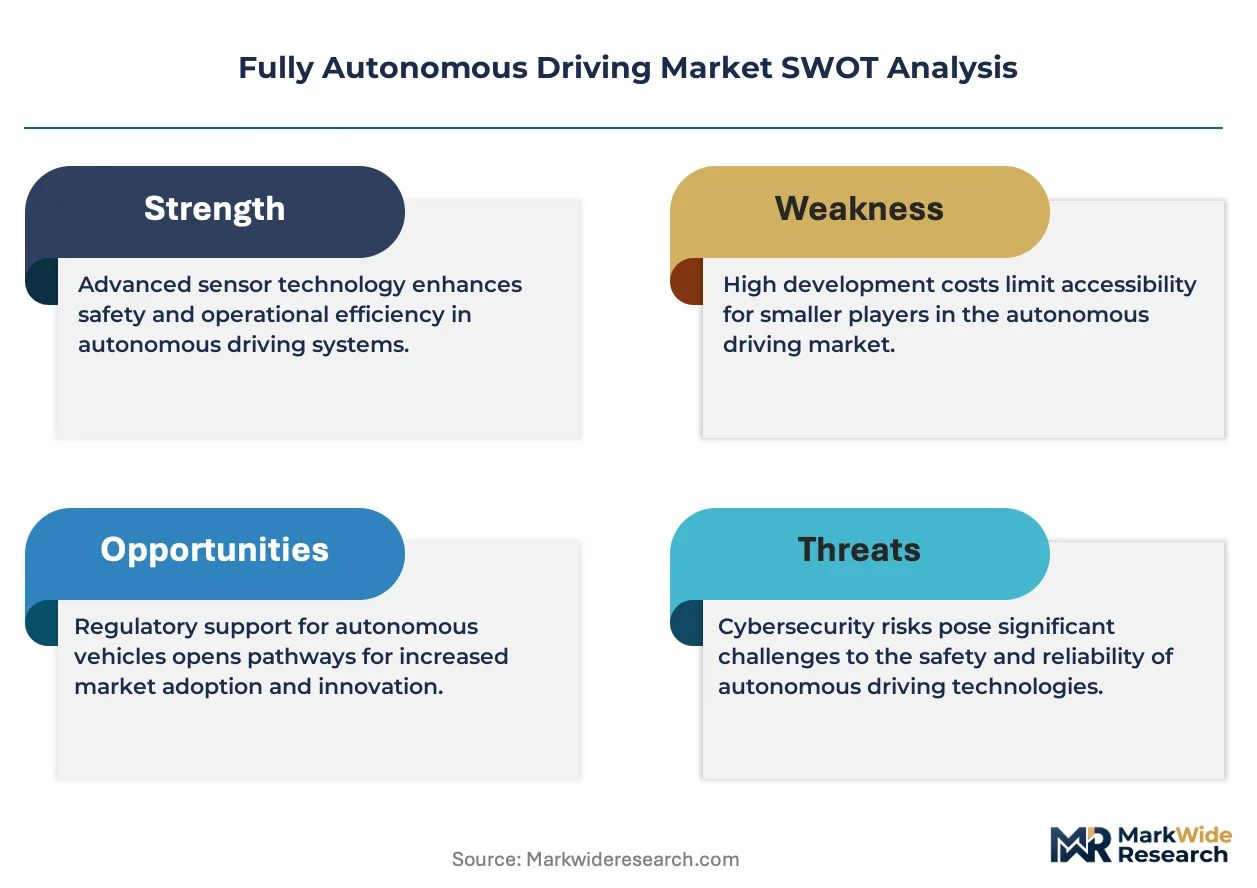
- EU AI Act compliance pathways:The regulation's risk-tiering framework provides legal certainty for Level 4 system deployments, accelerating homologation investments from European automotive suppliers.
- Phoenix-San Francisco corridor expansion:Permissive state frameworks in Arizona and California enable scaled robotaxi operations that generate real-world training data unavailable in restrictive jurisdictions.
- Lidar cost curves:Solid-state manufacturing advances are reducing per-unit sensor expenses, making centimeter-level ranging economically viable for mid-tier commercial fleets.
Market Restraints
- Neural training compute costs:Foundation model development for edge-case scenario recognition requires sustained capital commitments that strain balance sheets outside the largest technology conglomerates.
- UNECE WP.29 type-approval bottlenecks:Divergent national implementation timelines for the ALKS regulation create fragmented market access across European member states.
- High-definition mapping dependency:Proprietary geospatial data moats limit operational expansion to pre-mapped corridors, constraining addressable route networks.
Strategic Opportunities
- Highway-fixed-route freight corridors:Long-haul trucking applications face reduced edge-case complexity compared to urban environments, compressing regulatory approval timelines for heavy-duty deployments.
- Vehicle-to-everything spectrum allocation:FCC rulemaking on 5.9 GHz band usage creates first-mover advantages for operators integrating C-V2X communication stacks.
- Retrofit autonomy kits:Aftermarket sensor and compute packages for existing commercial fleets open addressable markets beyond OEM-integrated new vehicle sales.
Industry Challenges
- Safety driver transition protocols:Fleet operators face operational complexity in managing remote monitoring centers and teleoperation handoff procedures during edge-case interventions.
- Cross-jurisdictional liability frameworks:Fragmented state-level insurance and tort rules in the United States create compliance overhead for interstate commercial deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fully Autonomous Driving Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $96 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Lidar, Radar, Camera Systems, Ultrasonic Sensors Vehicle Type: Passenger Cars, Heavy-Duty Trucks, Buses, Delivery Drones End User: Consumers, Fleet Operators, Ride-Hailing Services, Logistics Companies Use Case: Personal Transportation, Goods Delivery, Public Transit, Emergency Services |
| Companies Covered | Waymo, Cruise, Tesla, Zoox, Motional, Torc, Gatik, Wayve, Aurora Innovation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fully Autonomous Driving Market Trends and Innovations
Foundation model architectures trained on synthetic and real-world driving data are compressing development cycles for perception systems, while regulatory clarity in select jurisdictions enables capital deployment toward scaled commercial service rather than perpetual pilot programs.
Occupancy network architectures are digitizing the representation of three-dimensional space around vehicles, replacing discrete object detection with continuous volumetric reasoning. Robotaxi operators in permissive U.S. markets are deploying these systems at scale, reducing reliance on pre-mapped HD vector layers. The shift is digitizing the economics of urban autonomous operations by lowering per-mile mapping maintenance costs.
The EU AI Act's conformity assessment requirements for high-risk AI systems are mandating documented training data provenance and model validation protocols for Level 4 deployments. European automotive suppliers are restructuring development workflows to meet these documentation burdens. Passenger mobility applications face the steepest compliance ramps, with urban robotaxi fleets requiring third-party audit trails absent from highway freight scenarios.
Fleet procurement is consolidating around performance-based service contracts that transfer mileage-risk to technology providers rather than capitalizing autonomous hardware. Third-party logistics operators are displacing traditional vehicle ownership models with per-mile subscriptions in Arizona and Texas freight corridors. The restructuring concentrates volume with vertically integrated stack owners capable of underwriting operational risk.
Fully Autonomous Driving Market Segmentation
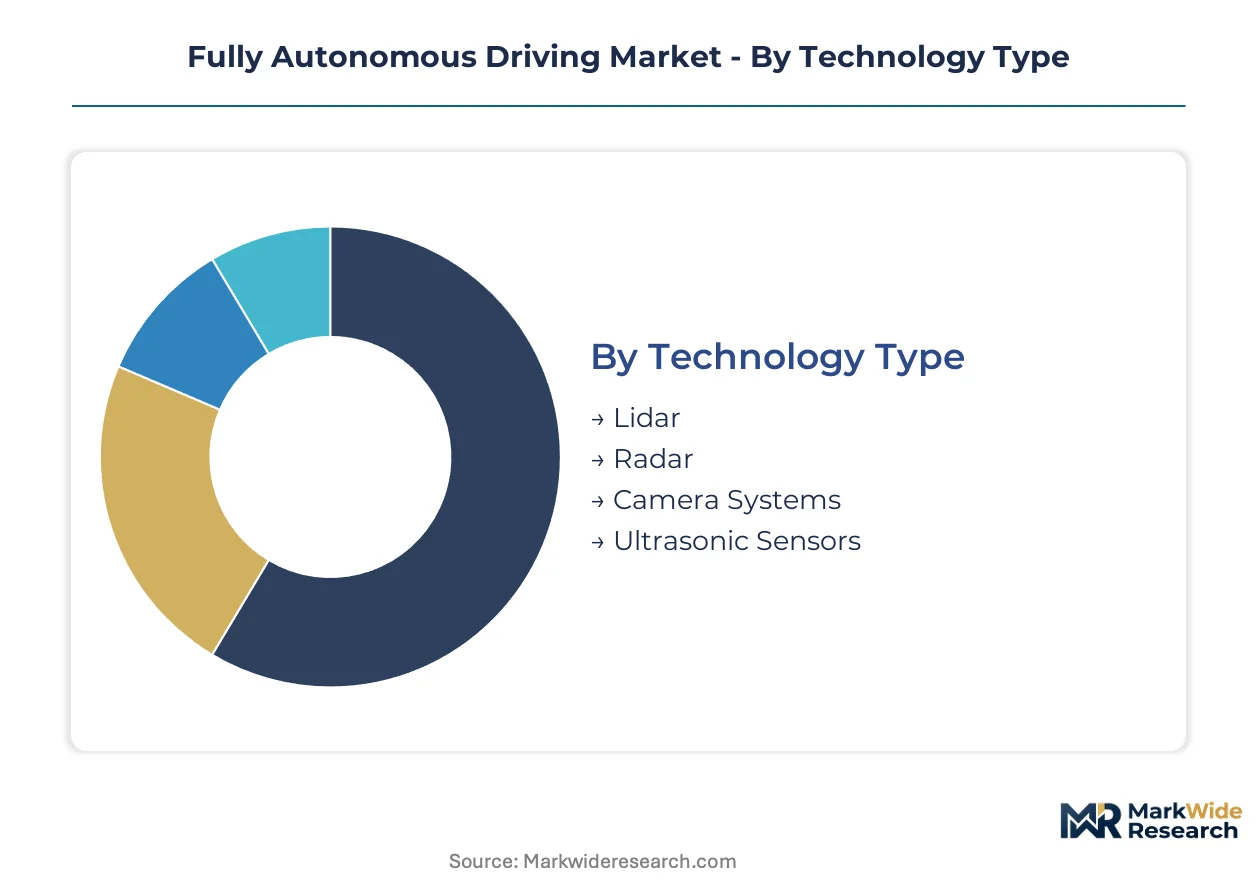
Segmentation in fully autonomous driving reveals how hardware economics, vehicle architecture, and operational models diverge across deployment contexts. Technology choices determine cost structures and regulatory pathways, while vehicle type and end-user concentration shape addressable market boundaries.
Technology Type:
Mature sensor modalities dominate current deployments, while emerging solid-state alternatives are compressing cost curves for mid-tier applications.
- Lidar:Time-of-flight and frequency-modulated continuous-wave systems emit laser pulses to construct centimeter-accurate 3D point clouds. Urban robotaxi fleets in Phoenix and San Francisco concentrate demand here, where NHTSA crashworthiness protocols reward redundant ranging precision.
- Camera Systems:Stereoscopic and monocular arrays capture visual spectrum data processed through convolutional neural networks for lane detection and traffic sign recognition. Tesla's production volumes anchor demand in this segment, with the camera-first architecture slashing per-vehicle sensor costs below lidar-equipped alternatives.
- Radar:Millimeter-wave units penetrate weather obscurants to measure relative velocity and range.
- Ultrasonic Sensors:Short-range acoustic modules handle parking maneuvers and low-speed obstacle detection.
Camera systems handle the majority of unit shipments; lidar is expanding most quickly in revenue terms as urban robotaxi fleets scale.
Vehicle Type:
Application complexity and regulatory approval timelines split the market between highway-dominated freight and dense urban passenger mobility.
- Heavy-Duty Trucks:Class 8 tractors with fixed-route highway autonomy reduce edge-case exposure versus urban environments. Aurora Innovation and Kodiak Robotics concentrate R&D investment here, leveraging simplified operational design domains to accelerate Federal Motor Carrier Safety Administration approval timelines for interstate freight corridors.
- Passenger Cars:Light-duty vehicles with SAE Level 4 capability target robotaxi and personal ownership markets. Waymo's vertically integrated sensor stack dominates this segment, sustaining unit economics across large-scale deployments in Arizona and California where permissive state frameworks enable expanded operations.
- Buses:Fixed-route public transit applications with dedicated infrastructure.
- Delivery Drones:Aerial last-mile systems operating below 400 feet in controlled airspace.
Heavy-duty trucks capture the steepest R&D allocation; passenger cars maintain the broadest addressable market footprint.
End User:
Risk tolerance and capital intensity differentiate procurement patterns across customer archetypes.
- Fleet Operators:Asset-heavy logistics and mobility companies purchase autonomous capability as operational infrastructure. Third-party logistics operators in Texas and Arizona freight corridors are displacing traditional vehicle ownership with per-mile subscriptions, transferring mileage-risk to technology providers.
- Ride-Hailing Services:Platform companies deploy robotaxi fleets to eliminate driver cost structures. Waymo and Cruise concentrate deployment here, leveraging permissive California DMV frameworks to generate real-world training data unavailable in restrictive jurisdictions.
- Consumers:Individual purchasers of personally owned autonomous vehicles.
- Logistics Companies:Supply-chain operators integrating autonomy into warehouse-to-doorstep networks.
Fleet operators command the dominant share of current procurement volume; ride-hailing services are climbing the fastest on deployment velocity.
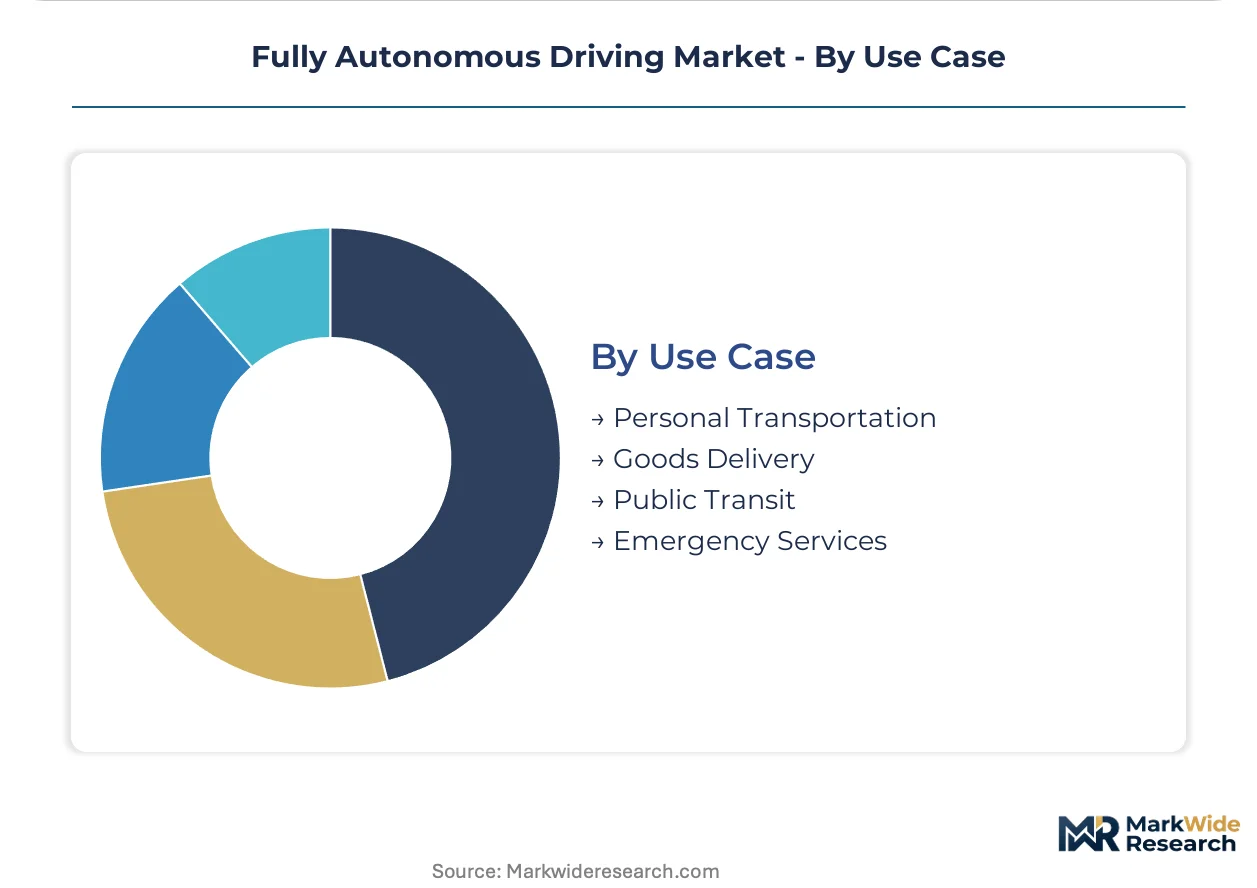
Use Case:
Regulatory clarity and revenue model maturity determine which applications exit pilot phase into commercial service.
- Goods Delivery:Autonomous vans and trucks executing business-to-business and last-mile distribution. Nuro and Amazon Scout concentrate investment here, exploiting simplified liability frameworks for property-carrying versus passenger-carrying operations.
- Personal Transportation:Robotaxi and privately owned vehicle autonomy for individual mobility. Waymo One operations in Phoenix anchor this segment, with California PUC permits enabling fare-charging service expansion.
- Public Transit:Fixed-route autonomous bus and shuttle networks.
- Emergency Services:Autonomous ambulances and disaster response vehicles operating in degraded infrastructure conditions.
Goods delivery handles the majority of commercial kilometers; personal transportation is gaining share fastest as robotaxi permits proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permissive regulatory frameworks and concentrated public R&D funding are accelerating commercial deployment timelines across select jurisdictions. National governments are racing to establish liability protocols and testing permits that attract autonomous vehicle developers. Geographic clusters are forming around cities with established sensor manufacturing bases and favorable insurance regimes.
United States
The NHTSA crashworthiness protocols and California DMV autonomous vehicle testing framework create dual regulatory gravity wells. The Federal Communications Commission governs 5.9 GHz spectrum allocation for vehicle-to-everything communication links. Phoenix, Arizona and San Francisco, California anchor robotaxi operations where permissive state frameworks enable fare-charging service expansion.
Germany
The KBA type-approval process and amended StVO traffic regulations permit Level 4 operation on designated highway segments. The EU AI Act conformity assessment mandates documented training data provenance for high-risk AI systems. Stuttgart and Munich concentrate automotive supplier restructuring around homologation investments for European market access.
China
MIIT intelligent vehicle standards and SAMR data security regulations shape deployment permissions for connected autonomous systems. The dual carbon goals accelerate electric-autonomous fleet integration in urban logistics. Beijing and Shanghai host concentrated pilot zones where municipal governments underwrite testing infrastructure.
United Kingdom
The Centre for Connected and Autonomous Vehicles funds R&D through the commercializing connected and automated mobility program. The Law Commission's automated vehicles review established liability frameworks for user-in-charge transitions. Oxford and Cambridge anchor academic-industrial clusters advancing occupancy network architectures.
Japan
METI's Society 5.0 roadmap prioritizes autonomous mobility for aging population demographics. The MLIT amended Road Transport Vehicle Act permits Level 4 operation in geofenced districts. Tokyo and Nagoya concentrate OEM-supplier consortia developing highway-fixed-route freight automation.
Fully Autonomous Driving Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated sensor stack owners and captive fleet operators with proven safety records. Capital discipline from per-mile revenue guarantees is compressing the field of credible competitors. Three archetypes dominate: technology conglomerates with foundation model capabilities, automotive OEMs with manufacturing scale, and venture-backed autonomy specialists with narrow operational design domains. Competitive dynamics center on strategic partnerships with fleet operators and regulatory lobbying for expanded testing permits.
Among technology-focused developers, Waymo, Tesla, and Aurora Innovation occupy distinct positioning vectors. Waymo exemplifies the vertically integrated archetype through captive lidar production and large-scale robotaxi deployment. Tesla represents the camera-first cost reduction pathway that slashes hardware expenses for consumer vehicle integration. Aurora Innovation anchors the long-haul freight specialization segment, leveraging simplified highway operational domains to accelerate regulatory timelines.
| Leading Market Players |
|---|
| Waymo |
| Cruise |
| Tesla |
| Zoox |
| Motional |
| Torc |
| Gatik |
| Wayve |
| Aurora Innovation |
| Others |
Pricing and Supply Chain Analysis
Waymo's Phoenix sensor manufacturing cluster anchors global lidar production capacity, with its captive supply of solid-state emitters translating directly into pricing power over robotaxi fleet operators negotiating per-mile service contracts. The concentration of high-definition mapping providers in California's Bay Area reinforces this dynamic, as proprietary geospatial data moats limit competitive entry and sustain premium positioning for urban autonomy deployments.
Pricing Analysis
Certification level under UNECE WP.29 type-approval creates the primary spread between premium lidar-integrated stacks and economy camera-first alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects hardware complexity, with urban robotaxi fleets absorbing premium sensor costs while long-haul freight operators prioritize economy-tier camera-radar fusion. Cost compression in the economy tier is intensifying because Tesla's production volumes drive component commoditization. Fleet operators exhibit the highest price sensitivity, whereas ride-hailing platforms with driver-cost elimination models accept premium hardware outlays.
Supply Chain Analysis
US Commerce Department export controls on advanced lidar emitters and AI accelerators constrain technology flows to Chinese autonomous vehicle developers, fragmenting global component sourcing. Manufacturing concentrates in the United States, Germany, and Taiwan, with solid-state lidar foundries in Arizona and California feeding domestic robotaxi deployments. The supply chain draws from rare-earth magnet suppliers for electric drivetrains, silicon photonics for lidar receivers, and high-bandwidth memory for neural inference. Single-source vulnerability around indium phosphide wafer supply poses structural risk. Distribution runs through Tier 1 automotive suppliers integrating full sensor suites for OEM assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from human-in-the-loop teleoperation services that delay full autonomy adoption while capturing intermediate efficiency gains. Fleet operators must defend market position against these hybrid alternatives through accelerated safety validation and regulatory capture.
For Market Incumbents: Build regulatory approval moats by pre-emptively certifying Level 4 systems under the EU AI Act's high-risk AI framework before competitors complete documentation workflows. Secure exclusive mapping licenses for dense urban corridors to constrain rival operational design domains. Human-supervised remote operation services threaten to commoditize autonomy value propositions; counter by demonstrating measurable safety superiority in disengagement metrics. Channel control through direct fleet ownership rather than technology licensing preserves pricing power.
For New Entrants and Emerging Players: Pursue retrofit autonomy kits for existing commercial truck fleets as the most penetrable white-space target, bypassing OEM integration timelines that favor established suppliers. Target Arizona and Texas freight corridors where permissive state frameworks reduce homologation barriers relative to passenger mobility applications. Aftermarket sensor packages for Class 8 tractors offer faster revenue capture than robotaxi development cycles. Go-to-market execution should anchor in per-mile subscription models that transfer operational risk from fleet buyers.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because autonomous freight corridors will capture toll-like revenue streams from logistics operators seeking predictable unit economics. Acquisition targets should display captive sensor production and proven safety records across million-plus miles. Vertically integrated stack owners with regulatory permits in multiple US states represent the optimal target archetype. Watch California DMV permit expansion velocity as the signal indicating inflection from pilot to commercial scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Stack Vertical Integration | Captive lidar production insulates Waymo from supply disruptions and sustains unit economics across scaled robotaxi deployments. |
| High-Definition Mapping Partnership | Exclusive geospatial data licenses constrain rival operational expansion to pre-mapped corridors in Phoenix and San Francisco. |
| EU AI Act Pre-Certification | Early conformity assessment completion accelerates European market access ahead of competitors restructuring documentation workflows. |
| Highway Freight Corridor Deployment | Fixed-route autonomy in Arizona and Texas exploits reduced edge-case complexity to compress FMCSA approval timelines. |
| Per-Mile Revenue Guarantee Structure | Performance-based contracts transfer mileage-risk to technology providers and consolidate volume with proven safety record holders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted to construct this analysis, combining structured interviews with fleet procurement directors, autonomous vehicle safety engineers, and regulatory affairs leads at technology developers with secondary validation against NHTSA defect investigation databases, California DMV autonomous vehicle testing reports, SEC 10-K filings from publicly traded autonomy companies, and UNECE WP.29 regulatory submission records. Bottom-up triangulation across sensor shipment volumes and top-down reconciliation against fleet operator capex disclosures ensured cross-verified market sizing.
Calibration against historical deployment trajectories in Phoenix and San Francisco informed growth assumptions across the projection horizon. The analytical framework modeled segmentation across sensor modality, vehicle type, and end-user archetype, with additional dimensioning by regulatory jurisdiction cluster. CAGRs were derived from logistic diffusion curves fitted to permit expansion rates and fleet operator procurement announcements. Neural training compute cost curves and lidar unit cost declines served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in logistics sector freight volumes and venture capital deployment into deep technology would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory permit expansion timelines and sensor cost reduction curves. Material shifts in NHTSA preemption proposals or UNECE WP.29 national implementation divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Europe IoT Connected Cars Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Autonomous Parking System Market