
 Europe ADAS Market | 2026-2036
Europe ADAS Market Size, Share, and Industry Trends Forecast 2026-2036
Europe ADAS Market Foresight
Fleet operators are reorganizing procurement priorities around advanced driver-assistance bundles as OEMs and rental services scale back discretionary tech spending. Continental AG leverages its integrated sensor portfolio to sustain long-term supply relationships with German and French automakers. Robert Bosch GmbH anchors European radar production through captive semiconductor sourcing and regional foundry partnerships. ZF Friedrichshafen AG differentiates via its integrated braking-steering platforms that bundle ADAS actuation with chassis control.
Advanced driver-assistance systems encompass sensor fusion architectures combining radar, camera, lidar, and ultrasonic modules with real-time processing units to automate partial vehicle control functions including adaptive speed regulation, trajectory correction, and collision mitigation. Camera-based systems lead installed volumes due to lower unit costs and versatility in lane-keeping and traffic-sign recognition applications, while lidar segments capture concentrated margin pools in premium collision-avoidance configurations for electric vehicles. End-user demand splits structurally between OEMs, which embed ADAS at factory level to meet type-approval requirements, and aftermarket providers serving retrofit demand from commercial fleets seeking compliance upgrades without full vehicle replacement.
EU type-approval frameworks under UNECE regulations, Euro NCAP assessment protocols, and the EU AI Act collectively mandate graduated safety performance thresholds that OEMs must satisfy for market access and consumer scoring visibility. EMA and national transport authorities coordinate cross-border recognition of automated system certifications, reducing fragmentation but imposing documentation burdens on non-EU component suppliers. Stakeholders must monitor evolving liability frameworks for mixed-autonomy driving scenarios where system failure and human override create ambiguous fault allocation.
Market Dynamics
EU type-approval frameworks and Euro NCAP safety scoring are compressing OEM development cycles, forcing suppliers to synchronize sensor validation timelines with accelerated vehicle platform launches while managing semiconductor allocation constraints across multiple automaker programs.
Growth Catalysts
- Euro NCAP Assessment Protocols:Star-rating thresholds for vulnerable road user protection mandate camera-radar fusion systems on all new vehicle registrations, pulling forward sensor procurement from fleet operators and rental services.
- Commercial Fleet Compliance Upgrades:Logistics operators across Germany, France, and Poland retrofit existing vehicle pools with aftermarket ADAS bundles to satisfy national work-safety directives without full fleet replacement.
- Sensor Fusion Architectures:Real-time integration of radar, camera, and ultrasonic modules enables partial automation functions that satisfy UNECE Regulation 79 for lane-keeping assistance.
Market Restraints
- Semiconductor Allocation Bottlenecks:Foundry capacity constraints for automotive-grade silicon carbide and radar chipsets extend lead times for Tier-1 suppliers serving German and French OEM programs.
- Liability Ambiguity in Mixed-Autonomy Scenarios:Unclear fault allocation between human override and system failure under EU AI Act and national tort frameworks elevates insurance costs for Level 2+ deployments.
- Camera System Margin Compression:Commoditization of mono-camera lane-keeping modules erodes supplier profitability despite volume expansion across mass-market vehicle segments.
Strategic Opportunities
- Eastern European Fleet Retrofit Demand:Underpenetrated commercial vehicle pools in Poland, Czech Republic, and Romania present white-space for aftermarket ADAS providers bundling compliance hardware with installation networks.
- Lidar Integration in Premium EV Platforms:Highway pilot and urban collision-avoidance configurations for electric vehicle architectures create concentrated margin pools as OEMs differentiate safety performance.
- EU Green Deal Procurement Incentives:Member-state subsidies for zero-emission commercial vehicles increasingly bundle ADAS requirements, linking environmental and safety technology adoption decisions.
Industry Challenges
- Functional Safety Engineer Scarcity:ISO 26262 certification expertise for ASIL-D rated systems remains concentrated among German and French engineering consultancies, constraining supplier scaling.
- Cross-Border Certification Documentation:EMA coordination of automated system approvals still imposes redundant testing burdens on non-EU component suppliers seeking multi-country market access.
- Legacy Vehicle Electrical Architecture Integration:Retrofit ADAS deployment on pre-2020 commercial fleets requires gateway module adaptation that fragments supplier software development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe ADAS Market |
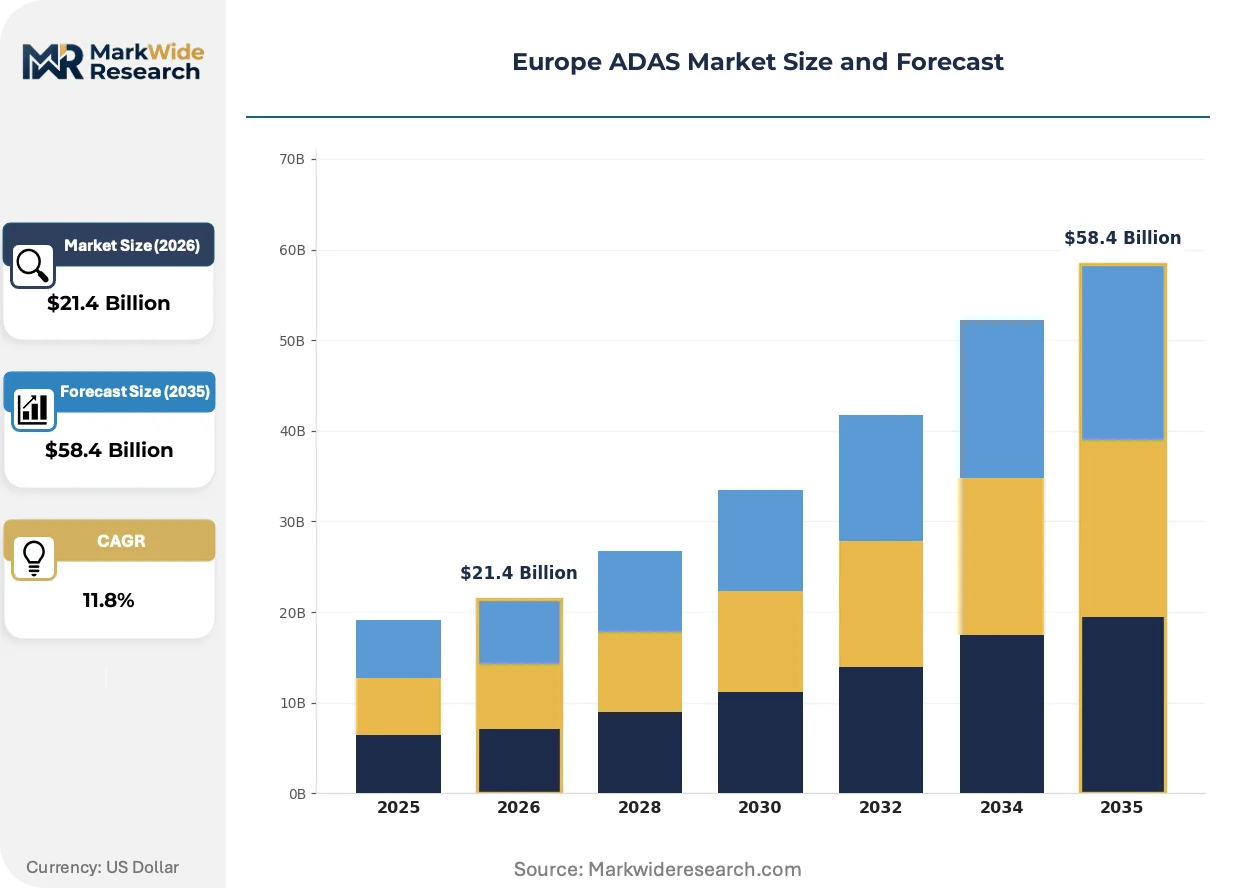
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $58.4 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, Lidar, Camera, Ultrasonic Application: Adaptive Cruise Control, Parking Assistance, Lane Keeping Assist, Collision Avoidance End User: OEMs, Aftermarket Providers, Fleet Operators, Rental Services Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Electric Vehicles |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Autoliv AB, Valeo SA, Aptiv PLC, Magna International Inc., Denso Corporation, Hella KGaA Hueck & Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe ADAS Market Shifts & Advancements
ADAS technology trajectories are diverging between cost-optimized mass-market configurations and compute-intensive premium automation stacks, with regulatory pressure and buyer segmentation driving parallel development paths rather than unified platform strategies.
Camera-based perception stacks are bifurcating into two distinct technology tiers. Mono-camera systems with basic traffic-sign recognition and lane-keeping dominate high-volume compact and mid-size vehicle programs where unit cost constraints predominate. Multi-camera surround-view architectures with neural-network-based object detection command premium positioning in luxury and electric vehicle segments, enabling highway pilot functions that satisfy Euro NCAP's assisted-driving grading. This technological split is compressing mid-tier supplier margins while concentrating R&D investment among firms with scalable software-defined perception platforms.
REACH and RoHS substance restrictions are tightening material compliance requirements for sensor housings and printed circuit board assemblies. The European Chemicals Agency's expanded candidate list for Substances of Very High Concern is forcing suppliers to reformulate solder alloys and housing polymers ahead of sunset dates. Camera module manufacturers serving French and Italian OEMs are accelerating qualification of halogen-free flame-retardant materials to maintain component eligibility across EU-27 type-approval jurisdictions.
Fleet procurement committees are consolidating vendor relationships around integrated braking-steering-ADAS platform suppliers capable of single-source liability for actuation performance. Rental and logistics operators in Germany and the Netherlands are displacing discrete component purchasing in favor of bundled chassis control contracts that package sensor hardware with over-the-air update commitments. This buyer concentration is most visible in long-term commercial vehicle leasing arrangements where residual value guarantees depend on documented safety technology maintenance.
Europe ADAS Market Segmentation
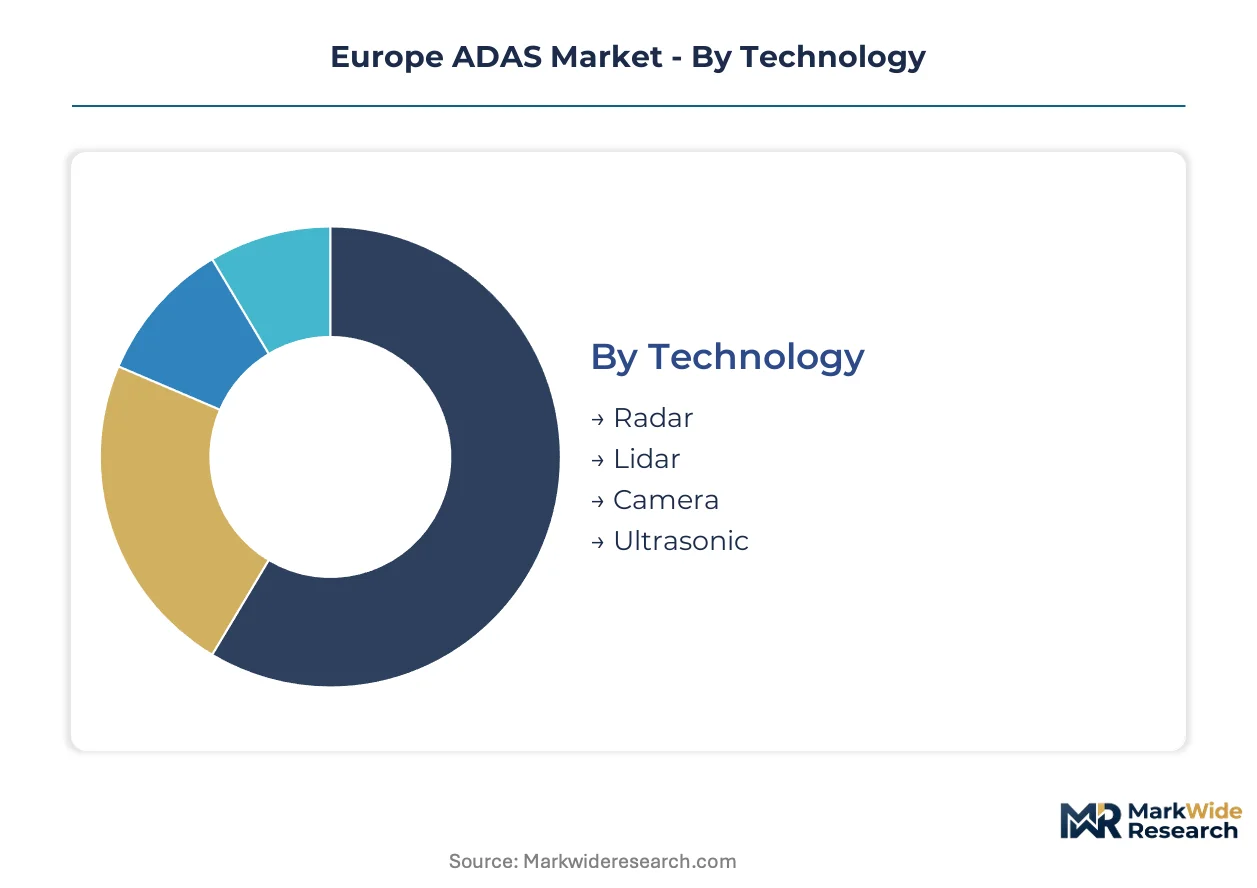
ADAS procurement patterns diverge sharply across technology tiers and vehicle categories, with regulatory pressure and fleet compliance timelines creating distinct demand pockets. Segment-level strategy requires matching sensor specifications to end-user procurement constraints and type-approval pathways.
Technology:
Radar and camera systems dominate domestic European supply chains, while lidar modules rely heavily on Asian component sourcing for laser emitters and photodetector arrays.
- Radar:77 GHz and 79 GHz frequency-modulated continuous wave architectures provide all-weather velocity and range detection for adaptive cruise control and blind-spot monitoring. German and French OEMs concentrate procurement here for highway automation functions, though foundry bottlenecks for gallium nitride front-end modules extend lead times.
- Camera:Mono and multi-camera perception stacks process traffic-sign recognition and lane-keeping through neural network inference on embedded GPUs. Mass-market vehicle programs across Spain and Italy drive volume, with cost pressure forcing consolidation around 2-megapixel baseline specifications.
- Lidar:Solid-state and hybrid scanning units generate dense point clouds for urban collision avoidance.
- Ultrasonic:Short-range parking assistance and low-speed maneuvering support.
Camera holds the largest share; momentum sits with lidar as premium EV platforms scale highway pilot deployments.
Application:
Cost tiering separates mandated safety functions from discretionary convenience features, with regulatory deadlines compressing the former into standard equipment.
- Adaptive Cruise Control:Radar-camera fusion maintains set speeds and following distances through longitudinal vehicle control, satisfying UNECE Regulation 79 for partial automation. Fleet operators in the Netherlands and Belgium prioritize this function for fuel efficiency and driver fatigue reduction on long-haul routes.
- Lane Keeping Assist:Camera-based trajectory correction applies steering torque when unintentional drift is detected. German OEMs embed this as standard across all vehicle classes to secure Euro NCAP five-star ratings, displacing optional bundling.
- Parking Assistance:Ultrasonic and camera fusion enables automated steering into confined spaces.
- Collision Avoidance:Multi-sensor emergency braking for vulnerable road user protection.
Lane keeping assist commands the broadest installation base; collision avoidance is expanding most quickly under pedestrian-safety mandates.
End User:
Volume concentration sits with factory-fit programs, though aftermarket retrofit is accelerating as commercial fleet compliance deadlines approach.
- OEMs:Vehicle manufacturers embed ADAS at platform development stage to secure type-approval and NCAP scoring visibility. German, French, and Swedish automakers synchronize sensor roadmaps with electrical architecture refreshes on 5-7 year cycles.
- Fleet Operators:Logistics and rental companies retrofit existing vehicle pools to satisfy national work-safety directives without full replacement. Polish and Romanian trucking fleets represent underpenetrated demand for bundled compliance hardware with installation networks.
- Aftermarket Providers:Independent installers serve owner-operators and small fleet segments.
- Rental Services:Short-term vehicle lessors specify ADAS to reduce incident liability and residual value risk.
OEMs retain the dominant procurement volume; fleet operators are gaining share fastest as retrofit deadlines tighten across Eastern Europe.
Vehicle Type:
Electrification strategy and safety regulation intersect differently across passenger, commercial, and two-wheeler segments.
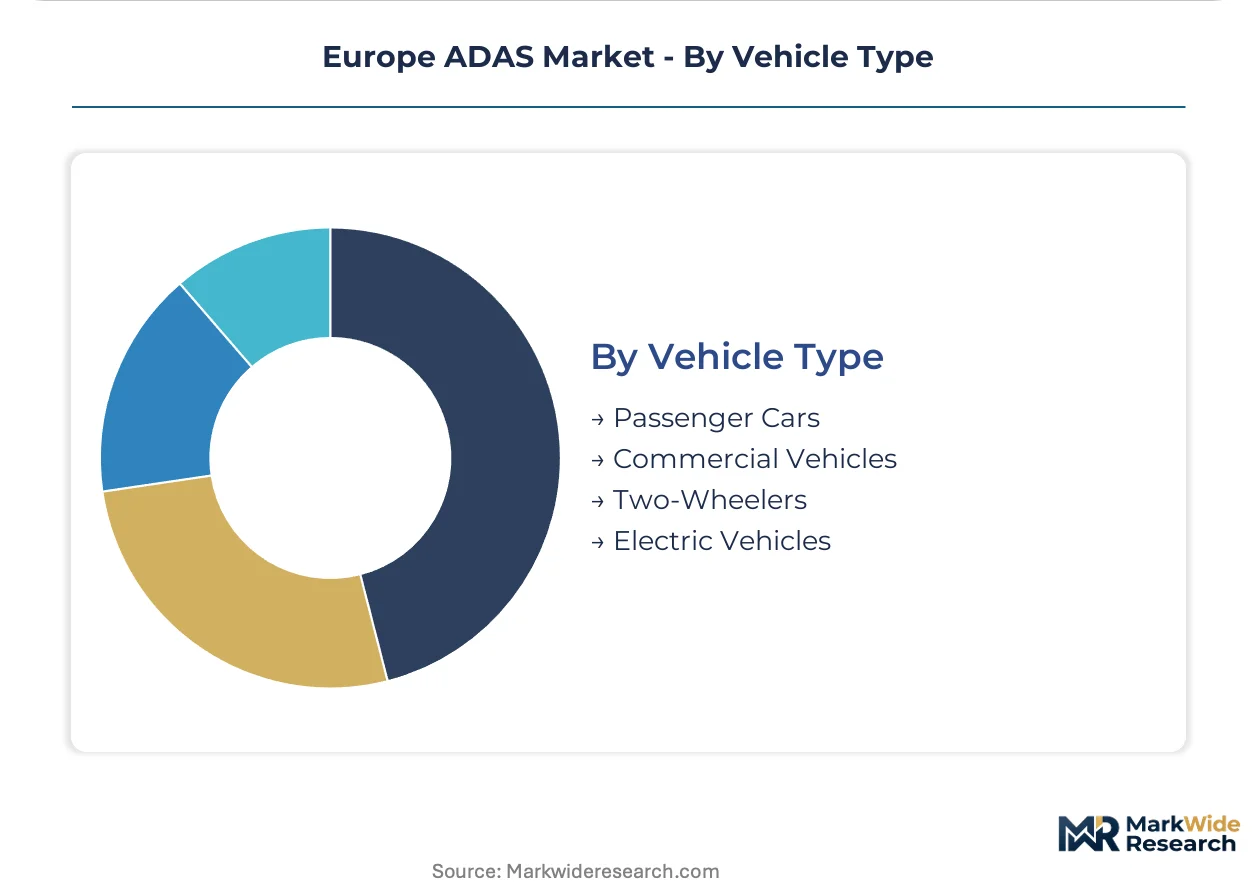
- Passenger Cars:Compact and mid-size vehicle programs drive camera-system volumes, while premium architectures integrate lidar for highway pilot differentiation. French and Italian OEMs lead mass-market penetration; German manufacturers anchor premium automation stacks.
- Electric Vehicles:Battery-electric platforms prioritize sensor-rich configurations to justify premium positioning and support over-the-air feature expansion. EU Green Deal procurement incentives increasingly bundle ADAS requirements with zero-emission subsidies.
- Commercial Vehicles:Heavy-duty trucks and vans face accelerating mandates for blind-spot monitoring and pedestrian detection.
- Two-Wheelers:Motorcycles and scooters adopt leaner ultrasonic and camera systems for rear collision warning.
Passenger cars represent the largest addressable base; electric vehicles are climbing the fastest as platform architectures enable sensor integration at design stage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor and the Trans-European Transport Network (TEN-T) freight corridors underwrite Central Europe's role as the primary logistics backbone for ADAS component distribution and fleet retrofit deployment.
Germany
Industrial demand concentrates around Stuttgart's automotive supplier cluster and Wolfsburg's OEM engineering centers. The KBA enforces UNECE Regulation 79 compliance timelines that compress sensor validation cycles. Continental AG and Robert Bosch GmbH anchor radar and camera production in Baden-Württemberg through captive semiconductor sourcing arrangements.
France
Paris-based fleet operators and Lyon-area commercial vehicle manufacturers drive procurement of lane-keeping and adaptive cruise bundles. ANSM coordinates with Euro NCAP on pedestrian-safety scoring protocols that mandate camera-radar fusion. Valeo SA exemplifies the tier-one supplier archetype through its integrated perception platform development in Île-de-France.
United Kingdom
Midlands automotive manufacturing and London-centric rental fleet operators shape aftermarket retrofit demand. The Driver and Vehicle Standards Agency aligns type-approval with evolving EU AI Act liability frameworks post-Brexit transition. Warwickshire engineering consultancies concentrate ISO 26262 functional safety certification expertise for ASIL-D rated systems.
Poland
Trucking corridors linking Warsaw to Berlin and Prague generate concentrated commercial fleet compliance upgrade demand. National work-safety directives from the Polish Ministry of Infrastructure mandate blind-spot monitoring on heavy-duty vehicles. Silesian logistics hubs present white-space opportunity for aftermarket ADAS providers bundling hardware with regional installation networks.
Netherlands
Rotterdam port logistics and Amsterdam-Schiphol freight corridors drive procurement of fuel-efficiency-optimized adaptive cruise systems. The Dutch Vehicle Authority enforces Euro NCAP five-star thresholds for fleet registrations used in cross-border EU operations. Eindhoven's high-tech campus anchors sensor fusion R&D partnerships between semiconductor foundries and tier-one suppliers.
Europe ADAS Market Competitive Landscape
Concentration sits with diversified automotive suppliers possessing captive semiconductor sourcing and integrated chassis control portfolios. The vendor base stratifies between full-stack platform providers and discrete component specialists, with mid-tier camera module manufacturers facing margin compression from commoditization. Three archetypes dominate: integrated braking-steering-ADAS platform suppliers, radar-centric sensor fusion specialists, and lidar-focused premium automation enablers. Competitive moves center on backward integration into gallium nitride foundry capacity and long-term fleet service contracts bundling hardware with over-the-air update commitments.
Within the integrated platform tier, Continental AG, ZF Friedrichshafen AG, and Robert Bosch GmbH exemplify the supplier archetype combining sensor hardware with chassis control actuation. These Germany-based entities occupy positions shaped by proximity to Stuttgart and Wolfsburg OEM engineering centers. Continental AG represents the diversified sensor portfolio approach, while ZF Friedrichshafen AG anchors integrated braking-steering platforms. Robert Bosch GmbH exemplifies radar production concentration through regional foundry partnerships. Autoliv AB and Valeo SA sit within the safety system specialist tier, with the former representing passive-active safety integration and the latter exemplifying French-centric perception platform development. Aptiv PLC and Magna International Inc. occupy positions as North American-headquartered suppliers with European manufacturing footprints.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Autoliv AB |
| Valeo SA |
| Aptiv PLC |
| Magna International Inc. |
| Denso Corporation |
| Hella KGaA Hueck & Co. |
| Others |
Supply & Pricing Matrix
Silicon carbide substrate substitution for traditional silicon is redrawing foundry geography toward European captive facilities while compressing radar chipset pricing through volume scale effects at German and French OEM programs.
Pricing Analysis
Volume-discount tiering structures separate German OEM direct procurement from Eastern European fleet retrofit bundles, with camera module commoditization forcing margin extraction toward software-defined perception stacks and over-the-air update subscriptions. Price differentiation hinges on ASIL-D functional safety certification and captive gallium nitride foundry access, with mass-market mono-camera tiers experiencing cost compression while lidar configurations for premium EV platforms sustain pricing power. Fleet operators in Poland and Romania exhibit highest price sensitivity due to compliance-driven retrofit mandates without platform integration leverage.
Supply Chain Analysis
Germany and France anchor radar and camera module production through Continental AG and Robert Bosch GmbH facilities in Baden-Württemberg, while Taiwan and South Korea supply photodetector arrays and laser emitters for lidar subassemblies. The European ADAS supply chain draws from automotive-grade silicon carbide wafers, gallium nitride front-end modules, and halogen-free flame-retardant housing polymers. Single-source vulnerability concentrates in Asian laser component sourcing for solid-state lidar. Distribution runs through Rhine-Main-Danube logistics corridors and TEN-T freight networks serving Stuttgart and Wolfsburg engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's ADAS market is recovering from semiconductor allocation troughs, with Euro NCAP mandate acceleration providing cyclical lift through compliance-driven sensor procurement.
For Market Incumbents: Compound defensive positioning through backward integration into gallium nitride foundry capacity and long-term fleet service contracts bundling hardware with over-the-air update commitments. Camera module commoditization from Chinese tier-two suppliers threatens discrete component margins, making integrated braking-steering-ADAS platform control the priority lever for sustaining OEM relationships.
For New Entrants and Emerging Players: Lead with aftermarket retrofit bundles targeting Polish and Romanian commercial fleets facing national work-safety directive deadlines without full vehicle replacement capital. White-space concentrates in Silesian logistics hubs where regional installation networks can pair compliance hardware with gateway module adaptation services for pre-2020 vehicle architectures.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sensor fusion software specialists possessing ISO 26262 ASIL-D certification expertise concentrated among German and French engineering consultancies. Long-term viability favors targets with scalable neural-network perception platforms and documented over-the-air update infrastructure. The signal to watch is Euro NCAP protocol expansion beyond highway automation into urban collision-avoidance scoring.
| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Foundry Backward Integration | Captive semiconductor sourcing secures radar chipset supply for German OEM programs against allocation bottlenecks. |
| Fleet Retrofit Installation Network Expansion | Regional service coverage in Poland and Romania captures compliance-driven hardware demand from trucking operators. |
| Software-Defined Perception Platform Development | Neural-network inference stacks differentiate premium EV offerings beyond commoditized mono-camera systems. |
| ASIL-D Functional Safety Certification Investment | ISO 26262 expertise scarcity creates defensive moats for suppliers serving Stuttgart and Wolfsburg engineering centers. |
| Over-the-Air Update Infrastructure Deployment | Feature expansion capabilities justify long-term leasing contracts with Dutch and German rental fleet operators. |
Research Methodology
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution managers, and fleet operations heads provided ongoing calibration against secondary validation from Euro NCAP assessment databases, UNECE Regulation 79 documentation, KBA type-approval records, and vehicle production registration data. Primary fieldwork combined structured interviews with German and French automotive clusters with bottom-up sensor shipment analysis triangulated against top-down OEM platform deployment schedules.
Consistency checks validated volume and value outputs against IHS Markit vehicle registration data and European rental fleet ADAS penetration surveys across the projection horizon. Segmentation modeling spanned technology tier, vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from installed base growth curves weighted by Euro NCAP scoring timeline acceleration and fleet compliance retrofit deadlines.
The analysis sits within stated boundaries; outcomes outside Euro NCAP protocol stability, semiconductor foundry capacity normalization, or EU AI Act liability framework clarity would require recalibration. Forecasts reflect assumptions regarding regulatory mandate enforcement consistency and fleet operator capital allocation priorities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Australia Autonomous Navigation Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
Global Driverless Car Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market
Autonomous Vehicles
Fully Autonomous Driving Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Automated Truck Technology Market