
 France Autonomous Navigation Market | 2026-2036
France Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
France Autonomous Navigation Market Insights
Specialized robotics and AI engineering talent is rotating toward defense-aerospace hybrids as commercial autonomous projects face funding compression. Thales leverages its sensor fusion heritage to anchor naval autonomous navigation programs. Safran sustains R&D intensity in aerial platforms through its Toulouse engineering base. Valeo competes in automotive-grade perception stacks, extending its ADAS supply relationships into robotaxi trials.
Autonomous navigation denotes self-directed positioning and path-planning systems that integrate multi-sensor data streams with real-time decision algorithms to operate without continuous human intervention, typically achieving sub-meter accuracy through Kalman-filtered GPS inertial coupling. The primary purpose spans mission-critical routing for unmanned vehicles across air, sea, and ground domains where operator latency or connectivity gaps create operational risk. Marine applications within the application dimension dominate near-term contract value, buoyed by French naval modernization and offshore energy inspection demand. Computer vision technology is displacing pure lidar architectures in cost-sensitive logistics robotics, though defense-grade aerial systems retain multi-sensor redundancy. Edge deployment configurations are capturing share from cloud-reliant setups as latency requirements tighten for collision-avoidance loops.
ANSM and France's national cybersecurity agency ANSSI shape medical and critical infrastructure autonomous system approvals, while EU AI Act risk-classification rules force algorithmic transparency documentation for high-stakes navigation decisions. REACH chemical constraints and CE marking directives govern sensor material composition and electromagnetic compatibility across deployed fleets. Stakeholders must weigh sovereignty-driven procurement preferences against the interoperability demands of NATO and EU defense collaboration frameworks.
Market Dynamics
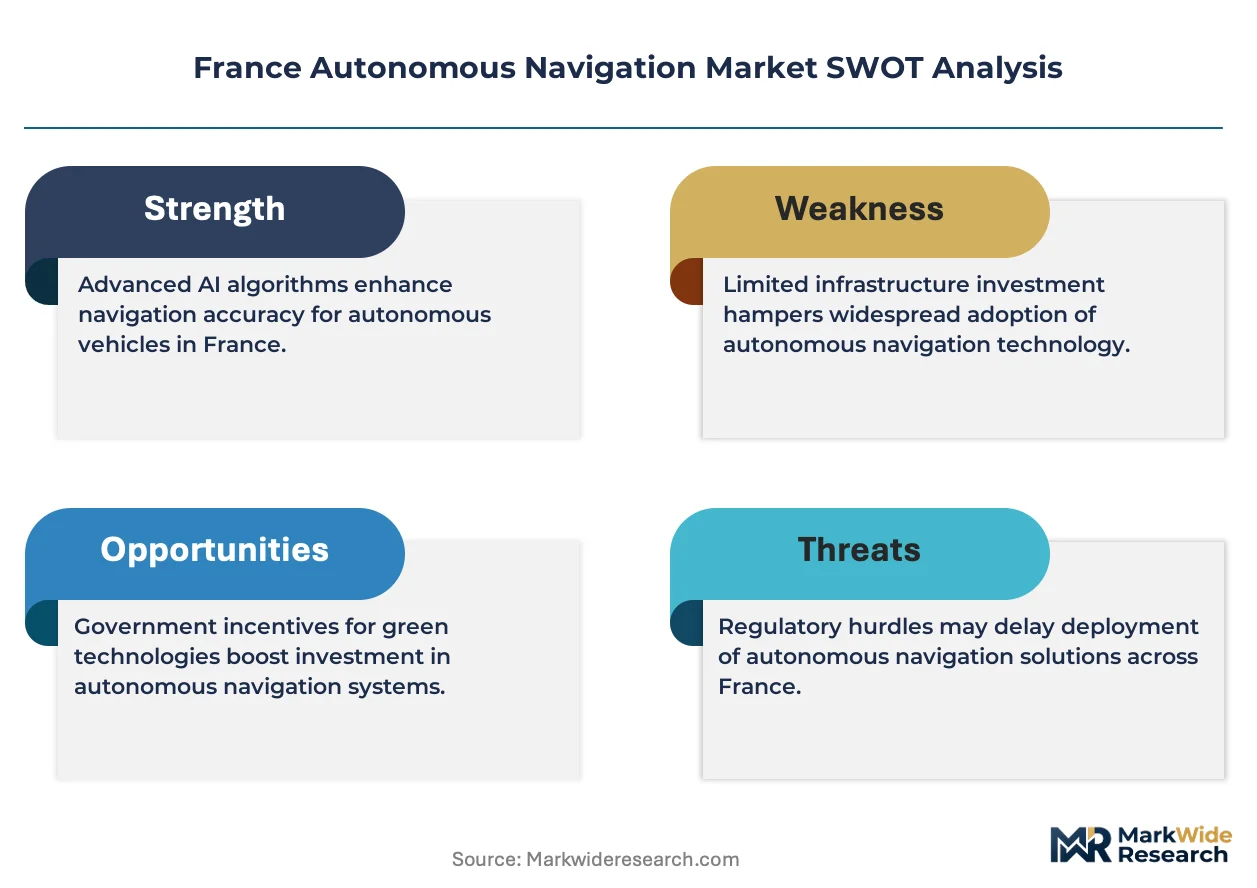
French naval modernization programs are compressing development cycles for autonomous maritime systems while EU AI Act certification requirements force algorithmic documentation standards that reshape vendor qualification pathways.
Growth Catalysts
- EU AI Act risk-classification framework:High-stakes navigation decisions now require transparent algorithmic documentation, creating formal procurement channels for certified autonomy providers.
- Offshore energy inspection demand:North Sea and Atlantic offshore wind installations drive unmanned surface vessel deployment for subsea cable monitoring.
- Toulouse aerospace cluster concentration:Engineering talent density around Airbus heritage facilities accelerates aerial autonomy prototyping and sensor integration.
Market Restraints
- Lidar sensor cost volatility:Defense-grade multi-sensor redundancy requirements sustain elevated bill-of-materials pressure against commercial cost-down trajectories.
- Edge computing hardware concentration:GPU and specialized inference chip supply chains concentrate in East Asian foundries, exposing French system integrators to geopolitical supply friction.
- CE marking electromagnetic compatibility delays:Fleet-wide certification timelines extend deployment schedules for multi-vehicle autonomous convoys.
Strategic Opportunities
- Paris-Saclay robotics corridor expansion:Research-to-commercialization pipelines for ground-based logistics autonomy remain underexploited relative to maritime and aerial segments.
- 5G-Advanced and satellite convergence:Low-earth orbit connectivity integration with terrestrial networks enables beyond-line-of-sight navigation for rural agricultural robotics.
- ANSSI cybersecurity certification:Critical infrastructure autonomous system approvals create preferential positioning for vendors meeting national sovereignty standards.
Industry Challenges
- Sensor fusion engineering scarcity:Kalman-filtered GPS inertial coupling expertise concentrates in defense-aerospace hybrids, constraining commercial robotics hiring pipelines.
- Multi-domain certification complexity:ANSM medical device navigation standards, ANSSI cybersecurity mandates, and EU AI Act documentation requirements impose overlapping compliance burdens.
- Legacy platform integration friction:Retrofitting autonomous navigation onto existing naval and industrial vehicle fleets demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Autonomous Navigation Market |
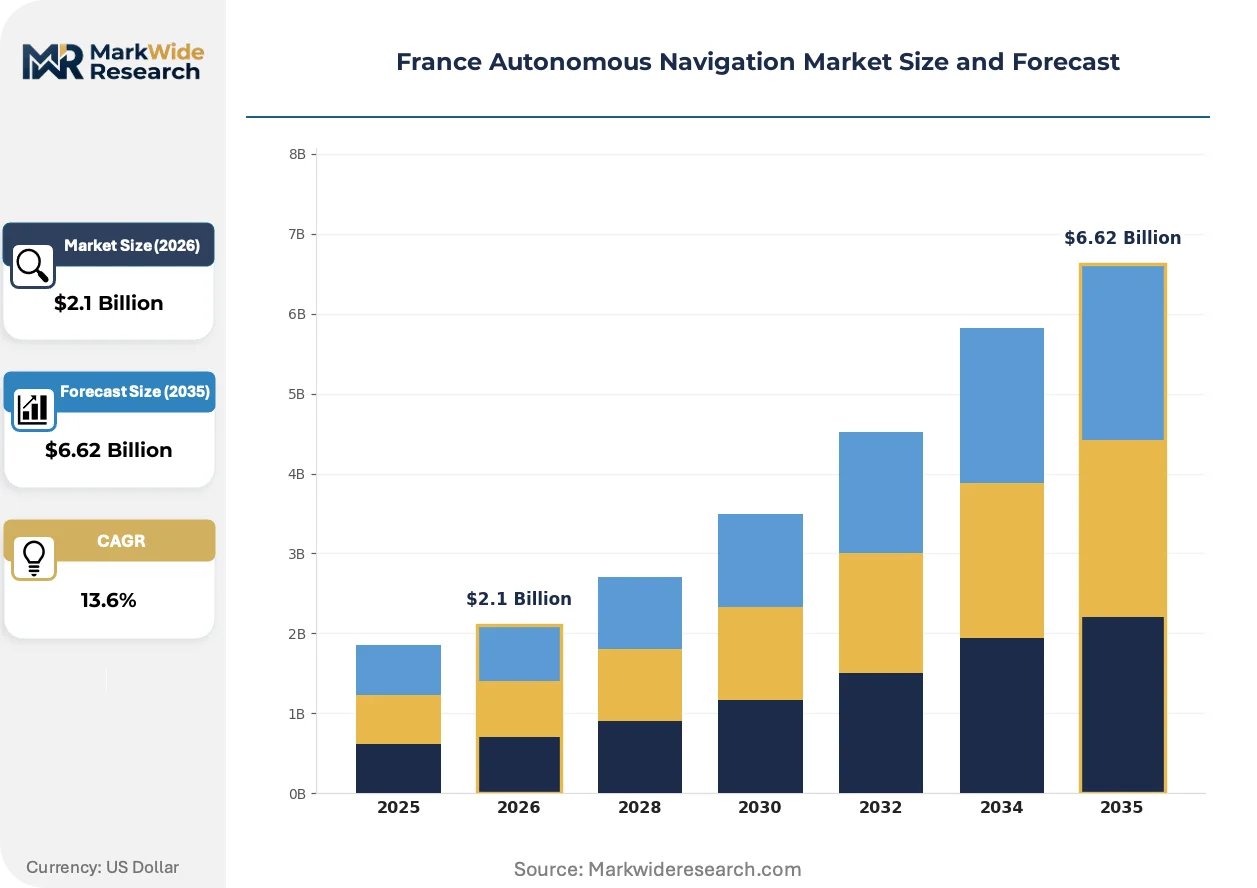
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.62 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lidar, Radar, Computer Vision, GPS Application: Marine, Automotive, Aerial, Robotics End User: Transportation, Defense, Agriculture, Logistics Deployment: On-Premise, Hybrid, Cloud, Edge |
| Companies Covered | Safran, Thales, ABB, BAE Systems, Elbit Systems, L3Harris Technologies, Moog, Northrop Grumman Corporation, Valeo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Autonomous Navigation Market Trends and Innovations
Algorithmic transparency mandates and compute-at-the-edge architectures are reconfiguring how French autonomy developers architect decision systems and hardware stacks.
Photonic integrated circuits for lidar signal processing are miniaturizing optical beam-steering modules to palm-scale formats. French maritime autonomy vendors adopt these compact sensors for unmanned surface vessels operating in cluttered port environments. The technology is miniaturizing perception hardware sufficiently to displace mechanical spinning assemblies in cost-sensitive inspection robotics.
France's national AI strategy implementation guidelines now require explicable decision pathways for high-risk autonomous systems deployed in public infrastructure. Industrial consequence includes mandatory training data documentation and model validation protocols that extend vendor onboarding timelines. Naval and medical navigation applications face the steepest compliance ramps, with ANSM and defense procurement agencies embedding these requirements into tender specifications.
Outcome-based contracting is displacing traditional equipment purchase models in offshore energy and logistics verticals. Autonomy providers now retain fleet ownership while selling inspection-hours or delivery-completions, transferring operational risk from end-users to technology vendors. This shift concentrates most visibly in Atlantic offshore wind zones and Rhône-Alpes automated warehouse corridors.
France Autonomous Navigation Market Segmentation
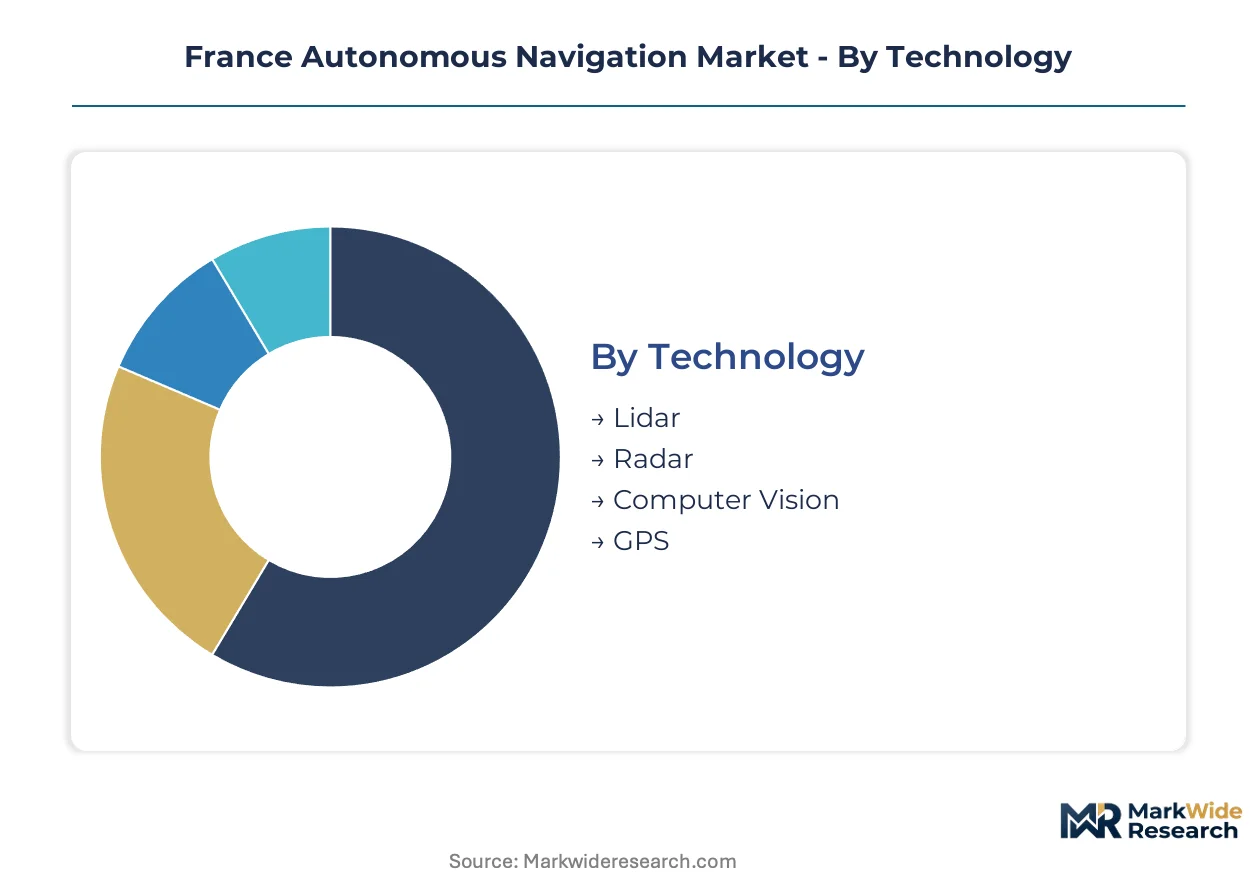
Segmentation in the France Autonomous Navigation Market reveals how procurement concentration around Toulouse aerospace and Atlantic offshore zones creates divergent technology requirements across domains. Each dimension carries distinct regulatory footprints from ANSSI cybersecurity mandates to EU AI Act documentation standards.
Technology:
Domestic demand clusters around defense-aerospace hybrids in Toulouse and maritime integrators in Brest, while export-oriented segments serve NATO interoperability requirements.
- Lidar:Optical beam-steering modules achieve palm-scale miniaturization through photonic integrated circuits. Defense-grade multi-sensor redundancy requirements in naval programs sustain elevated procurement volumes around Brest and Cherbourg despite commercial cost-down pressures.
- Computer Vision:Deep learning architectures process camera feeds for real-time obstacle classification. Logistics robotics in Rhône-Alpes automated warehouses and agricultural autonomy in Burgundy drive adoption as algorithmic transparency mandates under EU AI Act reshape vendor qualification.
- Radar:Millimeter-wave frequency modulated continuous wave systems penetrate adverse weather conditions for maritime navigation.
- GPS:Kalman-filtered inertial coupling delivers sub-meter accuracy for aerial platforms.
Lidar holds the largest share; momentum sits with Computer Vision.
Application:
Cost tier stratification separates defense-funded development cycles from commercial robotics operating on compressed payback timelines.
- Marine:Unmanned surface vessels integrate compact lidar with satellite connectivity for beyond-line-of-sight operations. North Sea and Atlantic offshore wind installations generate contract concentration around Brest and Saint-Nazaire for subsea cable inspection missions.
- Aerial:Fixed-wing and rotary platforms deploy multi-sensor fusion for autonomous flight path generation. Toulouse engineering density accelerates prototyping cycles for military and civilian drone applications under dual-use export control frameworks.
- Automotive:Robotaxi trials extend existing ADAS supply relationships into urban mobility pilots.
- Robotics:Ground-based platforms navigate warehouse corridors and agricultural fields with vision-centric perception stacks.
Marine applications dominate near-term contract value; aerial systems climb the fastest on R&D intensity.
End User:
Volume concentration maps directly to sovereign procurement priorities versus commercial automation adoption curves.
- Defense:Naval modernization programs compress development cycles for autonomous maritime patrol capabilities. French defense procurement agencies embed EU AI Act documentation requirements and ANSSI cybersecurity standards into tender specifications for unmanned systems.
- Logistics:Automated warehouse corridors in Rhône-Alpes and Île-de-France deploy ground robotics for inventory movement. Outcome-based contracting models transfer operational risk from end-users to technology vendors through inspection-hours or delivery-completion pricing.
- Transportation:Urban mobility pilots and intermodal freight routing integrate autonomous navigation for congestion reduction.
- Agriculture:Rural robotics leverage 5G-Advanced and low-earth orbit convergence for connectivity in dispersed farming regions.
Defense commands the largest procurement envelope; logistics gains share fastest on outcome-based model adoption.
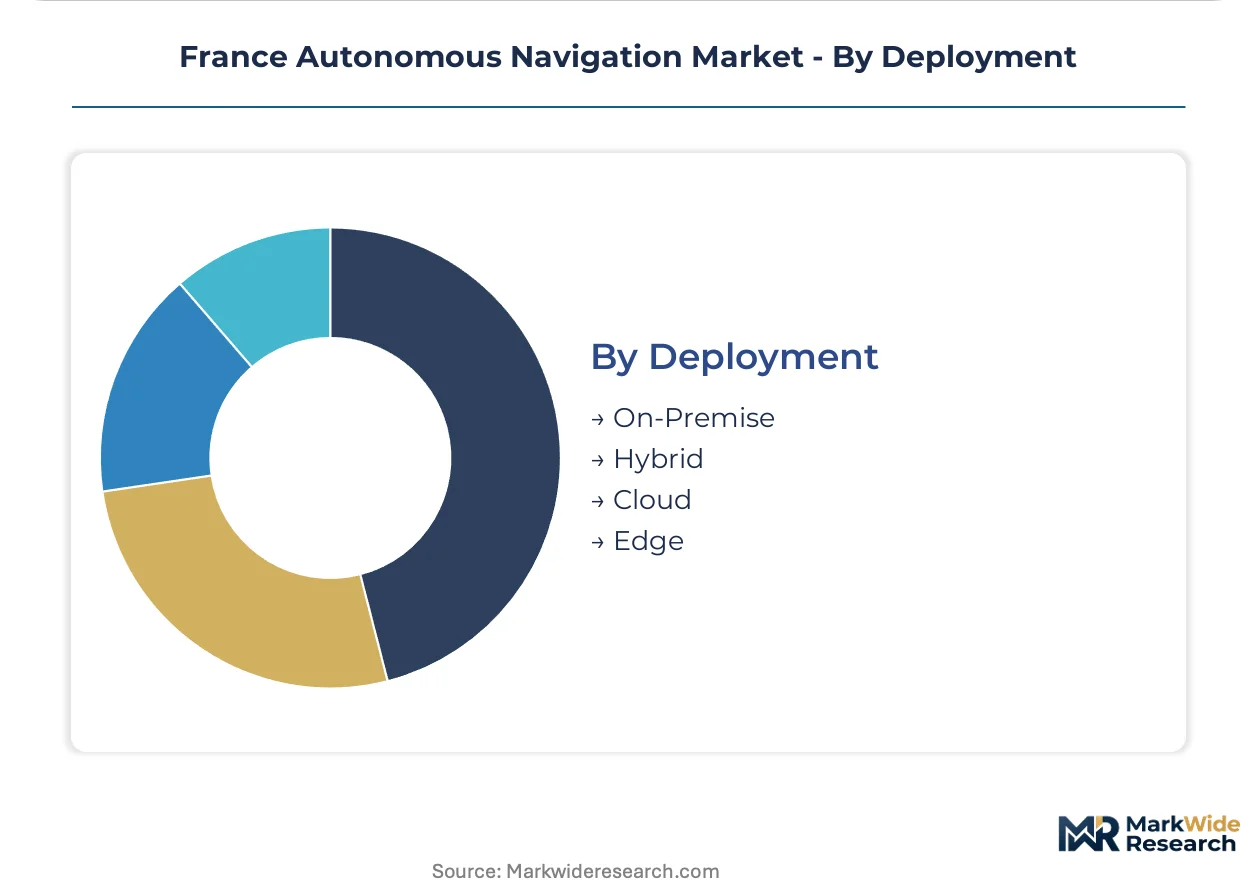
Deployment:
Latency requirements for collision-avoidance loops drive architectural shifts away from cloud dependency toward localized compute.
- Edge:GPU and specialized inference chips process sensor fusion onboard vehicles with sub-100 millisecond response thresholds. Supply chain concentration in East Asian foundries exposes French system integrators to geopolitical friction for critical hardware procurement.
- Hybrid:Partitioned architectures route non-time-critical analytics to cloud infrastructure while retaining safety-critical loops locally. ANSSI certification pathways for critical infrastructure create preferential positioning for vendors meeting national sovereignty standards.
- On-Premise:Fully localized server installations serve classified defense applications with air-gapped operational security.
- Cloud:Centralized processing persists in simulation and training environments with relaxed latency constraints.
Edge deployment captures the largest share; hybrid configurations expand most quickly on sovereignty-compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France commands pricing premiums over Occitanie for autonomous navigation engineering talent, reflecting the concentration of defense procurement agencies and AI research institutes in the Paris basin. This asymmetry shapes vendor location decisions and contract award patterns across French sub-regions.
Île-de-France
Defense procurement agencies and ANSSI headquarters drive demand for cybersecurity-certified autonomous systems. EU AI Act documentation requirements flow through Paris-based certification bodies, extending vendor onboarding timelines. The Paris-Saclay robotics corridor anchors ground-based logistics autonomy commercialization, with research-to-market pipelines accelerating warehouse robotics deployment.
Occitanie
Toulouse aerospace heritage concentrates aerial autonomy R&D and sensor integration engineering. France's national AI strategy implementation guidelines shape dual-use export control frameworks for drone applications. Airbus legacy facilities and Safran engineering bases sustain prototyping cycles for military and civilian unmanned platforms.
Bretagne
Naval modernization programs generate unmanned surface vessel contracts for Atlantic offshore operations. ANSSI cybersecurity mandates embed into defense tender specifications for maritime patrol capabilities. Brest and Saint-Nazaire cluster subsea cable inspection missions for North Sea and Atlantic offshore wind installations.
Auvergne-Rhône-Alpes
Automated warehouse corridors drive ground robotics demand for inventory movement and fulfillment optimization. Outcome-based contracting models transfer operational risk to technology vendors through delivery-completion pricing. Lyon and Grenoble engineering pools support vision-centric perception stack development for logistics applications.
Provence-Alpes-Côte d'Azur
Maritime autonomy testing infrastructure supports unmanned surface vessel validation in Mediterranean port environments. CE marking electromagnetic compatibility requirements extend fleet certification timelines for multi-vehicle convoys. Marseille and Toulon naval bases concentrate defense-grade autonomous maritime system integration.
France Autonomous Navigation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where defense-aerospace hybrids command premium positioning against automotive-tier suppliers. The vendor base concentrates around Toulouse engineering heritage and Paris-Saclay research corridors, with capability scarcity in sensor fusion engineering reinforcing incumbent advantages. Two strategic archetypes dominate: vertically integrated defense contractors with multi-domain certification expertise, and automotive-grade suppliers leveraging ADAS scale economies into adjacent robotics segments. Competitive moves center on strategic partnerships for algorithmic transparency compliance and geographic expansion into Atlantic offshore energy zones.
Among France-based defense-aerospace specialists, Safran and Thales occupy archetypal positions at the technology leadership tier, with Thales anchoring naval autonomous navigation programs through sensor fusion heritage and Safran sustaining aerial platform R&D intensity from its Toulouse engineering base. Valeo represents the automotive-tier archetype, competing in perception stacks and extending ADAS supply relationships into robotaxi trials.
| Leading Market Players |
|---|
| Safran |
| Thales |
| ABB |
| BAE Systems |
| Elbit Systems |
| L3Harris Technologies |
| Moog |
| Northrop Grumman Corporation |
| Valeo |
| Others |
Pricing and Supply Chain Analysis
Ninety-to-one-hundred-day GPU lead times from East Asian foundries concentrate hardware procurement power among defense-aerospace integrators with sovereign priority status, compressing margins for commercial robotics vendors competing for constrained edge-compute inventory.
Pricing Analysis
Île-de-France engineering talent commands thirty-to-fifty-percent premiums over Occitanie for equivalent sensor fusion expertise, stratifying vendor cost structures across regional clusters. Three-tier pricing structure across defense-certified, industrial-grade, and commercial-economy levels separates procurement envelopes, with ANSSI cybersecurity certification and EU AI Act documentation compliance functioning as the primary price differentiation drivers. Cost compression in commercial logistics robotics is intensifying because photonic integrated circuit miniaturization is displacing mechanical lidar assemblies. Defense procurement agencies exhibit the lowest price sensitivity, while agricultural automation startups in Burgundy face acute margin pressure from connectivity hardware costs.
Supply Chain Analysis
Extended electromagnetic compatibility testing timelines stretch component inventory cycles for multi-vehicle fleet deployments, forcing working capital commitments ahead of revenue recognition. Specialized inference chip supply concentrates in Taiwan, South Korea, and China, with photonic integrated circuits and millimeter-wave radar modules drawing from German and Japanese precision optics manufacturers. Single-source vulnerability in GPU foundry capacity exposes French system integrators to geopolitical supply friction. Distribution runs through defense procurement agencies for naval programs, direct OEM relationships for aerospace applications, and systems integrator consortia for logistics robotics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Autonomous Navigation Market functions as a high-growth disruption where EU AI Act algorithmic transparency mandates are forcing vendor consolidation around certified documentation capabilities, eliminating speculative R&D players from procurement pipelines.
For Market Incumbents: Compound sensor fusion engineering advantages by acquiring Paris-Saclay robotics corridor startups before EU AI Act certification windows close, anchoring naval and medical navigation tender qualifications. Deepen backward integration into photonic integrated circuit packaging to offset East Asian foundry concentration risk. Lock in Atlantic offshore wind inspection contracts through outcome-based fleet ownership models that transfer operational risk from energy operators. For New Entrants and Emerging Players: Agricultural autonomy connectivity gaps in rural Burgundy and Auvergne present white-space targets where 5G-Advanced and low-earth orbit convergence remains underexploited relative to maritime and aerial segments. Target ground-based logistics autonomy in Rhône-Alpes automated warehouse corridors where vision-centric perception stacks are displacing lidar-dependent incumbents on cost grounds. Pursue ANSSI cybersecurity pre-certification as a go-to-market angle for critical infrastructure positioning. For Investors and Strategic Acquirers: Long-term, this sits as a sovereign-capability play because French defense procurement preferences and NATO interoperability requirements will sustain premium procurement envelopes for domestic vendors regardless of commercial robotics cyclicality. Acquisition target archetype: mid-tier sensor fusion engineering shops with existing ANSM or defense agency relationships. Watch EU AI Act enforcement patterns as the inflection indicator for vendor qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| ANSSI Cybersecurity Pre-Certification | Creates preferential positioning for critical infrastructure autonomous system tenders in Île-de-France defense corridors. |
| Photonic Integrated Circuit Backward Integration | Captures palm-scale lidar miniaturization cost advantages for cluttered port environment deployments. |
| Paris-Saclay Robotics Corridor Acquisition | Secures Kalman-filtered GPS inertial coupling talent before EU AI Act documentation requirements reshape hiring pipelines. |
| Outcome-Based Fleet Ownership Model | Transfers operational risk from Atlantic offshore wind operators to autonomy vendors through inspection-hour pricing. |
| 5G-Advanced Satellite Convergence Partnership | Enables beyond-line-of-sight navigation for rural agricultural robotics in Burgundy connectivity gaps. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with autonomy program directors at French defense procurement agencies, sensor fusion engineering leads at Toulouse aerospace clusters, and logistics robotics procurement managers at Rhône-Alpes warehouse operators; and secondary validation through EU AI Act implementation guidelines, ANSSI cybersecurity certification protocols, CE marking electromagnetic compatibility directives, and Atlantic offshore wind development permits. Bottom-up segment sizing triangulated against top-down defense budget allocation patterns.
Across the projection horizon, the analytical framework modeled technology adoption curves by application dimension, deployment architecture latency requirements, and end-user procurement envelope concentration. CAGRs were derived from segment-level demand build-ups incorporating naval modernization program timelines, outcome-based contracting penetration rates, and edge-compute hardware availability constraints. Forecast inputs included photonic integrated circuit cost-down trajectories and EU AI Act documentation compliance burden estimates.
Underlying assumptions cover sustained French defense procurement priority for sovereign autonomy capabilities, with deviation risk concentrated in East Asian foundry supply disruptions or accelerated EU AI Act enforcement timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Driverless Taxi Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Self-Driving Truck Market