
 India Autonomous Navigation Market | 2026-2036
India Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
India Autonomous Navigation Market Insights
SAE Level 4 autonomy specifications is reorganizing competitive priorities among Indian and multinational developers. Tata Motors leverages its domestic manufacturing scale to anchor fleet trials for autonomous commercial vehicles. Mahindra & Mahindra sustains agricultural autonomy leadership through its precision farming equipment division. Mobileye competes by supplying computer vision systems to Indian OEMs seeking ADAS integration without full-stack development.
Autonomous navigation denotes self-directed platform positioning using fused sensor inputs, real-time path planning algorithms, and georeferenced decision logic operating without continuous human intervention. Systems integrate LiDAR point clouds, radar returns, and GPS-IMU corrections to achieve sub-meter localization accuracy across dynamic terrains. The technology serves commercial transportation, defense reconnaissance, and precision agriculture applications requiring reduced operator burden. Computer vision dominates technology investment due to declining camera costs and improving edge-processing throughput. Mapping Solutions command sustained revenue within the solution layer as high-definition spatial data becomes a recurring subscription asset. Fleet Operators represent the fastest-growing end user category as logistics consolidation drives automation economics.
The Ministry of Road Transport and Highways governs autonomous vehicle testing permits, while BIS develops localization performance standards for navigation hardware. CEA certification requirements for telecom-linked autonomous systems shape product design cycles and import compliance costs. Stakeholders must monitor regulatory clarity on liability frameworks before committing capital to passenger-grade deployment at scale.
Market Dynamics
Defense procurement acceleration from the Indian Armed Forces is restructuring capital allocation across unmanned systems developers, while the Ministry of Road Transport and Highways draft guidelines create parallel commercial testing corridors that split R&D investment between military-grade ruggedization and civilian cost optimization.
Growth Catalysts
- PLI scheme incentives:Production-linked incentives for advanced automotive technology are channeling domestic manufacturing investment toward sensor module assembly and edge-computing hardware for autonomous platforms.
- Precision agriculture mechanization:Farm consolidation in Punjab and Haryana is generating equipment replacement cycles that favor GPS-guided tractors and autonomous harvesters over conventional operator-dependent machinery.
- Karnataka technology cluster density:Bengaluru's concentrated startup formation and R&D facilities are creating talent pools and supplier networks that reduce development cycle times for navigation software stacks.
Market Restraints
- LiDAR import dependency:High-specification optical ranging modules rely on concentrated East Asian supply sources, exposing domestic integrators to input cost volatility and customs clearance friction.
- CEA certification timelines:Telecom-linked autonomous systems face extended type-approval procedures that compress product launch windows and elevate compliance overhead for hardware developers.
- HD mapping infrastructure gaps:Sub-meter accuracy navigation requires georeferenced road databases that remain incomplete beyond major highway corridors and technology district perimeters.
Strategic Opportunities
- Tamil Nadu automotive corridor penetration:Chennai's OEM supplier ecosystem offers underutilized manufacturing capacity for sensor fusion hardware targeting commercial vehicle retrofits.
- BIS localization standards development:Pending performance benchmarks for navigation hardware create first-mover advantages for domestic firms participating in technical committee consultations.
- 5G-Edge convergence:Integration of low-latency cellular networks with roadside unit computing enables cooperative perception architectures that reduce onboard sensor payload requirements.
Industry Challenges
- SLAM algorithm talent scarcity:Simultaneous localization and mapping expertise concentrates in defense research institutions, constraining commercial sector hiring pipelines.
- Legacy fleet integration complexity:Retrofitting autonomous navigation onto existing commercial vehicle CAN bus architectures requires proprietary protocol reverse-engineering that fragments solution providers.
- Field validation infrastructure:Controlled testing environments for edge-case scenario reproduction remain limited to defense establishments, delaying civilian system reliability certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Autonomous Navigation Market |
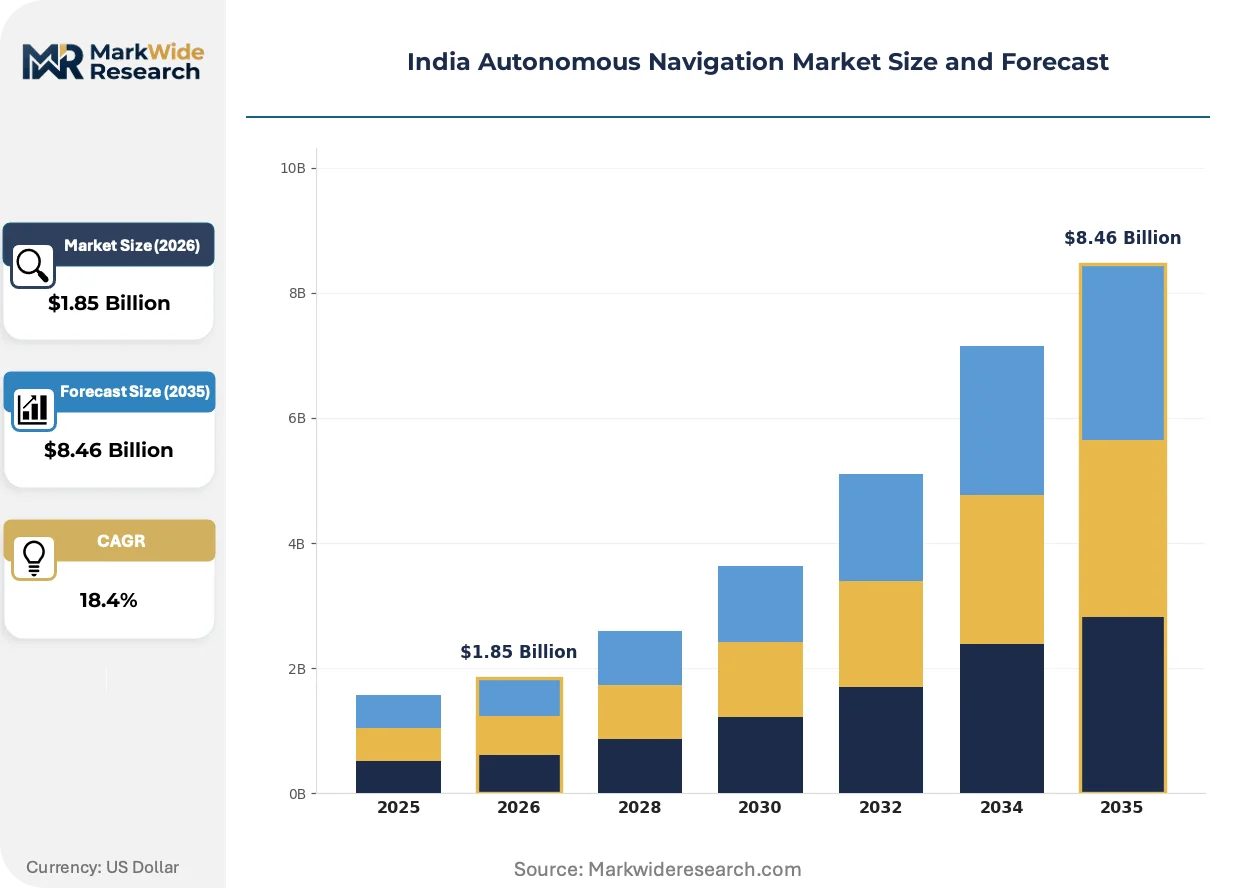
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Computer Vision, GPS, Radar Application: Transportation, Agriculture, Logistics, Military End User: OEMs, Fleet Operators, Government, Research Institutions Solution: Mapping Solutions, Autonomous Vehicles, Navigation Systems, Control Software |
| Companies Covered | Waymo, Tesla, Baidu, Tata Motors, Mahindra & Mahindra, L3Harris Technologies, Mobileye, Aurora Innovation, DeepRoute.ai, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Autonomous Navigation Market Trends and Innovations
Software-defined architectures are fragmenting traditional hardware-integrated navigation stacks, enabling modular upgrades that decouple sensor procurement from algorithm licensing and compress replacement cycles across defense and commercial fleets.
Computer vision is decomposing the dominance of multi-sensor fusion approaches in cost-sensitive commercial applications. Logistics fleet operators in Gujarat and Maharashtra are adopting camera-primary perception systems for highway corridor operations, reducing unit economics to levels that justify automation at medium fleet scales. This decomposition is compressing LiDAR vendor margins and forcing component suppliers toward defense-exclusive positioning or dramatic cost-down roadmaps.
Draft guidelines from the Ministry of Road Transport and Highways are mandating structured testing permit frameworks that partition autonomous vehicle development into corridor-specific phases. The industrial consequence is a geographic concentration of validation activity along the Delhi-Mumbai and Bengaluru-Chennai expressways, where infrastructure readiness permits progressive autonomy level escalation. Passenger-grade developers are responding by anchoring pilot programs to these designated corridors rather than pursuing nationwide deployment readiness.
Logistics procurement committees are compressing vendor qualification timelines and unbundling hardware acquisition from software subscription agreements. Third-party fleet management platforms are displacing OEM-captive service contracts in the commercial vehicle segment, particularly among mid-scale operators in Karnataka and Telangana consolidating under shared technology service providers. This behavioral shift is most visible in the e-commerce fulfillment vertical, where delivery density justifies dedicated autonomous last-mile pilot programs.
India Autonomous Navigation Market Segmentation
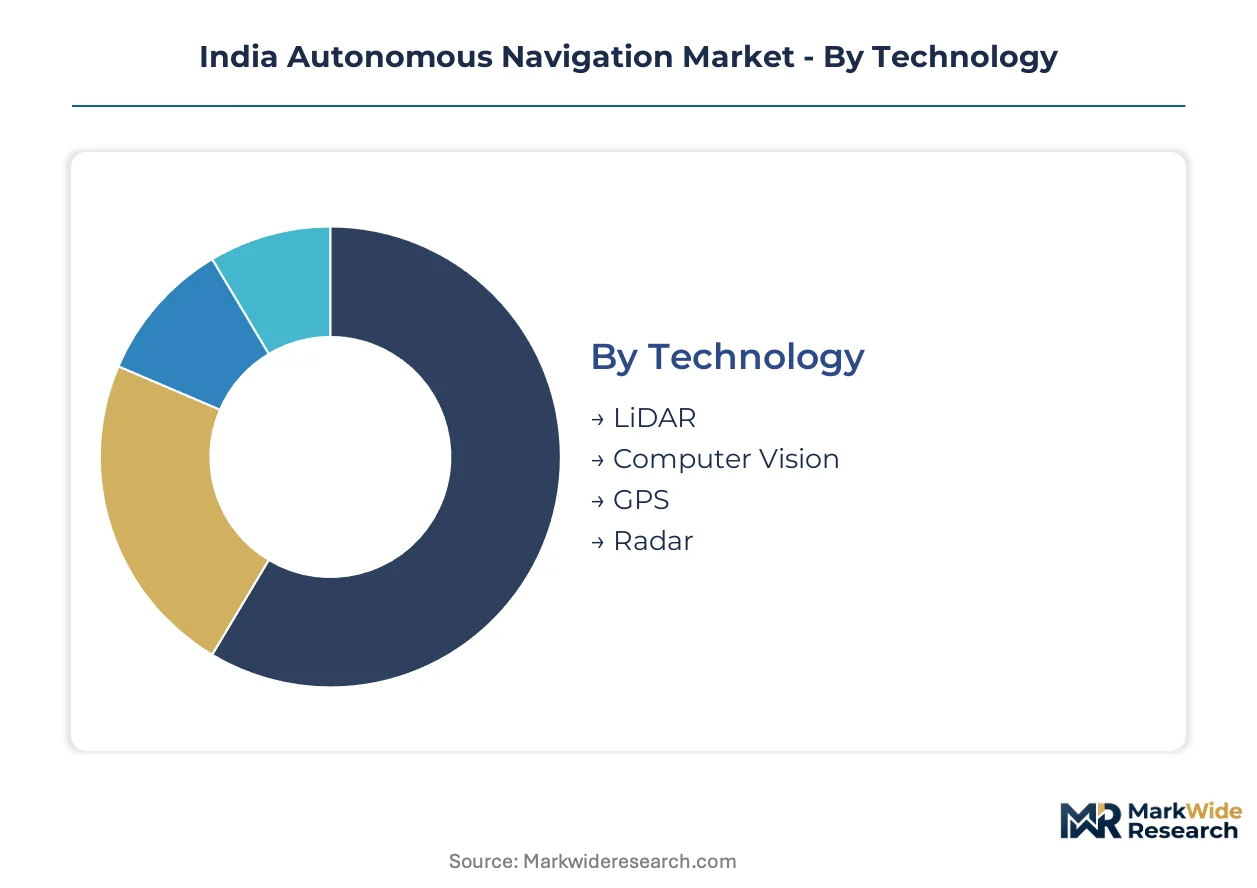
Segmentation reveals how autonomous navigation demand fragments across technology readiness levels and procurement authority structures in India. Defense and commercial applications operate on divergent hardware specifications and certification timelines, creating distinct supplier ecosystems.
Technology:
Domestic R&D concentrates on computer vision and GPS-IMU fusion for cost-sensitive commercial deployment, while LiDAR and high-specification radar modules remain import-dependent for defense-grade applications.
- Computer Vision:Camera-primary perception systems leverage declining sensor costs and edge-processing advances. Fleet operators in Gujarat and Maharashtra deploy these for highway corridor logistics, prioritizing unit economics over multi-sensor redundancy.
- LiDAR:Optical ranging modules generate dense point clouds for sub-meter localization accuracy. Defense procurement from the Indian Armed Forces absorbs high-unit-cost production, insulating domestic integrators from commercial price pressure.
- GPS:Satellite-based positioning with IMU correction provides foundational localization for agricultural autonomy. Punjab and Haryana farm consolidation drives replacement demand for GPS-guided tractors.
- Radar:Radio-frequency ranging performs in adverse weather where optical systems degrade. Military unmanned ground vehicles specify ruggedized radar for reconnaissance missions across varied terrain.
Computer Vision commands the established base. The steepest expansion runs through GPS as precision agriculture mechanization accelerates.
Application:
Cost tier differentiation separates defense-grade ruggedization from civilian cost optimization, with logistics applications occupying a mid-tier hybrid position.
- Transportation:Autonomous passenger and commercial vehicle development anchors to Ministry of Road Transport and Highways designated testing corridors. The Delhi-Mumbai and Bengaluru-Chennai expressways concentrate validation infrastructure.
- Logistics:E-commerce fulfillment density justifies dedicated last-mile pilot programs. Mid-scale operators in Karnataka and Telangana consolidate under shared technology service providers.
- Agriculture:GPS-guided tractors and autonomous harvesters replace operator-dependent machinery. Farm consolidation in Punjab and Haryana generates equipment replacement cycles favoring automation.
- Military:Unmanned aerial and ground systems for reconnaissance and surveillance absorb premium-grade sensor payloads. Defense procurement acceleration is restructuring capital allocation across unmanned systems developers.
Transportation holds the largest committed investment base. Logistics is gaining share fastest as procurement committees compress vendor qualification timelines.
End User:
Volume concentration varies by customer type, with fleet operators consolidating fastest and research institutions providing talent pipelines constrained by SLAM algorithm scarcity.
- Fleet Operators:Third-party fleet management platforms displace OEM-captive service contracts. Shared technology service providers aggregate mid-scale operator demand in Karnataka and Telangana.
- OEMs:Domestic manufacturers anchor fleet trials for autonomous commercial vehicles. Manufacturing scale advantages support sensor module assembly and edge-computing hardware integration.
- Government:Defense procurement and civilian testing permit issuance shape market access. The Ministry of Road Transport and Highways governs autonomous vehicle testing permits.
- Research Institutions:Defense research establishments concentrate SLAM algorithm expertise, constraining commercial sector hiring pipelines for simultaneous localization and mapping talent.
OEMs retain the deepest integration relationships. Fleet Operators are climbing the fastest as logistics consolidation drives automation economics.
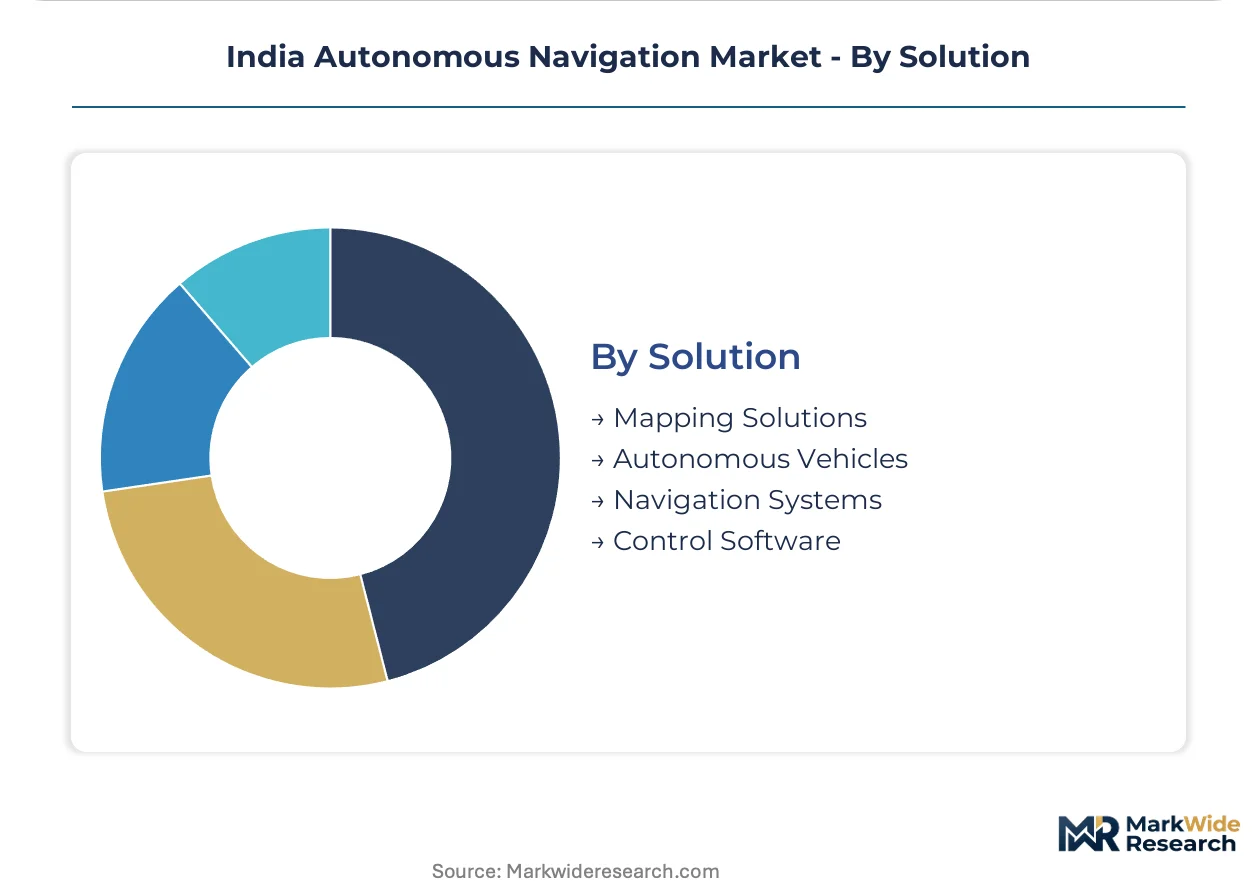
Solution:
Margin structure differentiates recurring subscription assets from one-time hardware sales, with mapping data commanding sustained revenue streams.
- Mapping Solutions:High-definition spatial data becomes a recurring subscription asset. Sub-meter accuracy requires georeferenced road databases that remain incomplete beyond major highway corridors.
- Navigation Systems:Integrated GPS-IMU hardware with sensor fusion software enables platform positioning. BIS localization performance standards for navigation hardware create first-mover advantages for domestic firms.
- Autonomous Vehicles:Self-directed platforms combine perception, planning, and control subsystems. SAE Level 4 autonomy specifications reorganize competitive priorities among Indian and multinational developers.
- Control Software:Real-time path planning algorithms and georeferenced decision logic operate without continuous human intervention. Software-defined architectures fragment traditional hardware-integrated navigation stacks.
Mapping Solutions anchor the recurring revenue base. Control Software is expanding most quickly as modular upgrades decouple sensor procurement from algorithm licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component assembly for autonomous navigation concentrates in southern and western industrial corridors, with sensor module manufacturing gravitating toward established automotive supplier ecosystems. State-level technology policies and defense procurement geography are redistributing R&D investment across the subcontinent.
Karnataka
Bengaluru's technology cluster hosts concentrated startup formation and R&D facilities for navigation software stacks. The state government's EV and mobility technology policies provide capital subsidies for autonomous vehicle testing infrastructure. Defense research establishments in the city concentrate SLAM algorithm expertise that constrains commercial sector hiring pipelines.
Tamil Nadu
Chennai's OEM supplier ecosystem offers underutilized manufacturing capacity for sensor fusion hardware targeting commercial vehicle retrofits. The state industrial development corporation has designated automotive technology parks with simplified environmental clearances for component testing. Sriperumbudur and Oragadam industrial belts are absorbing LiDAR module assembly investments from Tier-1 suppliers.
Maharashtra
Logistics fleet operators in Mumbai-Pune corridor are compressing vendor qualification timelines for autonomous trucking pilots. The state transport department has issued permits for platooning trials on the Mumbai-Nashik expressway. Chakan and Talegaon automotive clusters are integrating edge-computing hardware into existing commercial vehicle electronics supply chains.
Telangana
Mid-scale fleet operators in Hyderabad are consolidating under shared technology service providers for autonomous navigation subscriptions. T-Hub incubation programs channel venture capital toward localization algorithm developers. The Hyderabad automotive cluster is emerging as a secondary hub for GPS-IMU hardware integration outside Bengaluru's dominance.
Haryana and Punjab
Farm consolidation in these northern states generates equipment replacement cycles favoring GPS-guided tractors and autonomous harvesters. The Punjab Agricultural University collaborates with equipment manufacturers on precision farming validation protocols. Ambala and Ludhiana industrial zones host assembly operations for agricultural autonomy hardware serving the Indo-Gangetic plain.
India Autonomous Navigation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with full-stack autonomy developers competing against component specialists and fleet-service aggregators. The market structure is bifurcated between defense-grade system integrators absorbing premium sensor payloads and commercial vehicle retrofitters optimizing for unit economics. Three archetypes dominate: domestic automotive OEMs leveraging manufacturing scale, multinational perception technology licensors, and unmanned systems specialists serving defense procurement. Competitive dynamics center on strategic partnerships for sensor fusion development and geographic anchoring to designated testing corridors.
Among multinational technology providers, Waymo and Mobileye exemplify contrasting entry strategies for the Indian market, with the former representing capital-intensive full-stack deployment and the latter illustrating component-level ADAS integration partnerships. Domestic automotive manufacturers Tata Motors and Mahindra & Mahindra occupy positions as fleet trial anchors, leveraging existing commercial vehicle customer relationships to validate autonomous navigation at operational scale. Aurora Innovation represents the venture-backed full-stack developer archetype competing for defense and logistics procurement contracts.
| Leading Market Players |
|---|
| Waymo |
| Tesla |
| Baidu |
| Tata Motors |
| Mahindra & Mahindra |
| L3Harris Technologies |
| Mobileye |
| Aurora Innovation |
| DeepRoute.ai |
| Others |
Pricing and Supply Chain Analysis
Ninety-day LiDAR module lead times from East Asian suppliers compress Indian integrators' inventory turns and anchor pricing power with foreign component vendors, while domestic assembly operations absorb margin pressure through software licensing markups.
Pricing Analysis
CEA certification timelines for telecom-linked autonomous systems dictate the pricing tier structure across defense and commercial segments. Three-tier pricing structure across premium, standard, and economy levels separates military-grade ruggedized systems from civilian retrofit kits and agricultural guidance modules. Price differentiation centers on certification grade and after-sales service bundling. Cost compression in the commercial tier is intensifying because fleet operators unbundle hardware acquisition from software subscriptions. Mid-scale logistics operators in Karnataka and Telangana exhibit highest price sensitivity, while defense procurement committees prioritize performance specifications over unit economics.
Supply Chain Analysis
China and Taiwan anchor high-specification optical ranging module fabrication, while South Korea and Japan supply radar components and edge-processing semiconductors. Domestic assembly draws from concentrated East Asian inputs including LiDAR point-cloud generators, GPS-IMU correction chipsets, and ruggedized radar arrays. Single-source vulnerability in LiDAR supply exposes integrators to customs clearance friction and input cost volatility. Distribution runs through Tier-1 automotive suppliers in Chennai and Bengaluru, with sensor fusion hardware reaching fleet operators via OEM service networks and third-party technology service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in autonomous navigation are shifting toward interoperable software stacks that decouple sensor procurement from algorithm licensing, creating ecosystem leverage for middleware developers.
For Market Incumbents: Fortify defensive positions by deepening backward integration into edge-computing hardware assembly in Tamil Nadu's automotive corridors. Accelerate BIS certification investment for navigation hardware to capture first-mover advantages as localization standards crystallize. Counter the threat of software-defined architectures fragmenting hardware-integrated stacks by anchoring fleet trial relationships with binding multi-year service agreements.
For New Entrants and Emerging Players: HD mapping subscription gaps in tier-two highway corridors offer white-space entry points where incumbent coverage remains incomplete. Target precision agriculture retrofit markets in Punjab and Haryana, where farm consolidation outpaces OEM service capacity. Penetrate through cooperative perception pilots leveraging 5G-edge convergence to reduce onboard sensor payload requirements for mid-scale fleet operators.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense research establishments commercializing SLAM algorithm expertise. Long-term viability favors firms controlling recurring mapping data assets over hardware-dependent integrators. Watch for inflection signals in PLI scheme incentive disbursement rates, which indicate domestic manufacturing commitment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Hardware Localization | PLI scheme incentives channel capital toward domestic LiDAR module assembly in Tamil Nadu corridors. |
| Software-Defined Architecture Migration | Modular upgrades decouple sensor procurement from algorithm licensing across defense and commercial fleets. |
| 5G-Edge Cooperative Perception Deployment | Low-latency cellular integration reduces onboard payload requirements for highway corridor logistics operators. |
| HD Mapping Subscription Infrastructure | Georeferenced road databases become recurring revenue assets beyond major expressway perimeters. |
| Precision Agriculture Retrofit Partnerships | Farm consolidation in northern states generates equipment replacement cycles favoring GPS-guided autonomy. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with autonomous navigation stakeholders and secondary validation across regulatory and industry databases. Primary fieldwork engaged fleet operations directors at logistics consolidators in Karnataka and Telangana, platform engineers at domestic OEMs, procurement leads at defense unmanned systems integrators, and technical committee members at BIS standardization consultations. Secondary sources encompassed Ministry of Road Transport and Highways draft guideline releases, CEA type-approval procedural documentation, PLI scheme administrative filings, and vehicle production databases from IHS Markit. Bottom-up segment sizing triangulated against top-down macroeconomic anchoring.
Across the projection horizon, the analytical framework modeled technology adoption curves across computer vision, LiDAR, GPS-IMU fusion, and radar modalities. Segmentation dimensions included application verticals spanning transportation, logistics, agriculture, and military procurement, alongside solution layers from mapping subscriptions to control software licensing. CAGRs derived from fitted adoption curves calibrated to defense procurement acceleration timelines and commercial testing corridor permit issuance rates. Industry-specific inputs incorporated PLI incentive disbursement velocity and 5G infrastructure rollout schedules.
Material uncertainties — regulatory liability framework clarity, LiDAR import tariff trajectories, and SLAM algorithm talent migration from defense establishments — sit outside the modeled envelope. Forecasts reflect assumptions regarding corridor-specific testing permit expansion and precision agriculture mechanization continuation. Recalibration cycles align with material shifts in PLI scheme administrative guidance and BIS localization standard promulgation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Blind Spot Detection Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Automotive Adaptive Cruise Control Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Autonomous Navigation Sensing System Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market