
 Lung Cancer Surgery Market | 2026-2036
Lung Cancer Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Lung Cancer Surgery Market Intelligence
Demand from large-volume cancer treatment facilities is rotating away from traditional open surgeries toward minimally invasive procedures. Intuitive Surgical Inc. dominates the robotic-assisted surgery segment with its established platform. Medtronic Plc. competes with a diverse portfolio of surgical instruments and energy devices for both open and thoracoscopic procedures. Johnson & Johnson leverages its extensive hospital network to distribute its surgical staplers and advanced energy solutions.
Lung cancer surgery involves the physical removal of malignant tumors and surrounding lung tissue to achieve curative or palliative outcomes. The procedure requires precise dissection and resection to obtain clear pathological margins while preserving as much healthy lung function as possible. Video-Assisted Thoracoscopic Surgery (VATS) technology is displacing open thoracotomy due to reduced patient recovery times. Among procedure types, lobectomy remains the standard for most non-small cell lung cancer cases, while segmentectomy gains traction for smaller, peripheral tumors.
Medical device approvals from bodies like the US FDA, the European Medicines Agency under MDR, and China's NMPA govern market access for new surgical systems and instruments. These regulations mandate stringent clinical evidence for safety and efficacy, influencing device design and R&D timelines. Future competitive advantage will depend on integrating artificial intelligence for pre-operative planning and intra-operative guidance.
Market Dynamics
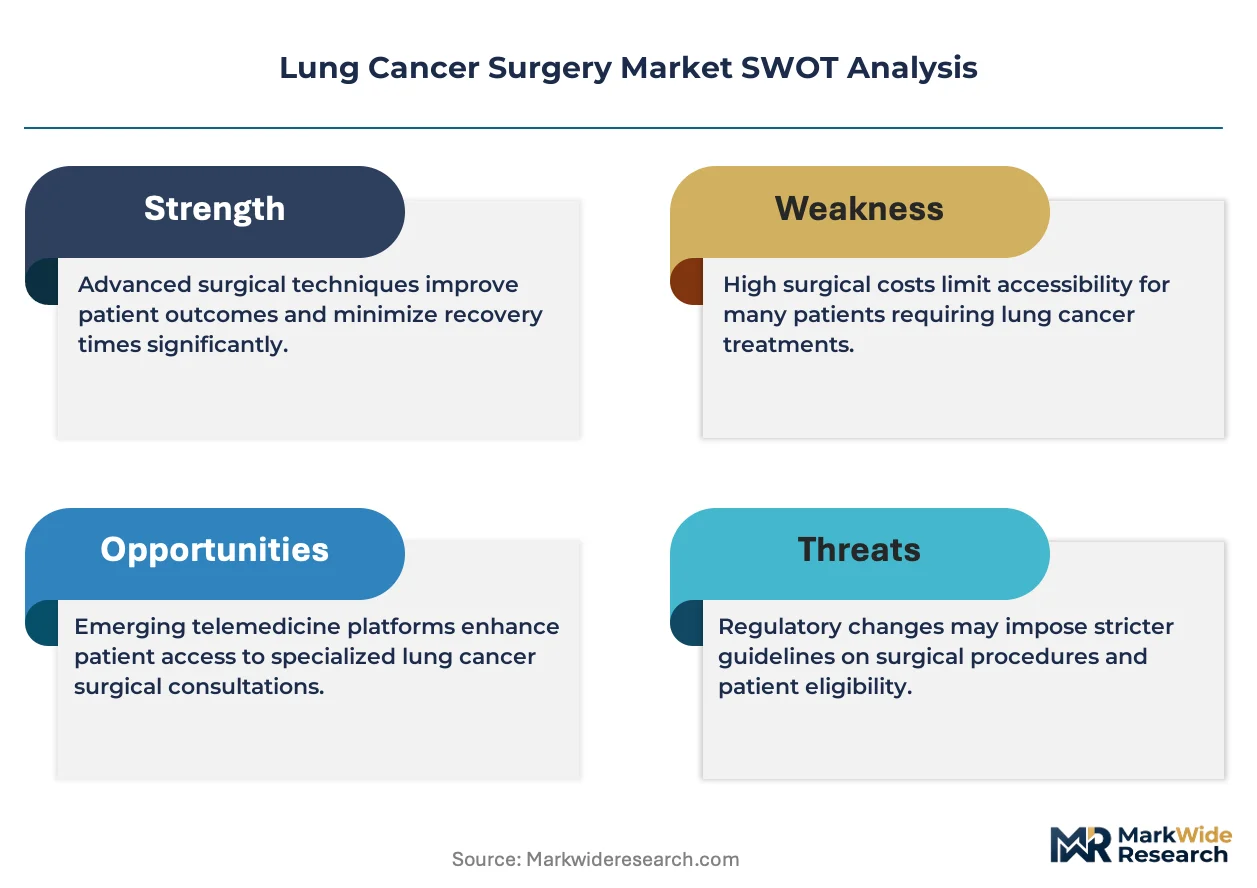
The central dynamic shaping the lung cancer surgery market is the technological and procedural shift away from traditional open thoracotomy. This rotation toward minimally invasive approaches, including both VATS and robotic-assisted platforms, is fundamentally altering surgical workflows, hospital investment priorities, and surgeon training requirements.
Growth Catalysts
- Advanced Surgical Platforms:The integration of artificial intelligence with robotic systems for pre-operative planning and augmented reality for intra-operative guidance improves surgical precision and patient outcomes, accelerating adoption in complex cancer cases.
- Demographic Shifts:Aging populations and expanded lung cancer screening programs in countries like Japan and the United States are increasing the detection of early-stage, surgically-resectable tumors, thereby expanding the eligible patient volume.
- Healthcare Infrastructure Investment:Government and private sector investment in new hospital construction and modernization, particularly in China, is creating new capacity for advanced surgical suites equipped for minimally invasive lung procedures.
Market Restraints
- High Capital Costs:The significant upfront investment required for robotic-assisted surgical systems and the associated instrumentation limits their adoption to large, well-funded hospitals, creating a barrier for smaller or regional medical centers.
- Specialized Training Requirements:A steep learning curve is associated with mastering robotic-assisted thoracoscopic surgery, leading to a shortage of proficient surgeons and constraining the pace of widespread adoption beyond specialized centers of excellence.
- Stringent Regulatory Hurdles:The rigorous clinical evidence mandates under regulations like the EU's MDR and the US FDA's premarket approval process extend R&D timelines and increase costs for new surgical systems and instruments.
Strategic Opportunities
- AI-Powered Surgical Intelligence:Developing software platforms that use artificial intelligence to analyze pre-operative scans and provide real-time intra-operative feedback presents a significant opportunity to enhance surgical decision-making and improve safety.
- Expansion in Emerging Markets:There is untapped potential in Latin American and Southeast Asian markets, where rising healthcare spending and an increasing incidence of lung cancer create demand for more accessible and cost-effective minimally invasive surgical solutions.
- Sub-Lobectomy Procedure Tools:As segmentectomy gains favor for smaller tumors, an opportunity exists to develop specialized instruments and energy devices optimized for the precise dissection and margin assessment required in lung-sparing resections.
Industry Challenges
- Surgical Skill Scarcity:A persistent shortage of surgeons and operating room staff proficient in advanced thoracoscopic and robotic-assisted techniques creates operational bottlenecks and limits procedure volume growth in many healthcare systems.
- System Interoperability:Hospitals face challenges integrating surgical robots, imaging systems, and digital health records from different vendors, as the lack of standardized data protocols complicates workflow efficiency and data analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lung Cancer Surgery Market |
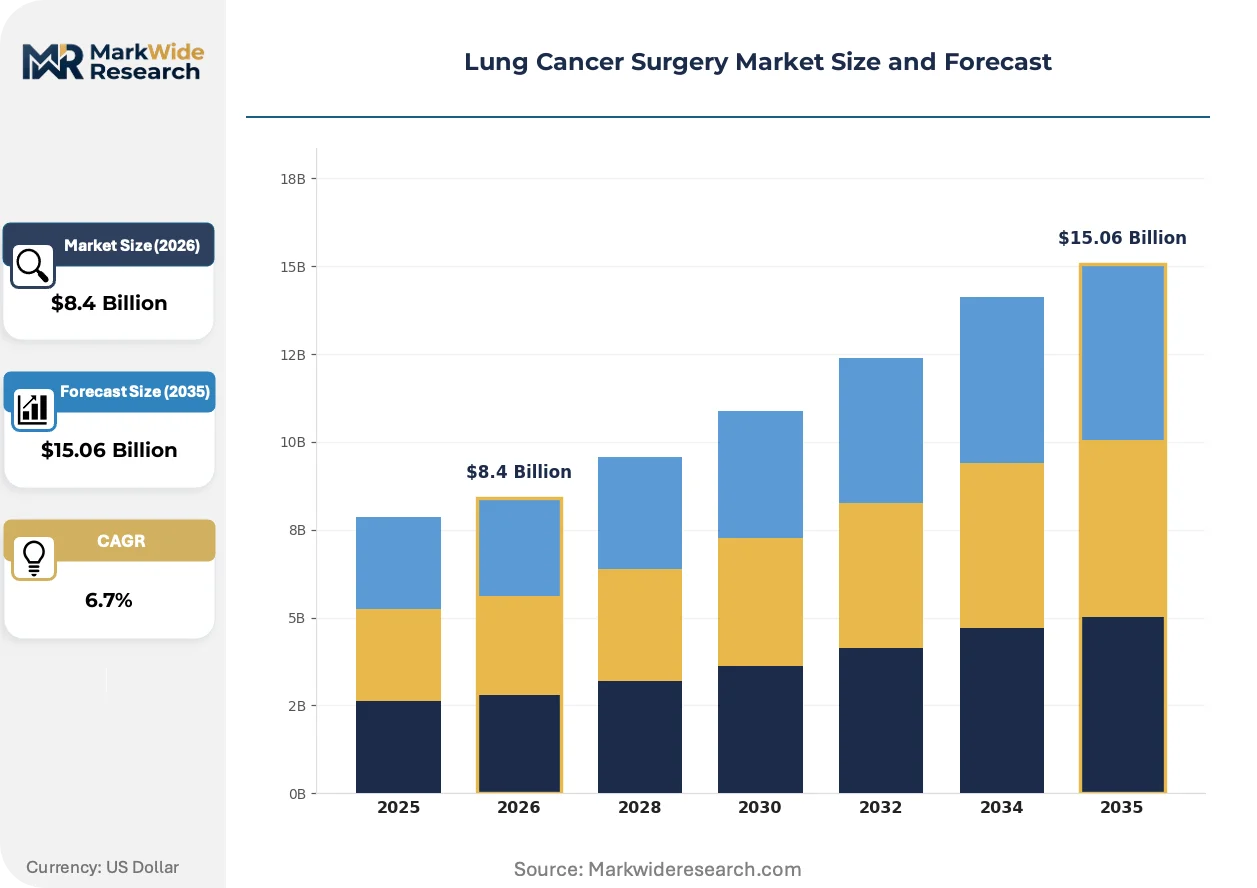
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Lobectomy, Pneumonectomy, Segmentectomy, Wedge Resection, Sleeve Resection Technology: Video-Assisted Thoracoscopic Surgery, Robotic-Assisted Surgery, Open Thoracotomy, Endoscopic Surgery, Laser Surgery Application: Non-Small Cell Lung Cancer, Small Cell Lung Cancer, Early Stage Lung Cancer, Advanced Stage Lung Cancer, Recurrent Lung Cancer End User: Specialty Clinics, Academic Medical Centers, Cancer Treatment Facilities, Community Hospitals, Surgical Centers |
| Companies Covered | Johnson & Johnson, Intuitive Surgical Inc., Medtronic Plc., Stryker Corporation, Olympus Corporation, Siemens Healthineers AG, GE Healthcare, Accuray Incorporated, KARL STORZ SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lung Cancer Surgery Market Strategic Shifts & Innovations
The market's evolution is defined by a convergence of data-driven surgical planning and less invasive procedural technologies. This combination is actively reshaping expectations for patient recovery and long-term outcomes, pushing device innovation toward greater precision and intelligence.
Robotic-assisted surgery platforms provide surgeons with enhanced dexterity, 3D visualization, and tremor filtration for complex procedures. Academic Medical Centers and high-volume cancer hospitals are rapidly adopting these systems for lobectomies and segmentectomies. This technology is bifurcating the market between centers capable of high-cost, high-precision robotic procedures and those relying on conventional VATS or open surgery.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on all medical devices. This regulation increases the compliance burden and development timelines for manufacturers of surgical instruments and systems seeking CE marking. The advanced energy device and surgical stapler segments are particularly affected, forcing reinvestment in clinical studies to maintain market access in Europe.
Hospital purchasing decisions are shifting from a focus on individual device costs to an evaluation of the total procedural cost and associated patient outcomes. This value-based approach disrupts traditional sales models, favoring suppliers who can demonstrate that their technology reduces recovery times and complication rates. This procurement model is most visible within integrated healthcare networks in the United States and public health systems in Western Europe.
Lung Cancer Surgery Market Segmentation
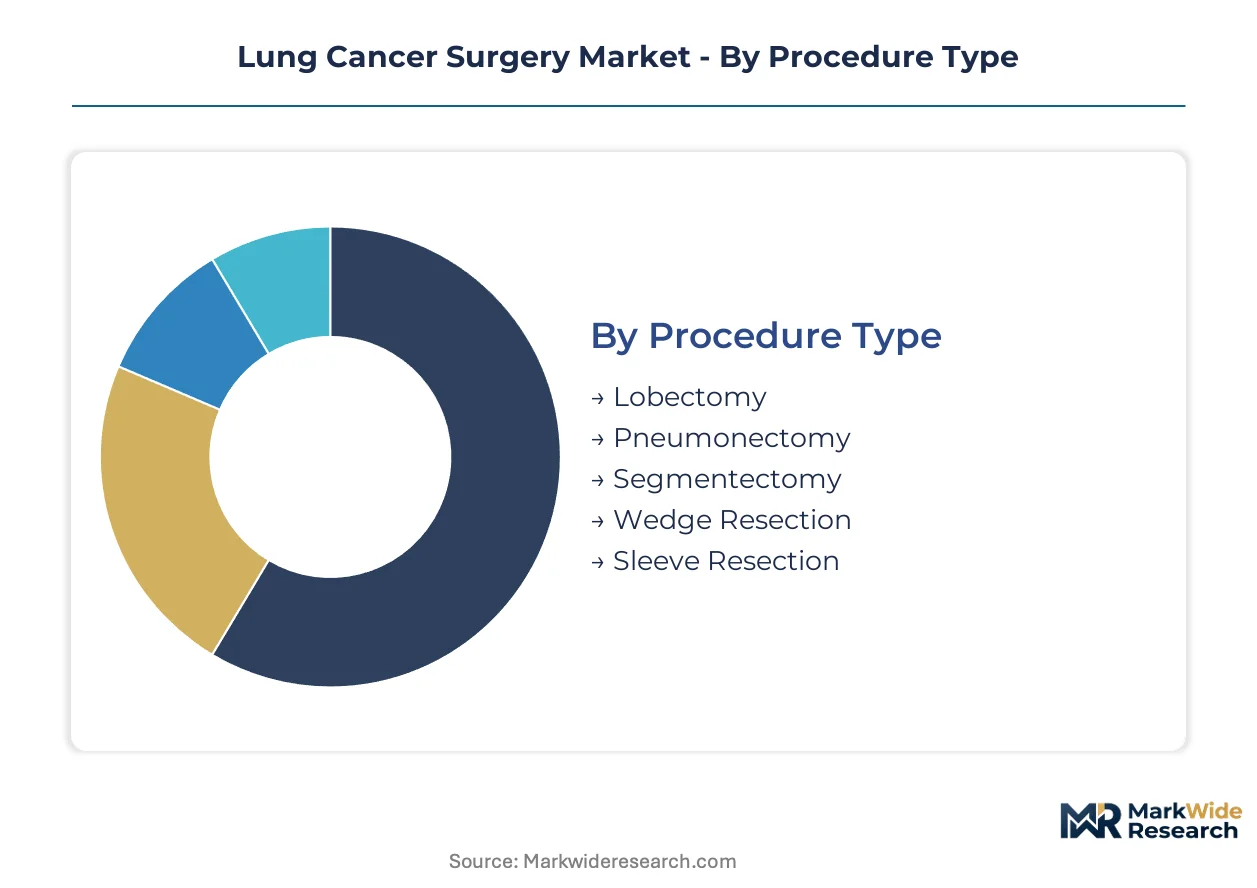
The lung cancer surgery market segments reflect diverse clinical needs and technological advancements. Understanding these segments allows precise analysis of surgical technique adoption, device innovation, and patient care pathways. Market dynamics vary by procedure type, enabling targeted planning.
Procedure Type:
The geographic distribution of surgical procedure types shows distinct preferences, with some techniques dominating established systems while others gain traction in emerging markets.
- Lobectomy:This procedure removes an entire lung lobe, typically for non-small cell lung cancer to achieve clear margins. Demand concentrates in the United States and Western Europe, driven by established protocols.
- Segmentectomy:This lung-sparing resection removes a specific anatomical segment of a lung lobe, preserving more healthy tissue. Demand expands in Japan and South Korea, where early detection identifies smaller tumors.
- Pneumonectomy:Pneumonectomy involves removing an entire lung, reserved for extensive tumors or central airway involvement.
- Wedge Resection:This procedure excises a small, wedge-shaped portion of lung tissue, used for diagnosis or very small lesions.
- Sleeve Resection:Sleeve resection removes a section of a main bronchus and surrounding lung tissue, then reconnects the remaining bronchus.
Lobectomy commands the established base. The steepest expansion runs through Segmentectomy.
Technology:
The cost tier associated with surgical technologies influences adoption, with high capital investment required for robotic platforms and lower costs for conventional approaches.
- Robotic-Assisted Surgery:These platforms provide surgeons enhanced dexterity, 3D visualization, and tremor filtration for complex dissections. Demand concentrates in academic medical centers in the United States and Germany.
- Video-Assisted Thoracoscopic Surgery:VATS uses small incisions and a video camera for lung resections, offering a less invasive alternative. Demand expands across China and India, supported by hospital investments in minimally invasive capabilities.
- Open Thoracotomy:This traditional approach involves a large incision to access the lung directly, used for very complex or extensive cases.
- Endoscopic Surgery:Endoscopic techniques involve inserting a flexible tube with a camera and instruments, primarily for diagnostic procedures.
- Laser Surgery:Laser technology is occasionally used for precise tissue ablation in specific lung cancer applications, particularly for metastatic lesions.
High capital expenditure defines one end of the technology spectrum, while cost-efficiency and broader accessibility drive demand at the other.
Application:
The volume of surgical interventions varies across different lung cancer applications, reflecting disease prevalence and treatment efficacy for specific tumor types.
- Non-Small Cell Lung Cancer:NSCLC is the most common lung cancer, accounting for approximately 85% of all cases, making it the primary application for surgical resection. Demand is consistently high across North America and Europe.
- Early Stage Lung Cancer:This application focuses on tumors detected at an early, localized stage, often through screening programs, leading to higher rates of curative surgery. Demand expands in the United States and Japan.
- Small Cell Lung Cancer:SCLC accounts for a smaller proportion of cases, typically treated with chemotherapy and radiation, with surgery reserved for very early disease.
- Advanced Stage Lung Cancer:Surgery for advanced stage lung cancer is primarily palliative or for managing complications, often combined with other therapies.
- Recurrent Lung Cancer:This application involves surgical intervention for tumors that have returned after initial treatment, requiring careful patient selection.
The largest patient cohorts are found in Non-Small Cell Lung Cancer, with Early Stage Lung Cancer representing a growing segment.
End User:
Different end-user types prioritize distinct aspects of surgical care, influencing their investment in technology and the complexity of procedures undertaken.
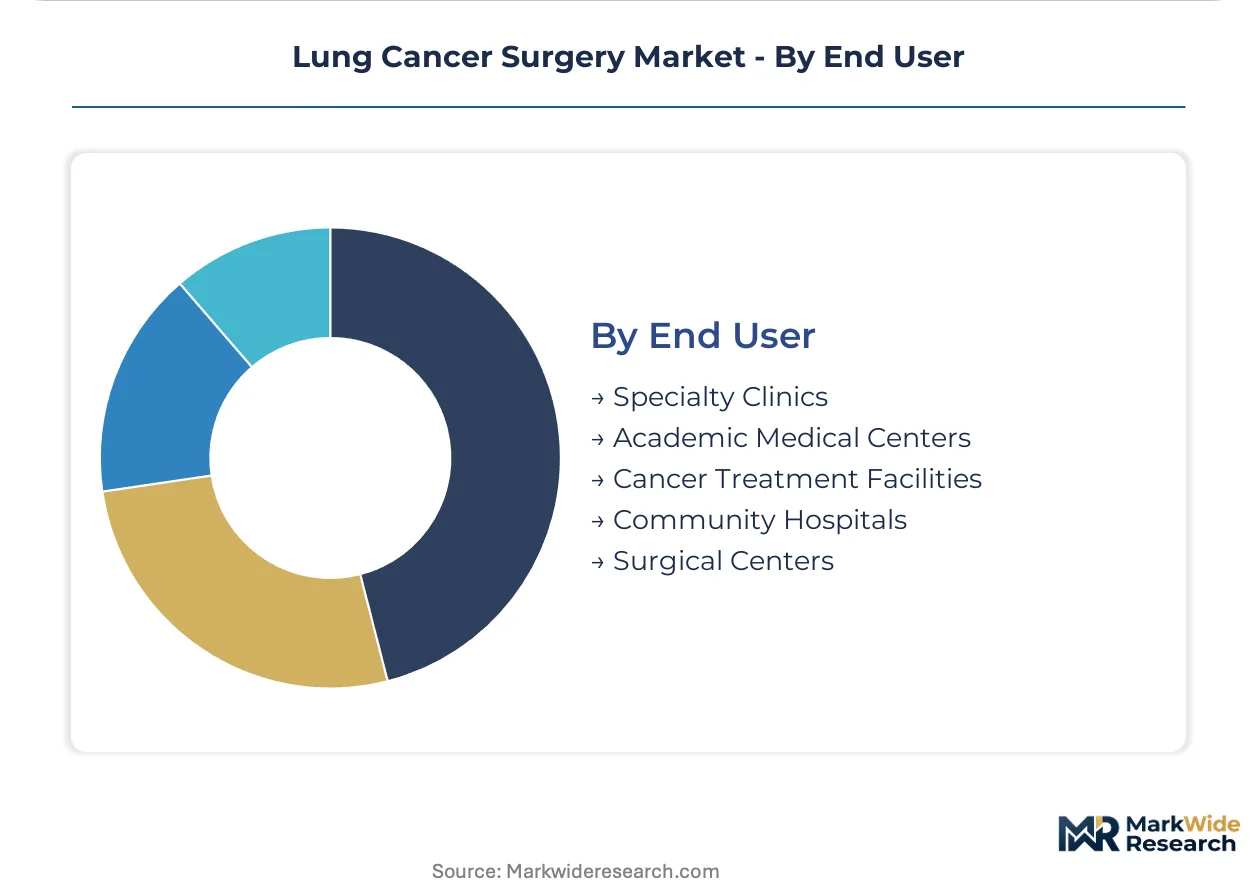
- Academic Medical Centers:These institutions are research-intensive, handling complex cases, and are early adopters of advanced surgical technologies like robotics. Demand concentrates in major metropolitan areas globally for specialized care.
- Cancer Treatment Facilities:These large-volume centers specialize in oncology care, performing many lung cancer surgeries and investing in dedicated surgical suites. Demand is strong in the United States and Germany.
- Specialty Clinics:Specialty clinics may focus on specific aspects of lung health or minimally invasive procedures.
- Community Hospitals:Community hospitals provide general surgical services and often refer complex lung cancer cases to larger facilities.
- Surgical Centers:Standalone surgical centers typically perform less complex, outpatient procedures, though some specialize in minimally invasive thoracic surgery.
Specialized care facilities prioritize Academic Medical Centers, while broader access is provided by Community Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology transfer from established medical device hubs in the United States to rapidly expanding healthcare markets like China is reshaping lung cancer surgery. This flow addresses a global need for minimally invasive procedures. New hospital investments support this transition across diverse geographies.
United States
The United States drives substantial demand for advanced lung cancer surgery, particularly for lobectomy and robotic-assisted procedures. US FDA regulations mandate stringent clinical evidence for new surgical systems, influencing market access. Academic medical centers in metropolitan areas like New York are early adopters of AI-integrated surgical platforms.
China
China's market expands due to significant healthcare infrastructure investment and a growing preference for Video-Assisted Thoracoscopic Surgery. China's NMPA ensures device safety and efficacy, shaping product availability. Large metropolitan areas such as Guangzhou are seeing increased capacity for advanced surgical suites for VATS procedures.
Japan
Japan exhibits strong demand for segmentectomy, driven by early cancer detection through advanced screening programs. Japan's PMDA ensures rigorous evaluation of new surgical instruments and systems before market entry. High-volume cancer hospitals in cities such as Kyoto prioritize precise, lung-sparing resections.
Germany
Germany registers high adoption rates for robotic-assisted surgery platforms, particularly within its specialized cancer treatment facilities. The European Medicines Agency under MDR imposes strict requirements for clinical evidence on surgical devices. Major university hospitals in cities like Munich are investing heavily in cutting-edge robotic systems.
India
India's market for lung cancer surgery is growing, fueled by increasing hospital investments in minimally invasive capabilities like VATS. India's CDSCO oversees medical device approvals, ensuring market access for newer technologies. Large urban centers such as Bangalore are emerging as hubs for specialized thoracic surgery.
Lung Cancer Surgery Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of lung cancer surgical devices and platforms. The market exhibits a tiered structure, with established medical technology giants offering comprehensive solutions alongside niche providers focusing on specific procedural tools. Innovators in robotic-assisted surgery, diversified instrument providers, and those leveraging extensive hospital networks represent key strategic archetypes. Companies pursue portfolio diversification and strategic partnerships to strengthen their market presence and expand technological reach.
Within the advanced surgical solutions segment, Johnson & Johnson, a US-based corporation, exemplifies a broad portfolio approach, leveraging its extensive global network. Intuitive Surgical Inc., another prominent US-based entity, anchors the robotic-assisted surgery market with its established platform. Medtronic Plc., an Irish-domiciled company, represents a diversified provider of surgical instruments and energy devices for various procedural types. These entities collectively shape innovation and distribution channels within the rapidly evolving lung cancer surgery landscape.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Intuitive Surgical Inc. |
| Medtronic Plc. |
| Stryker Corporation |
| Olympus Corporation |
| Siemens Healthineers AG |
| GE Healthcare |
| Accuray Incorporated |
| KARL STORZ SE & Co. KG |
| Others |
Cost & Logistics Intelligence
Three-month lead times for specialized robotic-assisted surgical systems influence hospital capital expenditure and supplier pricing power. This dynamic ensures that manufacturers of advanced platforms manage inventory carefully to meet demand from high-volume facilities.
Pricing Analysis
The pricing gap between advanced robotic platforms and conventional Video-Assisted Thoracoscopic Surgery (VATS) systems remains substantial, reflecting differing R&D investments. Value-based procurement models are gaining traction, shifting focus from individual device costs to total procedural cost and patient outcomes. Price differentiation stems from technology sophistication, such as AI integration, and the comprehensiveness of after-sales support and surgeon training. Pricing pressure intensifies for established VATS instruments due to increased competition and broader market adoption. Community hospitals typically exhibit higher price sensitivity compared to Academic Medical Centers.
Supply Chain Analysis
Extended lead times for critical components impact the delivery schedules of advanced surgical systems. Geographic supply concentration for high-precision surgical instruments and robotic components centers in the United States, Germany, and Japan. Raw material dependencies include specialized alloys for instruments, precision optics for visualization systems, and advanced microcontrollers for robotic platforms. Single-source vulnerability for proprietary components presents a structural risk. Distribution runs through direct sales teams to hospitals, often supported by specialized clinical training and technical service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lung cancer surgery market is experiencing a buyer-power shift, driven by the consolidation of integrated healthcare networks in regions like the United States.
For Market Incumbents:
Compound existing market share by integrating AI-powered pre-operative planning tools directly into proprietary robotic platforms. Deepen vertical integration into specialized instrument manufacturing to mitigate supply chain risks. Invest in comprehensive surgeon training programs to address skill scarcity and reinforce platform adoption. This strategy defends against the emergence of lower-cost robotic competitors and ensures long-term market leadership by leveraging regulatory expertise for new device approvals.
For New Entrants and Emerging Players:
Anchor in underserved regional markets in Southeast Asia and Latin America, focusing on more accessible, cost-effective minimally invasive solutions. Target the development of segmentectomy-specific instrumentation and AI-driven intra-operative guidance for VATS procedures. Community hospitals seeking to upgrade from open surgery represent the most penetrable segment. Partner with local distributors for rapid market penetration and surgeon training programs, establishing a strong go-to-market angle.
For Investors and Strategic Acquirers:
Long-term, this sits as a technology-driven growth play because aging populations and improved screening will expand the surgically eligible patient pool. Identify niche software developers specializing in surgical AI, advanced imaging analytics, or real-time pathological assessment as prime acquisition targets. A critical signal to watch will be reimbursement policy changes favoring lung-sparing resections and value-based care models, indicating accelerated market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Validates new surgical techniques and devices for broader adoption and regulatory approval. |
| Hospital System Partnership | Secures preferred vendor status and accelerates technology adoption within integrated networks. |
| Software Companion Development | Enhances surgical precision and decision-making through AI-driven planning and guidance. |
| Geographic Expansion (China/India) | Accesses rapidly growing patient populations and emerging healthcare infrastructure. |
| CE Marking Pathway (MDR compliance) | Ensures continued market access in the stringent European medical device market. |
Research Approach
Initial hypotheses were tested against primary input from thoracic surgeons, hospital procurement managers, medical device engineers, and regulatory specialists, and refined through iterative feedback. This primary research was triangulated with extensive secondary data from US FDA filings, European Medicines Agency submissions, China's NMPA device registries, and peer-reviewed clinical literature. The analysis employed both bottom-up market sizing, based on procedure volumes, and top-down validation from company revenues to ensure robust data integrity.
Variance decomposition across the modeling period identified key drivers influencing future market growth, including technological innovation and demographic shifts. The analytical framework segmented the market by procedure type, technology, application, end-user, and geographic region over the projection horizon. Compound annual growth rates were derived from historical growth patterns and projected market dynamics, with incidence rates of lung cancer and adoption rates of minimally invasive surgery serving as key forecast inputs.
Material uncertainties — including unforeseen regulatory changes or rapid shifts in treatment paradigms — sit outside the modeled envelope. Forecasts reflect assumptions regarding healthcare investment and technological progression. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Anemia Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Tennis Elbow Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Nontuberculous Mycobacterium Treatment Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Mexico Hair Transplant Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Psittacosis Treatment Market