
 Global Dermatoscope Market | 2026-2036
Global Dermatoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dermatoscope Market Foresight
The dermatology equipment distribution channel is rewriting how specialized imaging tools reach clinical buyers. Canfield Scientific leverages direct-to-clinic sales teams across North American academic medical centers. HEINE Optotechnik anchors its position through optometry and dermatology specialty distributors in European markets. FotoFinder Systems differentiates by controlling dedicated service networks that handle installation, training, and maintenance contracts.
A dermatoscope is a handheld or digital optical instrument employing polarized or non-polarized light with magnification typically ranging from 10x to 100x to visualize subsurface skin structures for lesion assessment. The device serves primarily to enhance diagnostic accuracy in melanoma detection and distinguish benign from malignant pigmented lesions before biopsy. Smartphone-enabled devices lead volume shipments due to their lower capital requirements and compatibility with telemedicine workflows, while artificial intelligence integration represents the fastest-expanding technology segment as algorithms gain regulatory clearance for lesion classification. Polarized optical systems command premium pricing in dermatology practices where reimbursement justifies higher equipment expenditure.
The FDA oversees dermatoscope classification as Class II medical devices requiring 510(k) clearance for digital imaging and AI-integrated systems, while the EU MDR imposes stricter clinical evidence requirements for software-as-medical-device functionality in European markets. ISO 13485 quality management standards govern manufacturing processes for optical and electronic components across major production centers. Stakeholders must monitor how divergent regulatory pathways for AI diagnostic algorithms reshape competitive entry barriers and product development timelines across jurisdictions.
Market Dynamics
The FDA's evolving classification framework for AI-assisted diagnostic devices is compressing product development timelines while forcing software integration requirements across all hardware tiers, fundamentally restructuring how manufacturers allocate R&D capital between optical engineering and algorithmic capabilities.
Growth Catalysts
- Skin cancer screening mandates:Australia's national melanoma prevention programs and Japan's aging demographic surveillance initiatives are expanding institutional procurement quotas for polarized imaging systems in outpatient dermatology settings.
- EU MDR software-as-medical-device pathways:The European Union's Medical Device Regulation creates regulatory clarity for AI-integrated lesion classification algorithms, accelerating CE marking submissions from developers seeking European market access.
- Telemedicine infrastructure deployment:Smartphone-enabled dermatoscope compatibility with remote diagnostic workflows is driving volume shipments to primary care networks in Germany and the United States where reimbursement codes now cover teledermatology consultations.
Market Restraints
- Optical component supply concentration:Premium polarized lens assemblies and high-resolution CMOS sensors concentrate manufacturing in East Asian production clusters, exposing procurement timelines to geopolitical logistics disruptions.
- 510(k) clearance bottlenecks:The FDA's predicate device requirements for digital imaging systems create extended review cycles for novel optical architectures, delaying commercialization of next-generation multispectral platforms.
- Pathology workflow substitution:Confocal laser microscopy and optical coherence tomography systems compete for capital allocation in academic medical centers, constraining mid-tier dermatoscope budget expansion.
Strategic Opportunities
- Underpenetrated primary care networks:Brazil's Sistema Único de Saúde expansion and India's Ayushman Bharat health infrastructure investments represent untapped demand for cost-effective non-polarized screening devices in community clinic settings.
- AI algorithm regulatory tailwinds:Health Canada's streamlined approval pathways for machine learning-enabled diagnostic software create first-mover advantages for vendors establishing North American algorithmic validation datasets.
- Veterinary dermatology convergence:Cross-species lesion classification algorithms paired with portable imaging hardware open specialty animal health channels where regulatory barriers remain lower than human medical device classifications.
Industry Challenges
- Dermoscopy interpretation skill scarcity:The shortage of board-certified dermatologists trained in pattern analysis protocols limits effective utilization of advanced imaging systems in general practice settings, constraining clinical outcome validation for AI-assisted tools.
- Legacy PACS integration complexity:Hospital information system vendors maintain proprietary data formats that fragment image storage architectures, forcing dermatoscope manufacturers to maintain multiple software middleware layers for enterprise deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dermatoscope Market |
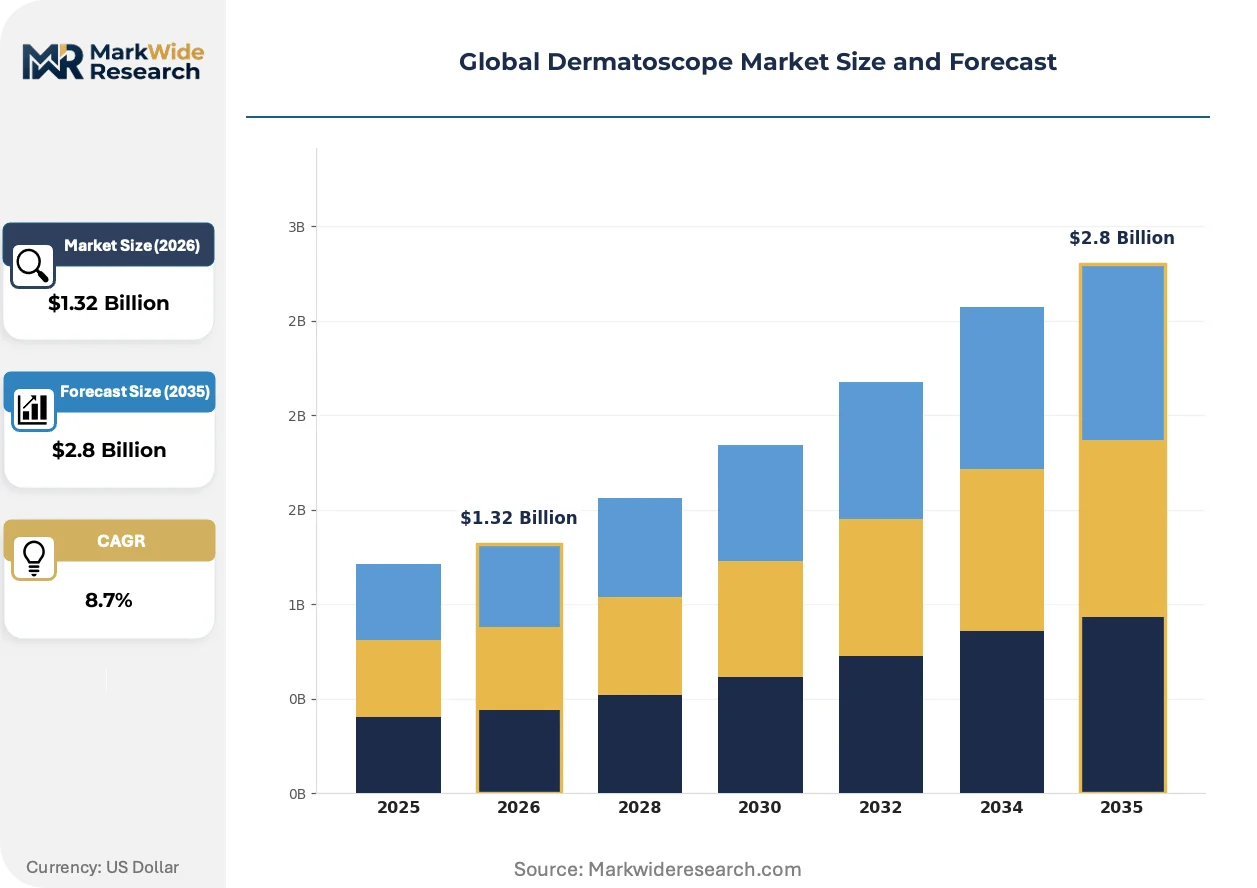
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Smartphone-Enabled, Video Dermatoscopes, Polarized, Non-Polarized Technology: Optical, Digital Imaging, Multispectral, 3D Imaging, Artificial Intelligence Integration Application: Skin Lesion Analysis, Pigmentation Assessment, Skin Cancer Screening, Hair and Scalp Evaluation, Vascular Condition Detection End User: Dermatologists, Skin Clinics, Research Laboratories, Telemedicine Providers, Cosmetic Centers |
| Companies Covered | Canfield Scientific, Inc., HEINE Optotechnik GmbH & Co. KG, FotoFinder Systems, 3Gen, DermLite, Firefly Global, ILLUCO Corporation Ltd., Welch Allyn, Caliber Imaging & Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dermatoscope Market Shifts & Advancements
Multispectral imaging architectures and edge-computing inference engines are converging to reshape diagnostic workflows, while regulatory frameworks race to catch up with algorithmic decision-support capabilities.
Deep learning lesion classification algorithms trained on federated dermatology datasets are rendering obsolete the traditional reliance on specialist pattern-recognition expertise for initial triage decisions. Community health centers in the United States and provincial hospitals in China are deploying these systems at accelerating rates. The structural consequence compresses the diagnostic funnel, shifting biopsy referral thresholds and reallocating specialist capacity toward complex case management.
The EU AI Act's risk-based classification system imposes conformity assessment requirements on high-risk medical AI applications, including dermatoscopic diagnostic support tools. Manufacturers must now maintain post-market monitoring systems and algorithmic change control protocols that mirror pharmaceutical vigilance standards. European dermatology practices purchasing integrated systems face extended vendor qualification timelines as software updates trigger re-certification obligations.
Hospital procurement departments are unbundling imaging hardware from service contracts and algorithm licensing fees, forcing vendors to compete on transparent lifecycle cost metrics rather than bundled capital expenditure packages. Academic medical centers in Germany and Australia now issue separate RFPs for device acquisition, maintenance networks, and AI software subscriptions. This fragmentation favors modular platform architectures over vertically integrated proprietary ecosystems.
Global Dermatoscope Market Segmentation
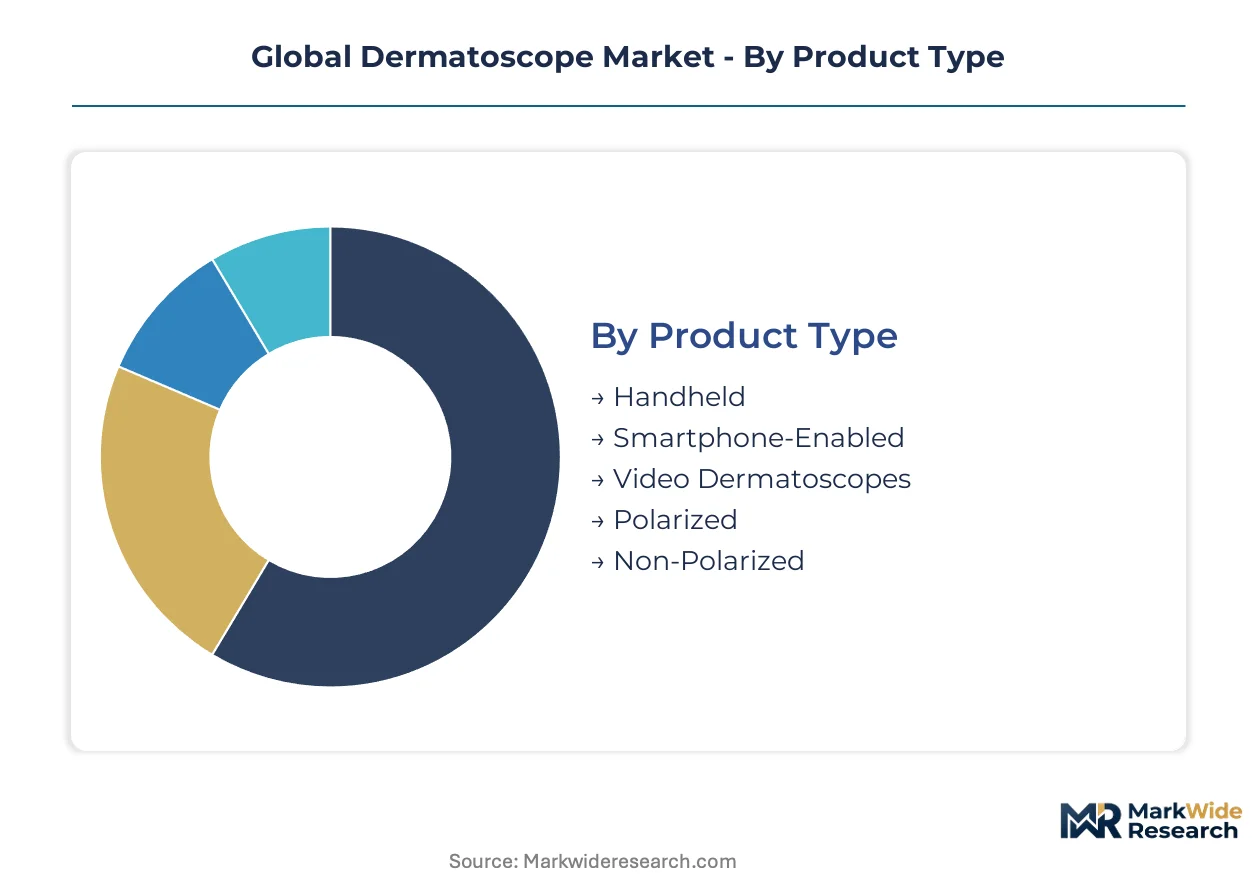
Dermatoscope segmentation reveals how technical specifications, clinical workflows, and procurement budgets fragment demand across healthcare systems. Understanding these divisions exposes where manufacturers can capture premium pricing versus where volume scale dominates.
Product Type:
Mature optical architectures coexist with emerging digital form factors as clinics balance diagnostic fidelity against capital constraints and telemedicine compatibility.
- Handheld:Compact battery-powered units with 10x to 40x magnification serve as the clinical standard for point-of-care lesion examination. Demand concentrates in United States dermatology practices where reimbursement codes reward in-person screening efficiency, though procurement timelines stretch when practices defer capital expenditure decisions.
- Smartphone-Enabled:Clip-on or docked devices leverage mobile camera sensors and cloud connectivity for image capture and remote consultation. Germany's expanding telemedicine reimbursement framework and Australia's rural health network investments are accelerating procurement quotas for these lower-cost systems.
- Video Dermatoscopes:Integrated camera and display systems enable real-time visualization and documentation for training and patient education.
- Polarized:Cross-polarized light filtration eliminates surface reflection to reveal deeper dermal structures. Japan's academic medical centers prioritize these systems for melanoma surveillance programs.
- Non-Polarized:Standard contact dermoscopy with immersion fluid remains the cost-effective default for high-volume screening workflows.
Handheld devices retain volume leadership; smartphone-enabled systems hold the steepest expansion curve.
Technology:
Cost tiers separate legacy optical methods from algorithm-augmented platforms as regulatory clearance becomes the gating factor for premium positioning.
- Optical:Conventional lens-and-light systems without electronic image processing dominate installed bases in cost-sensitive markets. Brazil's Sistema Único de Saúde procurement specifications favor these proven architectures for community clinic deployment.
- Digital Imaging:CMOS or CCD sensor-based capture with onboard storage and USB export meets documentation requirements in European practices subject to EU MDR data integrity standards.
- Multispectral:Sequential narrow-band illumination across ultraviolet to near-infrared wavelengths enhances melanin and hemoglobin contrast. Research laboratories in China and the United States are piloting these systems for algorithm training dataset generation.
- 3D Imaging:Stereoscopic or structured-light depth mapping quantifies lesion topography for surgical planning applications.
- Artificial Intelligence Integration:Embedded or cloud-connected inference engines classify lesion probability scores at the point of capture. Health Canada's streamlined approval pathways are attracting vendors seeking North American algorithmic validation footholds.
Digital imaging retains volume leadership; artificial intelligence integration holds the steepest expansion curve.
Application:
Customer type determines whether applications cluster around diagnostic accuracy or cosmetic consultation workflows.
- Skin Lesion Analysis:Pattern recognition for melanocytic nevi versus melanoma differentiation represents the core clinical use case. United States dermatologists trained in dermoscopy interpretation protocols drive replacement demand for higher-resolution systems.
- Pigmentation Assessment:Quantitative melanin mapping supports treatment monitoring for conditions like melasma and post-inflammatory hyperpigmentation. Cosmetic centers in Japan and South Korea are expanding procurement for these aesthetic applications.
- Skin Cancer Screening:Population-scale early detection programs in Australia and Germany are institutionalizing standardized imaging protocols for at-risk patient cohorts.
- Hair and Scalp Evaluation:Trichoscopy applications diagnose alopecia patterns and follicular disorders.
- Vascular Condition Detection:Hemangioma and telangiectasia assessment leverages specific wavelength filtering capabilities.
Skin lesion analysis retains volume leadership; pigmentation assessment holds the steepest expansion curve.
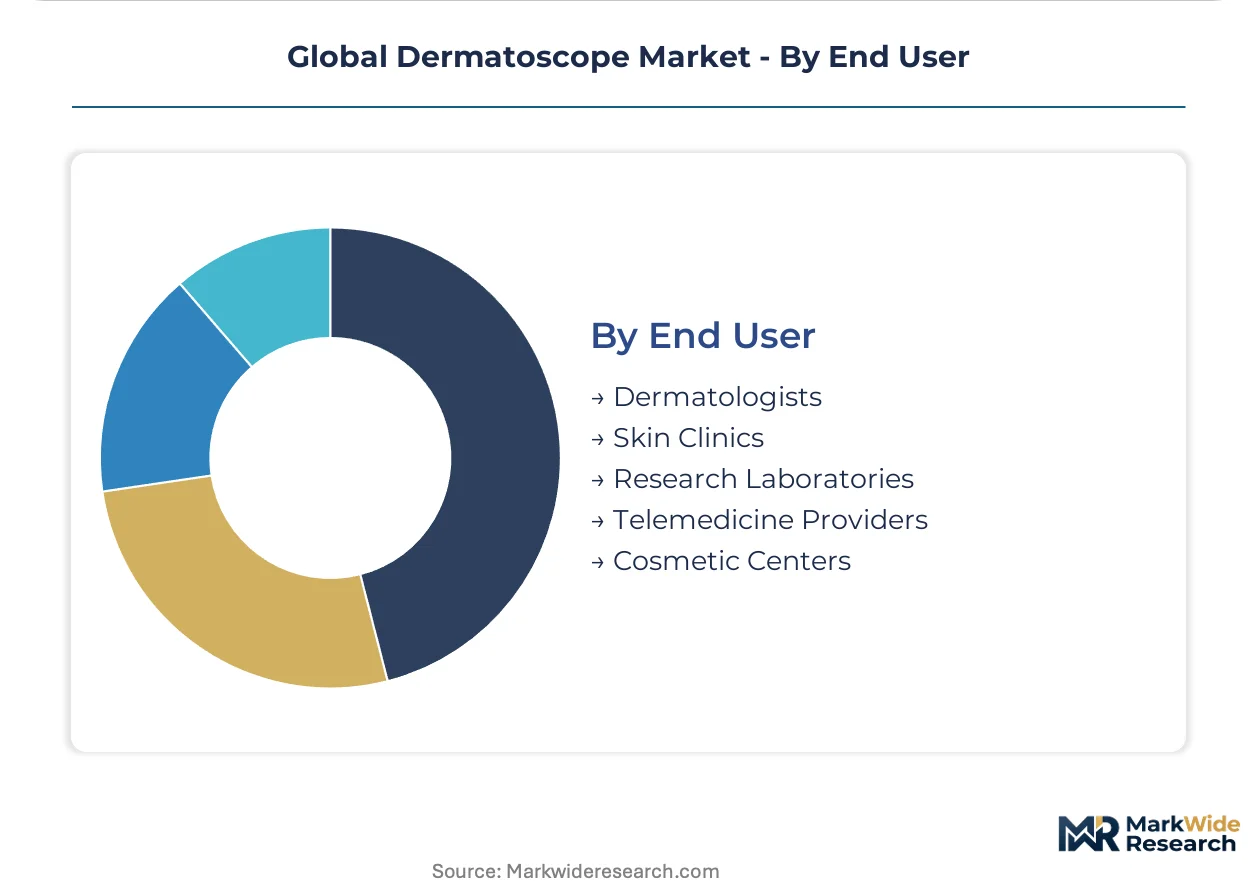
End User:
Geography and margin structure shape how end-user categories fragment across reimbursement environments and regulatory jurisdictions.
- Dermatologists:Board-certified specialists with formal dermoscopy training represent the highest-value customer segment for premium polarized and AI-integrated systems. Their diagnostic authority justifies equipment expenditure in United States and Japanese reimbursement frameworks.
- Skin Clinics:Dedicated outpatient facilities concentrate device utilization rates and amortize capital costs across high patient volumes. India's emerging dermatology chain networks are scaling procurement of mid-tier digital systems.
- Research Laboratories:Academic and pharmaceutical settings demand multispectral and 3D architectures for algorithm development and clinical trial endpoints.
- Telemedicine Providers:Remote diagnostic platforms prioritize smartphone-enabled compatibility and cloud-native image management architectures.
- Cosmetic Centers:Aesthetic practices in South Korea and the United Arab Emirates are expanding demand for pigmentation and vascular assessment capabilities.
Dermatologists retain volume leadership; telemedicine providers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's evolving classification framework for AI-assisted diagnostic devices anchors demand generation in the United States, while procurement clusters in Germany, Japan, China, and Australia concentrate specialized imaging equipment deployment across distinct reimbursement environments.
United States
Academic medical centers in Boston and New York Metro drive replacement demand for AI-integrated polarized systems as dermatology residency programs expand dermoscopy training curricula. FDA 510(k) clearance pathways for digital imaging systems shape vendor qualification timelines for multispectral platforms. The Mayo Clinic and MD Anderson procurement networks concentrate enterprise deployment decisions for integrated diagnostic workflows.
Germany
Telemedicine reimbursement expansion under the national health insurance framework accelerates smartphone-enabled device procurement for rural primary care networks. EU MDR software-as-medical-device requirements impose clinical evidence standards on AI algorithm developers seeking CE marking. Bavaria's dermatology clinic chains concentrate service contract negotiations for maintenance and training networks.
Japan
Aging demographic surveillance initiatives expand institutional quotas for polarized imaging systems in outpatient melanoma screening programs. PMDA regulatory pathways for machine learning-enabled diagnostic software create streamlined approval channels for algorithm developers. Tokyo and Osaka academic medical centers pilot multispectral architectures for algorithm training dataset generation.
China
Provincial hospital networks in Jiangsu and Guangdong deploy digital imaging systems at accelerating rates for community-based skin cancer screening expansion. NMPA medical device registration requirements govern manufacturing quality standards for CMOS sensor integration. Yangtze River Delta production clusters concentrate optical component assembly and high-resolution sensor sourcing.
Australia
National melanoma prevention programs institutionalize standardized imaging protocols across Queensland and New South Wales dermatology clinics. TGA approval pathways for AI diagnostic support tools align with post-market monitoring obligations under the EU AI Act risk-based framework. Melbourne and Sydney research laboratories federate dermatology datasets for deep learning algorithm validation.
Global Dermatoscope Market Competitive Landscape
Optical engineering specialists and digital health integrators split the market across technology tiers. The vendor base concentrates around three strategic archetypes: legacy optoelectronics manufacturers with established distribution networks, software-native entrants leveraging cloud connectivity, and vertically integrated platform vendors controlling service ecosystems. Dominant competitive moves include strategic partnerships between hardware fabricators and AI algorithm developers, plus geographic expansion through dedicated sales teams targeting academic medical centers.
Among North American equipment vendors, Canfield Scientific, Inc. occupies a position exemplifying the vertically integrated archetype with direct-to-clinic sales infrastructure. HEINE Optotechnik GmbH & Co. KG anchors the European optoelectronics tradition through specialty distributor relationships. FotoFinder Systems represents the service-network control model with dedicated installation and maintenance operations.
| Leading Market Players |
|---|
| Canfield Scientific, Inc. |
| HEINE Optotechnik GmbH & Co. KG |
| FotoFinder Systems |
| 3Gen |
| DermLite |
| Firefly Global |
| ILLUCO Corporation Ltd. |
| Welch Allyn |
| Caliber Imaging & Diagnostics |
| Others |
Supply & Pricing Matrix
Single-source dependency on East Asian CMOS sensor fabrication determines both the spread between configured-to-order AI-integrated systems and standard optical devices and the geographic shape of procurement networks. FDA 510(k) clearance timelines for digital imaging systems compress margin structures for mid-tier manufacturers while polarized lens assemblies from specialized Japanese and German optics houses command persistent premiums.
Pricing Analysis
The customization-premium spread between standard handheld optical units and configured-to-order AI-integrated polarized systems spans three distinct pricing tiers. Pricing stratifies across premium polarized systems with embedded inference engines, standard digital imaging platforms with cloud connectivity, and economy non-polarized devices for high-volume screening workflows. Cost compression in the smartphone-enabled tier intensifies as Chinese manufacturers scale CMOS sensor integration. Primary care networks in Brazil and India exhibit the highest price sensitivity, while academic medical centers in the United States and Japan prioritize diagnostic fidelity over capital expenditure constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for dermatoscope manufacturers sourcing high-resolution imaging sensors. Component assembly draws from production clusters in China, South Korea, and Japan, with polarized lens grinding concentrated in German and Swiss optical houses. Single-source vulnerability in specialized near-infrared sensor supply threatens multispectral platform rollouts. Distribution runs through dermatology specialty distributors in European markets and direct-to-clinic sales teams across North American academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital procurement departments unbundling hardware from service contracts and algorithm licensing fees, fragmenting vendor pricing power as German and Australian academic medical centers issue separate RFPs for device acquisition, maintenance, and AI subscriptions.
For Market Incumbents: Build regulatory clearance moats by accelerating FDA 510(k) submissions for next-generation multispectral architectures before predicate device requirements tighten. Deepen backward integration into polarized lens supply through captive partnerships with German optical fabricators. Channel control over dedicated installation and training networks in European markets defends against software-native entrants leveraging cloud connectivity. For New Entrants and Emerging Players: Pursue veterinary dermatology convergence where regulatory barriers remain lower than human medical device classifications and cross-species lesion classification algorithms face streamlined approval pathways. Brazil's Sistema Único de Saúde expansion and India's Ayushman Bharat health infrastructure investments represent the most penetrable demand clusters for cost-effective non-polarized screening devices. A smartphone-first go-to-market angle bypasses capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: AI algorithm developers with Health Canada validation datasets and modular platform architectures present the strongest acquisition target archetype for capturing North American algorithmic validation footholds. Long-term viability hinges on post-market monitoring capabilities that satisfy EU AI Act risk-based conformity assessment obligations. The signal to watch is TGA alignment with European post-market surveillance frameworks accelerating vendor consolidation in Australian procurement networks.| Strategic Initiative | Industry Significance |
|---|---|
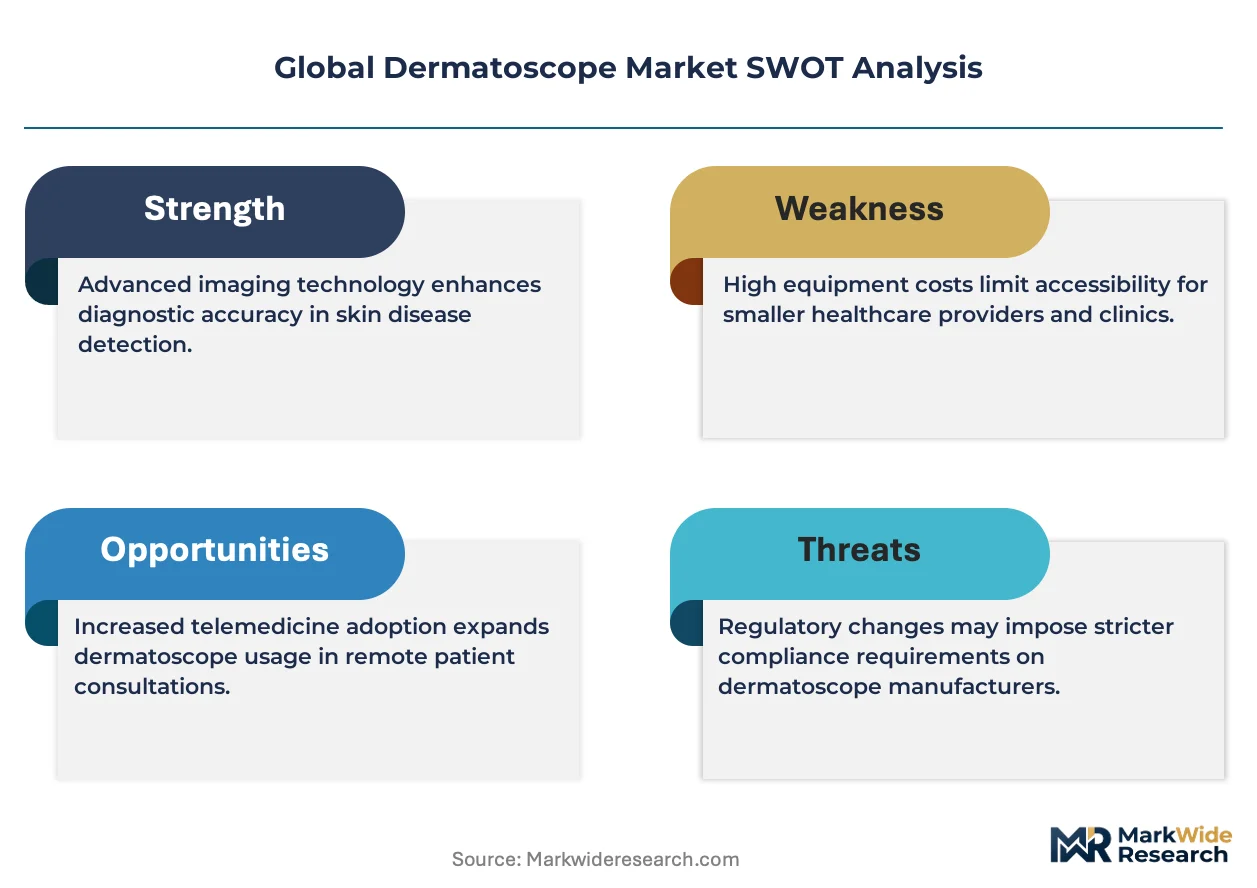
| CE Marking Pathway | EU MDR software-as-medical-device requirements impose clinical evidence standards on AI algorithm developers seeking European market access. |
| Hospital System Partnership | Unbundled procurement at German academic medical centers fragments vendor pricing power across separate hardware and service contracts. |
| Software Companion Development | Federated dermatology datasets in Melbourne and Sydney research laboratories enable deep learning algorithm validation for diagnostic support tools. |
| FDA Submission | 510(k) clearance bottlenecks for novel optical architectures delay commercialization of multispectral platforms in United States markets. |
| Reimbursement Strategy | Telemedicine reimbursement expansion under Germany's national health insurance framework accelerates smartphone-enabled device procurement. |
Research Methodology
The analysis maps handheld optical systems, smartphone-enabled devices, video dermatoscopes, and AI-integrated platforms, each validated through dermatology equipment procurement managers, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs leads at algorithm developers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR CE marking databases, TGA approval registers, and hospital procurement contract disclosures. Bottom-up shipment estimates by product tier triangulate against top-down expenditure flows from national health insurance frameworks.
The assumption-set holds regulatory clearance timelines and reimbursement code stability fixed while varying telemedicine infrastructure deployment rates and AI algorithm validation dataset availability across the projection horizon. The analytical framework models product type, technology tier, application use case, and end-user category segmentation dimensions. CAGRs derive from fitted growth curves anchored to dermatology clinic capital expenditure surveys and replacement cycle analysis. Forecast inputs include provincial hospital network expansion rates in China and rural health network investments in Australia.
Macroeconomic conditions sit as an overlay; deviation in health insurance reimbursement rates, medical device tariff schedules, or semiconductor export controls would shift the trajectory. Forecasts reflect these assumptions with continuous validation against operating reality as the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vein Finders Market
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
Endoscope Procedure Kits Market
Medical Devices
Cervical Total Disc Replacement Device Market
Medical Devices
Bioimpedance Spectroscopy Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Americas Medical Suction Device Market
Medical Devices
US Surgical Microscopes Market
Medical Devices
Laryngoscopes Market
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
Spinal Implant Market
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
US Clear Aligners Market
Medical Devices
External Nasal Dilator Market