
 Global Busbar Trunking Market | 2026-2036
Global Busbar Trunking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Busbar Trunking Market Analysis
Chinese busbar trunking manufacturing is consolidating around integrated copper processing and modular assembly hubs. Eaton leverages vertical integration across medium-voltage switchgear and busbar production to control input costs. Schneider Electric anchors its position through IEC-certified plug-in systems that dominate European data center retrofits. Siemens competes on digital-twin-enabled thermal monitoring embedded directly into busbar runs.
Busbar trunking refers to prefabricated electrical distribution systems comprising insulated conductors housed within protective enclosures, typically rated from 800A to 6300A for low- and medium-voltage power transmission. Aluminum conductors now capture substantial share in cost-sensitive commercial installations due to weight advantages and MIIT-mandated efficiency benchmarks, while copper retains dominance in data center and heavy industrial segments where thermal performance governs specification. Surface mounted installations lead volume in retrofit commercial buildings, though concealed systems command margin premiums in premium residential and healthcare projects across the Middle East.
FERC interconnection standards in the United States, EU Ecodesign requirements administered by ECHA, and China's GB/T 7251 series collectively dictate enclosure integrity, short-circuit withstand ratings, and electromagnetic compatibility thresholds that determine market access. India's CEA technical standards for busbar trunking in critical infrastructure further segment compliance burdens by voltage class and fault-current rating. Stakeholders must monitor evolving efficiency mandates and material certification protocols as procurement specifications harden across regulated end-use sectors.
Market Dynamics
Data center operators in India and Southeast Asia are accelerating procurement of high-ampacity busbar systems to support hyperscale facility expansion, creating a demand surge that is reshaping manufacturing capacity allocation across Asia-Pacific.
Growth Catalysts
- MIIT Efficiency Mandates:China's Ministry of Industry and Information Technology tightening loss-factor thresholds is pushing manufacturers toward aluminum-copper hybrid designs that meet stricter thermal performance benchmarks.
- Hyperscale Data Center Expansion:Operators in India and the Gulf states are specifying 4000A-6300A systems for AI training clusters, driving specification upgrades across the commercial segment.
- EU Ecodesign Framework:The European Chemicals Agency's administered requirements for electromagnetic compatibility and enclosure integrity are filtering non-compliant suppliers from European retrofit projects.
Market Restraints
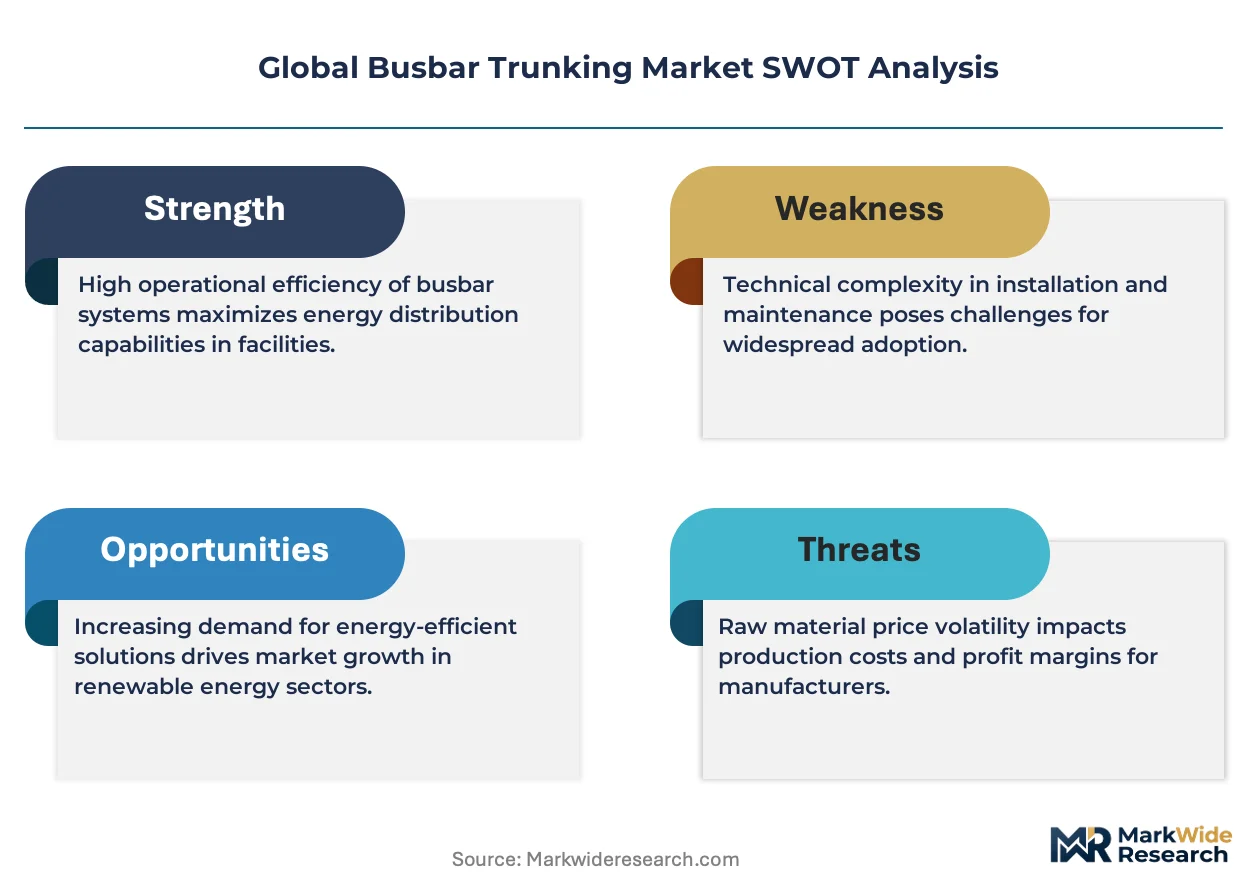
- Copper Price Volatility:Raw material cost swings for LME-grade copper concentrate are compressing margin predictability for manufacturers serving heavy industrial segments.
- Supply Concentration in Chinese Processing:Integrated copper smelting and extrusion capacity clusters in Jiangsu and Zhejiang provinces create geographic dependency risk for global procurement.
- Aluminum Thermal Limitations:Conductivity constraints in pure aluminum designs restrict deployment in fault-current environments above 50kA, preserving copper lock-in for critical infrastructure.
Strategic Opportunities
- Smart City Infrastructure in Saudi Arabia:NEOM and Red Sea Project developments are specifying concealed busbar systems for premium residential and healthcare verticals at margin premiums.
- Digital Twin Integration:Convergence of IoT sensor arrays with predictive thermal analytics is enabling condition-based maintenance contracts as a recurring revenue layer.
- India's Industrial Corridor Projects:Delhi-Mumbai and Bengaluru-Chennai freight corridors are tendering medium-voltage distribution systems with localized assembly requirements.
Industry Challenges
- IEC 61439-6 Certification Timelines:Short-circuit withstand testing and arc-fault containment validation cycles extend 14-18 months, delaying market entry for new product families.
- Legacy Switchgear Integration:Retrofit installations in European commercial buildings require custom adapter engineering to interface with 1980s-era breaker configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Busbar Trunking Market |
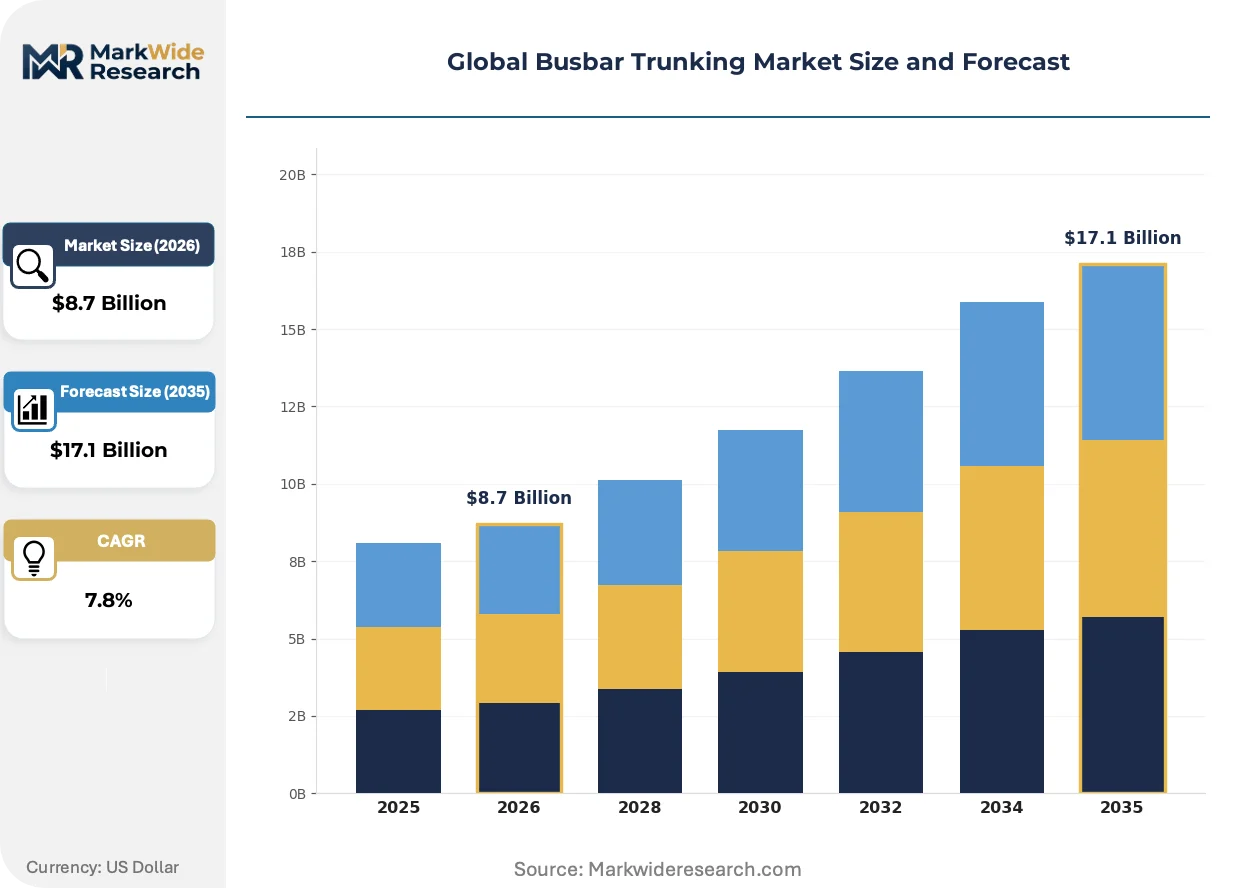
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IEC, ANSI, Hybrid, Modular Installation Method: Surface Mounted, Concealed, Overhead, Plug-In End User: Commercial, Industrial, Residential, Data Centers Material: Copper, Aluminum, Steel, Others |
| Companies Covered | Eaton, Godrej & Boyce, Schneider Electric, General Electric Company, Larsen & Toubro, Siemens, Legrand, EAE Elektrik, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Busbar Trunking Market Emerging Trajectories
Busbar trunking technology is undergoing material and digital transformation as efficiency mandates harden and end-users demand predictive operational visibility. Three developments are restructuring competitive differentiation.
Aluminum-copper hybrid conductor systems are unifying cost efficiency with thermal performance in a single enclosure design. Data center operators in Singapore and Mumbai are specifying these configurations for 1600A-3200A distribution runs. The technology is unifying previously separate procurement streams for commercial and industrial segments into a single specification tier.
REACH and RoHS amendments administered by ECHA are tightening substance restrictions on insulation compounds and enclosure coatings. Manufacturers serving European data center retrofits are reformulating halogen-free jacketing materials to maintain CE marking eligibility. German and Dutch electrical contractors are now requiring pre-submitted material compliance declarations as bid prerequisites.
Buying committees at hyperscale operators are consolidating vendor relationships from regional multi-source models to single-source framework agreements with embedded service provisions. Distributors in the Middle East are losing specification influence as direct procurement teams at Saudi Aramco and Emirates NBD facilities negotiate multi-year supply contracts. This concentration is most visible in UAE and Qatar where state-linked developers operate centralized procurement functions.
Global Busbar Trunking Market Segmentation
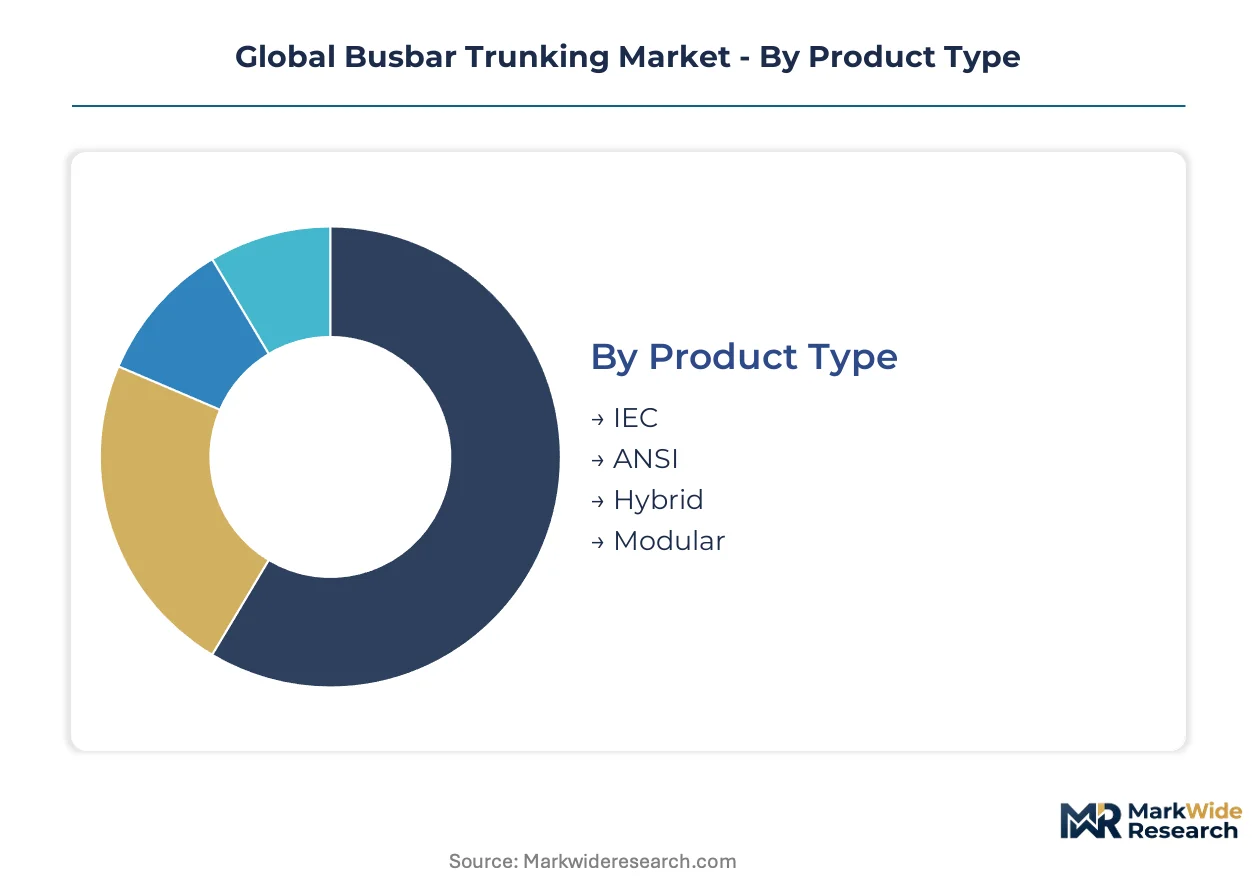
Busbar trunking procurement patterns diverge sharply across specification standards, mounting configurations, and material compositions. Segment boundaries harden as efficiency mandates from MIIT and Ecodesign filter incompatible suppliers from tender pools.
Product Type:
Upgrade cycles accelerate where certification regimes tighten loss-factor thresholds and electromagnetic compatibility requirements.
- IEC:IEC-certified plug-in systems dominate European data center retrofits where ECHA-administered Ecodesign requirements mandate enclosure integrity validation. German and Dutch electrical contractors now require pre-submitted material compliance declarations as bid prerequisites.
- ANSI:FERC interconnection standards in the United States dictate short-circuit withstand ratings and electromagnetic compatibility thresholds that determine market access for medium-voltage distribution systems. Surface mounted ANSI configurations lead volume in retrofit commercial buildings across Texas and California industrial corridors.
- Hybrid:Aluminum-copper hybrid designs unify cost efficiency with thermal performance for 1600A-3200A distribution runs in Singapore and Mumbai hyperscale facilities.
- Modular:Prefabricated modular assemblies reduce on-site installation labor for India's Delhi-Mumbai Industrial Corridor projects with localized assembly requirements.
Volume placements concentrate in IEC; the faster expansion belongs to Hybrid.
Installation Method:
Mounting configuration selection tracks building vintage, spatial constraints, and margin premiums available in premium verticals.
- Surface Mounted:Retrofit installations in European commercial buildings require custom adapter engineering to interface with 1980s-era breaker configurations. Surface systems capture substantial share in cost-sensitive commercial installations where weight advantages favor aluminum conductors.
- Concealed:Concealed busbar systems command margin premiums in premium residential and healthcare projects across Saudi Arabia's NEOM and Red Sea Project developments.
- Overhead:Overhead configurations serve manufacturing floors in China's Jiangsu and Zhejiang industrial clusters where ceiling-mounted distribution frees production space.
- Plug-In:Plug-in systems enable rapid reconfiguration for AI training clusters in UAE and Qatar state-linked facilities with centralized procurement functions.
Surface Mounted retains the largest installed base; Concealed gains share fastest in Gulf state smart city developments.
End User:
Customer-type segmentation reflects divergent thermal performance requirements and procurement centralization trends.
- Data Centers:Hyperscale operators in India and Southeast Asia specify 4000A-6300A systems for AI training clusters, driving specification upgrades across the commercial segment. Buying committees consolidate vendor relationships from regional multi-source models to single-source framework agreements.
- Industrial:Heavy industrial segments preserve copper lock-in for critical infrastructure where fault-current environments exceed 50kA. Raw material cost swings for LME-grade copper concentrate compress margin predictability for manufacturers serving this segment.
- Commercial:Aluminum conductors capture substantial share in cost-sensitive commercial installations due to MIIT-mandated efficiency benchmarks.
- Residential:Premium residential verticals in the Middle East specify concealed systems at margin premiums for aesthetic integration.
Industrial maintains the deepest penetration; Data Centers show the steepest expansion trajectory.
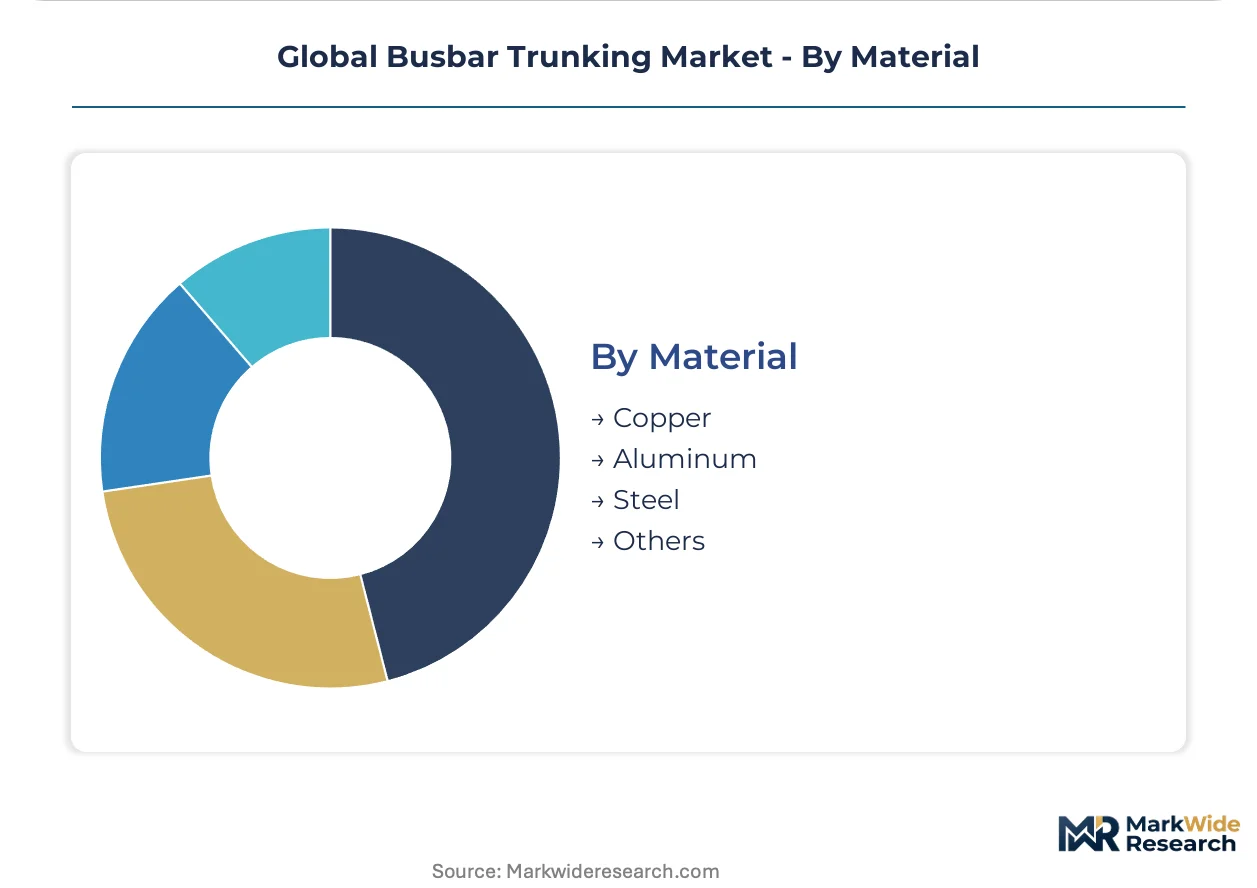
Material:
Conductor material selection concentrates where thermal performance governs specification and cost sensitivity dominates procurement.
- Copper:Copper retains dominance in data center and heavy industrial segments where thermal performance governs specification. Conductivity advantages preserve deployment in fault-current environments above 50kA.
- Aluminum:Aluminum conductors capture substantial share in cost-sensitive commercial installations due to weight advantages and MIIT-mandated efficiency benchmarks in China.
- Steel:Steel enclosures provide structural integrity for medium-voltage distribution systems in India's Bengaluru-Chennai freight corridor tenders.
- Others:Emerging composite formulations address REACH and RoHS amendments administered by ECHA for halogen-free jacketing materials.
Copper holds the revenue concentration; Aluminum climbs the fastest on cost-driven commercial substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated copper smelting and extrusion capacity clusters in Jiangsu and Zhejiang provinces anchor Asia-Pacific supply chains for busbar trunking systems. Raw material proximity shapes manufacturing allocation across three continents as efficiency mandates harden specification standards.
China
MIIT efficiency mandates are pushing manufacturers toward aluminum-copper hybrid designs that meet stricter thermal performance benchmarks. The GB/T 7251 series dictates enclosure integrity and electromagnetic compatibility thresholds that determine domestic market access. Jiangsu and Zhejiang industrial clusters concentrate integrated copper processing and modular assembly capacity for regional export.
India
Data center operators are accelerating procurement of high-ampacity busbar systems to support hyperscale facility expansion across Mumbai and Bengaluru. CEA technical standards for busbar trunking in critical infrastructure segment compliance burdens by voltage class and fault-current rating. Delhi-Mumbai and Bengaluru-Chennai freight corridors are tendering medium-voltage distribution systems with localized assembly requirements.
Germany
ECHA-administered Ecodesign requirements and REACH amendments are filtering non-compliant suppliers from European retrofit projects. German electrical contractors now require pre-submitted material compliance declarations as bid prerequisites. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate IEC-certified plug-in system manufacturing for data center specifications.
United States
FERC interconnection standards dictate short-circuit withstand ratings and electromagnetic compatibility thresholds for medium-voltage distribution systems. Surface mounted ANSI configurations lead volume in retrofit commercial buildings across Texas and California industrial corridors. Data center development in Northern Virginia and Phoenix is driving specification upgrades for 4000A-6300A systems.
Saudi Arabia
NEOM and Red Sea Project developments are specifying concealed busbar systems for premium residential and healthcare verticals at margin premiums. State-linked developers operate centralized procurement functions that consolidate vendor relationships into single-source framework agreements. Smart city infrastructure specifications in Riyadh and the Western Region are reshaping distributor influence across the Gulf.
Global Busbar Trunking Market Vendor Landscape
Global majors compete with regional champions across certification standards and material formulation capabilities. The vendor base spans three strategic tiers: integrated electrical conglomerates with captive copper processing, specialized busbar fabricators with modular assembly expertise, and regional contractors with localized certification relationships. Competitive differentiation concentrates on IEC 61439-6 compliance velocity, aluminum-copper hybrid design patents, and direct procurement relationships with hyperscale data center operators. M&A activity targets testing laboratory capabilities and regional certification portfolios.
Among integrated electrical conglomerates, Schneider Electric and Siemens exemplify the certification-driven tier with embedded digital monitoring architectures. Eaton occupies a position bridging medium-voltage switchgear and busbar production through upstream control over input costs. Regional specialists including Godrej & Boyce and Larsen & Toubro anchor the India-centric fabrication segment with localized assembly capacity for industrial corridor tenders. These archetypes represent the competitive structure without implying specific strategic actions or market positions.
| Leading Market Players |
|---|
| Eaton |
| Godrej & Boyce |
| Schneider Electric |
| General Electric Company |
| Larsen & Toubro |
| Siemens |
| Legrand |
| EAE Elektrik |
| ABB |
| Others |
Supply Flow & Price Mechanics
Specialized electrical assembly labor in China's Jiangsu and Zhejiang provinces anchors production cost structures, with wage differentials between coastal manufacturing clusters and inland assembly sites widening pricing spreads across IEC-certified premium tiers and unbranded economy alternatives.
Pricing Analysis
Warranty bundling and predictive maintenance subscriptions now separate premium vendor quotations from unbundled equipment-only pricing in data center procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and embedded IoT monitoring capabilities. Cost compression in aluminum-intensive commercial segments is intensifying because MIIT efficiency mandates force rapid design-cycle investments. Hyperscale operators exhibit lowest price sensitivity due to total-cost-of-ownership framing, while regional electrical contractors in Southeast Asia remain most responsive to unit-cost differentials.
Supply Chain Analysis
Dual-sourcing requirements from Saudi Aramco and Emirates NBD procurement teams are fragmenting order books across qualified suppliers in China, India, and Germany. Raw material flows draw from Chilean copper concentrate, Chinese aluminum billet, and German insulating compound formulations. Single-source vulnerability concentrates in IEC 61439-6 testing laboratory capacity, where 14-18 month certification cycles create bottleneck risk. Distribution runs through direct procurement teams at state-linked developers, bypassing traditional distributor networks in UAE and Qatar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics define this market, with IEC 61439-6 testing capacity shortages propping pricing power for certified incumbents while locking out unqualified competitors.
For Market Incumbents: Extend certification velocity advantages by acquiring testing laboratory capabilities in India and Southeast Asia, where CEA and local standards bodies are expanding validation demand. Lock in multi-year framework agreements with hyperscale operators before aluminum-copper hybrid patents expire. Vertical integration into copper extrusion insulates margin pressure from LME price volatility. For New Entrants and Emerging Players: Enter via modular assembly partnerships for India's Bengaluru-Chennai freight corridor tenders, where localized content requirements favor domestic fabrication footprints. Target concealed system specifications in Saudi Arabia's NEOM development, where aesthetic integration commands premium positioning absent from commodity commercial segments. Lead with digital-twin-enabled thermal monitoring as a differentiated service layer. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists holding captive IEC certification portfolios given accelerating procurement consolidation at hyperscale operators. Long-term viability hinges on testing asset ownership rather than pure manufacturing scale. Monitor IEC 61439-6 validation queue lengths as the inflection signal for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Testing Laboratory Acquisition | IEC 61439-6 validation capacity captures pricing power in certification-constrained procurement. |
| Aluminum-Copper Hybrid Patent Development | MIIT efficiency mandates favor designs unifying cost and thermal performance in single enclosures. |
| Direct Procurement Team Formation | State-linked developers in UAE and Qatar are consolidating vendor relationships away from distributors. |
| Digital Twin Service Layer Launch | IoT-enabled thermal monitoring enables recurring revenue from condition-based maintenance contracts. |
| Localized Assembly Partnership | India's industrial corridor tenders require domestic fabrication to meet content requirements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving data center procurement directors, electrical contractor project managers, busbar manufacturing plant engineers, and CEA compliance officers. ECHA substance restriction databases, MIIT efficiency standard publications, and IEC certification registries provided regulatory validation. Bottom-up installation volume estimates triangulated against top-down copper and aluminum consumption figures from customs records.
Data-stream reconciliation across product type, installation method, end-user vertical, conductor material, and geographic production hub enabled segmentation-level modeling throughout the forecast period. CAGRs derived from installation volume trajectories in hyperscale data center pipelines and industrial corridor tender schedules. Aluminum-copper hybrid adoption curves and digital-twin service attachment rates informed technology transition assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility extremes and IEC certification timeline delays. Deviation in MIIT efficiency mandate enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
DC Contactor Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
United States Electric Insulator Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
Insulator Market
Electrical Equipment
Slip Ring Market