
 Global Electrical Steel Market | 2026-2036
Global Electrical Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrical Steel Market Analysis
Power generation is pivoting toward renewable integration, forcing electrical steel specifications upward across transformer and generator supply chains. ArcelorMittal leverages its European flat-rolled capacity to dominate high-grade silicon steel for grid infrastructure. POSCO anchors Asia-Pacific supply through integrated mills optimized for thin-gauge electrical steel output. Tata Steel Limited competes on cost-adjusted efficiency in emerging market transformer segments.
Electrical steel is an iron-silicon alloy containing between one and four percent silicon, manufactured through controlled hot and cold rolling to achieve precise magnetic properties and minimal core loss. Its primary purpose centers on channeling magnetic flux with minimal energy dissipation in transformers, motors, and generators. Silicon steel sheets command the largest share of product value due to transformer OEM requirements for anisotropic grain orientation. The renewable energy application segment grows fastest as wind turbine generators and solar inverter transformers require higher-grade laminations. Coil form factors retain manufacturing scale advantages for automotive motor stamping operations.
The EU Green Deal and F-Gas Regulation tighten transformer efficiency mandates across Europe, while China's GB standards and MIIT directives enforce domestic content rules for grid equipment. The US Department of Energy and NHTSA indirectly shape demand through appliance efficiency rules and EV motor performance benchmarks. Stakeholders must monitor divergence between regional silicon content specifications and carbon border adjustment mechanisms as procurement criteria harden.
Market Dynamics
Transformer loss standards under the EU Green Deal and China's MIIT directives are forcing rapid grade migration across electrical steel supply chains, compressing demand for conventional laminations while premium silicon steel faces capacity bottlenecks.
Growth Catalysts
- EU F-Gas Regulation:Mandated efficiency upgrades for distribution transformers accelerate procurement of grain-oriented silicon steel across Germany, France, and Italy.
- Electric vehicle traction motors:Automakers specify high-frequency electrical steel grades for 800V architectures, pulling thin-gauge production from transformer applications.
- China's dual carbon goals:State Grid Corporation procurement rules favor domestic ultra-low-loss grades for ultra-high-voltage transmission corridors.
Market Restraints
- Silicon metal price volatility:Ferrosilicon input costs swing with Chinese smelter output curbs, squeezing mill margins on fixed-price transformer contracts.
- Supply concentration in East Asia:Thin-gauge cold-rolling capacity clusters in South Korea and Japan, creating single-source risk for European automotive stampers.
- Technical ceiling at 6.5% silicon:Workability constraints block further core loss reduction without amorphous metal substitution in distribution transformers.
Strategic Opportunities
- India's renewable buildout:Wind turbine generator OEMs source locally-failed silicon steel as PLI scheme incentives attract cold-rolling investment.
- Amorphous metal convergence:Metglas ribbon annealing advances enable hybrid core designs combining silicon steel and amorphous layers for distribution transformers.
- Direct-to-stamper digital platforms:Coil distributors bypass traditional service centers to supply just-in-time electrical steel to automotive tier-1s in Michigan and Bavaria.
Industry Challenges
- Magnetic domain expertise shortage:Fewer metallurgists specialize in Goss texture control as universities shift toward battery materials research.
- Multi-grade certification timelines:IEC 60404-8-7 testing protocols delay new product qualification by 18-24 months for transformer OEMs.
- Legacy stamping press incompatibility:Thin-gauge high-silicon grades require tool steel upgrades and blanking clearance recalibration at motor manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrical Steel Market |
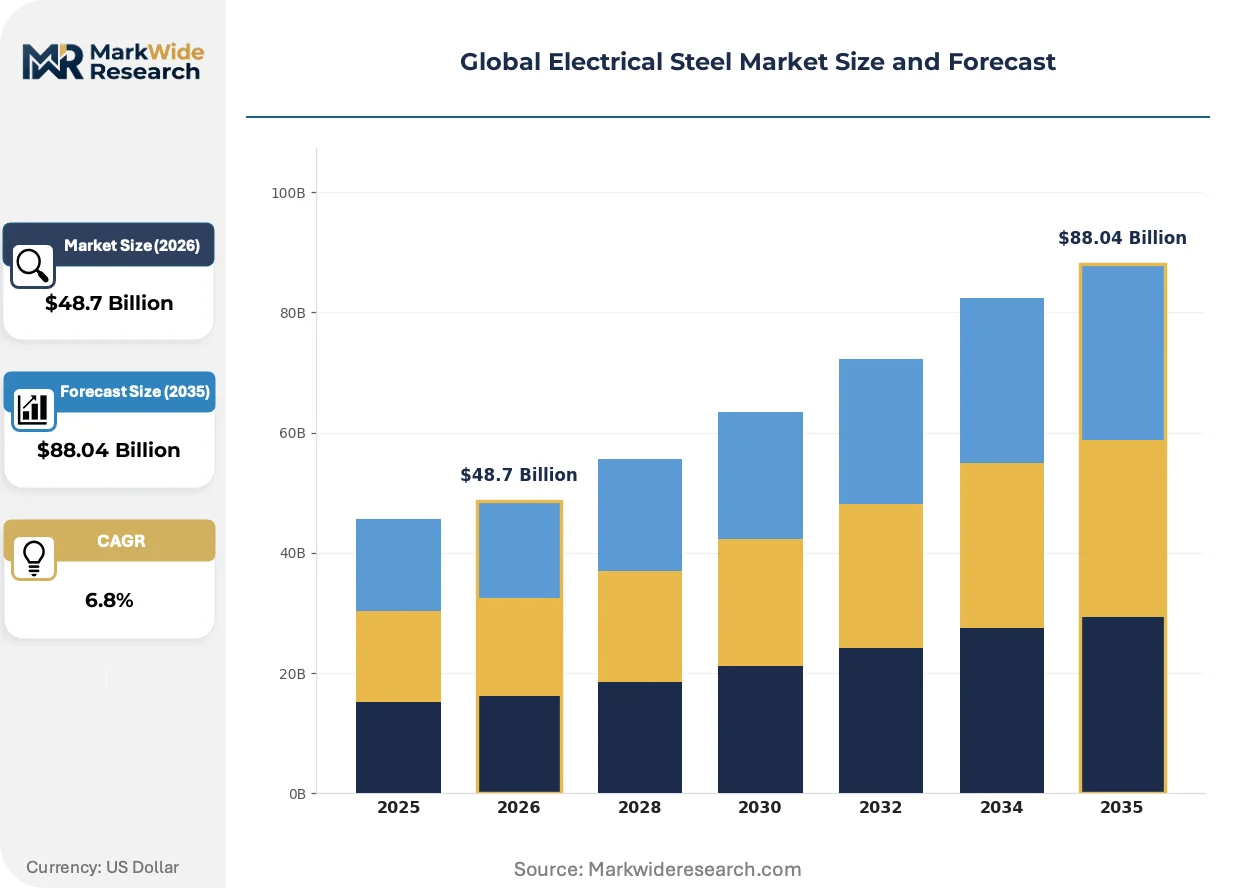
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Steel, Non-Silicon Steel, Lamination Steel, Cold-Rolled Steel End User: Transformers, Electric Motors, Generators, Inductors Form: Sheets, Coils, Strips, Bars Application: Power Generation, Transmission, Industrial Equipment, Renewable Energy |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, POSCO, China Baowu Steel Group, Baoshan Iron & Steel, Thyssenkrupp AG, JFE Steel Corporation, Tata Steel Limited, Voestalpine AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrical Steel Market Emerging Trajectories
Material science advances and regulatory efficiency floors are compressing the viable performance window for conventional electrical steel grades. Three developments dominate competitive positioning.
Thin-gauge 0.23mm and 0.27mm grain-oriented silicon steel is consolidating transformer procurement specifications across Europe and China. Grid operators in Poland and Spain now reject 0.30mm laminations for new substation builds. The technology is consolidating mid-grade producers into specialty niches or exit.
REACH and RoHS amendments tighten traceability requirements for electrical steel alloying elements. European transformer OEMs must document silicon source smelters and coating chemistry through supply chains. High-voltage direct current converter stations face the steepest compliance burden as they source from multi-continent coil suppliers.
Automotive motor buyers now specify core loss at 400Hz rather than 50Hz, reflecting inverter switching frequencies in EV powertrains. Tier-1 stamper qualification processes in Stuttgart and Shanghai prioritize high-frequency performance over legacy 50Hz metrics. This behavioral pivot redirects premium thin-gauge volumes from grid infrastructure toward mobility applications.
Global Electrical Steel Market Segmentation
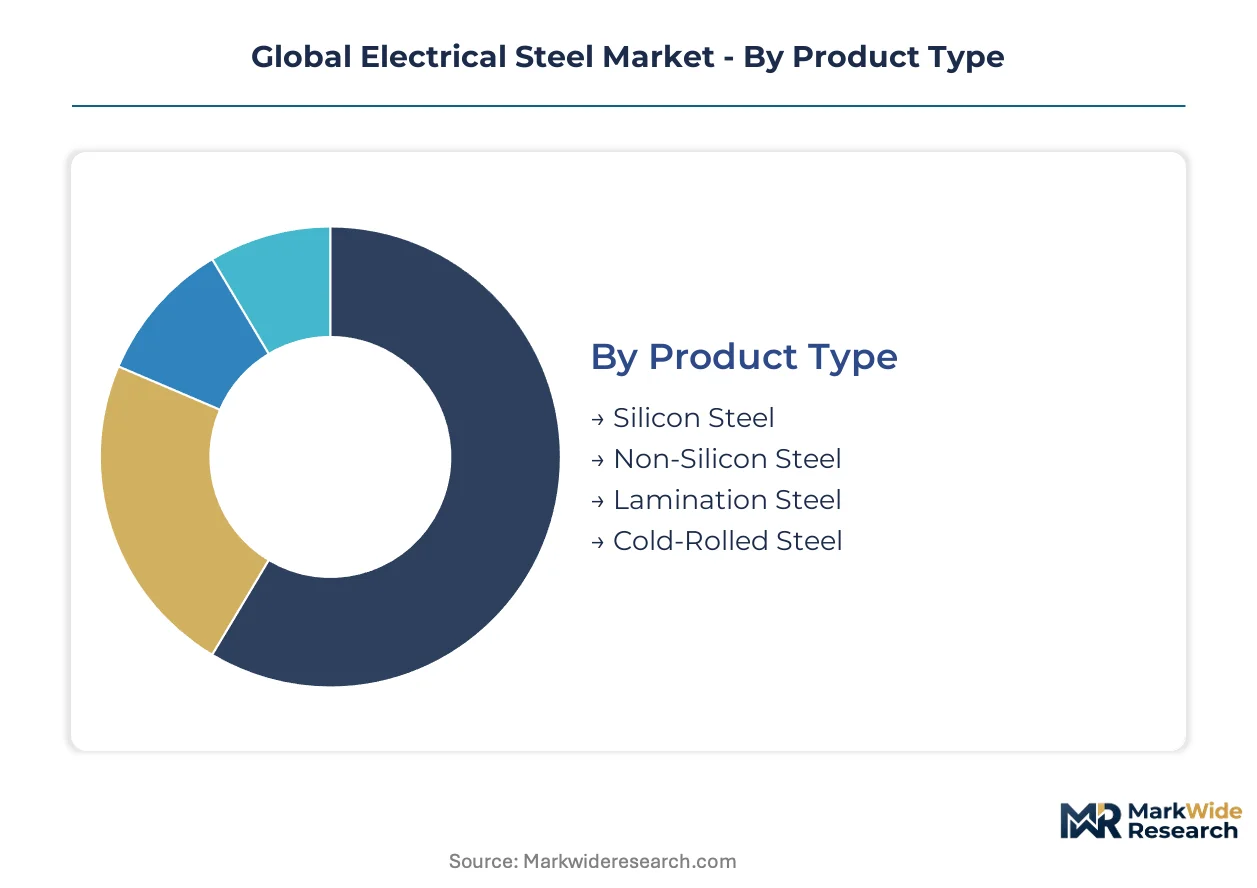
Electrical steel segmentation maps directly to magnetic performance requirements and manufacturing constraints. Product chemistry, end-use specifications, and form factors determine pricing tiers and supply chain routing across transformer, motor, and generator OEMs.
Product Type:
Volume concentrates in commodity silicon grades, while premium margins accrue to specialized alloys with tighter magnetic domain control.
- Silicon Steel:Iron-silicon alloys containing 1-4% silicon dominate transformer core laminations through controlled grain orientation. State Grid Corporation procurement in China and E.ON network upgrades in Germany absorb premium grain-oriented volumes for ultra-high-voltage corridors.
- Non-Silicon Steel:Low-carbon electrical steels without silicon additions serve cost-sensitive induction motor applications where core loss tolerance permits cheaper inputs. Indian small-motor manufacturers and Brazilian appliance producers favor this grade for fractional-horsepower stators.
- Lamination Steel:Pre-cut geometric blanks optimized for automated stacking in distribution transformer cores. Japanese transformer OEMs in Nagoya and Czech producers in Plzeň specify laser-cut laminations to minimize burr-induced eddy currents.
- Cold-Rolled Steel:General-purpose magnetic materials without anisotropic texture control for legacy equipment and repair markets. Russian rail traction motor rebuilders and Southeast Asian generator rewind shops source cold-rolled coils for non-critical rewind applications.
Today's leader: Silicon Steel. Tomorrow's challenger: Lamination Steel.
End User:
Application-specific magnetic loading patterns and operating frequencies dictate alloy selection and gauge thickness across customer segments.
- Transformers:Distribution and power transformer OEMs specify grain-oriented silicon steel with precise Goss texture for minimal hysteresis loss. EU F-Gas Regulation efficiency mandates in France and Italy accelerate procurement of 0.23mm thin-gauge grades.
- Electric Motors:Traction motor manufacturers for 800V EV architectures demand high-frequency performance validation at 400Hz. Tier-1 stampers in Stuttgart and Shanghai prioritize thin-gauge non-oriented steel with optimized silicon content for inverter-fed operation.
- Generators:Wind turbine generator builders source segmented core laminations with high permeability at low magnetizing force. Vestas nacelle assembly in Denmark and Goldwind manufacturing in Xinjiang specify thermally stable grades for variable-speed direct-drive machines.
- Inductors:Power electronics and automotive DC-DC converter applications require high saturation flux density with minimal core loss at elevated frequencies. German automotive tier-1s and Taiwanese power supply manufacturers specify specialized thin-gauge strips for compact magnetic components.
Transformers anchor current procurement volumes. Electric motors are climbing the fastest as EV production scales.
Form:
Manufacturing process economics and downstream stamping automation requirements segment supply by physical configuration.
- Sheets:Rectangular cut-to-length laminations for large power transformer core assembly. ABB and Siemens transformer factories in Switzerland and Germany specify width-tolerance-critical sheets for stepped-core construction.
- Coils:Continuous wound strip enabling high-speed progressive die stamping for automotive motor production. Hyundai Motor and BMW tier-1 suppliers in South Korea and Bavaria consume precision-slit coils for rotor and stator mass production.
- Strips:Narrow-width ribbon for segmented stator and specialized inductor winding. Japanese precision motor manufacturers and Swiss watchmaking equipment suppliers source slit strips for miniature electromagnetic applications.
- Bars:Solid cross-sections for DC motor field frames and specialty magnetic assemblies. Indian railway traction motor rebuilders and Brazilian mining equipment suppliers procure forged bars for legacy DC machine refurbishment.
Coils command the highest throughput. Sheets retain premium pricing through transformer OEM qualification barriers.
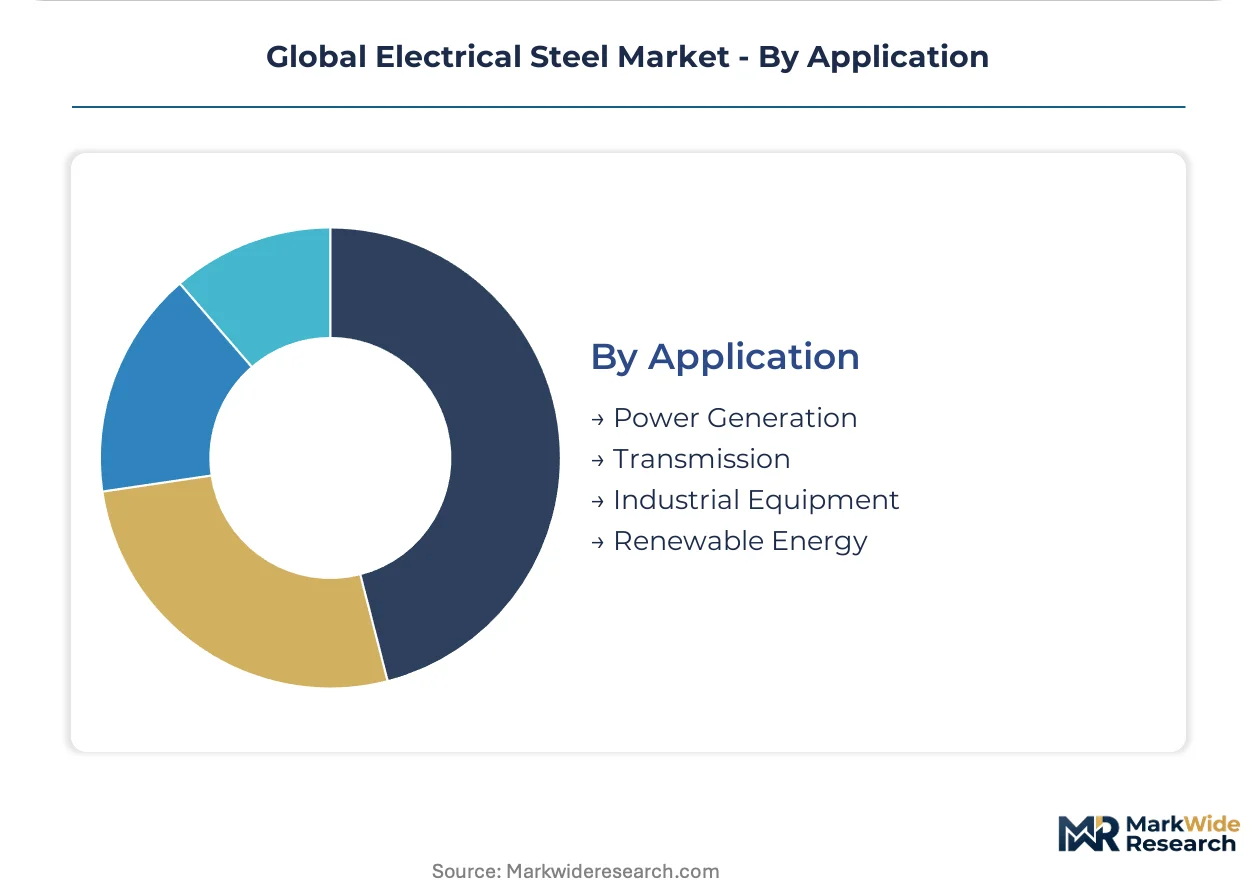
Application:
Grid infrastructure and mobility electrification create divergent performance specifications across end-use sectors.
- Power Generation:Turbo-generator rotor and stator laminations require high mechanical strength combined with magnetic softness. GE Vernova manufacturing in South Carolina and Harbin Electric in Heilongjiang specify creep-resistant grades for combined-cycle gas turbine generators.
- Transmission:High-voltage transformer cores and shunt reactor magnetic circuits demand ultra-low core loss at 50Hz/60Hz. National Grid substation procurement in the UK and Tennet network investment in the Netherlands specify IEC 60404-8-7 certified grades.
- Industrial Equipment:Pump, compressor, and conveyor motor cores prioritize cost-adjusted efficiency over absolute performance. Mexican maquiladora manufacturers and Turkish white goods producers specify mid-grade non-oriented steel for continuous-duty industrial motors.
- Renewable Energy:Wind turbine generators and solar inverter transformers require higher-grade laminations than conventional grid equipment. SGRE direct-drive generators in Denmark and Sungrow inverters in Anhui specify low-temperature-coefficient grades for variable loading profiles.
Transmission absorbs the largest tonnage. Renewable Energy shows the steepest expansion trajectory as capacity buildouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration tracks diverging carbon border adjustment timelines and transformer efficiency mandates, with mills relocating cold-rolling capacity toward jurisdictions offering compliance cost advantages. China and South Korea absorb investment in thin-gauge electrical steel as European carbon costs reshape procurement geography.
China
State Grid Corporation procurement rules and MIIT directives on ultra-high-voltage transmission infrastructure absorb domestic premium silicon steel volumes. The country's dual carbon goals enforce domestic content requirements for grid equipment. Manufacturing clusters in Shanghai and Baoshan anchor integrated production from hot rolling through final annealing.
Germany
E.ON and Tennet network investment programs accelerate procurement of 0.23mm thin-gauge grades for distribution transformer fleets. EU F-Gas Regulation efficiency mandates tighten loss standards across Bavaria and North Rhine-Westphalia. Siemens Energy manufacturing in Nuremberg specifies IEC-certified laminations for stepped-core construction.
United States
Department of Energy appliance efficiency rules and NHTSA EV motor benchmarks indirectly shape electrical steel specifications through downstream demand. FERC grid reliability standards influence transformer procurement for utility-scale infrastructure. Automotive tier-1 stampers in Michigan source precision-slit coils for traction motor production.
India
Wind turbine generator OEMs and solar inverter transformer builders source silicon steel as PLI scheme incentives attract cold-rolling investment. CEA procurement guidelines favor higher-efficiency grades for renewable integration. Manufacturing in Maharashtra and Gujarat concentrates lamination stamping for domestic transformer assembly.
Japan
METI energy efficiency standards and JIS certification requirements maintain premium-grade demand for precision motor applications. Thin-gauge production in Nagoya and Tokyo Bay industrial corridors supplies automotive and industrial equipment segments. JFE Steel and Nippon Steel operations anchor specialized annealing capacity for high-frequency grades.
Global Electrical Steel Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated mills add thin-gauge cold-rolling lines to capture EV motor and renewable transformer demand. The vendor base clusters around three strategic archetypes: diversified steel conglomerates with full metallurgical control, regional specialists focused on transformer-grade laminations, and automotive-centric stampers with captive coil supply. M&A activity and backward integration into silicon metal sourcing represent the primary competitive vectors as margin pressure intensifies.
Within the diversified conglomerate tier, ArcelorMittal and POSCO exemplify scale-driven positioning through integrated flat-rolled capacity spanning ore through finished electrical steel. Nippon Steel Corporation occupies a specialist position in high-frequency grades for precision motor applications. These three anchors demonstrate how geographic proximity to end-use clusters—European grid infrastructure, Asia-Pacific automotive stamping, and Japanese precision manufacturing—shapes competitive differentiation without requiring identical capability profiles.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| POSCO |
| China Baowu Steel Group |
| Baoshan Iron & Steel |
| Thyssenkrupp AG |
| JFE Steel Corporation |
| Tata Steel Limited |
| Voestalpine AG |
| Others |
Supply Flow & Price Mechanics
State Grid Corporation and E.ON procurement programs concentrate buyer power across premium transformer-grade volumes, anchoring contract-based long-term offtake pricing with volume-tier discounts for ultra-low-loss specifications. This buyer concentration forces mills to absorb ferrosilicon cost volatility while maintaining fixed-price commitments for multi-year grid infrastructure rollouts.
Pricing Analysis
Distributor margins for electrical steel coil supply to automotive tier-1 stampers run 8-12 percent above direct mill pricing to transformer OEMs. Three-tier pricing structure across premium grain-oriented, standard non-oriented, and economy cold-rolled grades reflects IEC 60404-8-7 certification tiers and silicon content precision. Cost compression in mid-grade non-oriented steel is intensifying because Indian and Southeast Asian mills are adding capacity ahead of qualification timelines. Distribution transformer OEMs in Poland and Spain exhibit highest price sensitivity due to competitive bidding mandates, while EV motor stampers in Bavaria and Michigan accept premium thin-gauge pricing for high-frequency performance validation.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Busan anchor hub-and-spoke patterns for coil inventory positioning near automotive stamping clusters. Manufacturing concentration in China, South Korea, and Japan controls thin-gauge cold-rolling capacity for high-frequency grades. Ferrosilicon smelter output, specialty coating chemicals, and precision slitting equipment draw from Chinese and German supplier bases. Single-source vulnerability in 0.23mm grain-oriented steel creates exposure for European transformer builders dependent on Nagoya and Pohang mill allocations. Distribution runs through mill-direct programs for large transformer OEMs and specialized coil distributors serving automotive tier-1s.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrical steel has entered a late-cycle quality phase where transformer loss standards and EV motor frequency specifications are compressing viable supply to certified premium grades. The demand shift toward 0.23mm thin-gauge grain-oriented steel for EU Green Deal compliance validates margin concentration at the specification ceiling.
For Market Incumbents: Deploy backward integration into ferrosilicon smelting to secure input cost stability against Chinese environmental curbs. Add thin-gauge annealing capacity in Poland or Michigan to capture automotive coil demand without trans-Pacific logistics exposure. Amorphous metal substitution threats in distribution transformers require hybrid core R&D investment to defend laminations market share. For New Entrants and Emerging Players: Capture India's renewable transformer lamination segment where PLI scheme incentives and CEA procurement guidelines favor local cold-rolling investment. Target wind turbine generator OEMs in Gujarat and Maharashtra with segmented core stamping capabilities. Qualify through direct-to-stamper digital platforms bypassing established service center relationships. For Investors and Strategic Acquirers: Diversified steel conglomerates with flat-rolled electrical steel capacity are the most active acquirers in this space, seeking metallurgical control from ore through finished coil. Five-to-ten year viability hinges on thin-gauge certification breadth and carbon border adjustment readiness. Acquisition targets should display IEC 60404-8-7 multi-grade qualification and proximity to EV motor or renewable transformer clusters. Monitor EU carbon border adjustment mechanism implementation timelines as the critical inflection signal for production geography repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Gauge Cold-Rolling Capacity Expansion | Captures EV motor demand from BMW and Hyundai tier-1 stampers requiring 0.23mm high-frequency grades. |
| Backward Integration into Ferrosilicon Smelting | Insulates mill margins from Chinese environmental curbs affecting silicon metal input costs. |
| IEC 60404-8-7 Multi-Grade Certification Investment | Accelerates transformer OEM qualification timelines currently delaying new product adoption by 18-24 months. |
| Direct-to-Stamper Digital Platform Launch | Bypasses traditional service centers to supply just-in-time coils to automotive tier-1s in Michigan and Bavaria. |
| Hybrid Core R&D Combining Silicon Steel and Amorphous Layers | Defends distribution transformer market share against Metglas ribbon substitution threats. |
Methodological Framework
Multiple input streams — primary interviews with transformer OEM procurement directors, EV motor stamper supply chain managers, and electrical steel mill technical directors; secondary validation through SEC filings, MIIT directive documentation, and IEC certification registries; customs trade data and State Grid Corporation procurement disclosures — were reconciled through bottom-up volume builds and top-down market sizing cross-checks.
Data-stream reconciliation anchored volume and value outputs across product type, end user, form factor, and application dimensions over the projection horizon. CAGRs were derived from segment-level growth rate synthesis and elasticity modeling against EV production forecasts and renewable capacity buildout trajectories. Forecast inputs included transformer loss standard compliance timelines, thin-gauge cold-rolling capacity expansion announcements, and ferrosilicon price elasticity assumptions.
Silicon metal supply disruptions, carbon border adjustment implementation delays, and amorphous metal technology breakthroughs are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on grade migration rates and certification timeline stickiness. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Medium Voltage Electric Drives Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Europe Busbar Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
Contactors Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
Passover Humidifiers Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
US Industrial Ceiling Fan Market
Electrical Equipment
Middle East and Africa Busbar Market
Electrical Equipment
GCC Ceiling Fan Market
Electrical Equipment
Motor Control Centers (MMC) Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
Flexible Heating Element Market