
 Global Cooling Fan Market | 2026-2036
Global Cooling Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cooling Fan Market Analysis
ISO 9001 and IATF 16949 qualification cycles is collapsing the supplier base for automotive and industrial OEMs, forcing smaller fan manufacturers to consolidate or exit. Delta Electronics Inc. leverages its vertical integration in motor-drive electronics to sustain pricing power across server-cooling segments. ebm-papst Group anchors European industrial demand with energy-optimized EC motor platforms that dominate HVAC retrofit specifications.
Cooling fans are electromechanical devices comprising impeller blades, motor assemblies, and housing structures designed to move air for thermal management, with critical parameters including static pressure, airflow rate measured in cubic feet per minute, and noise levels expressed in decibels. DC motor technology leads efficiency benchmarks in electronics cooling, while smart fans with variable-speed controls and IoT connectivity represent the fastest-expanding margin pool as building automation systems proliferate. Energy-efficient fans command premium positioning in commercial retrofits where operational cost reduction drives procurement criteria.
The EPA in the United States enforces energy conservation standards under the Energy Policy Act that mandate minimum efficiency thresholds for residential and commercial fan systems, while the EU Ecodesign Directive and F-Gas Regulation compel manufacturers to redesign products for lower electrical input power and reduced refrigerant dependency. China's MIIT enforces GB standards for motor efficiency that directly impact cooling fan specifications sold into industrial and data center applications. Stakeholders must monitor how tightening efficiency mandates across multiple jurisdictions will reshape motor technology roadmaps and sourcing strategies for impeller materials and drive electronics.
Market Dynamics
Data center operators are consolidating thermal management specifications around liquid-ready air handlers, compressing design cycles for traditional axial fan suppliers and forcing motor-drive electronics integration at the impeller level.
Growth Catalysts
- Hyperscale Facility Expansion:Cloud infrastructure deployment in India and the United States is pulling high-static-pressure centrifugal systems into bulk procurement frameworks with multi-year supply agreements.
- F-Gas Regulation:The EU mandate is accelerating indirect cooling architectures that depend on high-efficiency EC motor platforms for reduced refrigerant dependency.
- Industrial Electrification:Manufacturing automation in India is driving axial fan demand for motor cooling, variable frequency drives, and power electronics thermal management.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings from Chinese export controls are compressing margins for permanent-magnet synchronous motor designs.
- Supplier Consolidation:ISO 9001 and IATF 16949 qualification cycles are collapsing the certified vendor base for automotive and industrial OEMs, concentrating procurement risk.
- Technical Ceiling:Axial fan aerodynamics face fundamental limits on static pressure generation, blocking penetration into high-resistance liquid cooling cold plates.
Strategic Opportunities
- Building Automation Convergence:IoT-enabled variable-speed controls and BACnet integration are opening premium positioning in commercial HVAC retrofit specifications.
- India Industrial Cluster Growth:Commercial real estate expansion in Mumbai, Bangalore, and Hyderabad is creating demand for energy-optimized EC motor platforms.
- US Energy Policy Act:EPA efficiency thresholds are mandating minimum performance standards that favor electronically commutated motor technology over shaded-pole alternatives.
Industry Challenges
- Embedded Software Competency Gap:Fan manufacturers lack firmware engineering depth for motor control algorithms, sensor fusion, and predictive maintenance analytics.
- Multi-Jurisdiction Certification Burden:Simultaneous compliance with EPA Energy Policy Act, EU Ecodesign Directive, and China MIIT GB standards extends product launch timelines.
- Legacy System Integration Friction:Smart fan retrofits require protocol bridging to existing BAS infrastructure, complicating field commissioning and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cooling Fan Market |
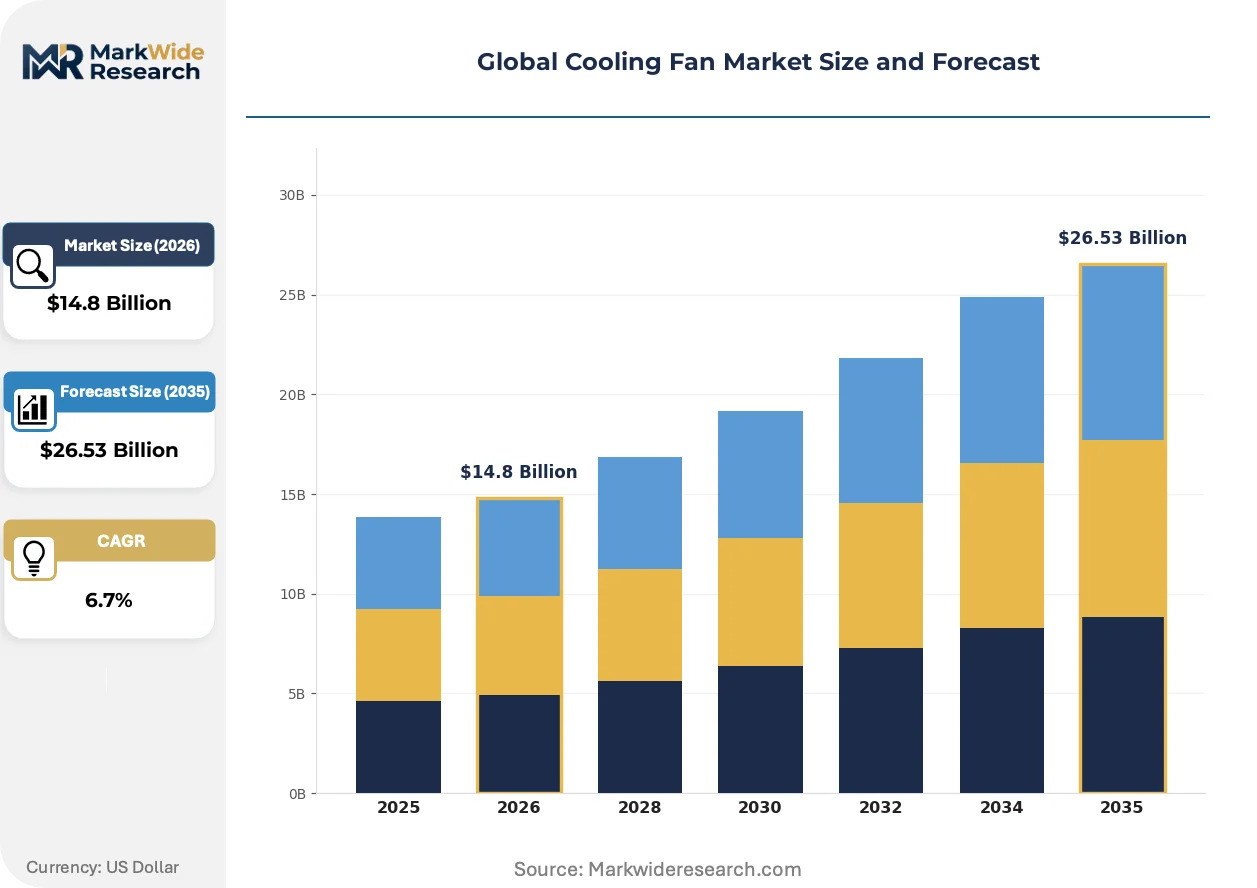
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling Fans, Table Fans, Pedestal Fans, Exhaust Fans Application: Residential, Commercial, Industrial, Automotive Technology: DC Motor, AC Motor, Smart Fans, Energy-Efficient Fans End User: Homeowners, Office Spaces, Factories, Retail Outlets |
| Companies Covered | Delta Electronics Inc., Multi-Wing America Inc., ebm-papst Group, Greenheck Fan Corporation, Rosenberg Ventilatoren GmbH, Ziehl-Abegg SE, Horton Holding GmbH & Co. KG, SPX Cooling Technologies, NIDEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cooling Fan Market Emerging Trajectories
Electrification of thermal management is compressing product lifecycles and collapsing the boundary between component suppliers and system integrators. Three forces are actively restructuring competitive positioning.
Magnetic bearing technology is fragmenting the high-reliability segment previously dominated by ball-bearing assemblies. Data center operators in the United States are specifying oil-free levitation for continuous-duty cooling towers and CRAC units. This shift is fragmenting the supplier base into magnetic actuator specialists and traditional impeller manufacturers lacking in-house magnetic circuit design.
REACH substance restrictions and EU F-Gas Regulation are forcing material substitutions in motor windings and impeller resins. Manufacturers are reformulating insulation systems to eliminate halogenated flame retardants and high-GWP blowing agents. HVAC OEMs in Germany and France are responding with accelerated validation programs for bio-based thermoplastics and vacuum-pressure-impregnated winding techniques.
Direct procurement from fan manufacturers is displacing traditional distribution channels in the data center vertical. Hyperscale operators in India and the United States are engaging Delta Electronics and ebm-papst on master service agreements that bypass mechanical contractors. This channel compression is most visible in server-cooling segments where thermal design authority has shifted from OEMs to facility operators.
Global Cooling Fan Market Segmentation
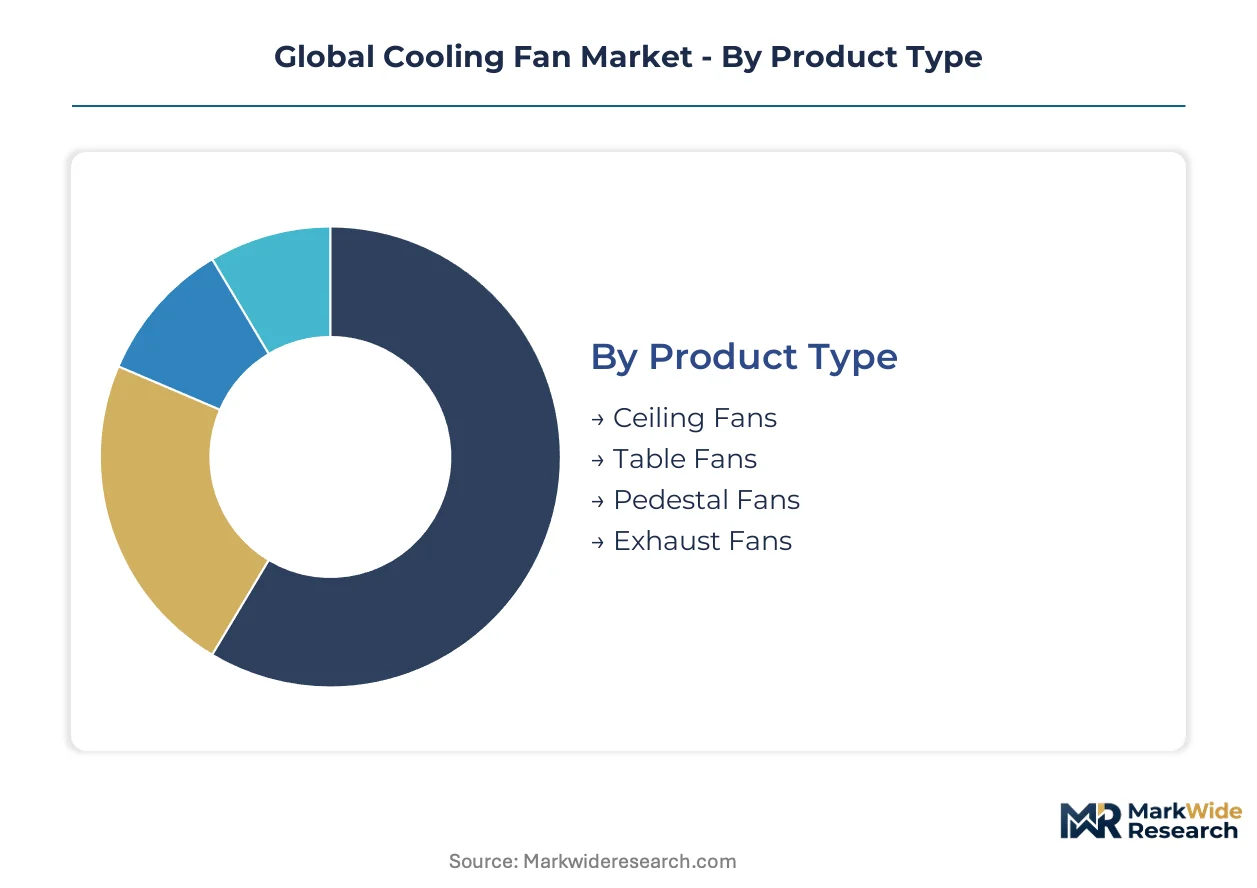
Cooling fan procurement patterns diverge sharply across residential, commercial, and industrial verticals, with specification authority shifting from distributors to end-users in data center and automotive applications. Segmentation clarity enables suppliers to align motor technology roadmaps with distinct efficiency mandates and channel structures.
Product Type:
Domestic consumption dominates ceiling and table fan procurement in India and Southeast Asia, while exhaust and pedestal systems serve export-led industrial markets in Germany and the United States.
- Ceiling Fans:These units incorporate AC induction or BLDC motor platforms with blade spans ranging from 900mm to 1400mm. Demand concentrates in Indian residential construction, where BIS energy labeling mandates and PLI scheme subsidies accelerate EC motor adoption. The steepest expansion runs through smart-enabled variants with IoT connectivity.
- Table Fans:Compact portable units with 300mm to 400mm blade diameters and tilting head mechanisms serve seasonal cooling needs. Office spaces in Mumbai, Delhi, and Bangalore drive bulk procurement during pre-monsoon months, with price sensitivity limiting DC motor penetration to premium tiers.
- Pedestal Fans:Height-adjustable standing units with oscillating grilles target commercial lobbies and factory floor stations. German industrial OEMs specify these for localized airflow in automotive assembly plants where HVAC zoning proves cost-prohibitive.
- Exhaust Fans:Wall- and roof-mounted ventilation systems with static pressure ratings from 50 to 250 Pa remove heat, moisture, and contaminants. Food processing facilities in France and pharmaceutical cleanrooms in Switzerland mandate corrosion-resistant housings and IP55 motor enclosures.
Ceiling fans command the established base. The steepest expansion runs through exhaust systems.
Application:
Cost tiers separate commodity residential units from precision-engineered automotive and industrial systems requiring vibration damping and EMI compliance.
- Residential:Mass-market cooling for apartments and single-family dwellings prioritizes noise reduction below 35 dB and energy efficiency compliance with EPA Energy Policy Act thresholds. Indian urban clusters in Hyderabad and Chennai drive volume through affordable housing programs.
- Commercial:Office buildings, hotels, and retail environments demand BACnet-integrated variable-speed controls for demand-responsive HVAC operation. French commercial real estate retrofits under EU Ecodesign Directive specifications favor EC motor platforms with 30% lower input power.
- Industrial:Heavy-duty axial and centrifugal systems manage thermal loads in steel mills, chemical plants, and power generation facilities. Chinese MIIT GB motor efficiency standards dictate minimum IE3 ratings for fans sold into industrial automation clusters in Shenzhen and Suzhou.
- Automotive:Underhood cooling, battery thermal management, and cabin HVAC systems require compact brushless DC motors with -40°C to 125°C operating ranges. IATF 16949 qualification barriers concentrate procurement among Tier-1 suppliers serving electric vehicle platforms in the United States and Germany.
Industrial applications anchor revenue stability. Automotive electrification is climbing the fastest.
Technology:
Volume concentration in AC motor legacy systems contrasts with margin expansion in digitally controlled smart platforms.
- DC Motor:Brushless DC and electronically commutated architectures deliver 70% efficiency gains over AC alternatives through precision speed control. Data center operators in Virginia and Texas specify these for server rack cooling where power usage effectiveness drives facility economics.
- AC Motor:Shaded-pole and capacitor-run induction motors dominate price-sensitive residential markets despite efficiency penalties. Indian mass-market distribution channels maintain AC motor share through sub-$20 retail pricing.
- Smart Fans:Wi-Fi and Bluetooth-enabled units with mobile app control, voice assistant integration, and occupancy-based automation command 40-60% retail premiums. US building automation convergence in commercial retrofits accelerates specification.
- Energy-Efficient Fans:ENERGY STAR-certified and EU Ecodesign-compliant systems with aerodynamically optimized blade profiles reduce operational expenditure. German HVAC contractors prioritize these for public sector tenders with lifecycle cost evaluation criteria.
AC motor systems command the established base. Smart connectivity is gaining share fastest.
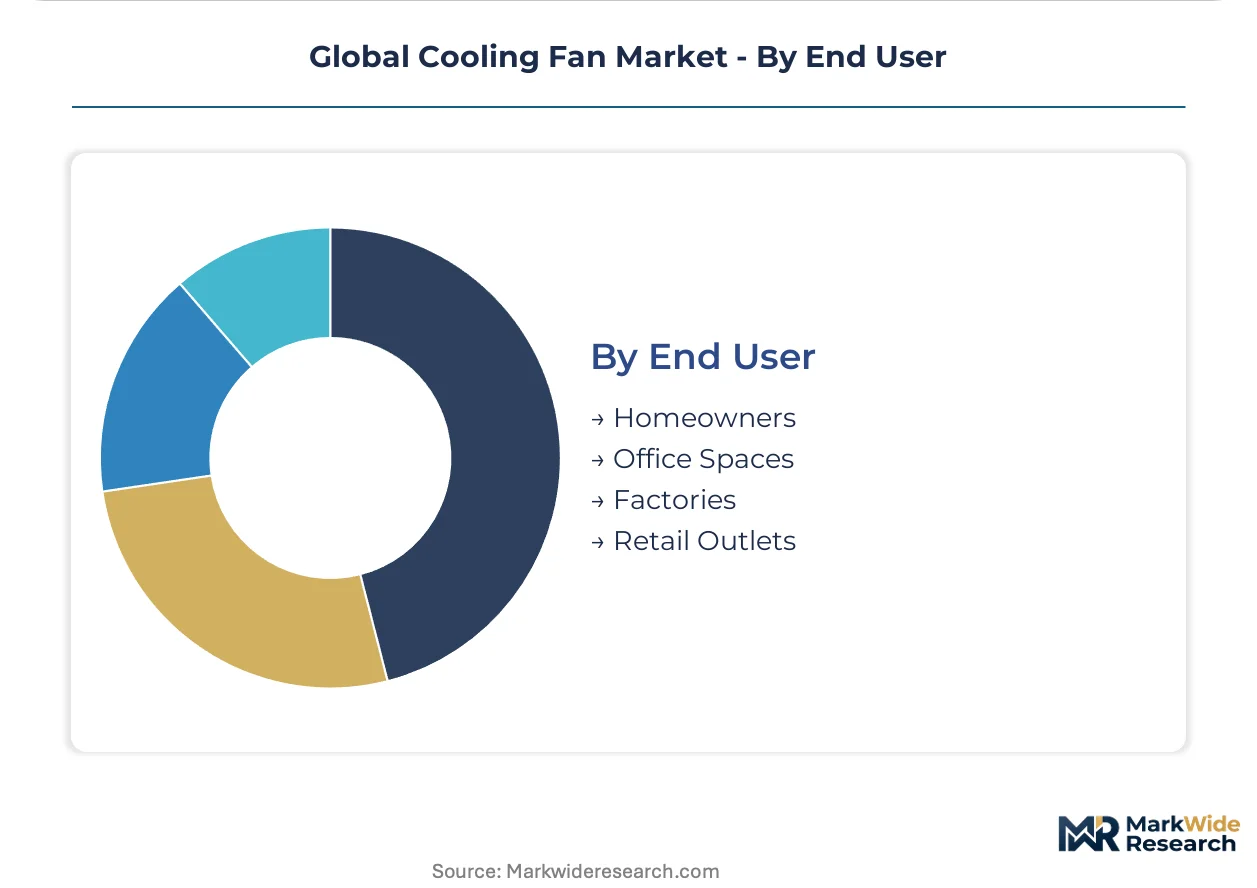
End User:
Customer type determines channel structure, with direct procurement displacing distribution in factory and retail outlet verticals.
- Homeowners:Individual purchasers through retail and e-commerce channels prioritize aesthetics, noise levels, and seasonal discounts. Indian online marketplaces drive private-label growth with aggressive pricing on BLDC ceiling fans.
- Office Spaces:Corporate facilities managers specify centralized procurement frameworks with 5-year maintenance agreements. French and German commercial property operators bundle fan upgrades with building energy management system deployments.
- Factories:Industrial maintenance departments source heavy-duty ventilation through direct manufacturer relationships, bypassing mechanical contractors. Hyperscale data center operators in India and the United States negotiate master service agreements with Delta Electronics and ebm-papst.
- Retail Outlets:Big-box and specialty retailers demand point-of-sale display support, seasonal inventory financing, and markdown protection. US home improvement chains specify exclusive SKUs with differentiated feature sets to prevent price matching.
Homeowners anchor volume throughput. Factory direct procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy efficiency mandates and industrial electrification programs are redirecting cooling fan procurement toward high-performance motor platforms across major manufacturing economies. Government incentives for data center construction and building automation retrofits are concentrating demand in specific national markets. The analysis tracks five countries where regulatory pressure and infrastructure investment are reshaping supplier relationships.
United States
Hyperscale data center expansion in Virginia and Texas is pulling high-static-pressure centrifugal systems into multi-year supply agreements. The EPA enforces Energy Policy Act efficiency thresholds that favor electronically commutated motor technology over shaded-pole alternatives. Server farm clusters in Loudoun County and Dallas-Fort Worth are consolidating thermal management specifications around liquid-ready air handlers.
Germany
HVAC retrofit specifications under EU Ecodesign Directive mandates are accelerating EC motor platform adoption in commercial real estate. The F-Gas Regulation compels manufacturers toward indirect cooling architectures with reduced refrigerant dependency. Industrial automation corridors in Bavaria and Baden-Württemberg specify energy-optimized fans for motor cooling and power electronics thermal management.
India
Industrial electrification and commercial real estate growth in Mumbai, Bangalore, and Hyderabad are driving bulk procurement of axial and centrifugal systems. The BIS energy labeling mandate and PLI scheme subsidies accelerate EC motor adoption in ceiling fan manufacturing. Automotive and electronics manufacturing clusters in Tamil Nadu and Maharashtra source compact brushless DC motors for underhood cooling and battery thermal management.
China
MIIT GB motor efficiency standards dictate minimum IE3 ratings for fans sold into industrial automation clusters in Shenzhen and Suzhou. Data center construction in the Yangtze River Delta and Pearl River Delta is absorbing high-volume shipments of server rack cooling equipment. The country's dual carbon goals are compressing design cycles for legacy AC motor platforms in favor of precision speed control architectures.
Japan
Precision manufacturing and semiconductor fabrication facilities in Kanto and Kansai regions require vibration-damped cooling systems with EMI compliance. METI efficiency programs and JIS standards guide motor technology roadmaps for industrial applications. Electronics OEMs in the Nagoya industrial corridor specify compact axial fans for power electronics thermal management in robotics and automation equipment.
Global Cooling Fan Market Vendor Landscape
Player mix skews toward vertically integrated motor-drive specialists and regional HVAC component fabricators. The supplier base concentrates around three strategic tiers: multinational electronics conglomerates with captive semiconductor capabilities, European precision motor specialists with energy-optimized platforms, and Asian volume manufacturers serving price-sensitive residential markets. Competitive moves center on backward integration into rare earth magnet supply chains and strategic partnerships with data center facility operators for direct procurement relationships.
Among the vertically integrated tier, Delta Electronics Inc. and ebm-papst Group exemplify contrasting geographic anchors for motor technology leadership. Delta Electronics Inc. occupies a position within the server-cooling segment where thermal design authority has shifted toward facility operators. The ebm-papst Group represents the European precision archetype with dominance in HVAC retrofit specifications. NIDEC Corporation sits within the scale-driven tier of compact motor manufacturing for automotive and electronics applications.
| Leading Market Players |
|---|
| Delta Electronics Inc. |
| Multi-Wing America Inc. |
| ebm-papst Group |
| Greenheck Fan Corporation |
| Rosenberg Ventilatoren GmbH |
| Ziehl-Abegg SE |
| Horton Holding GmbH & Co. KG |
| SPX Cooling Technologies |
| NIDEC Corporation |
| Others |
Supply Flow & Price Mechanics
EC motor substitution for legacy AC induction platforms is simultaneously shifting supply geography toward China and Germany while compressing pricing power in residential tiers. This material transition forces manufacturers to absorb rare earth magnet volatility or surrender margin to vertically integrated competitors with captive motor-drive electronics.
Pricing Analysis
Certification level creates the primary spread between automotive IATF 16949-qualified systems and commodity residential units. Three-tier pricing structure across premium EC motor platforms, mid-grade BLDC variants, and economy AC induction systems dominates procurement frameworks. Cost compression in the economy tier is intensifying because Chinese volume manufacturers are flooding Indian distribution channels with sub-$20 ceiling fans. Data center operators exhibit the lowest price sensitivity, prioritizing power usage effectiveness over unit cost.
Supply Chain Analysis
Inventory buffers for neodymium magnets and silicon steel laminations have stretched to 12-16 weeks following Chinese export control announcements. Manufacturing concentrates in China, Germany, and India, with each hub serving distinct specification tiers. The supply chain draws from rare earth mining operations in Inner Mongolia, precision stamping facilities in Bavaria, and wound-motor assembly clusters in Tamil Nadu. Single-source vulnerability in permanent-magnet supply creates concentration risk. Distribution runs through direct master service agreements with hyperscale data center operators, bypassing traditional mechanical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cooling fan market sits in early-cycle expansion as data center liquid-ready architectures and EU F-Gas Regulation mandates accelerate specification upgrades. Industrial electrification in India and automotive thermal management electrification create parallel penetration runways.
For Market Incumbents: Fortify backward integration into motor-drive electronics and rare earth magnet sourcing to defend against Delta Electronics and NIDEC Corporation's captive supply advantages. Accelerate IATF 16949 and ISO 9001 certification investments to collapse the qualified supplier base and deepen switching costs for automotive OEMs. For New Entrants and Emerging Players: CE marking fast-track programs for EC motor platforms open immediate access to German HVAC retrofit specifications under EU Ecodesign Directive mandates. Target India's commercial real estate clusters in Hyderabad and Bangalore with energy-optimized axial systems. Pursue white-label partnerships with Indian online marketplaces to bypass established distribution markups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European precision motor specialists holding energy-optimized EC platforms but lacking data center direct procurement relationships. The five-to-ten year viability window favors targets with firmware engineering depth for predictive maintenance analytics. Monitor hyperscale data center capex announcements as the inflection signal for server-cooling demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Motor-Drive Electronics Integration | Captive semiconductor capabilities at Delta Electronics compress design cycles for axial fan suppliers. |
| EC Motor Platform Expansion | ebm-papst Group anchors German HVAC retrofit specifications with energy-optimized architectures. |
| Rare Earth Magnet Backward Integration | Upstream control over neodymium supply hedges Chinese export control volatility for permanent-magnet designs. |
| Direct Procurement Relationships | Master service agreements with Virginia and Texas data center operators displace mechanical contractor channels. |
| Smart Fan Firmware Development | Predictive maintenance analytics capability addresses the embedded software competency gap among traditional manufacturers. |
Methodological Framework
The analysis maps axial, centrifugal, and tangential fan sub-sectors, each validated through facility engineering directors, HVAC contractor procurement leads, and motor-drive electronics specialists. Primary interviews with data center thermal design authorities, automotive Tier-1 supplier quality managers, and Indian commercial real estate developers combined with secondary validation against EPA Energy Policy Act filings, EU Ecodesign Directive compliance databases, and China MIIT GB standard certifications. Bottom-up unit shipment modeling and top-down value triangulation anchored segmentation outputs.
Consistency checks against hyperscaler capex disclosures and HVAC OEM revenue breakdowns validated volume and value outputs across the projection horizon. The analytical framework modeled product type, application vertical, motor technology tier, and end-user channel structure. CAGRs derived from segment-level growth rate reconciliation with macro drivers including industrial electrification penetration and data center construction permits. Forecast inputs incorporated F-Gas Regulation phase-out schedules and BIS energy labeling mandate compliance timelines.
Decision-makers should treat outputs as directional under assumptions of sustained rare earth magnet supply continuity and stable EPA efficiency threshold enforcement; material deviation would warrant model refresh. Specific risk factors include Chinese export control escalation, EU refrigerant regulation acceleration, and automotive platform electrification delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Contactors Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
High-Vacuum Fiber Feedthrough Flanges Market
Electrical Equipment
China DC Motor Market
Electrical Equipment
Low Voltage Circuit Breakers Market
Electrical Equipment
US Industrial Ceiling Fan Market
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
Global Electric Plugs and Sockets Market