
 Trioctyldodecyl Citrate Market | 2026-2036
Trioctyldodecyl Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Trioctyldodecyl Citrate Market Analytics
Technical service agreements for custom emollient blends is shifting how specialty chemical suppliers monetize relationships beyond base product sales. Siltech leverages its silicone-organic hybrid expertise to anchor premium positioning in skin-feel modification. Lubrizol sustains broad formulation support capabilities that extend its reach across multinational cosmetic houses. BASF SE dominates large-scale citrate ester production with backward integration into citric acid feedstocks.
Trioctyldodecyl citrate functions as a branched-chain citric acid ester synthesized via esterification of citric acid with 2-octyldodecanol, yielding a colorless oily liquid with a molecular weight near 757 g/mol and pour point below -30°C that imparts exceptional spreadability and oxidative stability in cosmetic formulations. The emollients category leads volume absorption due to its centrality in premium skincare and color cosmetic bases where sensorial performance commands price premiums. Plasticizers for nail care and flexible packaging applications represent the fastest-growing structural pocket as waterborne formulation trends intensify demand for non-phthalate alternatives. Solvents occupy a mature position in industrial cleaning applications with thinner margin pools relative to personal care grades.
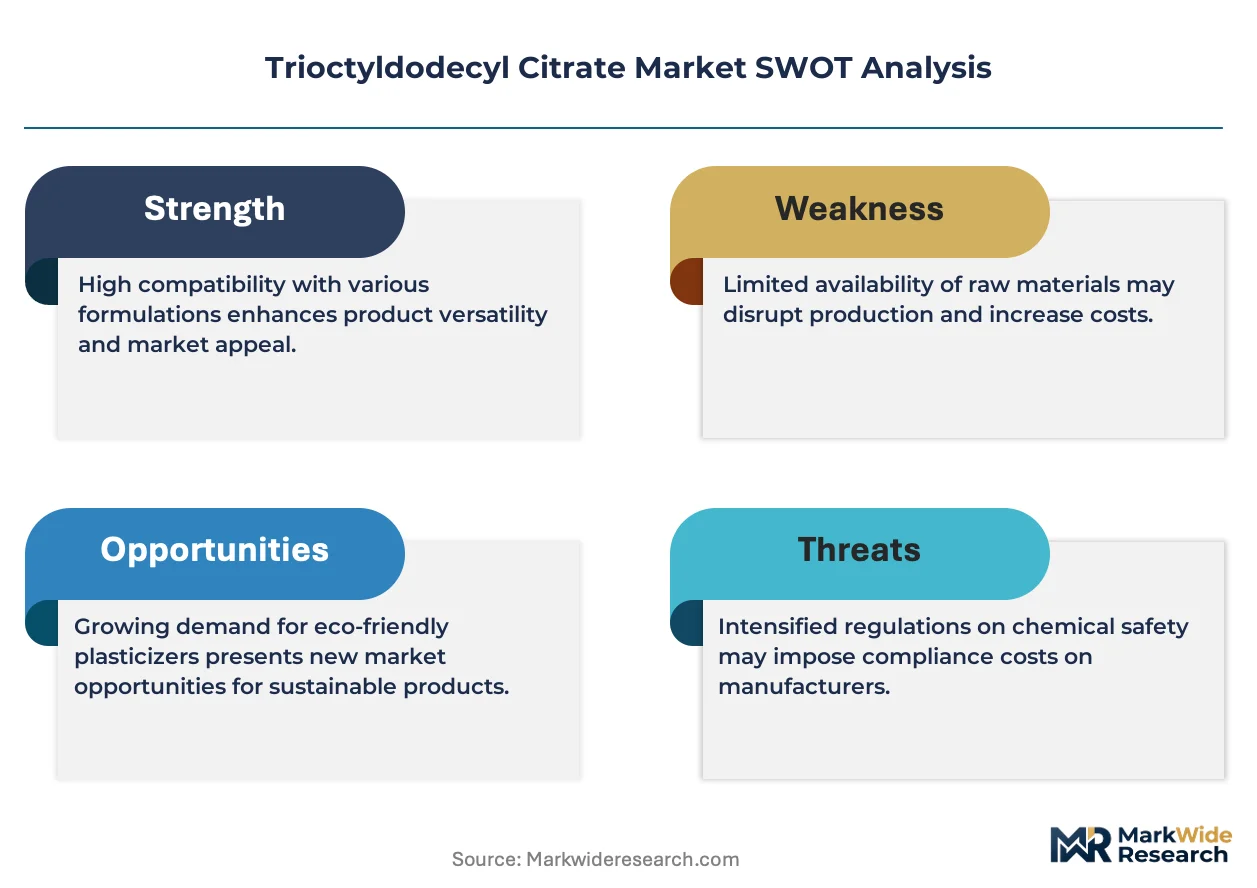
REACH registration requirements administered by ECHA mandate full toxicological dossiers for citrate ester imports above one tonne annually into EU member states, elevating compliance costs for non-European suppliers. FDA cosmetic ingredient regulations under the Modernization of Cosmetics Regulation Act now impose mandatory adverse event reporting and facility registration, reshaping how foreign manufacturers access US distribution channels. China's NMPA and GB standards for cosmetic raw materials impose separate safety assessment protocols that fragment market access requirements. Stakeholders must monitor divergence between EU hazard classification approaches and emerging clean beauty certification schemes to anticipate which formulation standards will propagate across downstream customer specifications.
Market Dynamics
Clean beauty certification schemes and REACH compliance requirements are compressing formulation timelines while elevating technical service demands on citrate ester suppliers. Formulators now require documented biodegradability profiles and supply chain transparency that reshape procurement criteria.
Growth Catalysts
- Clean Beauty Mandates:North American retailers are enforcing ingredient disclosure standards that favor citrate esters over petroleum-derived emollients. Formulators reformulate legacy products to meet Sephora Clean and Ulta Conscious Beauty specifications.
- Waterborne Nail Care Transition:South Korean manufacturers are accelerating non-phthalate plasticizer adoption for flexible packaging and nail enamel applications. Trioctyldodecyl citrate delivers film-forming performance without regulatory baggage.
- ECHA REACH Registration:Completed toxicological dossiers for citrate esters above one tonne annually create competitive moats for compliant suppliers. Non-European producers face elevated barrier costs to serve German and French personal care clusters.
Market Restraints
- Citric Acid Feedstock Volatility:Brazilian sugarcane harvest fluctuations and Chinese citric acid export quotas generate raw material price instability. Producers without backward integration into fermentation capacity absorb margin compression.
- Supplier Concentration Risk:Large-scale citrate ester synthesis capacity clusters in Ludwigshafen and Shanghai. Disruptions at either node propagate through multinational cosmetic house supply chains within weeks.
- Silicone-Organic Hybrid Substitution:Siltech and Dow silicone esters compete for premium skin-feel modification slots. These alternatives offer superior spreadability in high-pigment color cosmetic applications.
Strategic Opportunities
- Indian Personal Care Manufacturing:BIS standards alignment and CDSCO cosmetic ingredient pathways are opening formal market access. Domestic formulators seek compliant emollients for export-oriented production.
- Biodegradable Packaging Films:Convergence of citrate plasticizers with polylactic acid and polyhydroxyalkanoate substrates enables compostable flexible packaging. Food-contact approval expansion unlocks adjacent revenue pools.
- EU Green Deal Chemicals Strategy:Hazard classification simplification and essential use designations may accelerate citrate ester substitution for substances of very high concern. Early dossier preparation captures regulatory tailwind.
Industry Challenges
- Esterification Process Expertise Gap:Skilled technicians capable of optimizing 2-octyldodecanol-citric acid reaction kinetics are scarce. Training pipelines have not kept pace with capacity expansion plans.
- Multi-Jurisdiction Certification Timelines:Parallel FDA facility registration, REACH dossier maintenance, and NMPA safety assessment protocols strain regulatory affairs bandwidth. Synchronization failures delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trioctyldodecyl Citrate Market |
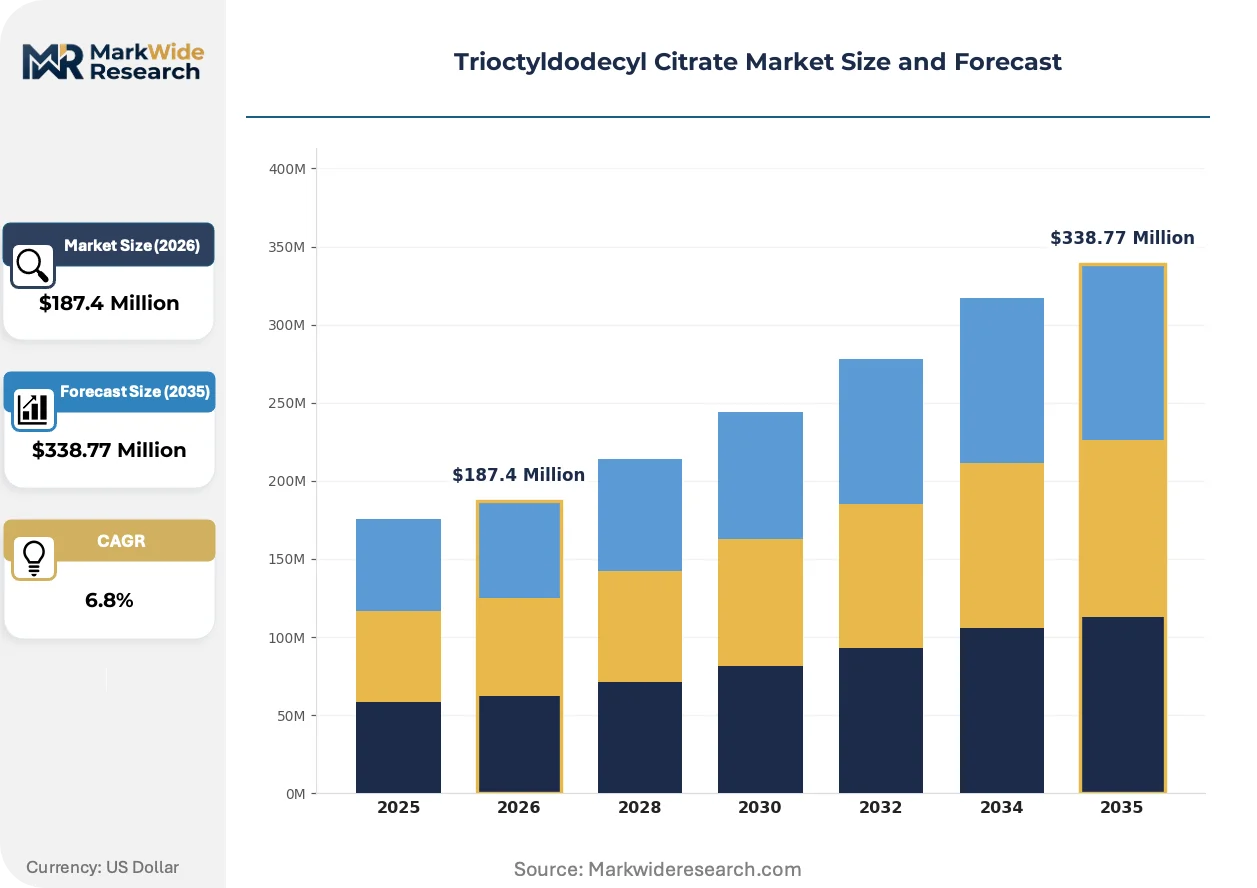
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emollients, Solvents, Plasticizers, Stabilizers Application: Cosmetics, Personal Care, Food Additives, Industrial Applications End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Siltech, Alzo International, Phoenix Chemical, Lubrizol, DPx Fine Chemicals, SRL Pharma GmbH, The Good Scents Company, Kobo Products, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trioctyldodecyl Citrate Market Evolving Landscape
Hybrid emollient architectures and reactive regulatory environments are compressing product development cycles. Suppliers must now embed compliance documentation into technical service offerings rather than treating it as post-sale support.
Bio-based process analytical technology is unifying real-time esterification monitoring with automated quality certification. German specialty chemical producers deploy in-line NIR spectroscopy to verify molecular weight distribution and pour point specifications during continuous production. This convergence compresses batch release timelines from days to hours while generating audit-ready data packages for ECHA inspections.
REACH authorization requirements for substances of very high concern are accelerating citrate ester substitution in nail care and flexible packaging segments. ECHA's 2024-2025 sunset date calendar pressures formulators to validate non-phthalate plasticizer performance in existing equipment. Personal care multinationals are front-loading reformulation projects to avoid supply discontinuity.
Technical service monetization is displacing commodity product sales as the primary revenue anchor. Cosmetic houses now contract for custom emollient blends with documented sensorial profiles rather than purchasing base esters for in-house modification. South Korean K-beauty manufacturers lead this shift, bundling formulation support into multi-year supply agreements with penalty clauses for performance shortfalls.
Trioctyldodecyl Citrate Market Segmentation
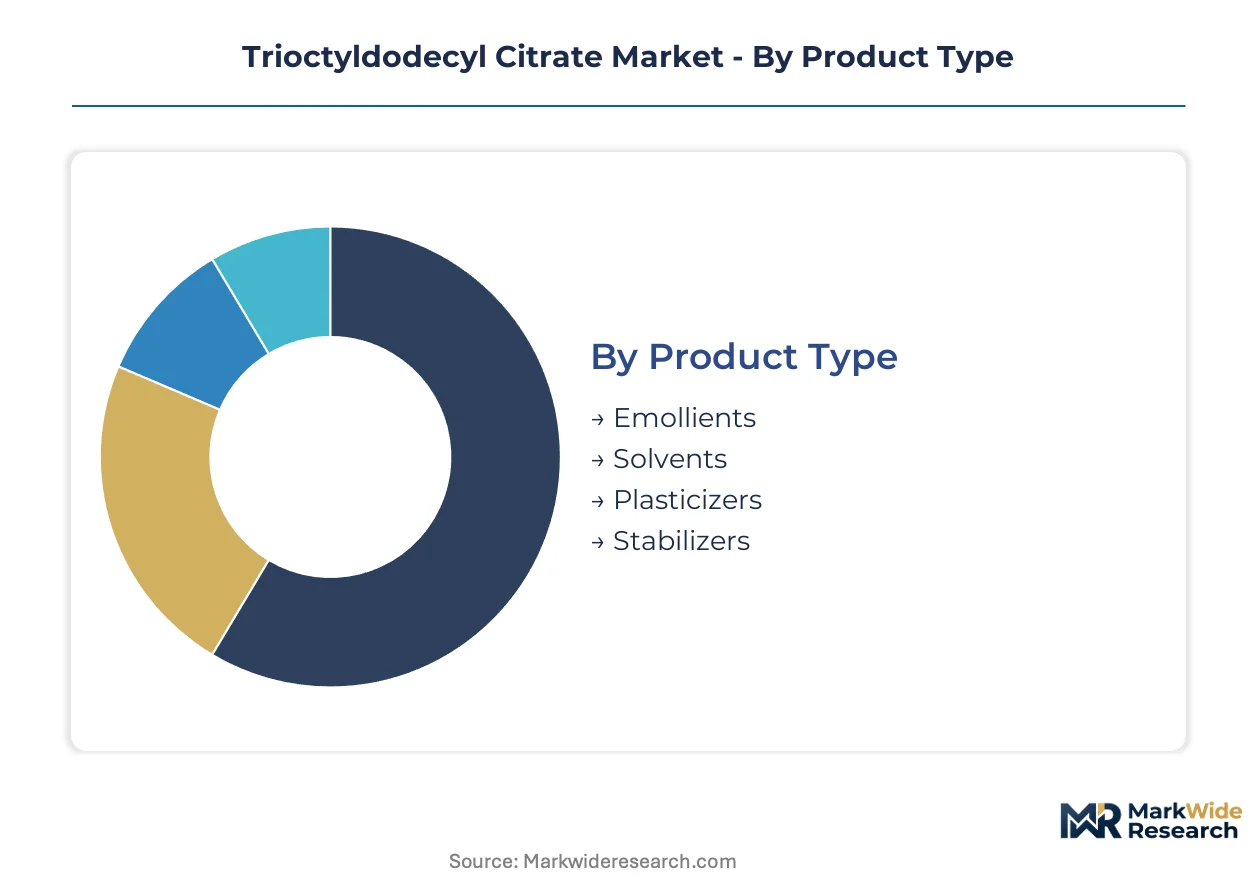
Segmentation in the trioctyldodecyl citrate market reveals distinct margin pools and technical service requirements across functional categories. Each segment demands different regulatory documentation depth and supply chain configurations.
Product Type:
Standalone emollient applications dominate premium formulations, while plasticizer and stabilizer functions embed deeper into compound systems with tighter performance specifications.
- Emollients:Branched-chain citric acid esters deliver exceptional spreadability and oxidative stability in premium skincare bases. South Korean K-beauty manufacturers concentrate procurement for long-wear color cosmetics where sensorial performance commands price premiums. Clean beauty certification schemes favor these bio-based alternatives over petroleum-derived competitors.
- Plasticizers:Non-phthalate film-forming performance drives substitution in waterborne nail care and flexible packaging. REACH sunset dates for substances of very high concern accelerate validation timelines for existing equipment compatibility. German personal care ingredient hubs source heavily for compliant reformulation projects.
- Solvents:Industrial cleaning applications occupy mature positioning with compressed margin structures relative to personal care grades.
- Stabilizers:Oxidative protection functions integrate into compound additive packages for extended shelf-life formulations.
Emollients lead volumes today; plasticizers are gaining share fastest.
Application:
Cosmetic formulators embed citrate esters at higher integration depths than food or industrial users, requiring documented biodegradability profiles and supply chain transparency.
- Cosmetics:Premium color cosmetic bases leverage trioctyldodecyl citrate for skin-feel modification and pigment wetting. Sephora Clean and Ulta Conscious Beauty specifications mandate ingredient disclosure that favors citrate esters. Technical service agreements now bundle custom emollient blends with sensorial profiling.
- Personal Care:Skincare and haircare formulations absorb volume through multinational cosmetic house supply chains. ECHA REACH registration creates competitive moats for compliant suppliers serving German and French manufacturing clusters.
- Food Additives:Food-contact approval expansion unlocks adjacent revenue pools in biodegradable packaging films.
- Industrial Applications:Cleaning solvents and process chemicals operate on thinner margin pools with standardized procurement criteria.
Cosmetics commands the largest value share; food additives present the steepest expansion trajectory.
End User:
Manufacturer procurement patterns concentrate technical service demands, while retailer and distributor channels fragment volume across smaller formulation houses.
- Manufacturers:Cosmetic compounders and packaging film producers contract for multi-year supply agreements with performance penalty clauses. Backward integration into citric acid feedstocks differentiates large-scale suppliers.
- Retailers:Clean beauty retailers enforce ingredient disclosure standards that reshape upstream procurement criteria.
- Distributors:Specialty chemical distributors aggregate demand from mid-tier formulators lacking direct supplier relationships.
- Consumers:Direct purchase remains negligible given industrial-intermediate positioning of citrate esters.
Manufacturers absorb the dominant volume share; retailers are tightening specification power fastest.
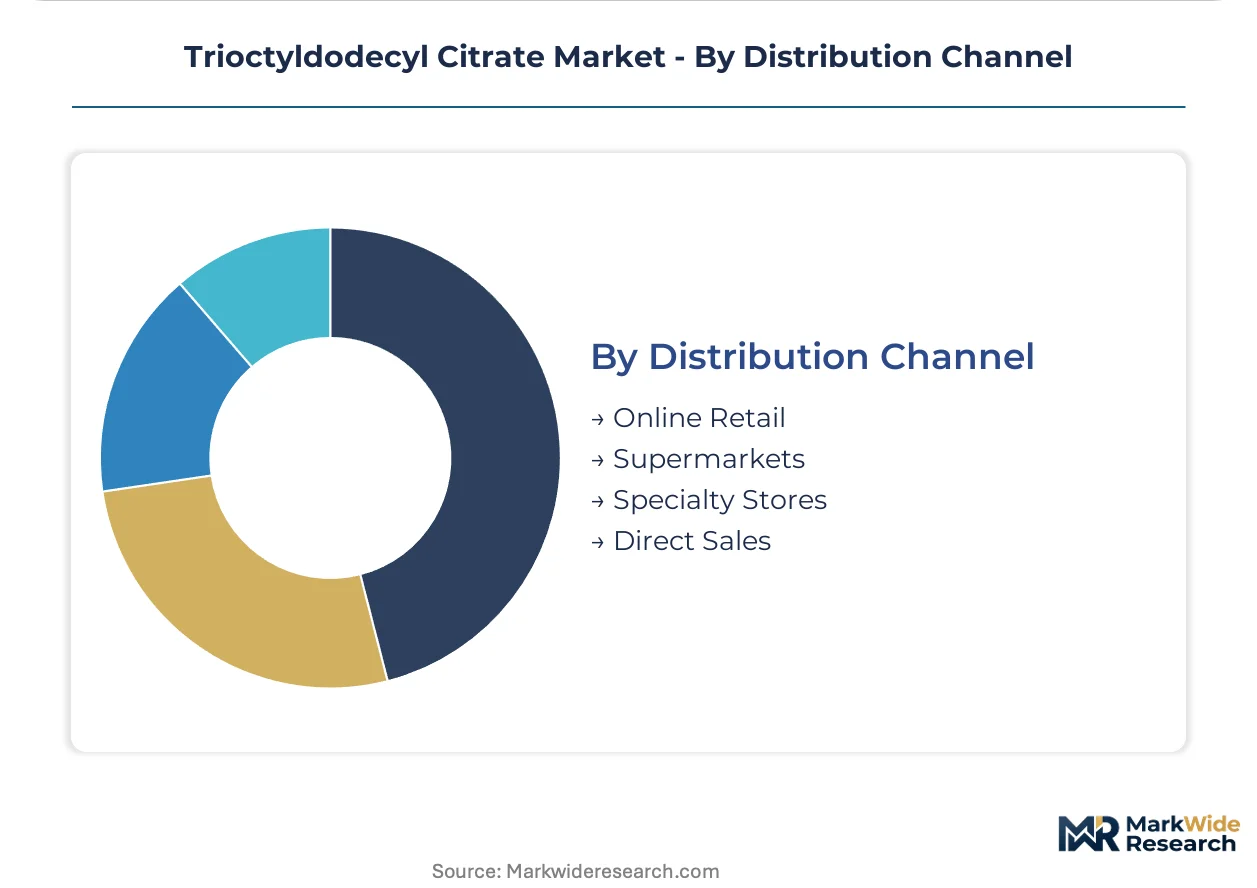
Distribution Channel:
Channel selection correlates with order scale and technical service intensity, with direct relationships commanding premium positioning.
- Direct Sales:Technical service agreements anchor relationships with multinational cosmetic houses and South Korean K-beauty manufacturers. Custom emollient blends with documented sensorial profiles displace commodity base ester transactions.
- Specialty Stores:Regional formulators access compliant emollients through distributors with REACH dossier maintenance capabilities.
- Online Retail:Smaller formulation houses procure standardized grades with limited technical support.
- Supermarkets:Minimal penetration given industrial-intermediate product positioning.
Direct sales dominates value capture; specialty stores are expanding coverage most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea and Germany command disproportionate influence in citrate ester procurement, though their demand drivers diverge sharply between K-beauty manufacturing clusters and REACH-compliant ingredient hubs.
South Korea
K-beauty manufacturers in the Seoul Capital Area drive emollient demand for long-wear color cosmetics requiring documented sensorial profiles. MFDS cosmetic ingredient regulations mandate safety assessments that favor established citrate ester suppliers with complete toxicological dossiers. Incheon's chemical processing zone concentrates formulation houses contracting for multi-year technical service agreements.
Germany
ECHA REACH registration requirements create competitive moats for compliant suppliers serving personal care multinationals. The EU Green Deal Chemicals Strategy accelerates substitution timelines for substances of very high concern in nail care applications. Ludwigshafen's integrated chemical complex anchors large-scale citrate ester synthesis with captive citric acid feedstock supply.
United States
FDA Modernization of Cosmetics Regulation Act mandates adverse event reporting and facility registration that reshape foreign manufacturer access. Sephora Clean and Ulta Conscious Beauty specifications enforce ingredient disclosure standards favoring bio-based emollients. New Jersey's specialty chemical corridor houses distributors aggregating demand from mid-tier formulators.
China
NMPA and GB standards impose separate safety assessment protocols that fragment market access requirements for citrate ester imports. Domestic citric acid production capacity in Shandong province generates feedstock cost advantages for local esterification operations. Shanghai's personal care ingredient trading hub concentrates procurement for multinational cosmetic houses with China-based manufacturing.
India
BIS standards alignment and CDSCO cosmetic ingredient pathways are opening formal market access for compliant emollient suppliers. Domestic formulators in Maharashtra and Gujarat seek certified raw materials for export-oriented production to Middle Eastern and African markets. Mumbai's specialty chemical distribution network aggregates demand from regional personal care manufacturers lacking direct supplier relationships.
Trioctyldodecyl Citrate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technical service intensity determining margin capture. Large-scale fermentation-based producers with backward integration into citric acid feedstocks occupy structurally defensible positions against specialty blenders. Three archetypes dominate: integrated chemical majors with captive raw material supply, silicone-organic hybrid specialists leveraging skin-feel expertise, and regional esterification houses serving formulation-specific procurement. Capacity expansion in Ludwigshafen and Shanghai clusters proceeds alongside technical service bundling into multi-year supply agreements.
Among integrated chemical majors, BASF SE exemplifies scale-driven positioning through its Rhineland-Palatinate production complex. Siltech and Lubrizol represent alternative archetypes—Siltech anchors premium skin-feel modification through silicone-organic hybrid expertise, while Lubrizol sustains broad formulation support capabilities across multinational cosmetic house portfolios. These three companies collectively illustrate how technical service monetization displaces commodity product transactions in mature emollient markets.
| Leading Market Players |
|---|
| Siltech |
| Alzo International |
| Phoenix Chemical |
| Lubrizol |
| DPx Fine Chemicals |
| SRL Pharma GmbH |
| The Good Scents Company |
| Kobo Products |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Continuous esterification process technology adoption in German and Chinese production clusters compresses unit economics while concentrating synthesis capacity around integrated chemical complexes with captive citric acid supply. This dual shift simultaneously lowers marginal production costs and elevates barriers for non-integrated competitors seeking REACH-compliant market access.
Pricing Analysis
Capacity additions in Ludwigshafen and Shanghai are reshaping price floors for standard-grade trioctyldodecyl citrate. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by REACH dossier completeness and technical service bundling. Pricing pressure stems from Brazilian sugarcane harvest volatility transmitting into citric acid feedstock costs. Small-scale regional formulators exhibit highest price sensitivity; multinational cosmetic houses prioritize sensorial documentation over unit cost.
Supply Chain Analysis
Citric acid feedstock supply rests on Brazilian fermentation operations and Shandong province synthetic capacity. Trioctyldodecyl citrate synthesis draws from 2-octyldodecanol specialty alcohol streams and catalytic esterification expertise concentrated in Germany, China, and South Korea. Single-source vulnerability propagates from Ludwigshafen complex disruptions through multinational cosmetic house supply chains. Distribution runs through direct technical service agreements for large accounts and specialty chemical distributors for mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trioctyldodecyl citrate functions as a regulatory compounder where ECHA REACH sunset dates for phthalate plasticizers are accelerating substitution demand across nail care and flexible packaging segments.
For Market Incumbents: Anticipate silicone-organic hybrid competition from Siltech and Dow by deepening technical service monetization through custom emollient blend contracts with sensorial performance guarantees. Secure backward integration into citric acid fermentation capacity or long-term offtake agreements with Brazilian and Chinese suppliers to defend margin position against feedstock volatility. Prioritize multi-jurisdiction dossier maintenance capabilities to capture reformulation timelines compressed by regulatory divergence. For New Entrants and Emerging Players: EU Green Deal Chemicals Strategy hazard classification simplification opens a window for compliant citrate ester suppliers to penetrate German and French personal care manufacturing clusters previously defended by registration moats. Target Indian domestic formulators in Maharashtra and Gujarat seeking export-certified emollients for Middle Eastern and African markets. Lead with biodegradable packaging film applications where food-contact approval expansion creates uncrowded white space. For Investors and Strategic Acquirers: Valuations sit cheapest among regional esterification houses lacking REACH dossier completeness but possessing 2-octyldodecanol-citric acid reaction optimization expertise. Long-term viability hinges on technical service bundling displacement of commodity transactions and regulatory tailwind capture from SVHC substitution mandates. Watch ECHA authorization timeline announcements as inflection indicators for reformulation project acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citric Acid Feedstock | Captive fermentation capacity insulates BASF and integrated majors from Brazilian harvest volatility and Chinese export quota disruptions. |
| REACH Dossier Maintenance Investment | Complete toxicological documentation creates competitive moats for ECHA-compliant suppliers serving German personal care clusters. |
| Technical Service Agreement Expansion | Custom emollient blend contracts with South Korean K-beauty manufacturers displace commodity base ester transactions. |
| Biodegradable Packaging Film Partnership | Convergence with polylactic acid substrates unlocks food-contact approval revenue pools in compostable flexible packaging. |
| Multi-Jurisdiction Certification Synchronization | Parallel FDA facility registration and NMPA safety assessment capabilities accelerate product launch timelines for multinational cosmetic houses. |
Research Methodology
Coverage spans South Korea, Germany, the United States, China, and India, with primary inputs from each market cluster. Primary interviews engaged cosmetic formulators, regulatory affairs specialists at citrate ester suppliers, procurement leads at multinational personal care houses, and technical R&D directors at specialty chemical producers. Secondary validation drew from ECHA registration databases, FDA facility registration records, NMPA cosmetic ingredient filings, and trade flow data from customs authorities. Bottom-up volume modeling triangulated against top-down market sizing from producer capacity assessments.
Segmentation granularity applied product type, application, and end-user dimensions at the country level, with regulatory cluster overlays for REACH, FDA, and NMPA compliance pathways. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated citric acid feedstock cost curves, clean beauty certification penetration rates, and waterborne nail care formulation adoption patterns.
Revisions become necessary when ECHA authorization timelines accelerate, Brazilian sugarcane harvests deviate from trend, or silicone-organic hybrid technologies achieve cost parity in skin-feel modification. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Phthalate Plasticizer Market
Additives
Plasticizers Market
Additives
Polysorbate-80 Market
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Ammonium Acetate Market
Additives
Dispersing Agents Market
Additives
Global Flame Retardant Masterbatches Market
Additives
Crystal Growth Modifier Market
Additives
Global Feed Acidulants Market
Additives
Anti-Slip Additives Market
Additives
Emulsifiers In Personal Care Market
Additives
Disodium Guanylate Market
Additives
Tricalcium Citrate Market
Additives
Inhibited Propylene Glycol Market
Additives
Anti-Wear Additives Market
Additives
Encapsulated Citric Acid Market