
 Low VOC Paints and Coatings Market | 2026-2036
Low VOC Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Low VOC Paints and Coatings Market Analysis
EPA VOC emission standards for architectural coatings is hardening compliance timelines across North American manufacturers. PPG Industries leverages its integrated resin production to sustain cost advantages in water-based acrylic systems. AkzoNobel anchors European demand through specialized marine and protective coatings with certified low-solvent content. BASF SE competes on advanced polymer dispersion technology that reduces co-solvent dependence without sacrificing film performance.
Low VOC paints and coatings are formulated with volatile organic compound content below regulatory thresholds, typically achieved through water-borne resin systems, high-solids thermoset polymers, or UV-curable chemistries that minimize atmospheric solvent release during application and cure. These products serve primarily to reduce ground-level ozone formation, indoor air pollution, and worker exposure hazards while maintaining substrate protection and aesthetic finish quality. Water-based coatings now lead volume globally due to decades of polymer science investment that closed the durability gap with solvent-borne predecessors. Acrylic Paints command the largest share among product types, benefiting from versatility across interior and exterior substrates. Automotive end users represent the fastest-growing demand pool as OEMs adopt stricter interior air quality protocols for cabin environments.
EPA regulates architectural coating VOC limits under 40 CFR Part 59, while ECHA administers REACH restrictions on hazardous substance content across European formulations. China's MEE enforces GB standards for building material pollutant control that directly affect coating certification requirements. Manufacturers must monitor evolving substance restriction lists, as regulatory expansion into semi-volatile and very volatile compound categories will force additional reformulation cycles within the decade.
Market Dynamics
Reformulation pressure from EPA 40 CFR Part 59 and ECHA REACH substance restrictions is forcing coating manufacturers to abandon solvent-borne alkyd systems faster than polymer science can close performance gaps in water-borne alternatives.
Growth Catalysts
- EPA architectural coating limits:Federal VOC ceilings under 40 CFR Part 59 compel residential and industrial applicators to specify certified low-solvent formulations for compliance.
- Automotive interior air protocols:OEM cabin environment standards now mandate sub-50 g/L VOC content in dashboard, seat, and trim coatings, creating specification pull through tier-one suppliers.
- Green building certification density:LEED and BREEAM point systems for indoor air quality reward projects specifying zero-VOC or low-emitting coating systems, channeling specification authority toward certified products.
Market Restraints
- Acrylic monomer cost volatility:Water-borne system dependence on petrochemical-derived acrylate monomers exposes margin compression when ethylene-propylene feedstock prices spike.
- Titanium dioxide supply concentration:Pigment production clusters in China create geographic chokepoints that disrupt opacity performance in reformulated low-VOC whites and pastels.
- Cure-rate limitations:Ambient-cure water-borne alkyds and urethanes remain slower than solvent-borne equivalents, restricting adoption in high-throughput industrial finishing lines.
Strategic Opportunities
- India building material certification:BIS adoption of GB-standard-aligned VOC limits for decorative coatings creates first-mover positioning for certified suppliers in underpenetrated tier-two construction markets.
- UV-curable wood furniture:Radiation-cure oligomer systems eliminate solvent entirely while enabling 30-second cure cycles, opening high-margin replacement of conventional nitrocellulose lacquers.
- EU Green Deal renovation wave:Building efficiency retrofit mandates will drive recoating volume across existing European housing stock, favoring low-odor, same-day reoccupancy formulations.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in colloidal stability and coalescent-free film formation sits concentrated among retiring technical specialists, constraining R&D throughput.
- Multi-certification timeline compression:Simultaneous pursuit of LEED v4.1, CDPH Section 01350, and French A+ labeling extends product validation cycles by 8-14 months.
- Legacy equipment incompatibility:Existing spray booths and drying ovens designed for high-solvent flash-off require capital retrofit to handle slower-evaporating water-borne films without defect.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low VOC Paints and Coatings Market |
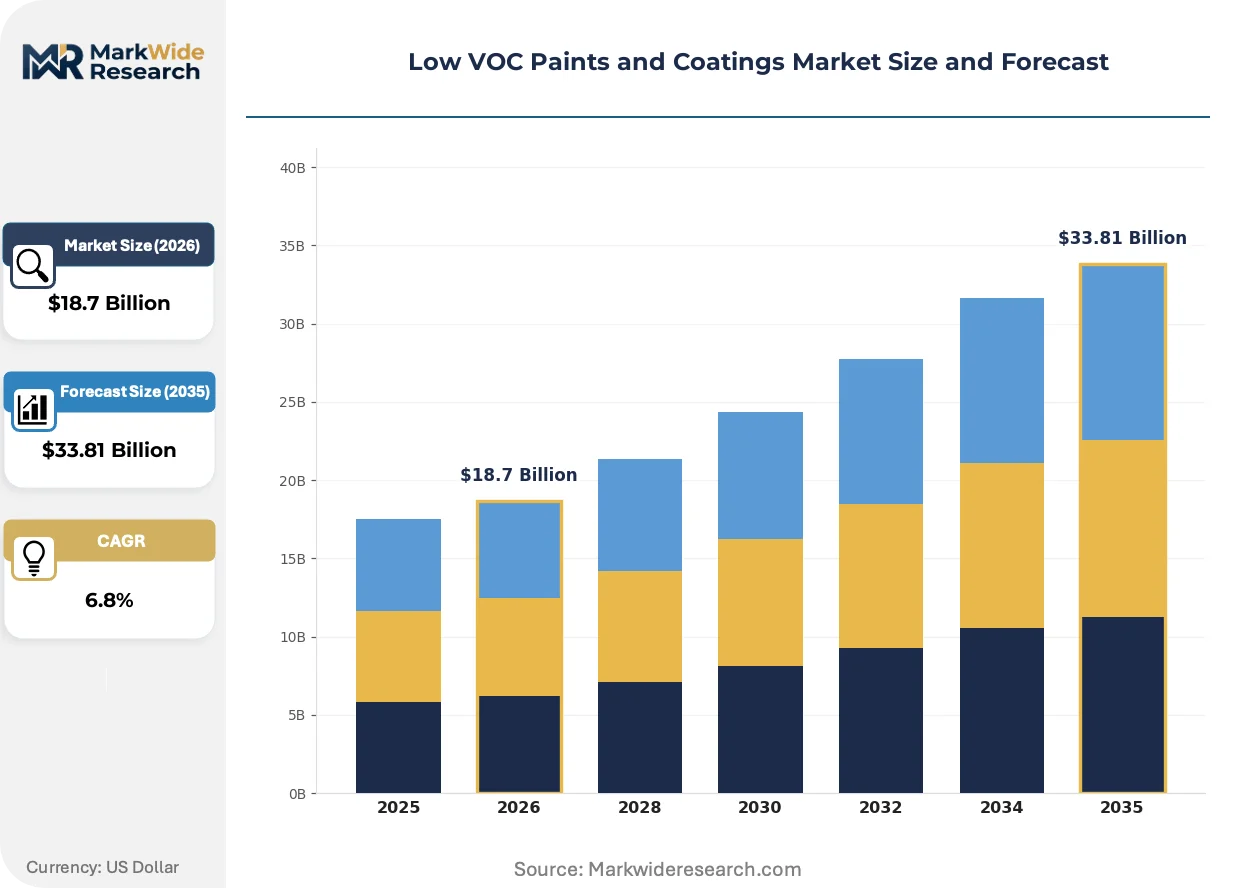
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Paints, Alkyd Paints, Water-Based Coatings, Oil-Based Coatings End User: Residential, Commercial, Industrial, Automotive Application: Interior, Exterior, Furniture, Flooring Packaging Type: Cans, Drums, Pails, Containers |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, AkzoNobel, BASF SE, Asian Paints, Nippon Paint Holdings Co., Ltd., Axalta Coating Systems, RPM International, Jotun A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low VOC Paints and Coatings Market Emerging Trajectories
Polymer architecture advances are collapsing the durability gap between water-borne and solvent-borne coatings while regulatory substance restrictions accelerate the obsolescence of legacy resin systems.
Bio-based polyurethane dispersions synthesized from castor oil-derived polyols are converging with conventional petroleum-based acrylics in performance attributes while offering renewable content claims. Flooring and cabinetry manufacturers in Germany and the Netherlands now specify these systems for commercial interior applications. The technology is converging with carbon accounting requirements in corporate sustainability reporting, compressing the premium price gap against conventional water-borne urethanes.
ECHA expansion of SVHC candidate list to include additional isocyanate precursors is forcing protective coating formulators to accelerate blocked isocyanate and polyaziridine crosslinker substitution programs. Marine and industrial maintenance sectors face reformulation timelines compressed by authorization sunset dates. North Sea offshore platform operators now demand pre-certified alternatives to conventional two-pack epoxy-amine systems to avoid maintenance scheduling disruption.
Specification authority is migrating from general contractors to certified industrial hygienists and building envelope consultants who control submittal approval for VOC emission testing data. Large commercial construction projects in California and New York now require third-party CDPH Section 01350 or ISO 16000-6 chamber test reports prior to coating approval. This behavioral shift concentrates purchasing influence among specification writers rather than traditional distributor relationships, compressing brand loyalty and rewarding testing documentation capabilities.
Low VOC Paints and Coatings Market Segmentation
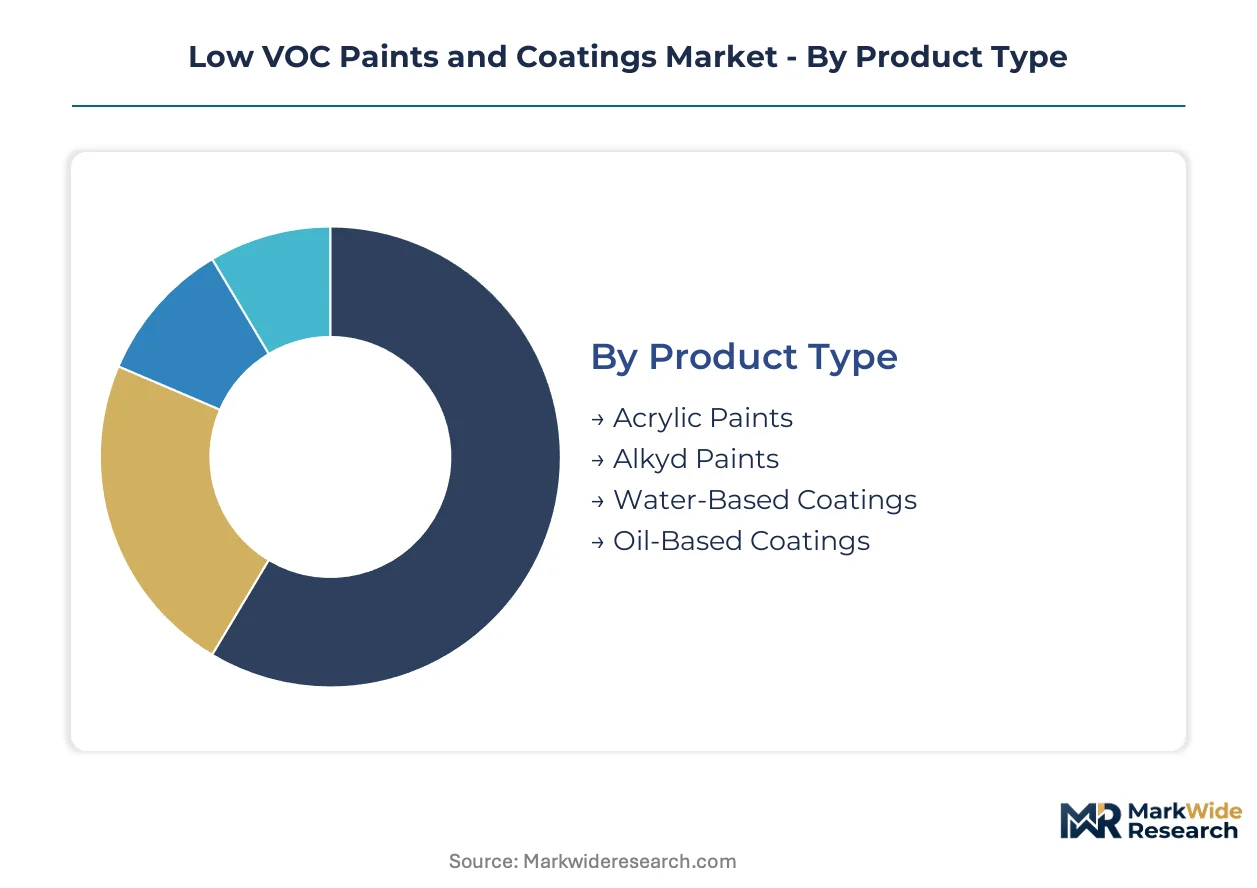
Low VOC paint and coating segments diverge sharply by reformulation maturity and regulatory exposure. Replacement cycles accelerate fastest where water-borne alternatives have closed durability gaps with legacy solvent systems.
Product Type:
Upgrade cycles vary by resin chemistry maturity, with some technologies already completing their transition while others face compressed compliance timelines.
- Acrylic Paints:Water-borne acrylic emulsions now achieve exterior durability parity with solvent-borne alkyds through core-shell polymer architecture. Residential interior demand concentrates in United States, Germany, and China as builders pursue LEED and BREEAM certification. EPA 40 CFR Part 59 compliance has become table stakes for specification.
- Water-Based Coatings:These systems rely on polymer dispersion technology that eliminates co-solvent dependence while maintaining film formation at ambient temperatures. Industrial maintenance applications in California and New York now mandate sub-50 g/L VOC content, forcing specification migration from conventional alkyds.
- Alkyd Paints:Solvent-borne alkyd systems face accelerated obsolescence under tightening ECHA REACH substance restrictions.
- Oil-Based Coatings:Niche applications in furniture and specialty wood finishing retain demand where water-borne alternatives struggle with grain raising.
Volume placements concentrate in Acrylic Paints; the faster expansion belongs to Water-Based Coatings.
End User:
Cost tier differentiation separates specification-driven premium segments from price-sensitive volume applications.
- Automotive:OEM cabin air quality protocols now mandate sub-50 g/L VOC content in dashboard, seat, and trim coatings, creating tier-one supplier specification pull. European and North American assembly plants lead adoption.
- Residential:Green building certification density channels specification authority toward zero-VOC and low-emitting systems. LEED point systems for indoor air quality reward compliant product selection.
- Commercial:Large construction projects require third-party CDPH Section 01350 or ISO 16000-6 chamber test reports prior to coating approval.
- Industrial:High-throughput finishing lines face cure-rate limitations with ambient-cure water-borne alternatives.
Automotive commands the steepest expansion trajectory as OEM protocols tighten; Residential retains the largest volume placement.
Application:
Surface exposure conditions dictate reformulation complexity and certification requirements across architectural and specialty segments.
- Interior:Same-day reoccupancy formulations gain specification share in healthcare and educational construction. CDPH Section 01350 emission testing has become mandatory for large commercial projects in California and New York.
- Flooring:Bio-based polyurethane dispersions from castor oil-derived polyols converge with petroleum-based acrylics in performance. German and Dutch cabinetry manufacturers now specify these systems for commercial interiors.
- Exterior:Durability requirements for UV resistance and hydrophobicity strain water-borne polymer design.
- Furniture:UV-curable oligomer systems enable 30-second cure cycles without solvent emission.
Interior applications dominate volume placements; Flooring gains share fastest on bio-based material claims.
Packaging Type:
Container specifications align with application scale and supply chain logistics rather than product chemistry differentiation.
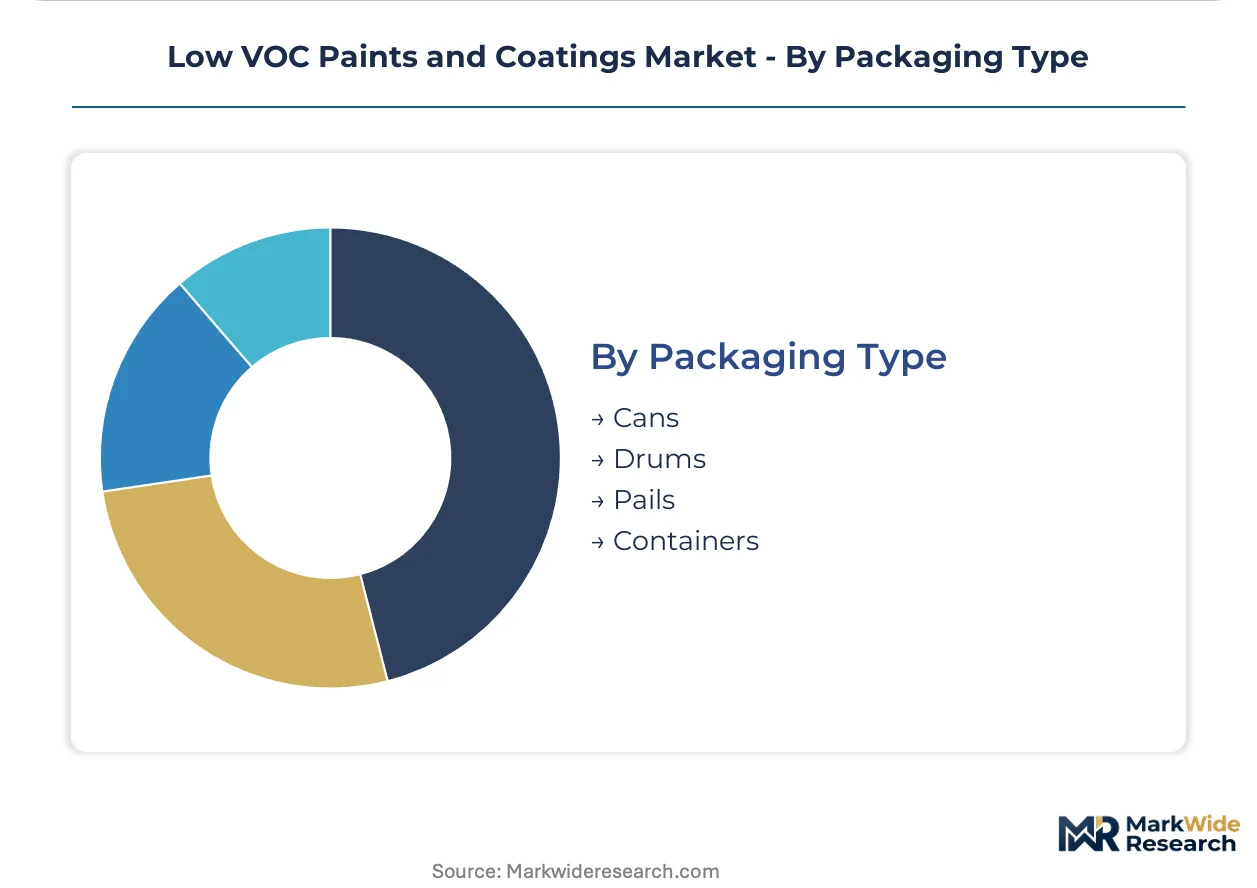
- Cans:Retail and residential trade channels favor 1-gallon and 5-gallon steel cans with integrated pour spouts and resealable closures.
- Pails:Commercial contractors specify stackable plastic pails for mid-volume interior and exterior projects.
- Drums:Industrial-scale consumers procure 55-gallon steel drums for high-throughput finishing lines.
- Containers:Aerosol and specialty packaging serves touch-up and repair applications with precise application requirements.
Cans and pails split volume leadership by channel; drum specifications expand most quickly in industrial consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pittsburgh anchors North American coatings R&D concentration through integrated resin production corridors. German chemical clusters along the Rhine drive European water-borne polymer innovation. Chinese manufacturing zones in Guangdong and Jiangsu scale capacity for Asia-Pacific demand.
United States
Residential construction in Texas and Florida drives interior coating volume as builders pursue LEED certification density. EPA 40 CFR Part 59 enforces federal VOC ceilings that compel specification migration from solvent-borne alkyds. California's South Coast Air Quality Management District maintains sub-100 g/L limits that exceed national baselines, forcing reformulation cycles ahead of federal timelines.
Germany
Commercial renovation across Bavaria and North Rhine-Westphalia channels demand toward same-day reoccupancy formulations. ECHA REACH substance restrictions accelerate blocked isocyanate substitution in protective coatings. The Cologne-Düsseldorf chemical corridor concentrates bio-based polyurethane dispersion development for flooring and cabinetry applications.
China
Urban residential towers in Shanghai and Shenzhen specify low-emitting interior systems as green building certification expands. MEE enforces GB standards for building material pollutant control that directly affect coating certification requirements. The Yangtze River Delta manufacturing belt scales water-based acrylic production for both domestic consumption and export markets.
India
Tier-two construction markets in Maharashtra and Gujarat create specification opportunities as BIS adopts GB-standard-aligned VOC limits. The country's national environmental regulator tightens decorative coating emission thresholds through state-level implementation. Mumbai-Pune industrial corridor attracts first-mover suppliers establishing certified distribution networks.
Netherlands
Rotterdam port logistics and Amsterdam commercial construction drive specification pull for marine and interior coating systems. EU Green Deal renovation wave mandates accelerate building efficiency retrofit volume across existing housing stock. Eindhoven-Brabant chemical cluster specializes in radiation-cure oligomer systems for furniture finishing applications.
Low VOC Paints and Coatings Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification complexity and technical service depth. The vendor base organizes into three tiers: integrated resin-coating conglomerates with captive raw material supply; mid-scale formulators competing on regional certification speed; and specialty niche operators serving single-application segments. Strategic moves concentrate on backward integration into polymer dispersion production and accelerated multi-certification testing throughput.
Within the integrated conglomerate tier, PPG Industries and BASF SE exemplify archetypes combining resin manufacturing with formulated coating distribution. AkzoNobel occupies a position bridging European protective coating specialization with global marine certification authority. Asian Paints represents the emerging-market archetype, scaling water-based capacity to serve underpenetrated construction corridors. These anchors demonstrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic actions.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries |
| AkzoNobel |
| BASF SE |
| Asian Paints |
| Nippon Paint Holdings Co., Ltd. |
| Axalta Coating Systems |
| RPM International |
| Jotun A/S |
| Others |
Supply Flow & Price Mechanics
Water-borne polymer dispersion technology simultaneously collapses production cost curves for compliant coatings while concentrating formulation expertise among integrated resin manufacturers in Germany, the United States, and China. This production-method transition rewards backward integration into acrylic emulsion production and penalizes standalone formulators exposed to petrochemical feedstock volatility.
Pricing Analysis
Certification-grade performance anchors value-based pricing across low-VOC coating tiers. Three-tier pricing structure across premium, standard, and economy levels separates LEED v4.1-certified systems from basic EPA 40 CFR Part 59 compliance and uncertified commodity alternatives. Cost compression in economy tiers intensifies because titanium dioxide supply concentration in China exposes margin pressure during pigment price spikes. Residential contractors exhibit highest price sensitivity, while automotive OEMs accept premium positioning for cabin air quality protocols.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive buyer demand, while distributor networks serve fragmented residential and commercial contractors. Raw material sourcing concentrates in China for titanium dioxide pigments, Germany for specialty isocyanate precursors, and the United States for acrylic monomer production. Formulation depends on petrochemical-derived acrylate feedstocks that create single-source vulnerability during ethylene-propylene price cycles. Distribution runs through regional coating specialists who control specification authority via certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-borne alkyd replacement cycles define this market's technology-transition phase, as ambient-cure polymer systems displace solvent-borne legacy formulations across architectural and industrial segments.
For Market Incumbents: Acquire captive resin production assets to secure margin control against acrylic monomer cost volatility. Defensive positioning requires accelerated multi-certification throughput for CDPH Section 01350, French A+, and BREEAM compliance to maintain specification authority. Threat from bio-based polyurethane dispatches demands R&D investment in castor oil-derived polyol integration.
For New Entrants and Emerging Players: UV-curable oligomer systems for wood furniture finishing offer technology-first wedge into high-margin specialty segments with sub-50 g/L VOC mandates. White-space concentration sits in India's tier-two construction markets as BIS adopts GB-standard-aligned limits. Go-to-market execution should target certified industrial hygienist specification networks rather than traditional distributor relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated resin-coating conglomerates with captive polymer dispersion technology and multi-regional certification infrastructure. Long-term viability favors targets with demonstrated ECHA REACH compliance acceleration and blocked isocyanate substitution capabilities. Signal to monitor: automotive OEM interior air protocol expansion beyond dashboard and trim into structural adhesives and sealants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Emulsion Production | Captive resin supply insulates margin compression from ethylene-propylene feedstock volatility. |
| Multi-Certification Testing Throughput Expansion | Parallel CDPH, BREEAM, and French A+ validation compresses product launch timelines by 8-14 months. |
| Bio-Based Polyurethane Dispersion Development | Castor oil-derived polyol systems satisfy corporate carbon accounting requirements in German and Dutch commercial interiors. |
| UV-Curable Oligomer Capacity Addition | Radiation-cure systems enable 30-second cure cycles without solvent emission for furniture finishing. |
| Industrial Hygienist Specification Network Partnership | Third-party chamber test documentation controls submittal approval in California and New York commercial construction. |
Methodological Framework
Document review covered EPA 40 CFR Part 59 regulatory filings, ECHA REACH substance restriction updates, and GB standard certification databases, complemented by interviews with formulation chemists, procurement leads at tier-one automotive suppliers, distribution channel partners, and technical R&D directors at integrated resin manufacturers. Secondary validation drew from customs trade data, SEC 10-K segment disclosures, and national building material certification registries. Bottom-up volume modeling triangulated against top-down regulatory compliance timelines.
Historical adoption curves for water-borne alkyd substitution cross-referenced against expert panel inputs on cure-rate performance gaps. Segmentation modeling spanned resin chemistry tier, end-use industry vertical, certification grade, and regional regulatory cluster across the analysis window. CAGR derivation incorporated polymer science advancement rates, reformulation cost trajectories, and green building certification penetration forecasts. Industry-specific inputs included automotive OEM interior air protocol expansion schedules and ECHA SVHC candidate list sunset timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA substance restriction expansion or sustained titanium dioxide supply disruption. Projections reflect assumptions regarding water-borne durability gap closure, regulatory harmonization across EPA and MEE standards, and industrial equipment retrofit adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Italy Industrial Wood Coatings Market
Paints & Coatings
India Architectural Coatings Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Paint and Coating Stripper Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Paint Sprayer Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Global Antifouling Paints and Coatings Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Sri Lanka Paints and Coatings Market