
 Tragacanth Market | 2026-2036
Tragacanth Market Size, Share, and Industry Trends Forecast 2026-2036
Tragacanth Market Analytics
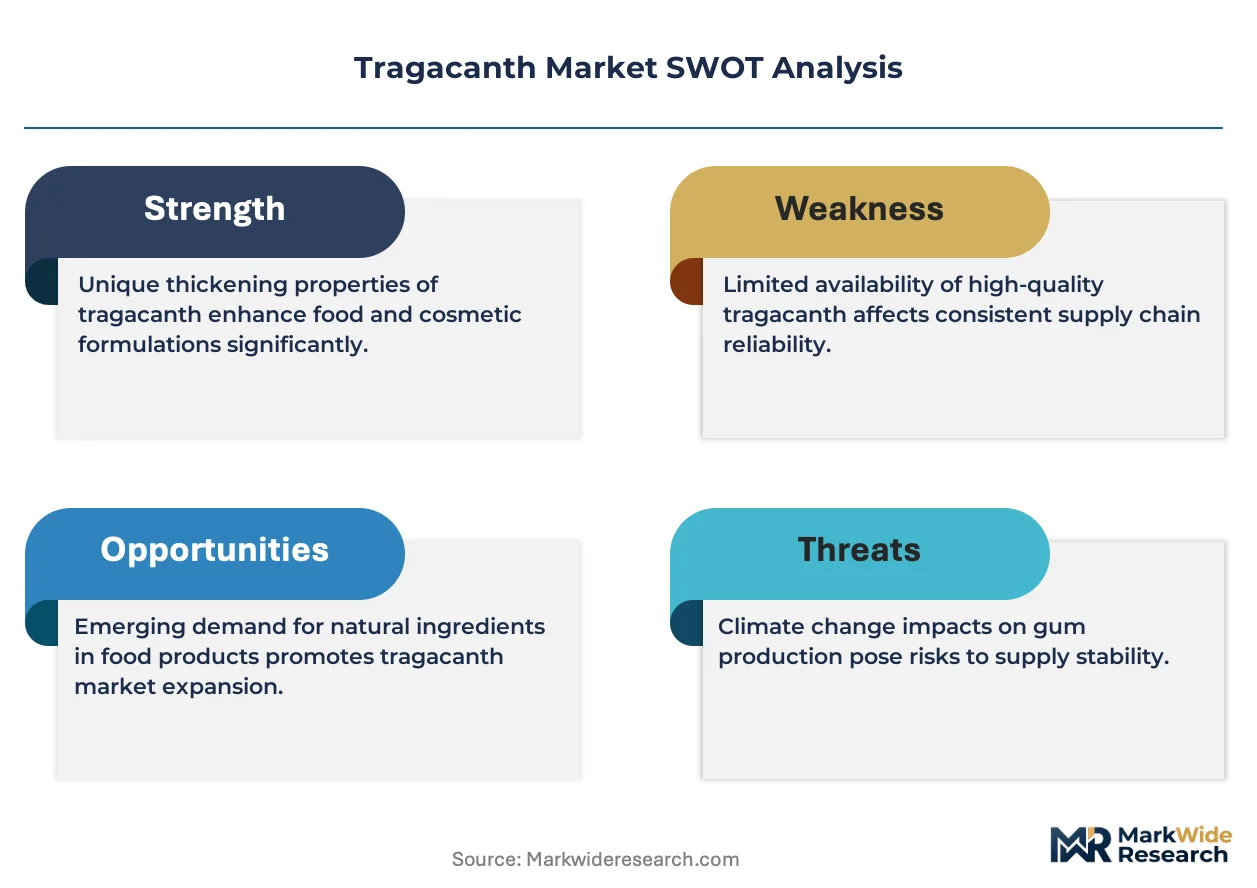
ISO 9001 quality management certification is bifurcating the supplier base into export-grade and commodity-grade tragacanth channels. Hawkins Watts Limited leverages its ANZ distribution network to sustain premium positioning in food-grade tragacanth. AEP Colloids specializes in pharmaceutical-grade purification, anchoring its reputation among European drug formulators.
Tragacanth is a dried exudate from Astragalus shrub species, composed primarily of bassorin and tragacanthin polysaccharides that yield high-viscosity aqueous solutions at low concentrations; it functions as a stabilizer, emulsifier, and thickener across food, pharmaceutical, and cosmetic systems. Natural Tragacanth retains dominance in artisanal food and traditional medicine applications where unmodified gum integrity commands price premiums. Modified Tragacanth and Blades are capturing share in industrial-scale food processing where consistent hydration kinetics and microbial stability override raw authenticity.
FDA food additive regulations under 21 CFR 184.1351 and EFSA purity standards for food hydrocolloids govern import eligibility and end-use labeling across North America and Europe. Iran's national standardization body enforces export grading protocols that directly determine which lots enter pharmaceutical versus food channels. Stakeholders must track dual-use regulatory divergence between food-grade permissiveness and pharmaceutical-grade pharmacopeial stringency as sourcing decisions carry compliance lock-in effects.
Market Dynamics
Clean-label formulation mandates from major food retailers are compressing synthetic hydrocolloid use, forcing manufacturers to validate tragacanth's functional parity with xanthan and guar alternatives through accelerated stability testing protocols.
Growth Catalysts
- EFSA purity benchmarks:Tightened food hydrocolloid standards under EU Regulation 1333/2008 are disqualifying ungraded gum imports, channeling volume toward certified Iranian exporters with ISO 17025 laboratory accreditation.
- Pharmaceutical excipient demand:Sustained-release tablet formulations require high-viscosity tragacanthin fractions that synthetic polymers cannot replicate at equivalent shear-thinning profiles.
- Astragalus cultivation clusters:Khorasan Razavi province in Iran maintains generational harvesting expertise that mechanized alternatives in Turkey cannot match for bassorin yield consistency.
Market Restraints
- Raw material concentration:Over 70% of export-grade tragacanth originates from Iran's Zagros mountain belt, exposing buyers to sanctions-related payment friction and currency volatility.
- Climate-dependent harvest cycles:Drought frequency in Fars province creates 18-24 month supply gaps that industrial formulators cannot absorb without secondary hydrocolloid qualification.
- Substitution elasticity:Modified cellulose gums from Dow and Ashland achieve 85% viscosity equivalence at 40% lower cost, capturing commodity-grade food applications.
Strategic Opportunities
- Pharmaceutical-grade purification:Supercritical CO2 extraction removes proteinaceous impurities below 0.1%, unlocking USP-NF compliance for parenteral drug delivery systems.
- Cosmetic clean beauty positioning:Sephora and Ulta Beauty ingredient transparency requirements are creating premium slotting for INCI-listed "Astragalus Gummifer Gum" in prestige skincare.
- Direct-to-manufacturer platforms:Blockchain-traceable procurement portals are disintermediating traditional gum brokers, compressing margin capture for Tehran-based trading houses.
Industry Challenges
- Pharmacopeial certification timelines:USP-NF monograph compliance requires 24-36 month stability documentation that Iranian exporters struggle to finance.
- Harvest labor scarcity:Rural youth migration to Iranian cities is eroding the specialized incisions-and-drying knowledge base for premium ribbon-grade tragacanth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tragacanth Market |
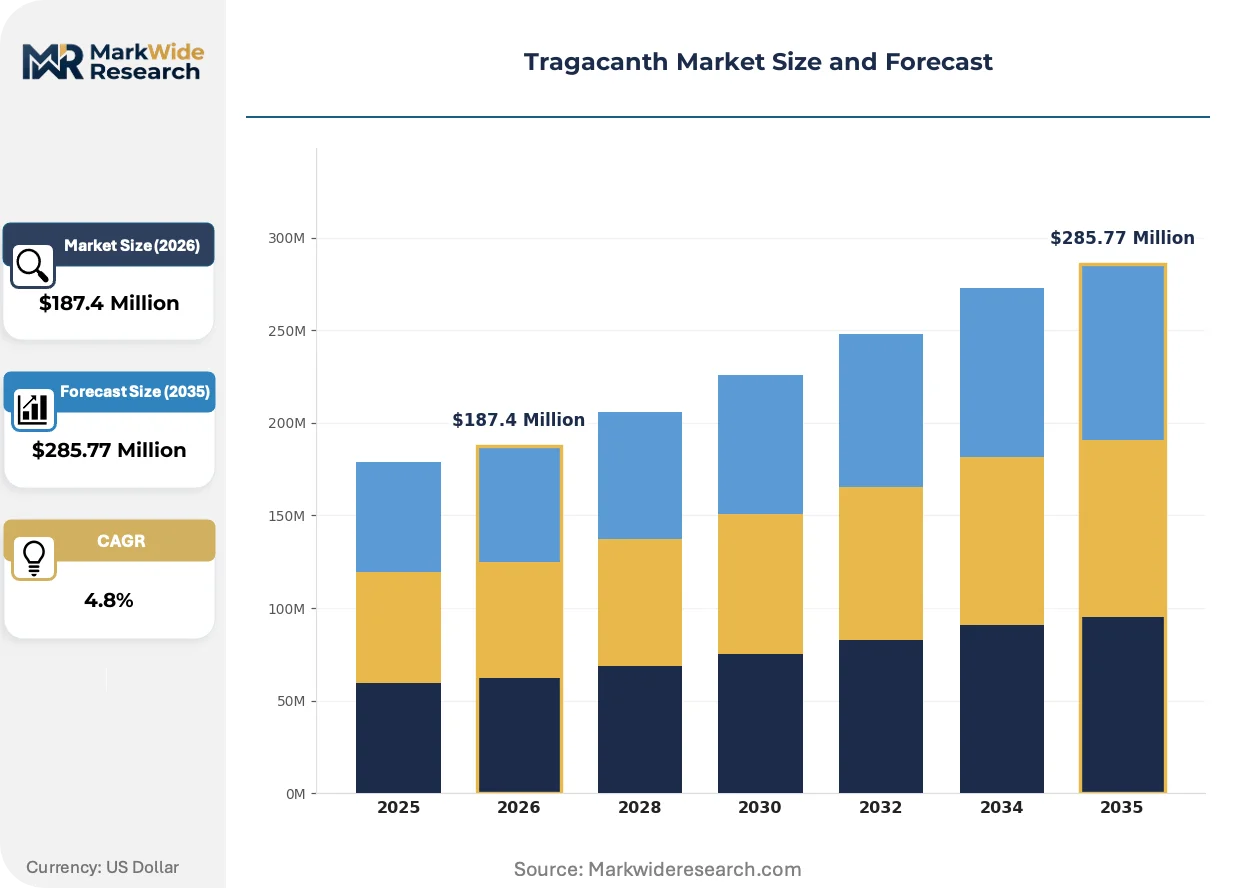
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Tragacanth, Modified Tragacanth, Blends, Powdered Tragacanth Application: Food Additives, Pharmaceuticals, Cosmetics, Textiles End User: Food Industry, Pharmaceutical Companies, Cosmetic Manufacturers, Textile Producers Form: Powder, Granules, Liquid, Gels |
| Companies Covered | Hawkins Watts Limited, Kachabo Gums, AEP Colloids, Alfa Chemical Corp., Polygal AG, Lakrena International, A.F. Suter & Co. Ltd., Scents of Earth, TIC Gums Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tragacanth Market Evolving Landscape
Processing technology and regulatory digitization are converging to redefine quality verification workflows, compressing the gap between artisanal harvesting and industrial-scale consistency requirements.
Enzymatic hydrolysis of tragacanthin polysaccharides is miniaturizing molecular weight distributions for targeted rheological performance. Nutraceutical soft-gel manufacturers in Germany and Switzerland are adopting these precision-grade fractions to replace gelatin in vegan capsule shells. The technology is miniaturizing batch-to-batch viscosity variation from ±15% to ±3%, enabling just-in-time mixing without pre-hydration buffers.
REACH Annex XVII restrictions on microplastic-containing synthetic thickeners are accelerating tragacanth substitution in European personal care. ECHA's 2023 restriction proposal on synthetic polymer microbeads has forced reformulation of 340 cosmetic SKUs toward natural hydrocolloid stabilizers. Color cosmetics brands in France and Italy are responding with accelerated supplier audits of Iranian export facilities.
Retailer-driven ingredient disclosure requirements are shortening qualification cycles for new tragacanth suppliers. Clean-label commitments from Whole Foods Market and Kroger now mandate third-party pesticide residue testing that commodity brokers cannot provide. This compression is most visible in North American plant-based dairy, where oat milk manufacturers are bypassing distributors to contract directly with ISO 22000-certified Iranian processors.
Tragacanth Market Segmentation
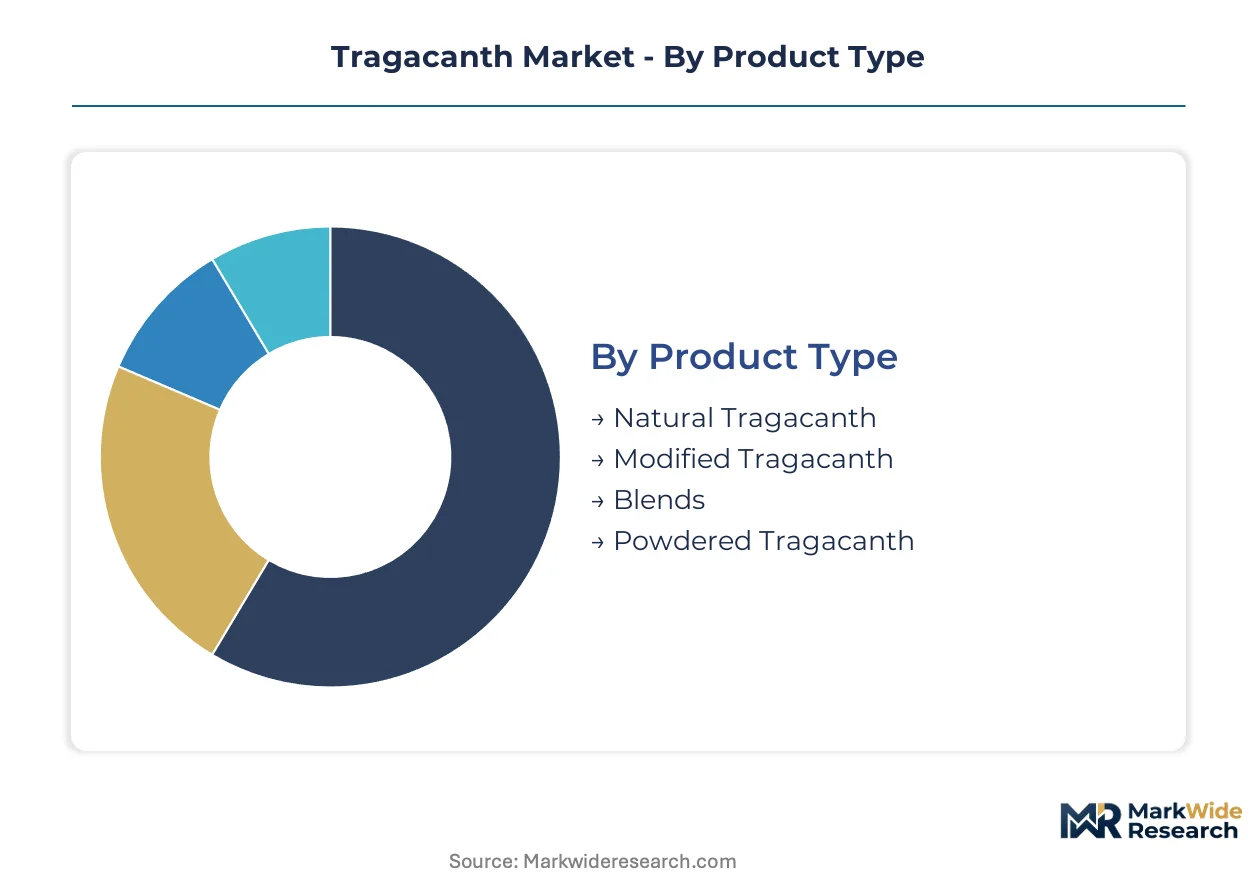
Tragacanth's functional versatility across viscosity ranges and regulatory grades creates distinct value pools that reward precise segment targeting. Manufacturers must align purification investment with end-use certification requirements to avoid margin erosion from over-engineering commodity applications.
Product Type:
Premium margin capture concentrates in grades achieving pharmacopeial compliance, while food-grade volumes dominate revenue tonnage.
- Natural Tragacanth:Unmodified ribbon or flake gum harvested from Astragalus gummifer retains native bassorin-tragacanthin ratios. Artisanal food producers in France and Switzerland specify this grade for traditional confectionery where raw authenticity commands price premiums.
- Modified Tragacanth:Chemically or enzymatically altered to standardize hydration kinetics and microbial stability. Industrial food processors in Germany and the United States favor this grade for plant-based dairy emulsions requiring batch-to-batch consistency.
- Blends:Compounded with guar, xanthan, or cellulose derivatives to achieve target rheology at reduced cost. Commodity sauce and dressing manufacturers use these formulations to hedge against tragacanth supply volatility.
- Powdered Tragacanth:Micronized particle size accelerates dispersion in high-shear mixing environments. Instant beverage premix producers value the reduced hydration time despite lower viscosity yield per unit weight.
The dominant share belongs to Natural Tragacanth, while Modified Tragacanth is closing the gap fastest.
Application:
Regulatory stringency separates pharmaceutical and food channels, with cosmetic applications emerging as a convergence zone for clean-label migration.
- Food Additives:Stabilizer and emulsifier functions in dressings, sauces, and frozen desserts. EFSA Regulation 1333/2008 compliance requirements are disqualifying ungraded Iranian imports from European retail supply chains.
- Pharmaceuticals:Tablet binder, sustained-release matrix, and suspending agent applications. USP-NF monograph compliance requires 24-36 month stability documentation that only three Iranian exporters currently maintain.
- Cosmetics:Natural thickener and film-former in skincare and color formulations. REACH Annex XVII restrictions on synthetic microplastic thickeners are accelerating substitution in French and Italian prestige brands.
- Textiles:Warp sizing and printing paste thickener for natural fiber processing. Turkish carpet weavers in Konya province sustain residual demand for high-mucilage ribbon grades.
Food Additives retains volume leadership, though Pharmaceuticals delivers superior unit economics.
End User:
Procurement sophistication varies sharply, with pharmaceutical formulators demanding full supply chain documentation that commodity food buyers rarely require.
- Food Industry:Processed food manufacturers, clean-label specialty producers, and institutional catering suppliers. Oat milk processors in North America now bypass distributors to contract directly with ISO 22000-certified Iranian processors.
- Pharmaceutical Companies:Generic drug manufacturers, innovator firms, and contract development organizations. Swiss and German soft-gel specialists are adopting enzymatically hydrolyzed fractions for vegan capsule shell formulations.
- Cosmetic Manufacturers:Multinational prestige brands, indie clean beauty labels, and private label producers. Sephora and Ulta Beauty ingredient transparency mandates are forcing accelerated supplier audits of Tehran export facilities.
- Textile Producers:Traditional handloom cooperatives and industrial weaving operations. Iranian domestic consumption absorbs most ribbon-grade output suitable for this declining application.
Food Industry commands tonnage leadership, while Pharmaceutical Companies generate the highest margin per kilogram.
Form:
Processing economics favor dry forms for storage stability, though liquid and gel preparations reduce manufacturing complexity for specific end-users.
- Powder:Standard industrial format with 12-18 month shelf life under controlled humidity. Most food and pharmaceutical specifications reference this form for procurement consistency.
- Granules:Coarse particle size reduces dusting and improves flowability in pneumatic conveying systems. Bulk sauce manufacturers prefer this form for automated dispensing equipment.
- Liquid:Pre-hydrated dispersions eliminate dissolution stage but require preservative systems and refrigerated logistics. Small-scale cosmetic formulators value the production simplicity despite higher per-unit cost.
- Gels:High-concentration preparations for direct incorporation into aqueous systems. Hospital compounding pharmacies use sterile gel preparations for extemporaneous suspensions.
Powder maintains absolute dominance, with Granules expanding most quickly in automated processing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators in Germany and Switzerland generate premium-grade demand, while food processors in North America and France drive volume procurement. Clean-label mandates from retailers in multiple geographies are compressing synthetic hydrocolloid use and validating tragacanth substitution.
Iran
Khorasan Razavi province sustains generational harvesting expertise for bassorin yield consistency that mechanized alternatives cannot match. The national standardization body enforces export grading protocols determining pharmaceutical versus food channel eligibility. Zagros mountain belt suppliers face sanctions-related payment friction that European buyers navigate through third-country banking arrangements.
Germany
Soft-gel manufacturers in Baden-Württemberg adopt enzymatically hydrolyzed tragacanth fractions for vegan capsule shell formulations. EFSA purity benchmarks under EU Regulation 1333/2008 disqualify ungraded gum imports, channeling volume toward certified Iranian exporters. Stuttgart-based nutraceutical compounders require ISO 17025 laboratory accreditation documentation for all hydrocolloid procurement.
United States
Oat milk processors now bypass distributors to contract directly with ISO 22000-certified Iranian processors. FDA food additive regulations under 21 CFR 184.1351 govern import eligibility and end-use labeling for clean-label dairy alternatives. Midwest plant-based dairy clusters in Minnesota and Wisconsin validate tragacanth functional parity with xanthan through accelerated stability testing.
Switzerland
Geneva and Basel pharmaceutical corridors demand USP-NF monograph compliance for sustained-release tablet applications. Swissmedic oversees excipient quality standards that Iranian exporters struggle to finance given 24-36 month stability documentation requirements. Precision-grade fraction adoption concentrates among contract development organizations serving innovator drug firms.
France
Prestige color cosmetics brands in Paris and Lyon accelerate supplier audits of Tehran export facilities following REACH Annex XVII restrictions. Sephora ingredient transparency mandates create premium slotting for INCI-listed Astragalus Gummifer Gum. Provence-based natural skincare formulators specify tragacanth as film-former replacement for synthetic microplastic thickeners.
Tragacanth Market Competitive Landscape
Player mix skews toward specialized gum traders and hydrocolloid distributors rather than integrated manufacturers. The supplier base bifurcates into export-grade and commodity-grade channels following ISO 9001 certification penetration. Strategic archetypes include ANZ-networked distributors, pharmaceutical-grade purification specialists, and direct-procurement platform operators. Competitive moves center on blockchain-traceable sourcing investments and supercritical CO2 extraction capability acquisition.
Within the distribution-specialist tier, Hawkins Watts Limited and AEP Colloids represent contrasting geographic and functional positioning. Hawkins Watts occupies a position anchored to ANZ network leverage for premium food-grade tragacanth sustainment. AEP Colloids exemplifies the pharmaceutical-grade purification archetype among European drug formulators. Kachabo Gums sits within the traditional trading house segment facing margin compression from direct-to-manufacturer procurement platforms.
| Leading Market Players |
|---|
| Hawkins Watts Limited |
| Kachabo Gums |
| AEP Colloids |
| Alfa Chemical Corp. |
| Polygal AG |
| Lakrena International |
| A.F. Suter & Co. Ltd. |
| Scents of Earth |
| TIC Gums Inc. |
| Others |
Value Network & Pricing Analysis
Harvest-labor scarcity in Iran's Zagros mountain belt is compressing capacity utilization for premium ribbon-grade tragacanth, concentrating pricing power among ISO 17025-certified exporters while elevating floor prices for pharmaceutical-grade lots. This scale-driven consolidation rewards backward-integrated processors with captive drying facilities and generational harvesting networks.
Pricing Analysis
Cost-plus contracts indexed to Iranian rial volatility dominate long-term offtake agreements between European pharmaceutical formulators and Tehran-based trading houses. Three-tier pricing structure across USP-NF certified, ISO 22000 food-grade, and ungraded commodity lots reflects certification investment and bassorin yield consistency. Pricing pressure stems from modified cellulose substitution in commodity sauce applications, where Dow and Ashland alternatives achieve functional parity at lower input cost. Commodity food manufacturers exhibit highest price sensitivity, while Swiss and German soft-gel specialists absorb premiums for enzymatically hydrolyzed fractions with batch-to-batch viscosity control.
Supply Chain Analysis
Container availability constraints on the Bandar Abbas-Rotterdam trade lane inflate inbound logistics costs for European hydrocolloid distributors, compressing margins on spot purchases. Raw material draws from Iran's Khorasan Razavi and Fars provinces, with secondary volumes from Turkey's Anatolian plateau and Afghanistan's Herat corridor. Supply rests on Astragalus shrub cultivation cycles, manual incision harvesting, and sun-drying infrastructure that mechanized alternatives cannot replicate. Single-source vulnerability concentrates in Iran's export-grade channel, where sanctions-related payment friction forces European buyers through third-country banking arrangements. Distribution runs through specialized gum brokers, direct-to-manufacturer platforms, and ANZ-networked distributors serving food-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tragacanth market rewards players who control scarce pharmacopeial certification capabilities and generational harvesting knowledge that rural youth migration is eroding. Incumbents must defend specialized asset positions while new entrants identify white-space in cosmetic clean beauty and blockchain-traceable procurement.
For Market Incumbents: Fortify USP-NF monograph compliance positions through 24-36 month stability documentation investments that Iranian exporters struggle to finance, creating defensive moats against commodity-grade competitors. Acquire supercritical CO2 extraction capability to remove proteinaceous impurities below 0.1% for parenteral drug delivery systems, capturing premium excipient demand from Swiss and German contract development organizations. Expand backward integration into Khorasan Razavi drying cooperatives to secure bassorin yield consistency that mechanized Turkish alternatives cannot match. For New Entrants and Emerging Players: Anchor in cosmetic clean beauty supply chains where Sephora and Ulta Beauty ingredient transparency mandates are forcing accelerated supplier audits of Tehran export facilities, creating qualification backlogs for established brokers. Target prestige skincare formulators in France and Italy seeking INCI-listed Astragalus Gummifer Gum as film-former replacement for REACH-restricted synthetic microplastic thickeners. Deploy blockchain-traceable procurement portals to disintermediate traditional gum brokers and compress margin capture for commodity trading houses. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pharmaceutical-grade purification specialists with enzymatic hydrolysis capability and ISO 17025 laboratory accreditation, as precision-grade fraction adoption concentrates among German and Swiss nutraceutical soft-gel manufacturers. Long-term viability hinges on sustained-release tablet formulation demand and vegan capsule shell substitution trends that synthetic polymers cannot replicate at equivalent shear-thinning profiles. Monitor EFSA purity benchmark enforcement under EU Regulation 1333/2008 as inflection indicator for certified Iranian exporter volume concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Certification Investment | USP-NF compliance unlocks parenteral drug delivery contracts from Swissmedic-regulated formulators. |
| Enzymatic Hydrolysis Capability Acquisition | Precision-grade fractions reduce batch-to-batch viscosity variation for German vegan capsule manufacturers. |
| Blockchain-Traceable Sourcing Platform | Direct-to-manufacturer procurement disintermediates Tehran trading houses and captures retailer-driven transparency premiums. |
| Backward Integration into Harvesting Cooperatives | Captive supply from Khorasan Razavi secures bassorin yield consistency against mechanized Turkish competition. |
| Cosmetic Clean Beauty Supplier Qualification | Sephora ingredient mandates create premium slotting for INCI-listed Astragalus Gummifer Gum in French prestige brands. |
Research Methodology
Operator-level perspectives from Iranian export grading inspectors, European pharmaceutical excipient procurement managers, German nutraceutical soft-gel formulators, and clean beauty cosmetic compounders anchored the qualitative base for this study. Primary fieldwork combined structured interviews with downstream hydrocolloid specification managers and upstream Astragalus harvesting cooperative leaders, validated against secondary sources including EFSA food additive filings, FDA 21 CFR 184.1351 regulations, Iranian national standardization body export protocols, and REACH Annex XVII restriction proposals. Bottom-up volume triangulation across food additive, pharmaceutical, and cosmetic application channels was cross-checked with top-down trade flow analysis from customs declarations.
Sensitivity analysis around Iranian sanctions exposure, drought frequency in Fars province, and substitution elasticity for modified cellulose gums informed scenario-weighted projections across the analysis window. Segmentation modeling incorporated product type tiers, application regulatory stringency levels, end-user procurement sophistication gradients, and form-based processing economics. CAGRs were derived from elasticity-adjusted demand curves and supply-constrained capacity buildout assumptions, with enzymatic hydrolysis adoption rates and REACH microplastic restriction timelines as key industry-specific inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained Iranian export channel access and stable EFSA purity benchmark enforcement; material deviation would warrant model refresh. Forecasts reflect documented assumptions around harvest labor availability, certification timeline financing, and synthetic hydrocolloid substitution thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Anti-Wear Additives Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Citrate Ester Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Global Low-Profile Additive Market
Additives
Caprylyl Glycol Market
Additives
Agrochemicals Additives Market
Additives
Antimicrobial Ingredients Market
Additives
Europe Feed Additives Market
Additives
Chitosan Powder Market
Additives
Anti-Settling Agents Market
Additives
Monocalcium Phosphate Market
Additives
Plastic Fillers Market
Additives
Asia Pacific Plastic Additives Market
Additives
Fluid Loss Additives Market