
 Global Propyl Acetate Market | 2026-2036
Global Propyl Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Propyl Acetate Market Foresight
Multi-source procurement among large coating formulators is consolidating as volatile n-propyl alcohol feedstock costs push buyers toward fewer, deeper supplier relationships. BASF SE leverages its integrated C1-value-chain architecture to stabilize ester output despite raw-material swings. Dow Inc. anchors North American supply through its Texas Gulf Coast manufacturing complex. OQ Chemicals GmbH differentiates via specialized industrial-grade streams tailored to European automotive OEM specifications.
Propyl acetate is an ester formed from n-propanol and acetic acid, characterized by a molecular weight of 102.13 g/mol and a boiling point near 101.5°C, functioning primarily as a medium-evaporation solvent in surface-coating systems. Industrial-grade material dominates volume flows due to its cost-positioning in high-throughput coating and adhesive operations, while pharmaceutical-grade streams command premium positioning through stringent impurity thresholds. Solvent applications absorb the majority of output, though flavors and fragrances represent a fast-growing niche where reagent-grade purity unlocks formulation access for fragrance producers.
EPA regulations in the United States restrict volatile organic compound emissions from architectural coatings, directly shaping propyl acetate demand in low-VOC reformulations. REACH registration requirements in Europe govern industrial-grade import volumes and impurity disclosure protocols. China's MEE enforces national standards on solvent emissions from furniture and automotive coating facilities. Stakeholders must monitor how feedstock bio-based substitution pathways and regional emission-credit mechanisms reshape procurement economics across these jurisdictions.
Market Dynamics
Waterborne coating reformulations are compressing solvent demand curves as automotive and furniture manufacturers absorb higher volumes of propyl acetate under tightening emission protocols across East Asia.
Growth Catalysts
- China's MEE emission standards:National solvent emission limits for furniture and automotive coating facilities are forcing formulators toward compliant ester solvents. Industrial-grade propyl acetate flows are accelerating into Guangdong and Zhejiang manufacturing clusters.
- Automotive refinishing expansion:Collision repair networks in Germany and the United States are standardizing on medium-evaporation esters for basecoat-clearcoat systems. OEM specification convergence is pulling consistent industrial-grade volumes.
- Wood furniture export manufacturing:Vietnamese and Indonesian finishing facilities serving European retail chains are adopting propyl acetate to meet REACH-registered import requirements. Export compliance is reshaping solvent procurement in Southeast Asian supply chains.
Market Restraints
- N-propanol feedstock volatility:Crude propylene price swings transmit directly into ester production economics. Integrated producers with captive alcohol supply command structural cost advantages over merchant buyers.
- Gulf Coast supply concentration:North American propyl acetate output clusters along Texas chemical corridors. Hurricane exposure and ethylene chain disruptions create regional shortage risk during Atlantic storm seasons.
- Waterborne technology substitution:High-solids and UV-curable coating platforms are compressing solvent loading factors in architectural applications. Formulation chemistry advances are eroding addressable solvent volume in mature end-uses.
Strategic Opportunities
- India's BIS industrial chemical certification:Formal adoption of Indian Standards for solvent purity is creating a regulated import channel. Early REACH-registered suppliers can establish specification leadership before domestic capacity scales.
- Fragrance-grade ester demand:Reagent-grade propyl acetate for flavor and fragrance synthesis commands premium positioning. European fragrance houses are qualifying new suppliers to diversify beyond traditional ester sources.
- Bio-based acetic acid integration:Fermentation-derived acetic acid is converging with renewable n-propanol pathways. Brand-committed coating formulators are sourcing mass-balance-certified esters for scope 3 emission reductions.
Industry Challenges
- REACH registration data gaps:Industrial-grade importers face substance evaluation deadlines without complete toxicological dossiers. Compliance timeline compression is straining smaller traders with limited regulatory affairs capacity.
- Multi-grade inventory complexity:Pharmaceutical, industrial, and reagent grades require segregated storage and handling infrastructure. Distribution networks must absorb working capital intensity to serve fragmented purity requirements.
- Automotive coating qualification cycles:OEM solvent approvals extend across 18-24 month validation protocols. Supplier switching costs lock formulators into incumbent relationships despite marginal price differentials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Propyl Acetate Market |
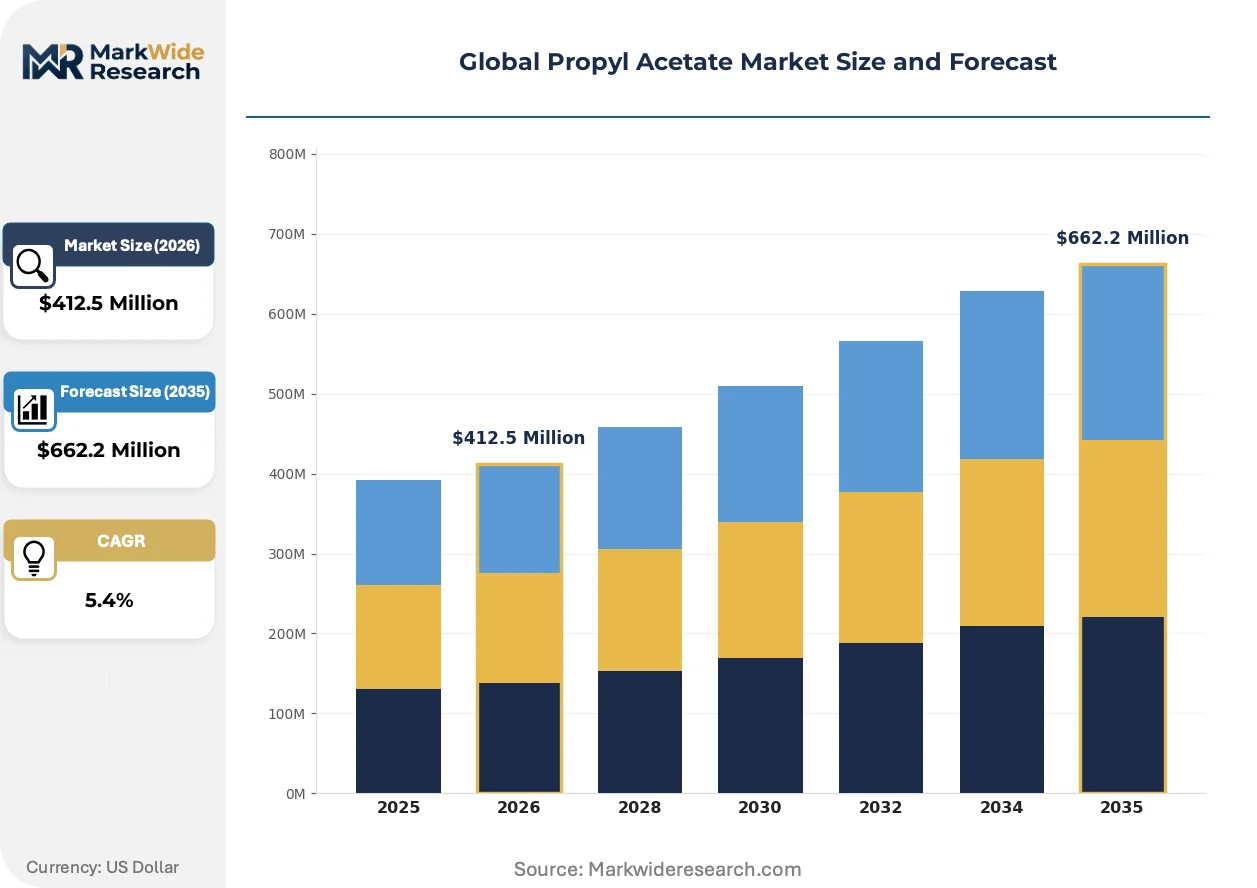
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Industrial Grade, Reagent Grade, Food Grade, Cosmetic Grade Application: Solvents, Coatings, Printing Inks, Adhesives, Pharmaceuticals, Flavors & Fragrances End User Industry: Paint Manufacturers, Printing Companies, Pharmaceutical Firms, Fragrance Producers, Adhesive Makers, Cosmetic Manufacturers Packaging Type: Drums, Bulk Containers, Carboys, IBC Totes, Cylinders |
| Companies Covered | BASF SE, Dow Inc., Eastman Chemical Company, Solvay S.A., OQ Chemicals GmbH, Showa Denko K.K., Daicel Corporation, Sasol, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Propyl Acetate Market Shifts & Advancements
Reactive diluent technologies and bio-based feedstock pathways are restructuring how coating formulators specify ester solvents across automotive and industrial applications.
Continuous esterification reactor designs are overtaking batch production for industrial-grade material. Automotive coating formulators in Germany and Japan are qualifying continuously produced esters for reduced batch-to-batch viscosity variation. This process technology is enabling tighter solvent specification bands that compress quality-adjusted procurement costs for high-throughput finishers.
REACH authorization requirements for Substances of Very High Concern are tightening impurity disclosure protocols for industrial-grade imports. European automotive OEMs are cascading substance restriction lists down coating supply chains. Formulators serving BMW, Volkswagen, and Stellantis networks are demanding full composition data that exceeds standard industrial certificates of analysis.
Direct mill-supply arrangements are consolidating solvent procurement among large coating manufacturers. Regional distributors in the United States are losing volume to tanker-truck direct deliveries from Gulf Coast producers. This channel compression is most visible in automotive refinish supply chains where Axalta, PPG, and BASF coating divisions negotiate integrated solvent-of-esters contracts.
Global Propyl Acetate Market Segmentation
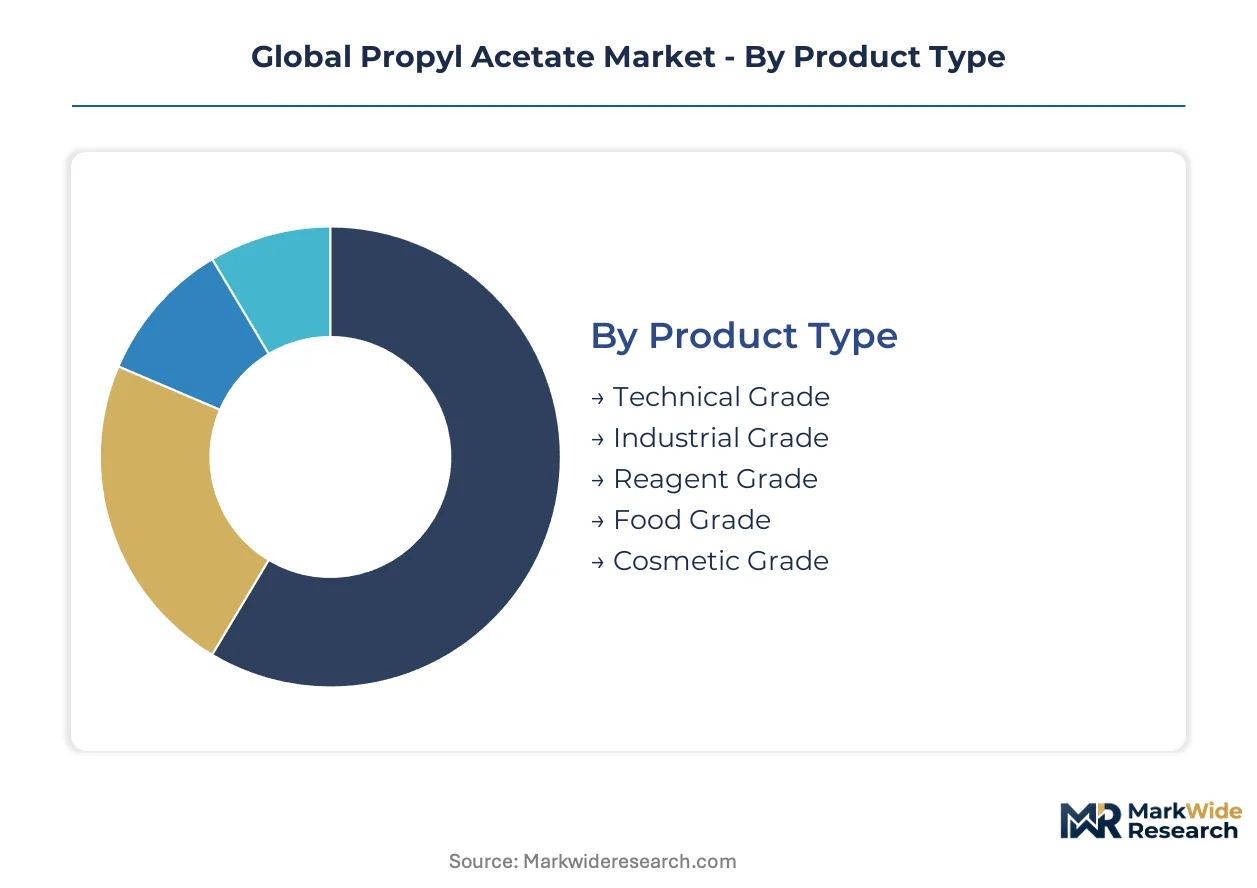
Propyl acetate specification tiers determine pricing architecture and regulatory burden across coating, pharmaceutical, and fragrance supply chains. Grade purity thresholds and packaging configurations directly shape procurement economics for formulators serving automotive OEMs versus artisan fragrance houses.
Product Type:
Technical specification axes separate commodity solvent flows from premium-grade streams where impurity thresholds unlock formulation access.
- Technical Grade:Contains residual acids and water content up to 0.5%, suitable for industrial cleaning and degreasing operations where solvent recovery systems tolerate broader specification bands. Paint manufacturers in China's Guangdong province absorb technical-grade volumes for cost-sensitive wood primer formulations under MEE emission compliance timelines.
- Industrial Grade:Specifications cap moisture at 0.1% and acid number below 0.02 mg KOH/g, enabling consistent drying performance in automotive basecoat-clearcoat systems. German collision repair networks standardize on industrial-grade material for OEM-matched refinishing, pulling consistent volumes through qualified distributor channels.
- Reagent Grade:Purity exceeds 99.5% with comprehensive impurity profiling for analytical and research applications. European fragrance houses in Grasse and Geneva qualify reagent-grade streams for captive esterification of specialty aroma chemicals.
- Food Grade:Meets FCC and JECFA specifications for residual solvent limits in flavor extraction processes. Coffee decaffeination facilities in Colombia and Indonesia specify food-grade propyl acetate for natural caffeine extraction cycles.
- Cosmetic Grade:Conforms to EC 1223/2009 and FDA 21 CFR requirements for dermal exposure limits. Korean skincare formulators source cosmetic-grade material for nail polish and fragrance solvent applications.
Industrial grade leads on scale; reagent grade leads on momentum.
Application:
End-use functional requirements drive solvent loading factors and evaporation rate specifications across divergent formulation chemistries.
- Solvents:Medium-evaporation characteristics position propyl acetate between ethyl acetate and butyl acetate in lacquer thinner formulations. Vietnamese furniture exporters specify solvent-grade material for European retail chain compliance under REACH-registered import protocols.
- Coatings:Automotive refinishing demands precise viscosity control and orange peel minimization in metallic basecoats. PPG and Axalta coating divisions negotiate direct tanker-truck deliveries from Gulf Coast producers to compress working capital cycles.
- Printing Inks:Fast-drying properties suit gravure and flexographic packaging applications. Flexible packaging converters in India's Maharashtra state absorb industrial-grade volumes for food-contact laminate production.
- Adhesives:Solvent-borne pressure-sensitive adhesive formulations require consistent ester purity for tack stability. Tape manufacturers in Japan's Kansai region specify industrial-grade material for automotive interior bonding applications.
- Pharmaceuticals:Extraction and crystallization processes demand pharmaceutical-grade certification with complete impurity disclosure. CDSCO-registered Indian API producers source compliant material for export to regulated markets.
- Flavors & Fragrances:Reagent-grade purity enables ester synthesis for natural-identical aroma compounds. Swiss fragrance houses in Geneva are qualifying alternative suppliers to diversify beyond traditional European ester sources.
Coatings applications anchor volume throughput; flavors and fragrances climb the fastest.
End User Industry:
Customer scale and specification discipline fragment procurement patterns across multinational OEMs and regional specialists.
- Paint Manufacturers:Waterborne reformulation mandates in China and the EU are compressing solvent loading factors while elevating purity requirements for remaining ester content. Large formulators consolidate procurement through direct mill-supply arrangements.
- Printing Companies:Flexible packaging demand in Southeast Asia drives solvent consumption for rotogravure ink systems. Indonesian converters serving export markets specify REACH-registered material for European brand owner compliance.
- Pharmaceutical Firms:API synthesis and extraction processes require pharmaceutical-grade certification with batch-specific COA documentation. Indian generic producers represent expanding demand as BIS standards formalize import channels.
- Fragrance Producers:Natural-identical ester synthesis commands premium positioning for reagent-grade streams. Grasse-based houses maintain strict supplier qualification protocols extending across 18-24 month validation cycles.
- Adhesive Makers:Pressure-sensitive tape and label applications consume industrial-grade material for solvent-borne acrylic systems. Japanese automotive suppliers specify consistent viscosity grades for interior trim bonding.
- Cosmetic Manufacturers:Nail care and personal fragrance formulations require cosmetic-grade certification with dermal safety documentation. Korean beauty conglomerates source through approved distributors with segregated storage infrastructure.
Paint manufacturers command volume concentration; fragrance producers deliver steepest expansion trajectory.
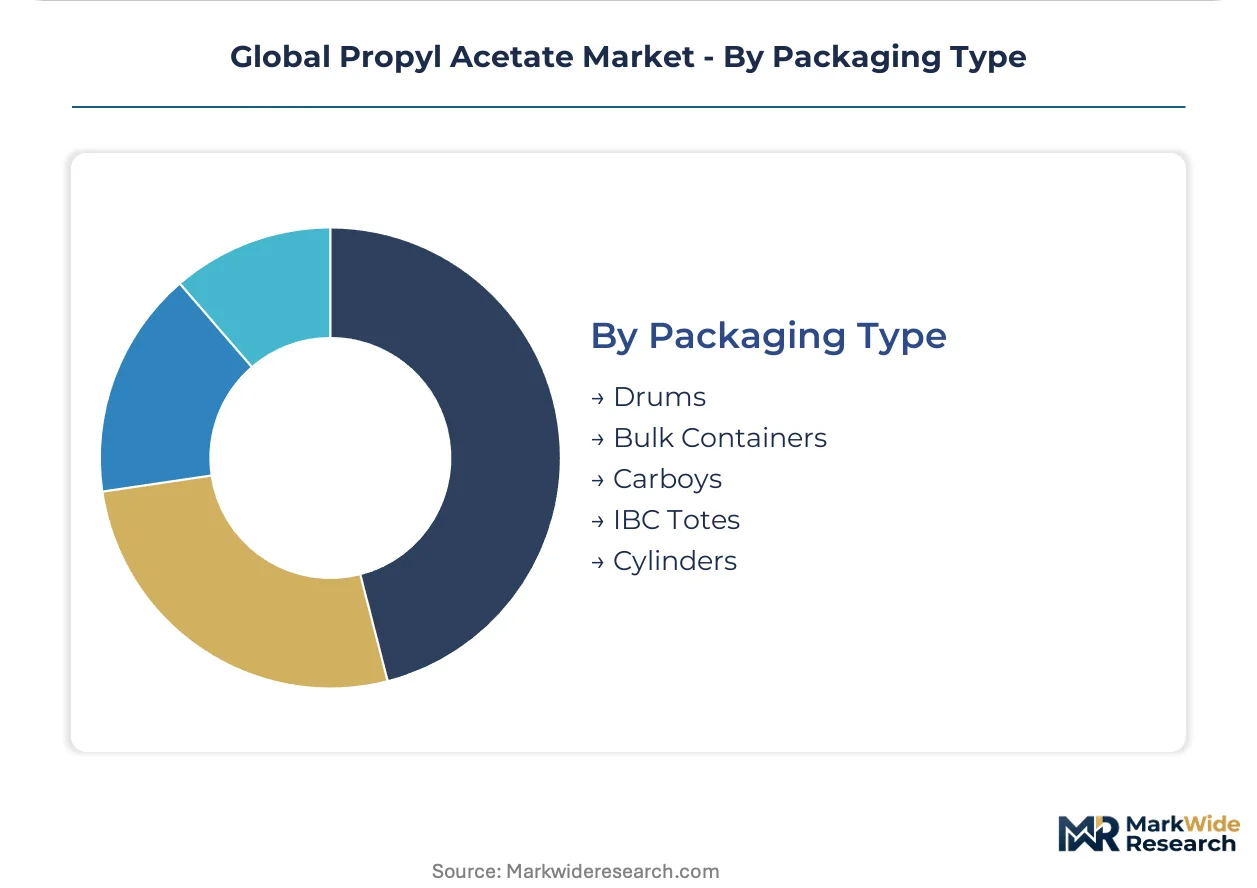
Packaging Type:
Logistics configuration aligns with customer scale, regulatory documentation requirements, and inventory velocity across fragmented end-use bases.
- Drums:200-liter steel drums serve mid-sized coating formulators and adhesive producers with moderate consumption rates. Regional distributors in the United States maintain drum stock for automotive refinish jobbers.
- Bulk Containers:Tanker-truck and railcar deliveries anchor procurement for large paint manufacturers and printing companies with captive storage infrastructure. Direct supply contracts compress per-unit logistics costs.
- Carboys:Glass or HDPE carboys accommodate laboratory-scale and pilot-plant consumption for pharmaceutical and fragrance synthesis. Swiss and German research facilities specify carboy packaging for reagent-grade material.
- IBC Totes:Intermediate bulk containers bridge drum and bulk economies for medium-scale adhesive and cosmetic manufacturers. Southeast Asian converters favor IBC configurations for flexibility across multi-product facilities.
- Cylinders:Pressurized gas cylinders serve specialized applications requiring vapor-phase delivery or ultra-high-purity handling. Semiconductor and electronics cleaning applications in Japan and South Korea specify cylinder packaging.
Bulk containers dominate tonnage flows; IBC totes gain share fastest among mid-scale formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province's manufacturing clusters absorb the largest industrial-grade propyl acetate volumes as waterborne coating reformulations accelerate under tightening emission protocols. National regulators across multiple jurisdictions are reshaping solvent procurement economics through divergent compliance frameworks.
China
Automotive refinishing and wood furniture finishing operations in Guangdong and Zhejiang provinces drive concentrated demand for industrial-grade material. The Ministry of Ecology and Environment enforces national solvent emission standards that force formulators toward compliant ester solvents. Manufacturing clusters in the Pearl River Delta are absorbing larger volumes as waterborne coating formulations gain regulatory traction.
Germany
Collision repair networks standardize on medium-evaporation esters for basecoat-clearcoat systems requiring precise viscosity control. REACH authorization requirements for Substances of Very High Concern tighten impurity disclosure protocols for industrial-grade imports. Automotive coating formulators in Baden-Württemberg and North Rhine-Westphalia are qualifying continuously produced esters for reduced batch-to-batch variation.
United States
Architectural coatings manufacturers reformulate under EPA volatile organic compound emission restrictions that directly shape propyl acetate demand. The Texas Gulf Coast manufacturing complex anchors North American supply through integrated production infrastructure. Hurricane exposure along chemical corridors creates regional shortage risk during Atlantic storm seasons.
India
Flexible packaging converters in Maharashtra absorb industrial-grade volumes for food-contact laminate production. The Bureau of Indian Standards formal adoption of industrial chemical certification creates regulated import channels for early REACH-registered suppliers. CDSCO-registered API producers in Gujarat and Telangana source compliant material for export to regulated markets.
Japan
Tape manufacturers in the Kansai region specify industrial-grade material for solvent-borne pressure-sensitive adhesive formulations. METI industrial standards govern solvent purity specifications for automotive interior bonding applications. Continuous esterification reactor designs from Japanese equipment suppliers enable tighter solvent specification bands for high-throughput finishers.
Global Propyl Acetate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based feedstock differentiation and specialty-grade positioning. The vendor base clusters around integrated petrochemical majors with captive alcohol supply and regional specialists serving fragrance and pharmaceutical purity tiers. Three archetypes dominate: integrated C1-value-chain operators, regional industrial-grade suppliers, and reagent-grade specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure backward integration into n-propanol feedstock.
Among integrated chemical majors, BASF SE, Dow Inc., and OQ Chemicals GmbH exemplify divergent geographic anchoring strategies. BASF SE represents the integrated value-chain archetype with European manufacturing presence. Dow Inc. anchors North American supply through Gulf Coast infrastructure. OQ Chemicals GmbH occupies a position within the specialized industrial-grade tier serving automotive OEM specification requirements.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Eastman Chemical Company |
| Solvay S.A. |
| OQ Chemicals GmbH |
| Showa Denko K.K. |
| Daicel Corporation |
| Sasol |
| Celanese Corporation |
| Others |
Supply & Pricing Matrix
Continuous esterification reactor designs are compressing unit production costs while concentrating supply among producers with capital-intensive process technology. German and Japanese automotive coating formulators are qualifying continuously produced esters for tighter viscosity specification bands, rewarding integrated producers with captive n-propanol supply and squeezing batch-process merchant suppliers.
Pricing Analysis
Crude propylene and n-propanol feedstock volatility transmits directly into ester production economics, forcing contract-based long-term offtake agreements to dominate procurement for large coating formulators. Price differentiation rests on certification grade and volume scale, with REACH-registered industrial-grade material commanding premiums over technical-grade alternatives. Cost compression in technical-grade streams is intensifying because Chinese MEE compliance deadlines are accelerating demand for specification-upgraded material. Paint manufacturers in Guangdong province exhibit highest price sensitivity, while European fragrance houses demonstrate lowest sensitivity due to 18-24 month supplier qualification lock-ins.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand as PPG, Axalta, and BASF coating divisions negotiate integrated solvent-of-esters contracts with Gulf Coast producers. Production gravity centers on the United States, Germany, and China, with raw material dependencies drawing from propylene feedstock, acetic acid, and catalytic esterification technology. Single-source vulnerability concentrates in Texas chemical corridors where hurricane exposure creates regional shortage risk during Atlantic storm seasons. Distribution runs through tanker-truck direct deliveries for large formulators and regional drum stock for automotive refinish jobbers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Propyl Acetate Market functions as a stable compounder anchored by regulatory-driven solvent reformulation mandates that guarantee sustained demand replacement cycles across coating supply chains.
For Market Incumbents: To counter waterborne technology substitution eroding architectural solvent volumes, BASF SE and Dow Inc. should deepen backward integration into bio-based n-propanol pathways while expanding continuous reactor capacity in Texas and Ludwigshafen to capture specification premiums from German automotive OEMs. For New Entrants and Emerging Players: The price-point gap between reagent-grade fragrance material and industrial-grade coatings feedstock offers entry latitude for specialty ester producers targeting Indian BIS-certified import channels before domestic capacity scales, with direct qualification to European fragrance houses in Grasse as the optimal go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional industrial-grade suppliers lacking REACH registration dossiers, though long-term viability across a 5-10 year window favors integrated C1-value-chain operators with captive alcohol supply; the signal to watch is MEE enforcement intensity in Guangdong province as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into N-Propanol | Captive feedstock supply insulates BASF SE from propylene price volatility. |
| Continuous Esterification Capacity Expansion | Tighter specification bands unlock German automotive OEM qualification protocols. |
| REACH Registration Investment | Full toxicological dossiers enable European industrial-grade import channel access. |
| Bio-Based Acetic Acid Partnership | Fermentation-derived inputs satisfy brand-committed coating formulator scope 3 targets. |
| Direct Mill-Supply Arrangement | Tanker-truck delivery contracts compress working capital cycles for PPG and Axalta. |
Research Methodology
Multiple input streams — primary interviews with plant managers, procurement leads at coating OEMs, distribution channel partners, and technical R&D directors; secondary validation through customs/trade data, ACC and Cefic industry reports, and SEC 10-K filings; plus patent and equipment supplier documentation — were reconciled through bottom-up and top-down triangulation to construct segment-level volume and value estimates.
Historical production and consumption trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the analysis window. The forecast framework models grade tier, end-use industry, packaging format, and regional production hub as primary segmentation dimensions, with CAGRs derived from feedstock cost pass-through elasticity and regulatory compliance timeline acceleration. Key inputs include MEE enforcement schedules in China and REACH authorization deadlines in Europe.
The model assumes a particular technology adoption path; alternative pathways for waterborne coating substitution would alter the outlook if high-solids or UV-curable platforms achieve faster penetration than baseline assumptions. Forecasts reflect documented assumptions regarding feedstock price corridors and regulatory implementation fidelity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Phthalate Plasticizer Market
Additives
Paint Additives Market
Additives
Calcium Diglutamate Market
Additives
Plastic Fillers Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Piperonyl Butoxide (PBO) Market
Additives
Sodium Stearyl Fumarate Market
Additives
Tragacanth Market
Additives
Global Synthetic Tackifier Market
Additives
Fuel Additives Market
Additives
Pearlizers Market
Additives
Silicone Additives Market
Additives
Octane Improver Fuel Additives Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Anti-Pollution Ingredients Market