
 Japan Sodium Reduction Ingredient Market | 2026-2036
Japan Sodium Reduction Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Sodium Reduction Ingredient Market Foresight
Food technologist shortages in Japan's flavor-modulation specialty is reorganizing how domestic manufacturers scale clean-label sodium replacement programs. Ajinomoto Co., Inc. leverages its amino acid expertise to dominate umami-based salt alternatives. Cargill Inc anchors supply security through regional potassium chloride distribution networks. Kerry Group plc differentiates via integrated taste and nutrition platforms tailored to Japanese palates.
Japan sodium reduction ingredients comprise functional compounds—potassium chloride, yeast extracts, nucleotide blends, and mineral salts—engineered to replicate sodium's osmotic, preservative, and sensory properties at reduced concentrations, typically delivering 25-50% sodium reduction without compromising microbial stability or consumer acceptance. The ingredient type dimension shows potassium chloride and flavor enhancers capturing the fastest expansion as manufacturers bypass sodium chloride's cardiovascular stigma, while the application dimension reveals processed foods and sauces as the mature volume base where reformulation mandates bite deepest, with snacks and beverages representing emerging margin pools as clean-label claims proliferate.
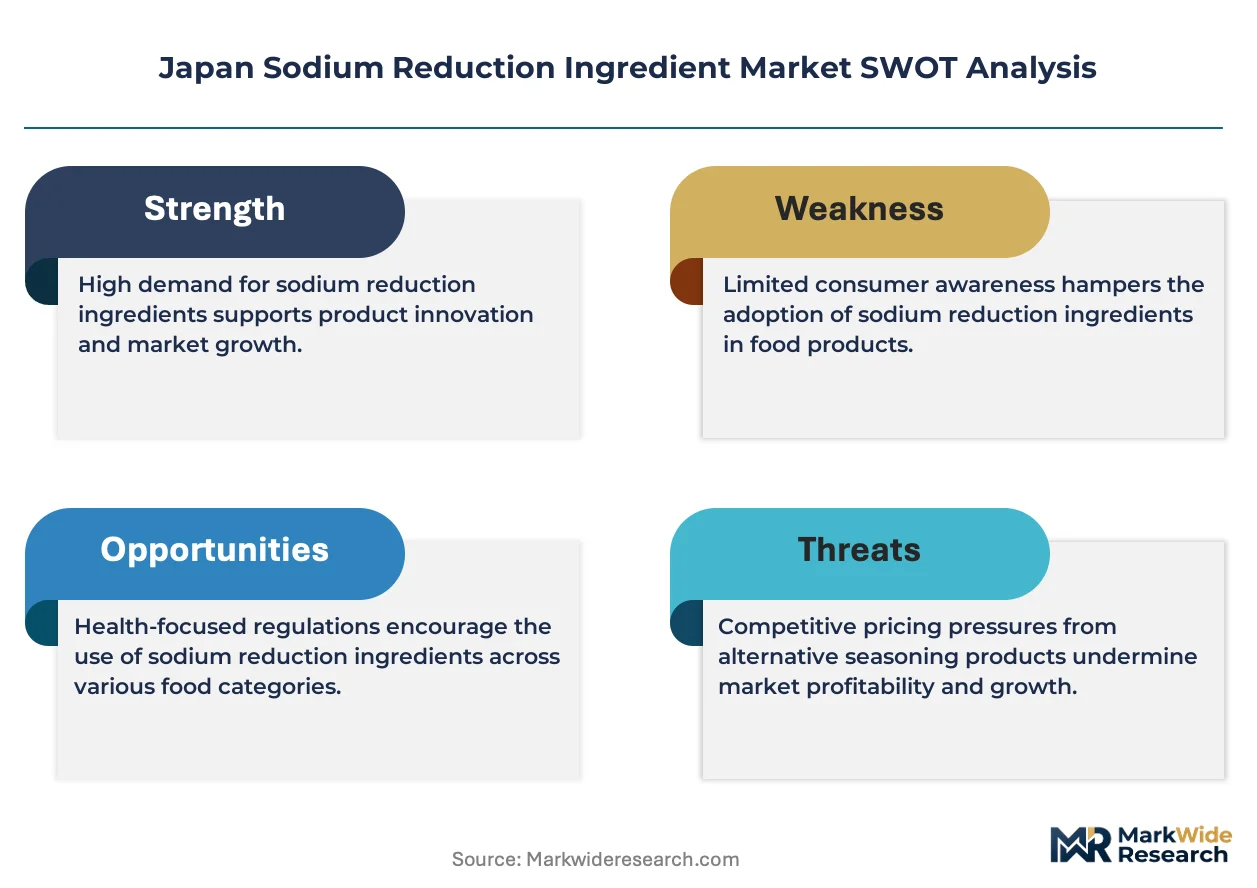
Japan's Ministry of Health, Labour and Welfare (MHLW) enforces progressive sodium reduction benchmarks through its Health Japan 21 initiative, compelling food manufacturers to reformulate or risk exclusion from institutional procurement and school meal programs. METI's Food Industry Vision reinforces this pressure by linking processed food innovation subsidies to documented sodium reduction achievements. Stakeholders must monitor how PMDA's evolving stance on potassium-based additives as novel food ingredients reshapes formulation freedom and import clearance timelines.
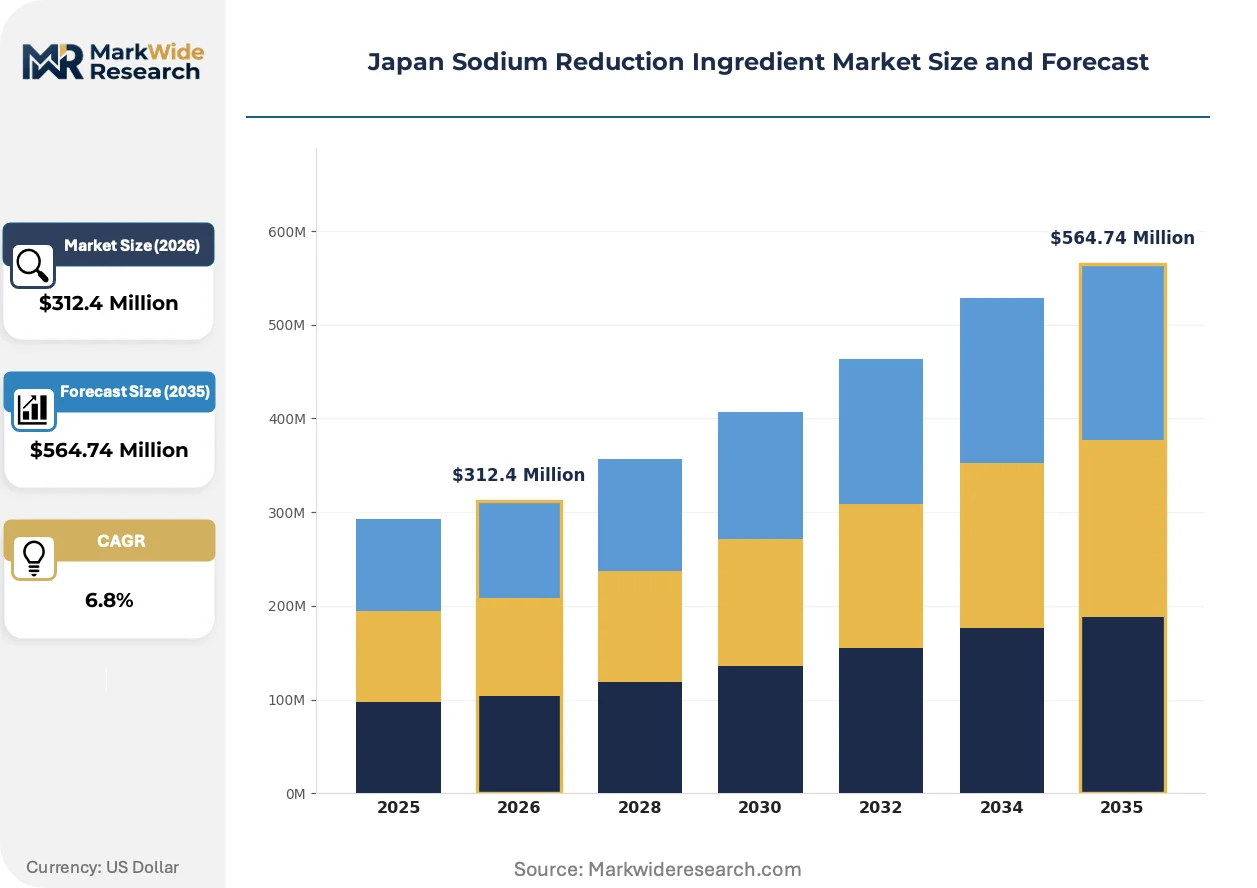
Market Dynamics
Japan's sodium reduction ingredient market pivots on MHLW's tightening Health Japan 21 benchmarks, which compel food manufacturers to reformulate processed products or face exclusion from institutional procurement channels. This regulatory compression is reshaping ingredient sourcing priorities across the archipelago's food processing clusters.
Growth Catalysts
- Health Japan 21 Mandates:MHLW's progressive sodium reduction targets force manufacturers to adopt functional salt alternatives in sauces, processed foods, and ready meals to maintain school meal program eligibility.
- Umami Science Maturation:Amino acid-based flavor modulation technologies enable 35-50% sodium reduction without sensory compromise, accelerating adoption in Tokyo's dense food processing corridor.
- Processed Food Export Requirements:Japanese manufacturers reformulate for reduced-sodium specifications demanded by health-conscious import markets in Southeast Asia and North America.
Market Restraints
- Potassium Chloride Supply Concentration:Domestic food-grade potassium chloride relies heavily on regional import channels, exposing formulators to logistics volatility and currency fluctuation risks.
- PMDA Novel Ingredient Classification:Emerging mineral salt blends face extended safety review timelines, delaying product launches and freezing formulation pipelines for 18-24 month windows.
- Yeast Extract Cost Structure:Fermentation-based flavor enhancers carry 40-60% raw material premiums versus conventional salt, compressing margins in mass-market sauce categories.
Strategic Opportunities
- Kansai Underpenetration:Osaka-Kobe's food manufacturing base lags Tokyo in clean-label sodium replacement adoption, creating procurement conversion potential for technical ingredient suppliers.
- Beverage Clean-Label Pivot:Sports drinks and functional beverages represent nascent application territory where mineral salt systems can replace sodium without taste degradation.
- METI Innovation Subsidies:The Food Industry Vision ties processed food R&D grants to documented sodium reduction achievements, subsidizing pilot-scale reformulation programs.
Industry Challenges
- Flavor Chemist Scarcity:Japan's specialized workforce in umami modulation and salt taste receptor science remains critically thin, extending product development cycles.
- Legacy Equipment Retrofit Costs:Existing sodium chloride handling infrastructure requires capital-intensive modification to process hygroscopic potassium chloride and nucleotide blends without caking or flow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Sodium Reduction Ingredient Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Sodium Chloride, Potassium Chloride, Sea Salt, Flavor Enhancers Application: Processed Foods, Sauces, Snacks, Beverages Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Foodservice Customer Type: Food Manufacturers, Retailers, Restaurants, Health-conscious Consumers |
| Companies Covered | Cargill Inc, Givaudan SA, Tate & Lyle Plc, BASF SE, Ajinomoto Co., Inc., Kerry Group plc, Royal DSM NV, Archer Daniels Midland, Armor Proteines SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Sodium Reduction Ingredient Market Shifts & Advancements
Active reformulation across Japan's processed food sector is compressing development timelines and forcing ingredient suppliers to demonstrate measurable sodium reduction without sensory trade-offs. Three converging developments are restructuring competitive positioning.
Yeast extract and nucleotide-based flavor enhancers are bifurcating the sodium replacement landscape. Premium sauce manufacturers in the Kanto region adopt these systems for 30-40% sodium reduction with clean-label positioning, while mass-market processors cling to potassium chloride for cost containment. This technological split is creating distinct supply chain tiers with incompatible specification requirements.
METI's Food Industry Vision reinforces MHLW health targets by linking innovation subsidies to verified sodium reduction metrics. Processed food manufacturers must document formulation changes to qualify for procurement preferences and R&D tax incentives. The policy convergence tightens most severely on institutional meal suppliers serving schools and hospitals, where sodium ceilings are now binding constraints.
Direct technical partnerships between ingredient suppliers and mid-tier food processors are displacing traditional distributor-mediated procurement in the Kansai region. Manufacturers seek collaborative formulation support rather than commodity transactions, exchanging long-term supply agreements for dedicated application laboratories. This relationship shift concentrates most visibly in Osaka's sauce and seasoning production cluster.
Japan Sodium Reduction Ingredient Market Segmentation
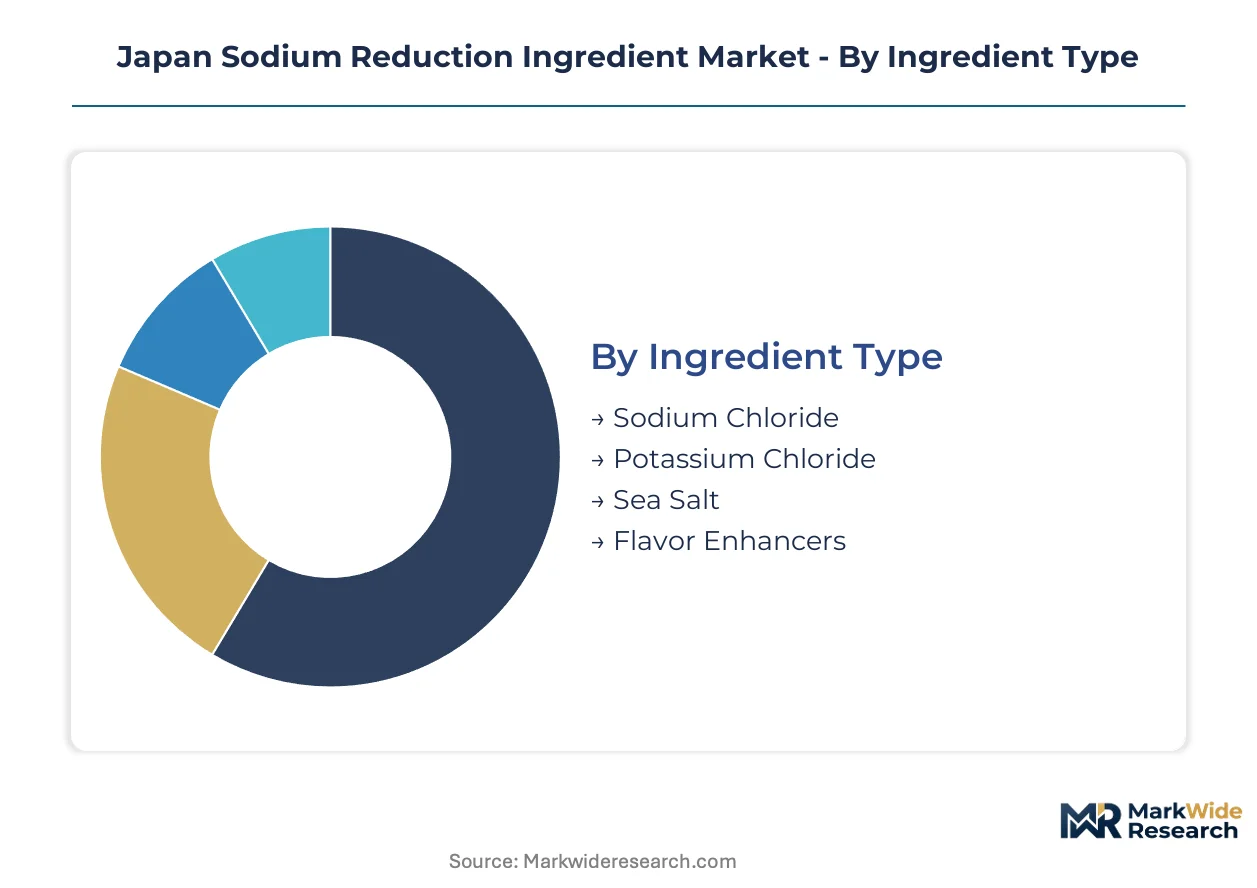
Japan's sodium reduction ingredient procurement flows through distinct channel hierarchies that determine specification requirements and technical service intensity. Ingredient suppliers calibrate their sales coverage and application support based on where segments concentrate demand.
Ingredient Type:
Channel mix varies sharply by ingredient chemistry—potassium chloride and mineral salts move through bulk industrial distributors serving Kanto food manufacturers, while flavor enhancers require technical sales teams for direct formulation partnership.
- Potassium Chloride:Crystalline salt substitute delivering 25-40% sodium reduction in processed foods and sauces. Demand concentrates in Tokyo's institutional meal supply chain, where MHLW sodium ceilings for school programs force rapid adoption despite hygroscopic handling challenges.
- Flavor Enhancers:Yeast extracts and nucleotide blends modulating umami receptors to mask potassium chloride's metallic aftertaste. Osaka-Kobe sauce manufacturers drive procurement growth as clean-label positioning displaces monosodium glutamate in premium export formulations.
- Sodium Chloride:Modified crystal structures and reduced-density formulations for gradual sodium reduction in mass-market categories. Food manufacturers blend reduced-sodium salt with potassium chloride to manage consumer taste migration.
- Sea Salt:Mineral-rich evaporative salts marketed for trace element content and regional provenance claims. Specialty retailers and premium foodservice channels absorb limited volumes for positioning differentiation.
Potassium chloride dominates installed base. Flavor enhancers are where expansion concentrates.
Application:
Cost tier stratification separates mature applications with thin margins from emerging categories where technical premiums stick—processed foods anchor volume, beverages command formulation fees.
- Processed Foods:Ready meals, cured meats, and preserved vegetables requiring sodium replacement for both sensory and microbial stability. Kanto institutional suppliers face binding MHLW procurement standards that accelerate ingredient switching.
- Sauces:Soy sauce, miso, and dressing categories where umami modulation complexity demands integrated potassium chloride-flavor enhancer systems. Technical partnerships between suppliers and Osaka manufacturers concentrate procurement conversion efforts.
- Snacks:Seasoning applications for crackers and rice products where surface-salt replacement allows partial sodium reduction without full reformulation. Mass-market processors prioritize cost containment over clean-label claims.
- Beverages:Sports drinks and functional beverages adopting mineral salt systems for electrolyte balance with reduced sodium. Emerging application territory where technical service intensity justifies supplier investment in application laboratories.
Processed foods absorb the highest ingredient tonnage. Beverages are climbing the fastest as clean-label electrolyte positioning spreads.
Distribution Channel:
Volume concentration determines logistics infrastructure—supermarkets and foodservice demand pallet-scale delivery with formulation support, while online and convenience channels fragment order patterns.
- Supermarkets:Primary channel for branded reduced-sodium products reaching health-conscious household consumers. Private-label penetration drives ingredient supplier engagement with retail technical teams.
- Foodservice:Institutional meal programs, restaurant chains, and catering operations where MHLW sodium mandates apply directly to procurement specifications. Direct supplier relationships predominate over distributor intermediation.
- Online Stores:Specialty reduced-sodium ingredients and premium sea salt variants reaching niche consumer segments. Limited volume but high margin profile attracts direct-to-consumer ingredient brands.
- Convenience Stores:Packaged ready meals and on-the-go sauces where space constraints favor established sodium-reduced product lines with proven turnover. Limited ingredient supplier visibility to end formulation.
Foodservice captures the steepest expansion trajectory. Supermarkets retain the deepest established volume.
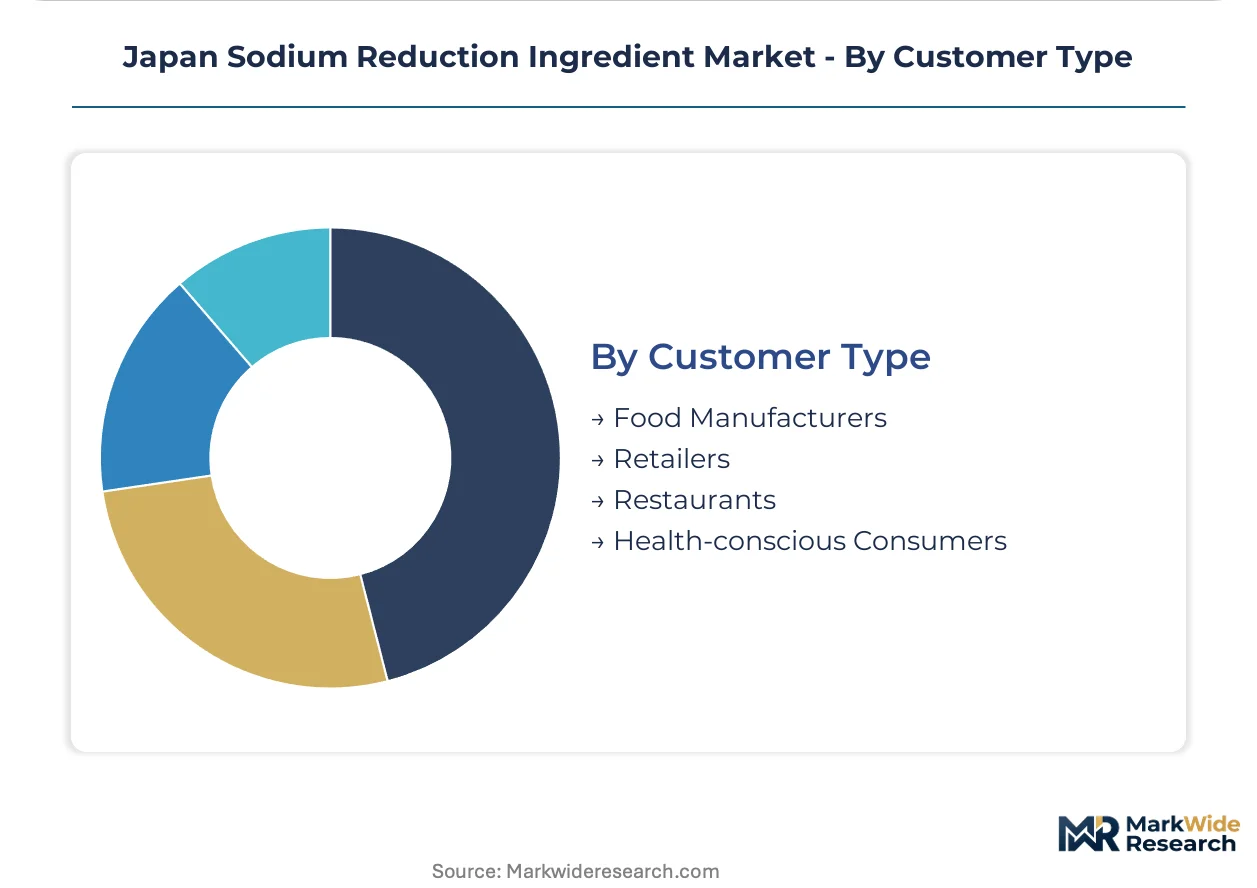
Customer Type:
Supply relationships stratify by technical sophistication—food manufacturers demand collaborative formulation, while retailers and restaurants prioritize finished product availability.
- Food Manufacturers:Integrated processors with in-house R&D capabilities driving specification development for sodium-reduced formulations. Direct technical partnerships with ingredient suppliers compress development cycles.
- Restaurants:Chain operators and institutional caterers implementing sodium reduction under MHLW guidance for school and hospital meal programs. Procurement concentrates through foodservice distributors with formulation advisory capacity.
- Retailers:Supermarket and convenience store operators influencing ingredient selection through private-label development programs. Technical engagement limited to finished product performance specifications.
- Health-conscious Consumers:End-user segment driving demand pull for reduced-sodium products, indirectly shaping manufacturer formulation priorities through purchase data and label claim responsiveness.
Food manufacturers command supplier attention. Health-conscious consumers exert indirect influence through purchase behavior signals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's food processing corridor commands premium pricing for technical sodium reduction ingredients, while Osaka-Kobe manufacturers negotiate harder on potassium chloride bulk contracts. This pricing-power asymmetry reflects divergent regulatory pressure intensity and formulation sophistication across Japan's two dominant industrial zones.
Kanto/Tokyo
Institutional meal suppliers and premium sauce manufacturers drive demand for integrated flavor-enhancer systems. MHLW's Health Japan 21 sodium ceilings bind school and hospital procurement specifications, forcing rapid ingredient switching. Tokyo's dense food processing cluster concentrates technical partnership activity between suppliers and reformulation teams.
Kansai/Osaka
Mass-market processed food and seasoning producers prioritize cost containment in sodium replacement programs. METI's Food Industry Vision innovation subsidies attract mid-tier manufacturers seeking documented sodium reduction achievements. Osaka's sauce production cluster lags Tokyo in clean-label adoption, creating procurement conversion opportunities for technical suppliers.
Chubu/Nagoya
Confectionery and beverage manufacturers experiment with mineral salt systems for electrolyte balance applications. PMDA's evolving stance on potassium-based additives shapes import clearance timelines for novel formulations. Nagoya's automotive supplier density indirectly supports food logistics infrastructure serving regional processors.
Kyushu
Seafood processing and preserved food manufacturers face sodium reduction mandates for export market access. Regional food-grade potassium chloride distribution networks remain underdeveloped compared to Kanto. Fukuoka's emerging food tech startup ecosystem attracts pilot-scale reformulation programs.
Hokkaido
Dairy and agricultural product processors seek sodium reduction for health-conscious domestic positioning. Geographic isolation elevates logistics costs for specialized ingredient procurement. Sapporo's institutional meal programs implement MHLW guidelines with limited local technical support infrastructure.
Japan Sodium Reduction Ingredient Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Amino acid-based flavor modulation specialists command premium positioning in Tokyo's institutional supply chain, while bulk potassium chloride distributors anchor cost-driven procurement in mass-market categories. The market stratifies across three archetypes: integrated taste-nutrition platforms, regional salt substitute distributors, and fermentation-derived enhancer specialists. Dominant competitive moves include direct technical partnerships with mid-tier processors and METI-linked innovation subsidy capture.
Among Japan-based amino acid specialists, Ajinomoto Co., Inc. exemplifies the integrated taste technology archetype. Cargill Inc and Kerry Group plc represent multinational ingredient platforms with regional distribution depth. These three companies occupy positions spanning the premium technical partnership tier and the bulk supply infrastructure layer, reflecting divergent strategic bets on formulation sophistication versus scale economics.
| Leading Market Players |
|---|
| Cargill Inc |
| Givaudan SA |
| Tate & Lyle Plc |
| BASF SE |
| Ajinomoto Co., Inc. |
| Kerry Group plc |
| Royal DSM NV |
| Archer Daniels Midland |
| Armor Proteines SAS |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Kanto food manufacturers and potassium chloride distributors lock in both supply access and price visibility, insulating reformulation programs from currency volatility while constraining flexibility to pivot toward flavor-enhancer systems. These contract structures reflect MHLW procurement mandates that penalize supply disruption in institutional meal channels.
Pricing Analysis
The customization-premium spread separates configured-to-order umami modulation systems from standard potassium chloride grades. Three-tier pricing structure across premium, standard, and economy levels tracks technical service intensity and formulation partnership depth. Price differentiation hinges on certification grade (food-grade JIS compliance vs. pharmaceutical-tier purity) and geographic delivery cost from Kanto distribution hubs. Pricing pressure stems from yeast extract raw material premiums compressing margins in mass-market sauce categories. Mass-market processed food manufacturers exhibit highest price sensitivity, while Tokyo institutional suppliers absorb technical premiums for documented sodium reduction compliance.
Supply Chain Analysis
Strategic stockpile preferences dominate potassium chloride procurement given hygroscopic handling requirements and MHLW reformulation deadlines, while flavor enhancers flow through just-in-time fermentation batch schedules. Geographic supply concentration draws from China, Canada, and Israel for food-grade potassium chloride feedstock. Raw material dependencies rest on potash mining output, yeast fermentation substrates, and nucleotide precursor chemicals. Single-source vulnerability runs through concentrated Canadian potash rail corridors to Kanto ports. Distribution runs through bulk industrial distributors serving Tokyo's food processing corridor, with technical ingredient suppliers maintaining direct sales teams for formulation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's sodium reduction ingredient market constitutes a high-growth disruption driven by MHLW's binding Health Japan 21 sodium ceilings that transform voluntary reformulation into procurement survival. The regulatory inflection compresses development timelines and elevates technical partnership premiums.
For Market Incumbents: Fortify supply security through backward integration into regional potassium chloride distribution networks or captive yeast extract fermentation capacity. Deepen technical service infrastructure in Osaka-Kobe to capture underpenetrated clean-label conversion. Defend against emerging mineral salt blend specialists by accelerating PMDA pre-submission dialogues to freeze formulation pipelines for competitors. For New Entrants and Emerging Players: Differentiate on beverage electrolyte applications where mineral salt systems lack established supplier relationships and technical specifications remain fluid. Target Nagoya's confectionery and functional beverage manufacturers for pilot-scale partnerships. Penetrate through collaborative formulation laboratories offering documented sodium reduction metrics for METI subsidy qualification rather than commodity ingredient transactions. For Investors and Strategic Acquirers: Amino acid-based taste modulation specialists with established PMDA ingredient master files and Tokyo institutional supply relationships represent priority acquisition targets. Long-term viability rests on regulatory compliance infrastructure rather than cost position alone. Watch PMDA's evolving novel food ingredient classification stance as the inflection signal that reshapes formulation freedom and import clearance economics.| Strategic Initiative | Industry Significance |
|---|---|
| Technical Partnership Laboratory | Direct formulation collaboration with Osaka-Kobe sauce manufacturers accelerates clean-label conversion timelines. |
| PMDA Pre-Submission Dialogue | Early regulatory engagement compresses novel mineral salt blend approval windows by 12-18 months. |
| Backward Integration into Potassium Chloride | Captive supply from Canadian or Israeli potash sources insulates against logistics volatility and currency fluctuation. |
| Yeast Extract Fermentation Scale-Up | Proprietary fermentation capacity reduces 40-60% raw material premiums versus merchant supply. |
| METI Innovation Subsidy Capture | Documented sodium reduction achievements unlock processed food R&D grants and procurement preferences. |
Research Methodology
Desk research of MHLW regulatory filings, METI subsidy program documentation, and PMDA ingredient approval databases preceded structured interviews with food manufacturer R&D directors, flavor chemists, potassium chloride procurement managers, and institutional meal program nutritionists. Primary fieldwork combined telephone and in-person interviews across Tokyo, Osaka, and Nagoya food processing clusters. Secondary validation drew from Japan Food Chemical Research Foundation reports, customs import statistics for potassium chloride, and Food Industry Vision implementation progress disclosures. Bottom-up ingredient demand modeling triangulated against top-down processed food production volume estimates.
Variance decomposition across ingredient type, application, and regional adoption patterns shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include ingredient chemistry, food manufacturing application, distribution channel tier, and customer technical sophistication. CAGRs derived from regression analysis against MHLW sodium reduction benchmark trajectories and METI innovation subsidy uptake rates. Industry-specific forecast inputs incorporated PMDA review timeline distributions and yeast extract fermentation capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained MHLW enforcement intensity or stable potassium chloride import channels would require recalibration. Forecasts reflect assumptions regarding Health Japan 21 procurement mandate continuity and PMDA regulatory science capacity. Revision becomes warranted when PMDA novel ingredient classification thresholds or Canadian potash logistics reliability crosses material disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Plastic Antioxidants Market
Additives
Dishwashing Additives Market
Additives
Wax Additives Market
Additives
Amino Acids Premixes Market
Additives
Automotive Additives Market
Additives
Anti Crystallizing Agents Market
Additives
Europe Fuel Additives Market
Additives
Viscosity Index Improvers Market
Additives
Green Polymer Additive Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Metal Deactivators Market
Additives
Lauroyl Methyl Glucamide Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Silicone Additives Market
Additives
Antimicrobial Ingredients Market