
 Syntactic Foam Market | 2026-2036
Syntactic Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Syntactic Foam Market Intelligence
Custom formulation services for application-specific syntactic foams is fragmenting the traditional value chain based on bulk material supply. Trelleborg AB leverages its scale in polymer engineering to offer integrated buoyancy solutions for offshore and subsea applications. Deepwater Buoyancy specializes in custom-molded products for specific oceanographic and offshore energy projects, while Balmoral Comtec Ltd dominates the European market for subsea buoyancy and insulation products.
Syntactic foam is a composite material comprising hollow microspheres, typically glass or ceramic, suspended within a polymer matrix like epoxy or vinyl ester. This composition yields a material with exceptionally low density and high compressive strength, making it ideal for deep-sea buoyancy applications. Epoxy-based systems command the largest share due to their superior strength and chemical resistance. Marine buoyancy remains the most significant application, while aerospace components are exhibiting rapid expansion.
Material qualification is governed by standards like ISO 13628 for petroleum and natural gas industries, ensuring performance in subsea production systems. Concurrently, chemical safety regulations such as the EU's REACH framework and directives from the US EPA influence the selection of matrix resins. Future competitiveness will hinge on developing materials that meet stricter environmental standards and performance requirements for extreme depth environments.
Market Dynamics
The expansion of offshore energy projects into ultra-deepwater environments is the central force shaping the syntactic foam market. This push necessitates materials that withstand extreme hydrostatic pressures, driving innovation in polymer matrix systems and microsphere qualification.
Growth Catalysts
- Deepwater Exploration:New offshore projects in the US Gulf of Mexico and Brazil require high-performance buoyancy for subsea infrastructure, creating sustained demand.
- Material Advancement:The creation of higher-strength glass microspheres enables foams with improved buoyancy-to-weight ratios, critical for increasing operational depths.
- Subsea Safety Standards:Adherence to ISO 13628 mandates qualified buoyancy materials for subsea systems, reinforcing demand for certified syntactic foam.
Market Restraints
- High Material Costs:The price of specialty epoxy resins and high-strength hollow glass microspheres makes syntactic foam a capital-intensive buoyancy solution compared to alternatives.
- Processing Complexity:Manufacturing requires precise control over mixing and curing to prevent defects, which limits the number of qualified, large-scale producers.
- Substitution Threat:In shallower water, conventional steel air cans and solid polymer buoys present a lower-cost alternative for buoyancy applications.
Strategic Opportunities
- Autonomous Underwater Systems:The use of AUVs and ROVs in oceanography and defense creates demand for custom-molded, lightweight buoyancy components.
- Bio-Based Resins:Developing foams with bio-based polymer matrices helps meet stricter environmental regulations like the EU's REACH framework and ESG mandates.
- Aerospace Components:The aerospace sector is a fast-growing opportunity for lightweight foam in structural parts where high strength-to-weight ratios are critical.
Industry Challenges
- Lengthy Material Qualification:New foam formulations undergo extensive and time-consuming testing to achieve certification against standards like ISO 13628, delaying market entry for innovative materials.
- Specialized Talent Scarcity:A shortage of polymer engineers and composite technicians with expertise in high-pressure material science and subsea applications constrains new product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syntactic Foam Market |
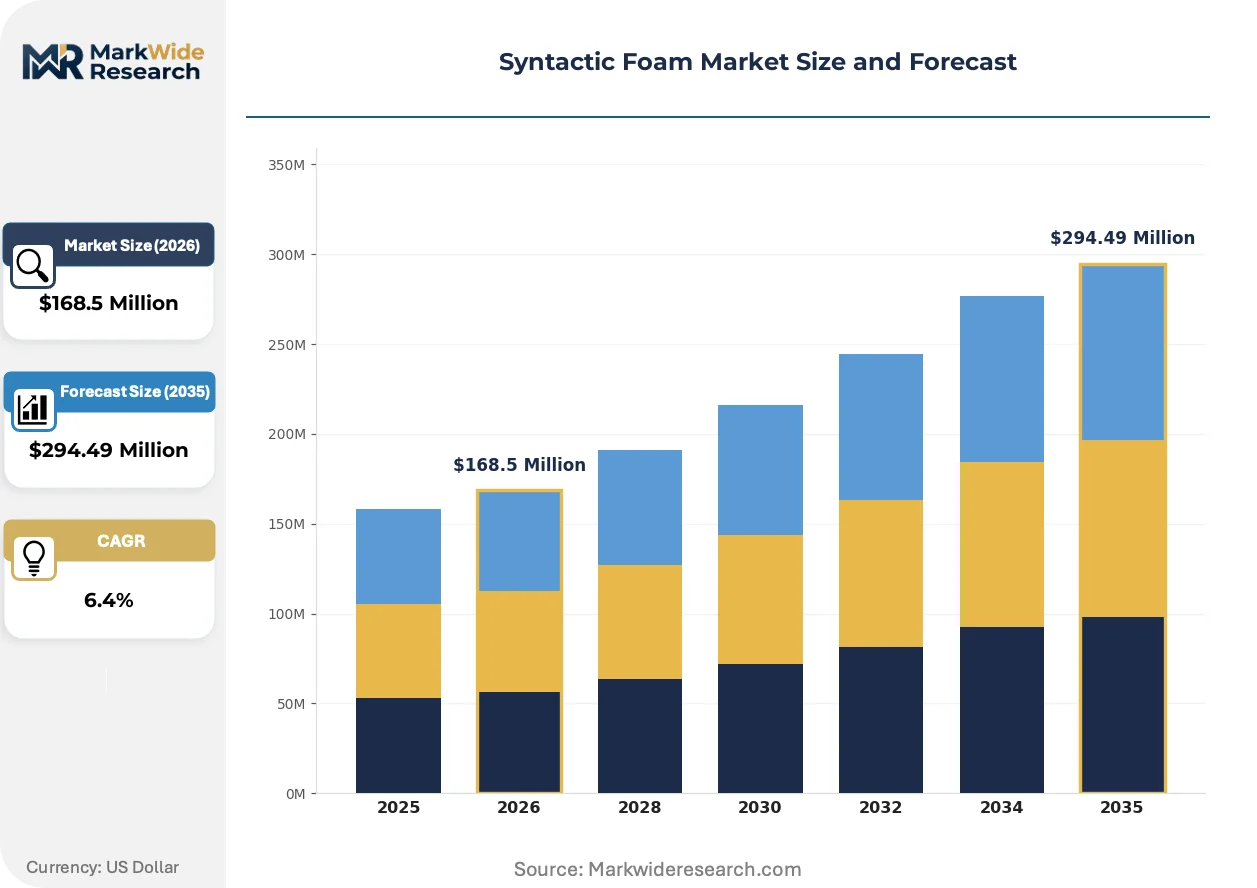
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $294.49 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy-Based, Vinyl Ester, Phenolic, Polyester, Polyurethane Application: Marine Buoyancy, Aerospace Components, Automotive Lightweighting, Oil & Gas Drilling, Sports Equipment End User Industry: Defense Contractors, Civil Aerospace, Vehicle Manufacturers, Energy Exploration, Sporting Goods Manufacturers Form: Block, Sheet, Molded, Coated, Laminated |
| Companies Covered | Trelleborg AB, SynFoam, Diab International AB, Acoustic Polymers Limited, Deepwater Buoyancy, CMT Materials, Engineered Syntactic Systems, Advanced Insulation, Balmoral Comtec Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syntactic Foam Market Strategic Shifts & Innovations
The market's evolution reflects a shift from supplying bulk materials to providing engineered, application-specific solutions. This transition is driven by the dual pressures of extreme operational environments and the need for greater system-level integration and performance predictability.
Digital twin modeling allows for the simulation of syntactic foam performance under specific subsea pressure and temperature conditions. Offshore engineering firms and EPC contractors are adopting this technology to de-risk material selection for deepwater projects. This advanced simulation capability is digitizing the material qualification process, reducing reliance on costly and time-consuming physical prototyping for custom formulations.
Chemical safety regulations, including the EU's REACH framework and directives from the US EPA, are scrutinizing the monomers and additives used in polymer matrices. This regulatory pressure is forcing a reformulation away from certain legacy chemicals toward greener alternatives. Epoxy-based systems are most affected, prompting research into bio-based resins and alternative curing agents to ensure future compliance.
A key behavioral shift involves customers demanding integrated buoyancy solutions rather than just purchasing bulk syntactic foam blocks. This disrupts the traditional model of material suppliers selling to fabricators, favoring vendors who can offer design, molding, and installation support. This trend is most visible in the offshore energy sector in Norway and the United States, where project complexity is highest.
Syntactic Foam Market Segmentation
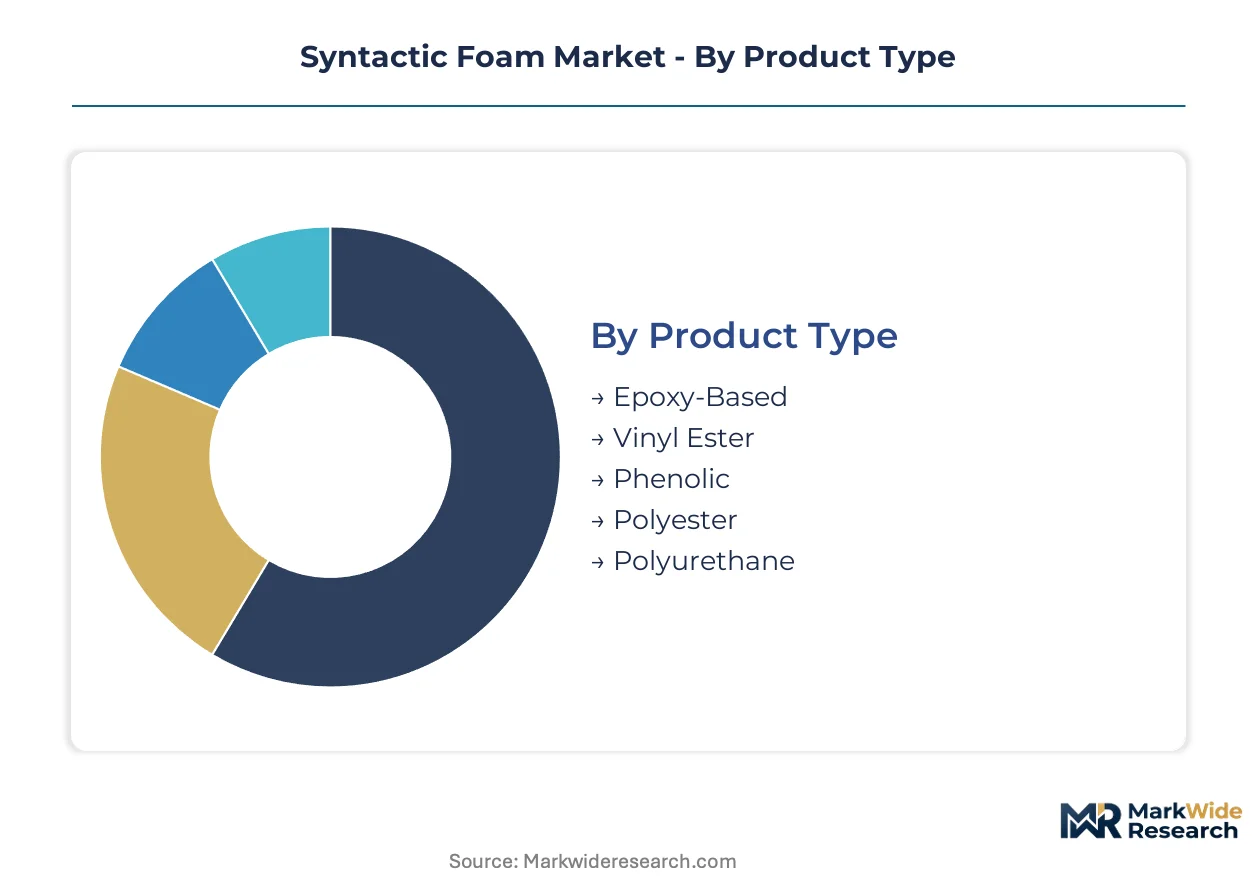
The segmentation of the syntactic foam market provides a granular view of material compositions, application areas, and end-user requirements. Understanding these distinct segments is crucial for identifying specific growth trajectories and technological preferences within the industry.
Product Type:
The lifecycle of syntactic foam product types varies significantly, with some formulations seeing rapid iteration while others maintain long-standing specifications.
- Epoxy-Based:This composite material integrates hollow microspheres within an epoxy resin matrix, providing superior strength and chemical resistance for demanding applications. Demand concentrates in deep-sea marine buoyancy systems, driven by its robust performance under extreme hydrostatic pressures.
- Vinyl Ester:These foams utilize vinyl ester resins as the matrix, offering good chemical resistance and mechanical properties, often at a lower cost than epoxy systems. Offshore energy projects, particularly in the US Gulf of Mexico, increasingly specify vinyl ester for its balance of performance and economic viability.
- Phenolic:Phenolic-based foams provide excellent fire resistance and thermal insulation, finding niche uses in specialized industrial applications.
- Polyester:Polyester resins offer a cost-effective matrix solution for syntactic foams, suitable for less extreme pressure environments.
- Polyurethane:Polyurethane foams are known for their flexibility and impact resistance, often used in applications requiring shock absorption.
Epoxy-Based formulations anchor the volume base while Vinyl Ester gains share at the steepest rate.
Application:
Syntactic foam applications span diverse industrial sectors, each demanding specific material properties and performance characteristics.
- Marine Buoyancy:Syntactic foams provide essential lift for subsea equipment by integrating hollow microspheres into a polymer matrix, crucial for deepwater operations. Demand is high in offshore energy hubs like Norway and the United States, driven by new exploration activities.
- Aerospace Components:These lightweight foams contribute to structural integrity and weight reduction in aircraft, utilizing high strength-to-weight ratios for critical parts. The sector exhibits rapid expansion, particularly for advanced unmanned aerial systems.
- Automotive Lightweighting:Syntactic foams reduce vehicle weight, improving fuel efficiency and electric vehicle range through composite integration.
- Oil & Gas Drilling:Foams are used in drilling operations for thermal insulation and buoyancy in demanding subsea environments.
- Sports Equipment:Lightweight and high-strength foams enhance performance in specialized sporting goods, including marine and outdoor gear.
Marine Buoyancy dominates the market while Aerospace Components is emerging as a critical growth area.
End User Industry:
End-user industries for syntactic foam are characterized by distinct procurement cycles and technical specification requirements.
- Energy Exploration:Firms engaged in offshore oil and gas projects require high-performance buoyancy solutions for subsea infrastructure and remotely operated vehicles. This industry drives demand for materials qualified to ISO 13628 standards for extreme hydrostatic pressures.
- Civil Aerospace:Aircraft manufacturers and their suppliers integrate syntactic foams into components to achieve weight reduction and enhance fuel efficiency. This segment prioritizes materials with stringent qualification requirements and long operational lifespans.
- Defense Contractors:These entities utilize syntactic foams for lightweighting and buoyancy in naval vessels, autonomous underwater vehicles, and aerospace platforms.
- Vehicle Manufacturers:Automotive companies incorporate lightweight foam composites to reduce vehicle mass and improve performance metrics.
- Sporting Goods Manufacturers:Makers of high-performance sports equipment employ syntactic foams for their strength-to-weight advantages in specialized products.
Demands for Energy Exploration and Civil Aerospace dictate product development.
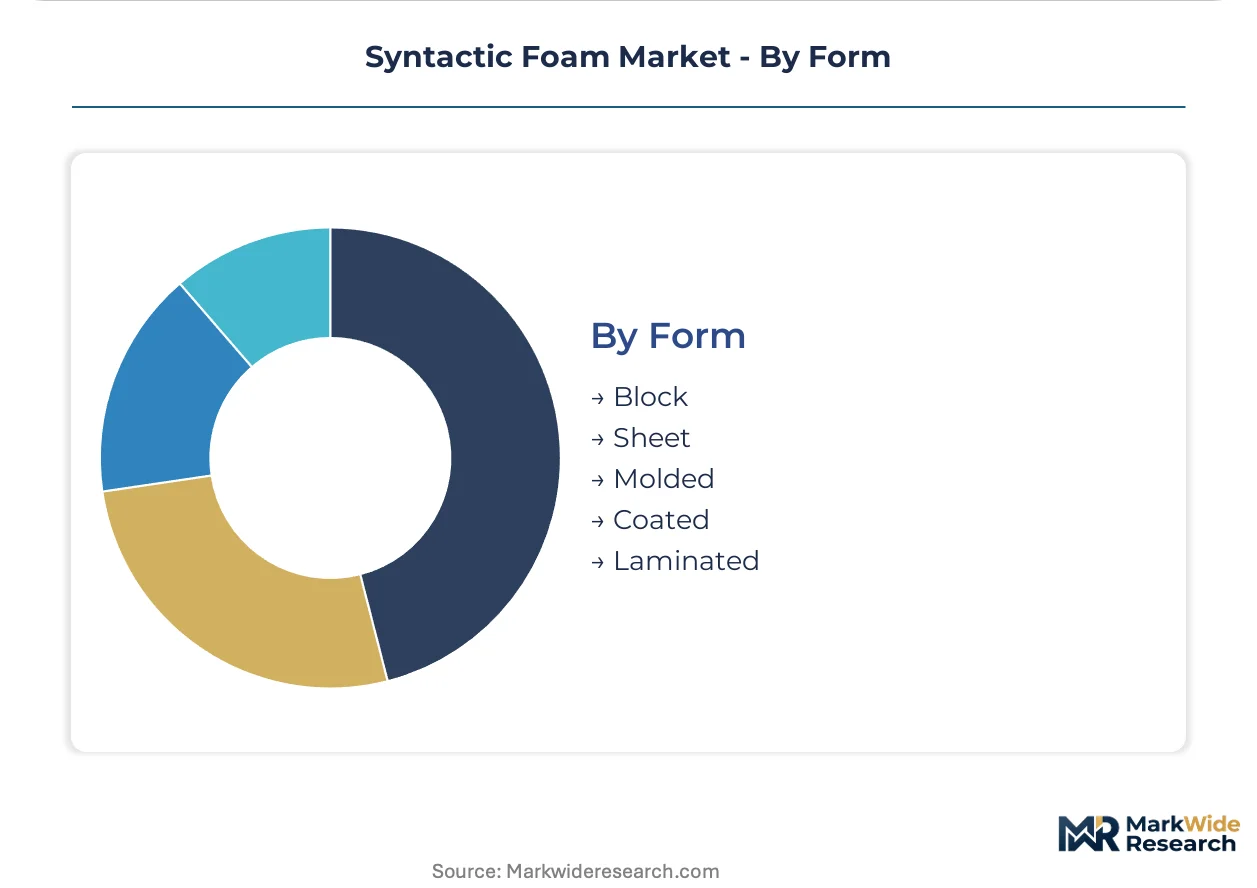
Form:
The form of syntactic foam dictates its manufacturing complexity and the specific processing techniques required for final product integration.
- Molded:Custom-molded syntactic foam products are engineered for specific application geometries, providing precise buoyancy and structural support for subsea components. Deepwater Buoyancy specializes in these customized solutions for oceanographic and offshore energy projects.
- Block:Syntactic foam is supplied in bulk block form, offering a versatile raw material for fabricators to machine into various shapes and sizes. This traditional supply method caters to a broad range of general buoyancy and structural requirements.
- Sheet:Syntactic foam sheets are used for flat panel applications requiring lightweight structural integrity or insulation properties.
- Coated:Coated syntactic foams protect the material from environmental degradation and enhance surface properties for demanding conditions.
- Laminated:Laminated foam structures combine syntactic foam with other materials to create multi-functional composites with improved performance.
The market is observing a shift from Block towards Molded solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Syntactic foam demand shows varied price sensitivity across regions. Buyers in established deepwater markets prioritize performance over cost. Conversely, emerging offshore areas or shallower water applications might consider cost-effective alternatives, influencing material selection and supply chain strategies.
United States
Demand for syntactic foam in the United States primarily stems from deepwater exploration in the Gulf of Mexico. New subsea infrastructure projects require high-performance buoyancy materials capable of extreme pressure. The US EPA regulations influence the selection of polymer matrix resins for environmental compliance in these applications. Houston, Texas, serves as a major hub for offshore oil and gas engineering, driving specialized material specification.
Norway
Norway's robust offshore energy sector drives significant demand for subsea buoyancy solutions. The country's focus on ultra-deepwater projects necessitates highly durable and pressure-resistant syntactic foams. Adherence to ISO 13628 standards is critical for material qualification in Norwegian subsea production systems. Stavanger is a key center for offshore technology development, influencing advanced foam applications.
Brazil
Brazil's pre-salt oil and gas fields generate substantial demand for advanced buoyancy in challenging deepwater environments. The country's expanding offshore exploration activities require materials capable of extreme hydrostatic pressures. Brazilian environmental regulations guide the use of chemical components in subsea materials for project approval. Rio de Janeiro is a central point for offshore energy operations, fostering specialized material procurement.
Germany
German industrial sectors, including aerospace and specialized marine applications, contribute to syntactic foam demand. The country's strong engineering base requires lightweight composites for structural integrity in high-performance systems. The EU's REACH framework significantly impacts the selection of polymer matrices and additives used in German manufacturing. Hamburg's maritime industry and aerospace clusters drive innovation in high-performance foam development.
Syntactic Foam Market Key Industry Players
Integrators and specialized material suppliers split the syntactic foam market. Large polymer engineering firms offer comprehensive buoyancy solutions, leveraging extensive scale and R&D capabilities for complex subsea projects. Niche manufacturers focus on custom-molded products for specific deep-sea and aerospace applications, emphasizing precision. Strategic partnerships between material providers and offshore engineering firms are common to ensure system-level integration. Companies also engage in portfolio diversification to address various end-user requirements across different industries.
Specialized providers of integrated buoyancy solutions, such as Trelleborg AB, leverage their polymer engineering scale to serve demanding offshore and subsea applications. Deepwater Buoyancy exemplifies a custom-molding specialist, focusing on specific oceanographic and energy projects with tailored designs. Balmoral Comtec Ltd, a European-based entity, anchors the regional market for subsea buoyancy and insulation products. These firms represent distinct approaches, ranging from broad-based material supply to highly tailored engineering services. Their offerings reflect the market's shift towards application-specific performance requirements and integrated solutions.
| Leading Market Players |
|---|
| Trelleborg AB |
| SynFoam |
| Diab International AB |
| Acoustic Polymers Limited |
| Deepwater Buoyancy |
| CMT Materials |
| Engineered Syntactic Systems |
| Advanced Insulation |
| Balmoral Comtec Ltd |
| Others |
Cost & Logistics Intelligence
Transatlantic shipping lanes' cost dynamics significantly influence syntactic foam pricing, particularly for specialized deepwater buoyancy solutions where supply is concentrated among a few key producers.
Pricing Analysis
Integrated buoyancy solution design services drive lifetime value by ensuring optimal material performance and subsea system longevity. Project-based pricing dominates specialized market segments, reflecting the high customization level and ISO 13628 certification requirements. Upward pricing pressure stems from the high cost of specialty epoxy resins and high-strength hollow glass microspheres. Energy exploration firms prioritize performance over cost, while automotive and sports equipment manufacturers exhibit higher price sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities often support the capital-intensive procurement of high-performance syntactic foam components. Production capability concentrates in Europe, particularly Germany, and the United States for advanced formulations. The supply chain relies heavily on specialized hollow glass microspheres and high-grade epoxy resins. Regulatory restrictions from the EU's REACH framework and the US EPA pose a structural risk to resin sourcing. Distribution runs primarily through direct contracts with offshore engineering firms and specialized fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
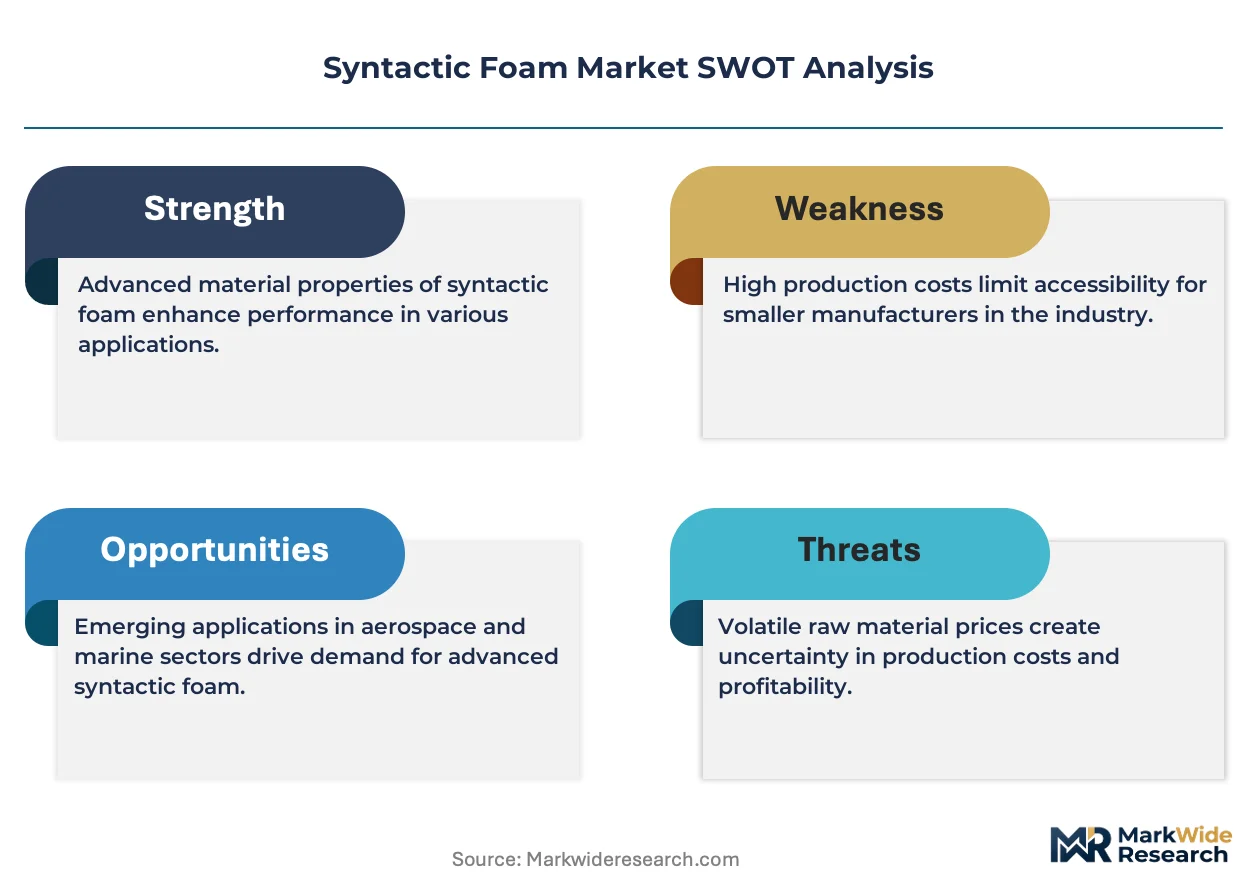
The syntactic foam market presents a fragmentation opportunity, driven by the demand for application-specific custom-molded products in autonomous underwater systems.
For Market Incumbents:Harden core competencies in ultra-deepwater material science and integrated solution delivery to counter substitution threats from lower-cost alternatives in shallower water. Invest further in polymer engineering and advanced microsphere qualification to meet future extreme pressure requirements. Pursue strategic acquisitions of specialized custom-molding firms to consolidate market share. Emphasize ISO 13628 certification as a key differentiation lever for subsea applications.
For New Entrants and Emerging Players:Build out specialized capabilities in custom-molded components for autonomous underwater systems, targeting oceanography and defense applications. The aerospace sector, particularly for advanced unmanned aerial systems, offers a penetrable segment for lightweight foams. Develop bio-based resin formulations to meet stricter environmental regulations like the EU's REACH framework. Position offerings on high strength-to-weight ratios and application-specific performance.
For Investors and Strategic Acquirers:Niche custom-molding specialists with proprietary formulations represent compelling acquisition targets for long-term viability in extreme environment applications. The market is positioned for sustained growth over the next decade, driven by ultra-deepwater energy and aerospace expansion. Focus on firms demonstrating expertise in high-strength glass microspheres and advanced polymer matrices. The signal to watch is the widespread adoption of digital twin modeling for rapid material qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses growing demand for deepwater buoyancy in offshore energy hubs. |
| Green Manufacturing Transition | Ensures compliance with stricter environmental regulations like REACH. |
| Joint Venture | Accelerates development of next-generation microspheres for extreme pressures. |
| Technology Licensing | Expands market reach for specialized aerospace and defense applications. |
| Product Portfolio Diversification | Mitigates reliance on single application areas like marine buoyancy. |
Research Approach
Operator-level perspectives from offshore engineering leads, polymer scientists, and subsea equipment manufacturers anchored the qualitative base of this study. Primary interviews were triangulated with secondary validation from ISO standards documents, US EPA regulatory filings, and industry association reports. This approach ensured a robust bottom-up and top-down understanding of market dynamics. Data collection focused on both material suppliers and end-user procurement patterns.
Scenario-bracketing informed the quantitative model, projecting market trajectories under various adoption and regulatory conditions across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, and geographic region. Compound annual growth rates were derived from historical data and projected demand drivers. Key forecast inputs included deepwater exploration project pipelines and aerospace manufacturing output.
Practitioners should monitor geopolitical shifts affecting offshore energy and material cost volatility for early signals of market recalibration. Forecasts reflect assumptions regarding technological advancements and regulatory stability. New environmental legislation or unforeseen material breakthroughs could also influence future projections. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Acoustic Materials Market
Insulation Materials
Thin Insulation Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Global High Temperature Insulation Materials Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
Passive Fire Protection Materials Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Protective Building Materials Market