
 OEM Insulation Market | 2026-2036
OEM Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
OEM Insulation Market Analysis
Aftermarket service revenue is tilting toward original equipment specification compliance as OEMs tighten thermal performance warranties. Owens Corning leverages its fiberglass platform to anchor automotive underhood contracts with Detroit-based OEMs. Saint-Gobain ISOVER competes through mineral wool specialization in European aerospace fire-protection tiers. Knauf Insulation extends its board-format dominance into HVAC equipment assembly lines across North American manufacturing hubs.
OEM insulation comprises engineered thermal, acoustic, and fire-resistant materials specified by original equipment manufacturers for integration into finished products during assembly, typically requiring density ratings below 50 kg/m³ for automotive applications and flame-spread indices under 25 for aerospace compliance. Its primary purpose is to meet end-product energy efficiency mandates and safety certifications while minimizing weight penalty. Mineral wool commands the largest share of industrial equipment applications due to its 1,000°C service temperature threshold and chemical stability against process vapors. Foam materials represent the fastest-expanding category as spray-applied polyurethane systems displace pre-cut batts in complex HVAC duct geometries where labor cost reduction outweighs raw material premiums. Batts remain the most mature format, with margin pools compressing toward commodity fiberglass supply contracts.
The EPA regulates VOC emissions from spray foam installation in US manufacturing facilities, while REACH restricts halogenated flame retardants in European OEM supply chains, forcing reformulation of polyurethane precursors across both jurisdictions. China's GB standards mandate thermal conductivity testing protocols that diverge from ISO methods, creating dual-certification burdens for multinational suppliers. Stakeholders must monitor divergence between regional fire-test standards as OEMs consolidate global platform sourcing and demand single-SKU material qualifications.
Market Dynamics
Automotive OEMs are consolidating thermal management specifications across global vehicle platforms, forcing insulation suppliers to harmonize material formulations for simultaneous US, EU, and China compliance rather than regional customization.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon blowing agents accelerates conversion to water-blown polyurethane systems in HVAC equipment manufacturing across Germany and France.
- Electric vehicle battery packs:Cell-to-pack architectures require compression-resistant aerogel interlayers that maintain thermal runaway containment at 800°C service temperatures.
- China's industrial equipment sector:GB standards for thermal conductivity testing create captive demand for certified mineral wool suppliers serving state-owned boiler manufacturers in Jiangsu and Shandong provinces.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate pricing swings compress margin pools for spray polyurethane contractors serving North American appliance OEMs.
- Supply concentration in boron-sourced mineral wool:Turkish and US boron ore dependencies create input cost vulnerability for European stone wool producers.
- REACH flame retardant restrictions:Halogenated additive bans force polyurethane reformulation cycles that extend qualification timelines by 18-24 months for aerospace tier suppliers.
Strategic Opportunities
- India's automotive corridor:Tamil Nadu and Maharashtra assembly plants lack qualified local aerogel converters, creating first-mover advantage for certified importers.
- CE marking harmonization:Consolidated EU fire-test standards enable single-SKU qualification across 27 member states, reducing SKU proliferation costs for HVAC duct insulation.
- Spray robotics integration:Automated polyurethane dispensing systems converge with machine vision to enable complex geometry coverage without masking labor.
Industry Challenges
- Dual certification burdens:China's GB thermal conductivity protocols diverge from ISO methods, requiring parallel test campaigns for multinational OEMs sourcing globally.
- Fire-test standard fragmentation:OEM platform consolidation demands single material qualifications while ASTM E84, EN 13501-2, and GB 8624 classification criteria remain non-harmonized.
- Technical workforce scarcity:Spray foam application certification programs lag equipment deployment rates in Mexican and Eastern European manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OEM Insulation Market |
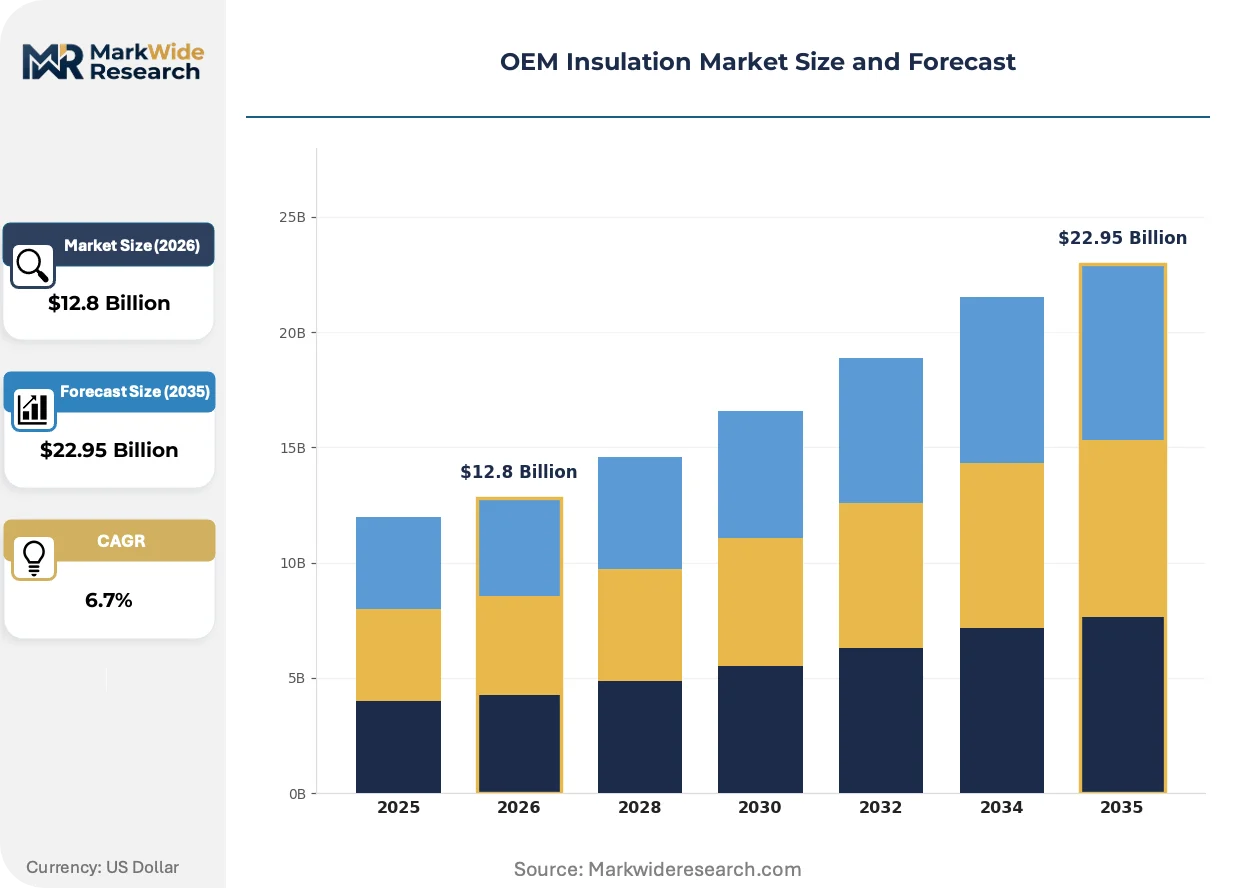
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Foam, Mineral Wool, Cellulose Product Form: Batts, Boards, Spray Foam, Blankets End User: Automotive OEMs, Aerospace Manufacturers, Industrial Equipment, HVAC Application: Thermal Insulation, Acoustic Insulation, Fire Protection, Energy Saving |
| Companies Covered | Owens Corning, Saint-Gobain ISOVER, Rockwool International A/S, Knauf Insulation, Johns Manville Corporation, Covestro AG, Armacell International S.A., Huntsman Corporation, Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OEM Insulation Market Emerging Trajectories
Digital specification tools and automated application systems are compressing the traditional engineer-to-order cycle for complex thermal barriers, while regulatory chemistry restrictions force material science reinvention across every major supply basin.
Aerogel blanket systems are virtualizing the legacy multi-layer insulation stack for electric vehicle battery enclosures. Cell manufacturers in South Korea and Germany specify 3-5 mm silica aerogel composites in place of 15-20 mm mica-polyimide assemblies. The technology is virtualizing thermal protection design constraints, enabling pack energy density gains without sacrificing fire containment ratings.
REACH restrictions on halogenated flame retardants are forcing polyurethane precursor reformulation across European OEM supply chains. ECHA substance evaluation timelines compress supplier response windows while maintaining end-product fire performance under EN 13501-2. German automotive HVAC suppliers bear the heaviest compliance burden, migrating to phosphorus-based intumescent systems ahead of 2025 sunset dates.
Buyer specification behavior is consolidating around platform-level thermal performance warranties rather than discrete material certifications. Tier-one automotive suppliers in Detroit and Stuttgart now contract for system-level energy efficiency outcomes, transferring formulation liability downstream to insulation converters. This shift is most pronounced in North American electric vehicle programs, where battery thermal management warranties extend to 8 years or 160,000 miles.
OEM Insulation Market Segmentation
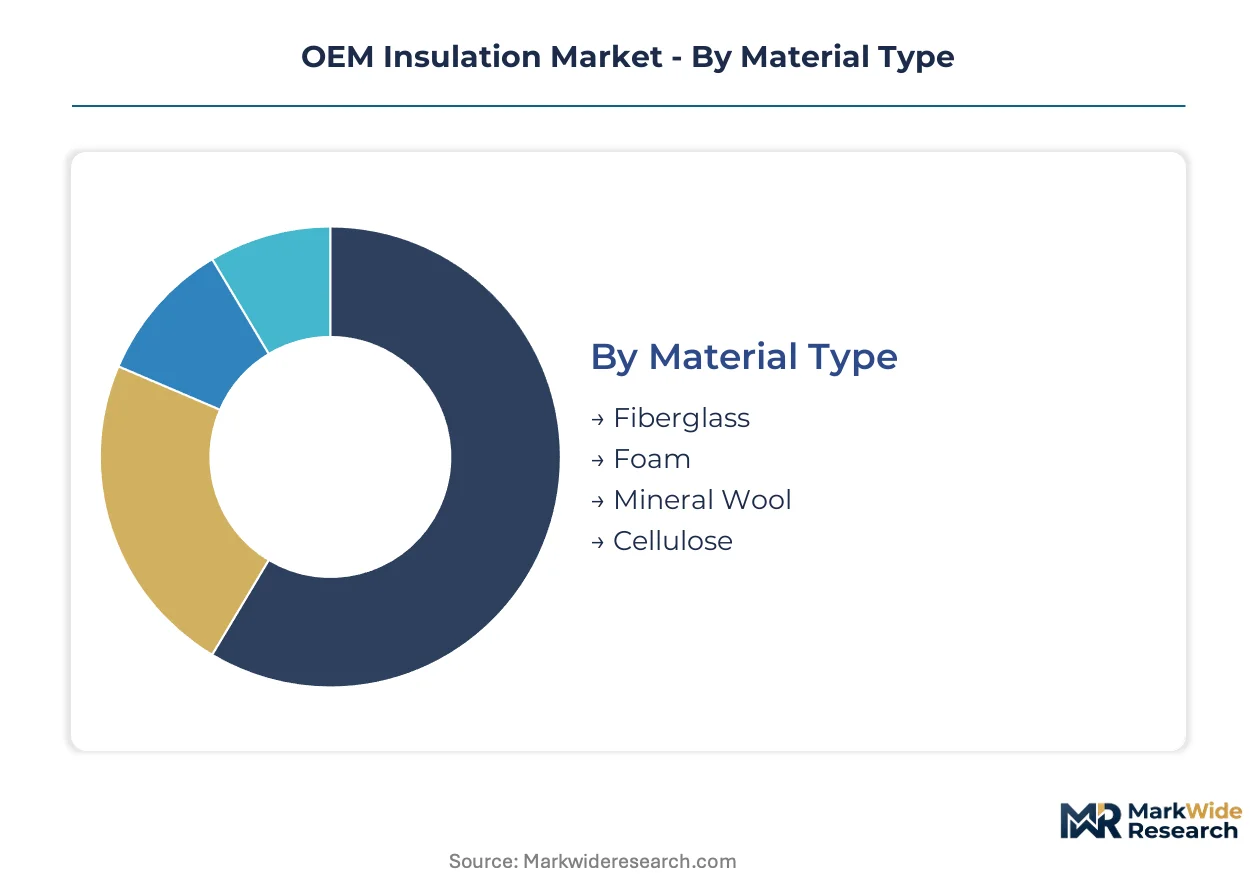
OEM insulation procurement patterns diverge sharply across material chemistry, physical form, and end-use certification requirements. Specification behavior varies by thermal performance threshold, flame-spread rating, and assembly-line integration constraints.
Material Type:
The use-case spectrum spans sub-50 kg/m³ automotive underhood barriers to 1,000°C industrial process linings, with density and service temperature driving specification splits.
- Foam:Spray-applied polyurethane systems displace pre-cut batts in complex HVAC duct geometries where labor cost reduction outweighs raw material premiums. Water-blown formulations are accelerating conversion in German and French equipment manufacturing as EU F-Gas Regulation phases down hydrofluorocarbon blowing agents.
- Mineral Wool:Stone and slag wool variants command industrial equipment applications due to chemical stability against process vapors and 1,000°C service temperature thresholds. State-owned boiler manufacturers in China's Jiangsu and Shandong provinces anchor demand through GB-standard thermal conductivity certification requirements.
- Fiberglass:Lightweight thermal barriers below 50 kg/m³ density serve automotive underhood specifications with established supply contracts.
- Cellulose:Fiberized paper-based insulation meets niche acoustic damping requirements in commercial vehicle cabins.
The dominant share belongs to mineral wool, while foam is closing the gap fastest.
Product Form:
Cost tier differentiation separates commodity batts from precision-engineered blankets and automated spray systems.
- Batts:Pre-cut fiberglass and mineral wool segments remain the most mature format, with margin pools compressing toward commodity supply contracts for high-volume appliance OEMs.
- Blankets:Silica aerogel composites in 3-5 mm thicknesses virtualize legacy 15-20 mm mica-polyimide assemblies for electric vehicle battery enclosures. South Korean and German cell manufacturers specify these for cell-to-pack architectures requiring compression-resistant thermal runaway containment.
- Boards:Rigid mineral wool and fiberglass formats dominate HVAC equipment assembly lines across North American manufacturing hubs.
- Spray Foam:Automated polyurethane dispensing systems with machine vision enable complex geometry coverage without masking labor.
Batts retain volume leadership, though blankets are expanding most quickly in premium thermal management applications.
End User:
Customer type determines certification burden, with aerospace fire-protection tiers imposing the longest qualification cycles.
- Automotive OEMs:Platform consolidation across US, EU, and China compliance zones forces harmonized material formulations rather than regional customization. Detroit and Stuttgart tier-one suppliers now contract for system-level energy efficiency outcomes with 8-year battery thermal management warranties.
- Aerospace Manufacturers:EN 13501-2 and ASTM E84 fire-test classifications impose 18-24 month qualification timelines for REACH-compliant halogen-free polyurethane systems. REACH flame retardant restrictions force reformulation cycles that extend supplier response windows.
- Industrial Equipment:Process vapor exposure and high-temperature service conditions favor mineral wool specifications.
- HVAC:Duct geometry complexity drives spray foam adoption for labor reduction.
Automotive OEMs command the largest specification volume, while aerospace manufacturers impose the steepest margin premiums.
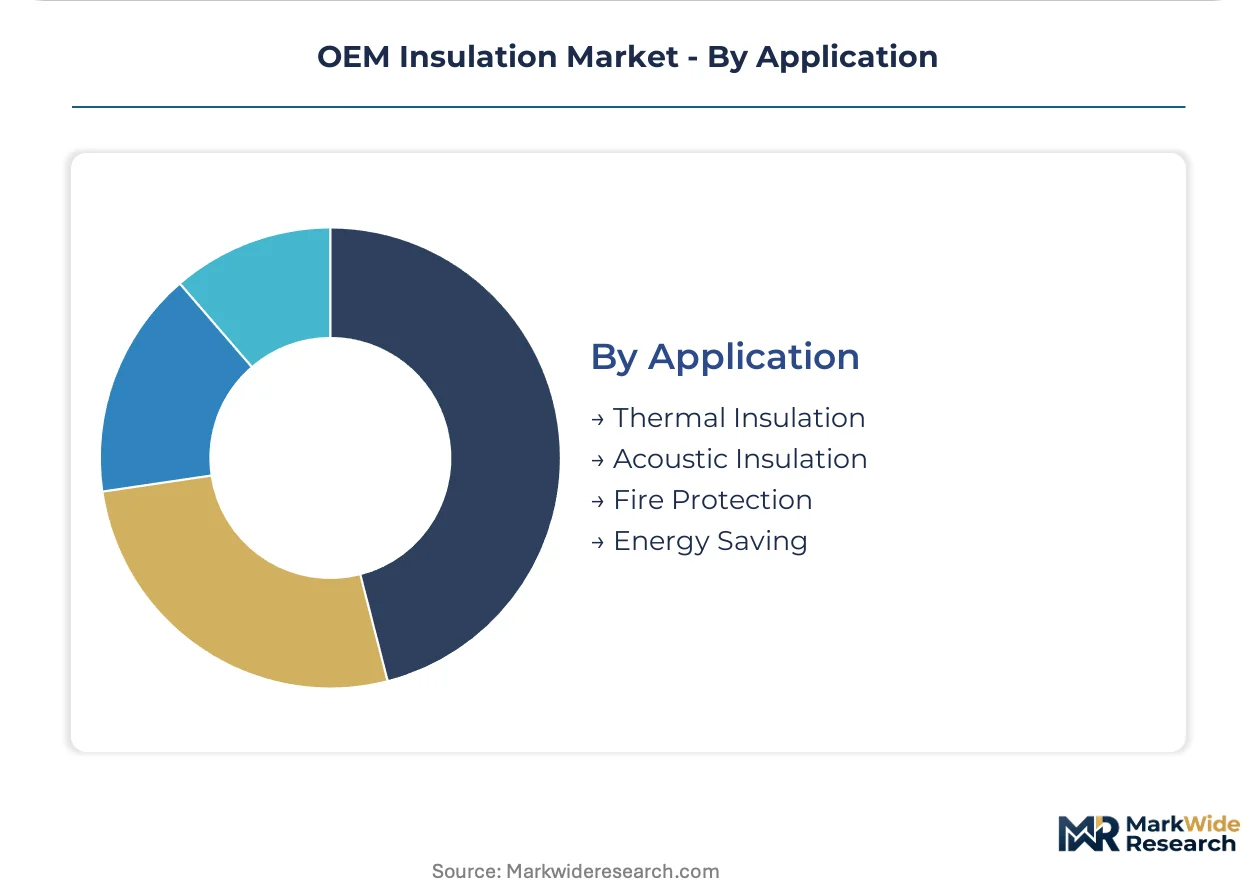
Application:
Functional performance requirements create segmentation by thermal conductivity, acoustic transmission loss, and flame-spread index.
- Thermal Insulation:Energy efficiency mandates in building codes and appliance standards drive specification across all material categories. China's GB standards mandate testing protocols that diverge from ISO methods, creating dual-certification burdens.
- Fire Protection:Flame-spread indices under 25 for aerospace compliance and EN 13501-2 classifications for European construction products reshape chemistry formulations. Phosphorus-based intumescent systems are migrating ahead of halogenated additive sunset dates.
- Acoustic Insulation:Transmission loss specifications in commercial vehicle and rail applications favor denser mineral wool and fiberglass composites.
- Energy Saving:System-level efficiency warranties consolidate procurement around outcome-based contracting rather than discrete material certifications.
Thermal insulation holds the broadest addressable base, while fire protection commands the highest specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's state-owned industrial sector show lowest price elasticity due to GB-standard certification lock-in, while North American appliance OEMs negotiate aggressively on spray foam contracts. European automotive suppliers occupy the middle ground, balancing REACH compliance costs against platform consolidation savings.
United States
Detroit-based automotive tier-one suppliers anchor thermal management specification volumes, particularly for electric vehicle battery enclosure programs. EPA VOC emission rules from spray foam installation reshape polyurethane procurement in Midwest manufacturing corridors. The Southeast appliance assembly belt, spanning Kentucky and Tennessee, drives water-blown foam conversion as contractors seek labor cost reduction.
Germany
Automotive HVAC suppliers in Stuttgart and Munich bear the heaviest REACH flame retardant compliance burden, migrating to phosphorus-based intumescent systems ahead of 2025 sunset dates. The EU F-Gas Regulation accelerates water-blown polyurethane adoption across equipment manufacturing in Bavaria and Baden-Württemberg. Dresden-area industrial boiler fabricators specify mineral wool through EN 13501-2 certification pathways.
China
State-owned boiler manufacturers in Jiangsu and Shandong provinces generate captive demand for GB-standard certified mineral wool suppliers. MIIT industrial efficiency mandates tighten thermal conductivity requirements for process equipment. The Yangtze River Delta automotive cluster, centered on Shanghai and Suzhou, specifies lightweight underhood barriers for export-platform vehicles.
South Korea
Cell manufacturers in Gyeonggi Province specify 3-5 mm silica aerogel composites for cell-to-pack battery architectures requiring 800°C thermal runaway containment. Korean battery OEMs drive premium thermal barrier specification with extended warranty terms. The Busan-Ulsan industrial corridor maintains mineral wool demand for petrochemical process insulation.
India
Tamil Nadu and Maharashtra automotive assembly plants lack qualified local aerogel converters, creating import dependence for compression-resistant battery interlayers. BIS thermal testing protocol adoption lags equipment deployment rates. The Pune-Nashik industrial belt shows emerging spray foam demand as HVAC equipment localization accelerates.
OEM Insulation Market Vendor Landscape
Capability concentration sits with specialized aerogel and intumescent formulators; scale advantage sits with integrated fiberglass and mineral wool producers. The market structures around three tiers: global materials conglomerates with captive mineral reserves, regional converters serving single-industry certification requirements, and emerging technology specialists betting on electric vehicle thermal management. Two competitive moves dominate: backward integration into boron ore and basalt feedstocks, and technology licensing partnerships to compress qualification timelines for REACH-compliant formulations.
Among North American building materials conglomerates, Owens Corning and Johns Manville occupy positions exemplifying scale-driven fiberglass supply. Saint-Gobain ISOVER represents the European mineral wool specialization archetype, while Rockwool International A/S anchors the stone wool segment with Nordic industrial heritage. These three serve as reference points for competitive positioning across automotive underhood, aerospace fire-protection, and industrial process insulation tiers.
| Leading Market Players |
|---|
| Owens Corning |
| Saint-Gobain ISOVER |
| Rockwool International A/S |
| Knauf Insulation |
| Johns Manville Corporation |
| Covestro AG |
| Armacell International S.A. |
| Huntsman Corporation |
| Kingspan Group |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Ruhr freight corridor carries boron-sourced mineral wool feedstock from Turkish ore deposits into German stone wool manufacturing hubs, with its cost volatility transmitting directly into supply concentration among integrated producers and downstream price stratification across automotive underhood and aerospace fire-protection tiers.
Pricing Analysis
Aftermarket service revenue from extended thermal performance warranties drives lifetime value for OEM insulation suppliers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant aerogel systems from commodity fiberglass batts and project-grade mineral wool boards. Pricing pressure stems from petrochemical feedstock volatility in polyol and isocyanate markets, compressing margins for spray polyurethane contractors. North American appliance OEMs exhibit highest price sensitivity through aggressive contract negotiation, while China's state-owned boiler manufacturers show lowest elasticity due to GB-standard certification lock-in.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain finance facilities has become critical for mineral wool converters managing boron ore inventory cycles. Raw material sourcing draws from Turkish boron deposits, US basalt reserves, and Chinese slag processing capacity. Supply chain risk centers on single-source vulnerability for aerospace-grade aerogel precursors. Distribution runs through tier-one automotive supplier networks in Detroit and Stuttgart, with direct-to-OEM contracts for electric vehicle battery thermal management programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against emerging thin-film ceramic coatings that threaten to displace traditional multi-layer insulation stacks in next-generation battery architectures.
For Market Incumbents: Insulate core revenue streams through backward integration into boron ore and basalt feedstocks, securing captive supply against Turkish export restrictions. Accelerate REACH-compliant phosphorus-based intumescent certification to preempt regulatory sunset dates. Deepen platform-level thermal performance warranty offerings to lock in Detroit and Stuttgart tier-one automotive contracts. For New Entrants and Emerging Players: Pursue white-space opportunities in India's Tamil Nadu and Maharashtra automotive corridors, where qualified local aerogel converters remain absent. Target spray foam application certification programs in Mexican manufacturing hubs to capture HVAC equipment localization demand. Lead with automated polyurethane dispensing system partnerships to differentiate from labor-dependent incumbents. For Investors and Strategic Acquirers: Specialized aerogel formulators with electric vehicle battery enclosure qualifications represent the most compelling acquisition targets, given their scarcity value and premium margin capture. Monitor divergence between China's GB thermal conductivity protocols and ISO methods as the key inflection signal—accelerating harmonization would compress dual-certification cost burdens and unlock multinational OEM consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Ore | Captive supply from Turkish deposits insulates stone wool producers against export restriction risks. |
| REACH-Compliant Formulation Licensing | Phosphorus-based intumescent technology partnerships compress 18-24 month aerospace qualification timelines. |
| Spray Robotics Integration | Machine vision-enabled polyurethane dispensing eliminates masking labor in complex HVAC duct geometries. |
| Platform-Level Warranty Contracts | System-level energy efficiency outcomes transfer formulation liability downstream to insulation converters. |
| Aerogel Capacity Expansion | 3-5 mm silica aerogel output scales to serve South Korean and German cell-to-pack battery architectures. |
Methodological Framework
A standing panel of OEM procurement managers, thermal systems engineers, insulation converter operations heads, and aftermarket service directors provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with tier-one automotive suppliers in Detroit and Stuttgart, mineral wool plant managers in Germany's industrial corridor, and aerogel specification leads at South Korean battery manufacturers. Secondary validation drew from EPA VOC emission filings, ECHA REACH substance evaluations, Chinese GB standard thermal conductivity protocols, and SEC disclosures from North American building materials conglomerates. Bottom-up volume builds across material type, product form, and end-use segments triangulated against top-down macroeconomic drivers.
Scenario-bracketing framed demand projections across conservative, baseline, and expansion cases throughout the forecast period. Segmentation modeling captured material chemistry splits, physical form differentiation, and application-specific certification requirements. CAGRs derived from weighted average growth rates across automotive platform consolidation, electric vehicle battery thermal management adoption curves, and industrial equipment efficiency mandate compliance trajectories. Input assumptions incorporated EU F-Gas Regulation phase-down schedules, REACH flame retardant sunset dates, and China's MIIT industrial efficiency tightening timelines.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, petrochemical feedstock pricing, or cross-border regulatory harmonization velocity would shift the trajectory. Forecasts reflect documented assumptions regarding platform standardization rates and certification timeline compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Multi-Layer Cryogenic Insulation Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Radiation Shielding Materials Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
High Temperature Insulation Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Silver Ion Antibacterial Insulation Cup Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
Global Insulation Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
Global Industrial Foam Market