
 Food Display Counter Market | 2026-2036
Food Display Counter Market Size, Share, and Industry Trends Forecast 2026-2036
Food Display Counter Market Foresight
Quick service restaurants is consolidating as the dominant end-user vertical, displacing traditional cafeteria procurement in North American and European foodservice chains. Hoshizaki leverages its refrigeration technology leadership to anchor premium positions in Asian markets. True Manufacturing sustains manufacturing scale advantages through its Missouri-based production complex. Turbo Air competes aggressively on cost-engineered units for independent restaurant operators.
Food display counters are insulated, temperature-controlled enclosures engineered from stainless steel, tempered glass, and polyurethane foam insulation, designed to maintain precise thermal zones between minus two and plus sixty degrees Celsius for safe merchandise presentation. Refrigerated counters dominate installed base value while grab and go counters represent the fastest-growing product category as convenience retail formats multiply. Foodservice applications capture the largest application share, though bakery segment margins benefit from shorter replacement cycles and higher customization requirements.
The US Department of Energy and the EPA enforce minimum efficiency standards and refrigerant phase-down schedules that reshape product development priorities for manufacturers selling into North America. Epta Group navigates European regulatory complexity through CE-marked, F-Gas-compliant systems designed for EMA-monitored food safety environments. Stakeholders must monitor refrigerant transition timelines and energy labeling evolutions to avoid stranded inventory positions.
Market Dynamics
Quick service restaurants are consolidating their cold-chain display footprints as consumer preference for visible freshness forces equipment refresh cycles. Hydrocarbon-based cooling systems are gaining traction as the US Department of Energy tightens commercial refrigeration efficiency standards.
Growth Catalysts
- Urban foodservice modernization:Southeast Asian cities including Ho Chi Minh City, Bangkok, and Jakarta are upgrading food retail infrastructure. Street food vendors and small-format grocers drive demand for compact refrigerated displays.
- F-Gas Regulation compliance:European manufacturers accelerate refrigerant transitions to meet phasedown schedules. This creates replacement demand for legacy units across EMA-monitored food safety environments.
- Grab-and-go format proliferation:Convenience retail chains expand self-service chilled merchandise zones. Independent operators and petrol station forecourts adopt standardized display configurations.
Market Restraints
- Stainless steel price volatility:Input cost swings for 304-grade stainless and tempered glass compress manufacturer margins. Fabricators face working capital pressure from commodity-linked raw material exposure.
- Compressor supply concentration:Critical refrigeration components originate from a limited supplier base in East Asia. Geopolitical friction risks disrupt just-in-time assembly schedules.
- Refrigerant transition friction:EPA phase-down timelines for HFC-based systems strand inventory positions. Distributors hesitate to stock transitional models amid regulatory uncertainty.
Strategic Opportunities
- Vietnam infrastructure buildout:Foreign direct investment flows into Vietnamese food processing and retail cold chain. Local assembly partnerships reduce landed cost for imported components.
- Dual-temperature hybrid units:Convergence of heated holding and refrigerated display in single enclosures addresses space-constrained urban formats. Bakeries and prepared food operators pilot flexible zone configurations.
- Direct-to-operator digital channels:Equipment manufacturers bypass traditional distribution layers through e-commerce platforms. Independent restaurant operators compare specifications and pricing through specialized procurement portals.
Industry Challenges
- Hydrocarbon system certification:Technicians require specialized training for flammable refrigerant handling. Workforce development lags behind equipment rollout schedules.
- Legacy control integration:IoT-enabled temperature monitoring must interface with existing building management systems. Retrofit complexity slows adoption in established foodservice chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Display Counter Market |
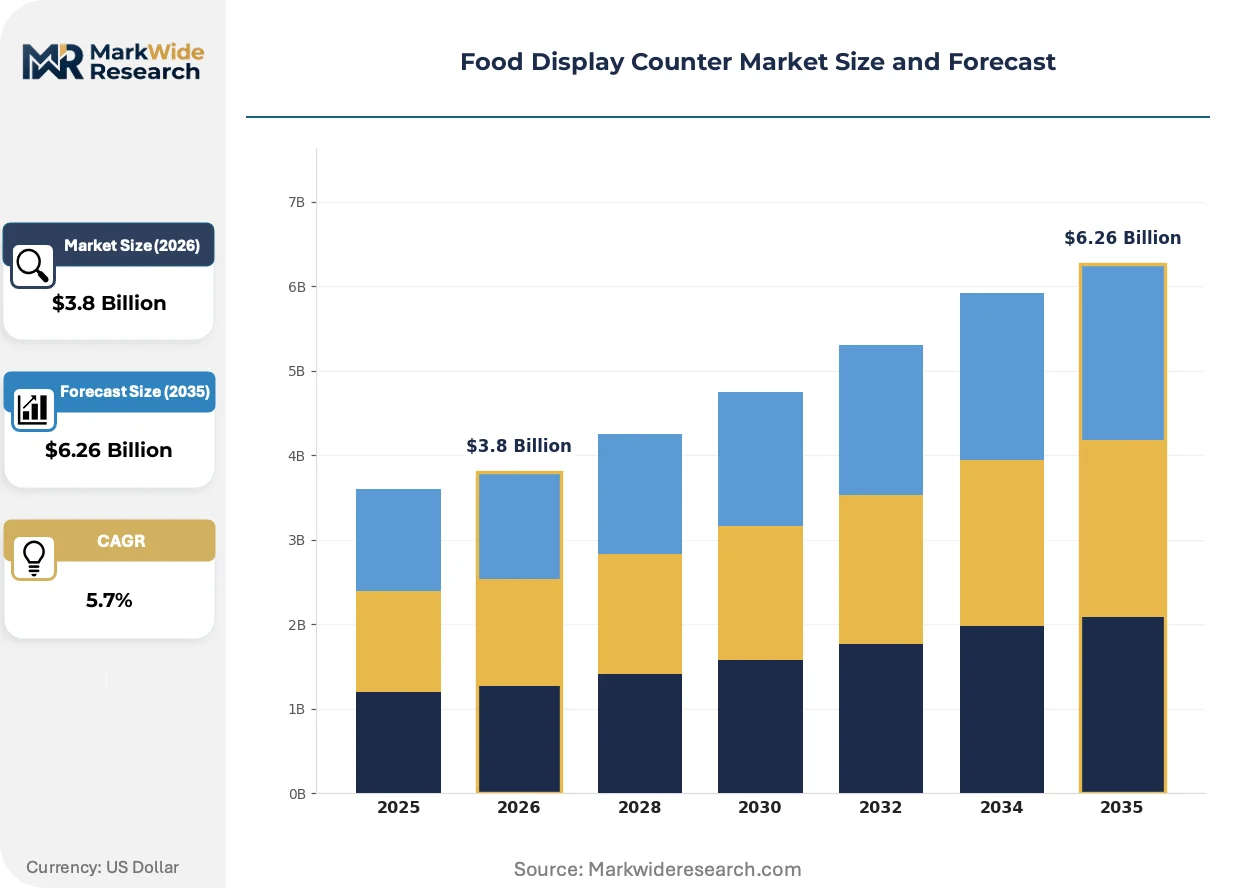
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated Counters, Heated Counters, Ambient Counters, Grab & Go Counters Application: Bakery, Delicatessen, Cafeteria, Confectionery, Foodservice End User: Quick Service Restaurants, Hotels, Catering Services, Institutional Canteens Sales Channel: Direct Sales, Distributors, Online Retailers, Wholesale Suppliers |
| Companies Covered | Hoshizaki, True Manufacturing, Turbo Air, Alto-Shaam, Hatco, The Vollrath Company, Carrier Global Corporation, The Middleby Corporation, Epta Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Display Counter Market Shifts & Advancements
Equipment design is pivoting toward adaptive thermal zones and connected monitoring as operators demand operational visibility. Manufacturers embed sensors and modular architecture to compress service intervals and reduce energy intensity.
Plug-and-play refrigeration modules are modularizing field service and upgrade pathways. Quick service chains adopt swappable compressor units to minimize downtime during maintenance windows. This architecture compresses total cost of ownership calculations and accelerates replacement decisions among multi-unit operators.
The US Department of Energy's commercial refrigeration efficiency standards are forcing hydrocarbon and CO2 system investments. Manufacturers redesign heat exchangers and insulation packages to meet minimum performance thresholds. North American production lines retool fastest, while export-oriented Asian suppliers face certification timeline compression.
Visible freshness merchandising is reshaping equipment specification priorities. Bakery and prepared food operators prioritize curved glass and LED illumination over pure thermal performance. European and Southeast Asian markets show strongest preference for display-optimized configurations over utilitarian back-of-house units.
Food Display Counter Market Segmentation
Equipment specification diverges sharply across thermal zones and operational formats. Procurement patterns cluster around temperature requirements, traffic density, and regulatory exposure rather than simple capacity metrics.
Product Type:
Capital intensity peaks in refrigerated configurations due to compressor systems, hydrocarbon-compatible heat exchangers, and multi-layer insulation packages. Heated and ambient alternatives require lower upfront outlays but face steeper lifecycle energy costs in certain deployment contexts.
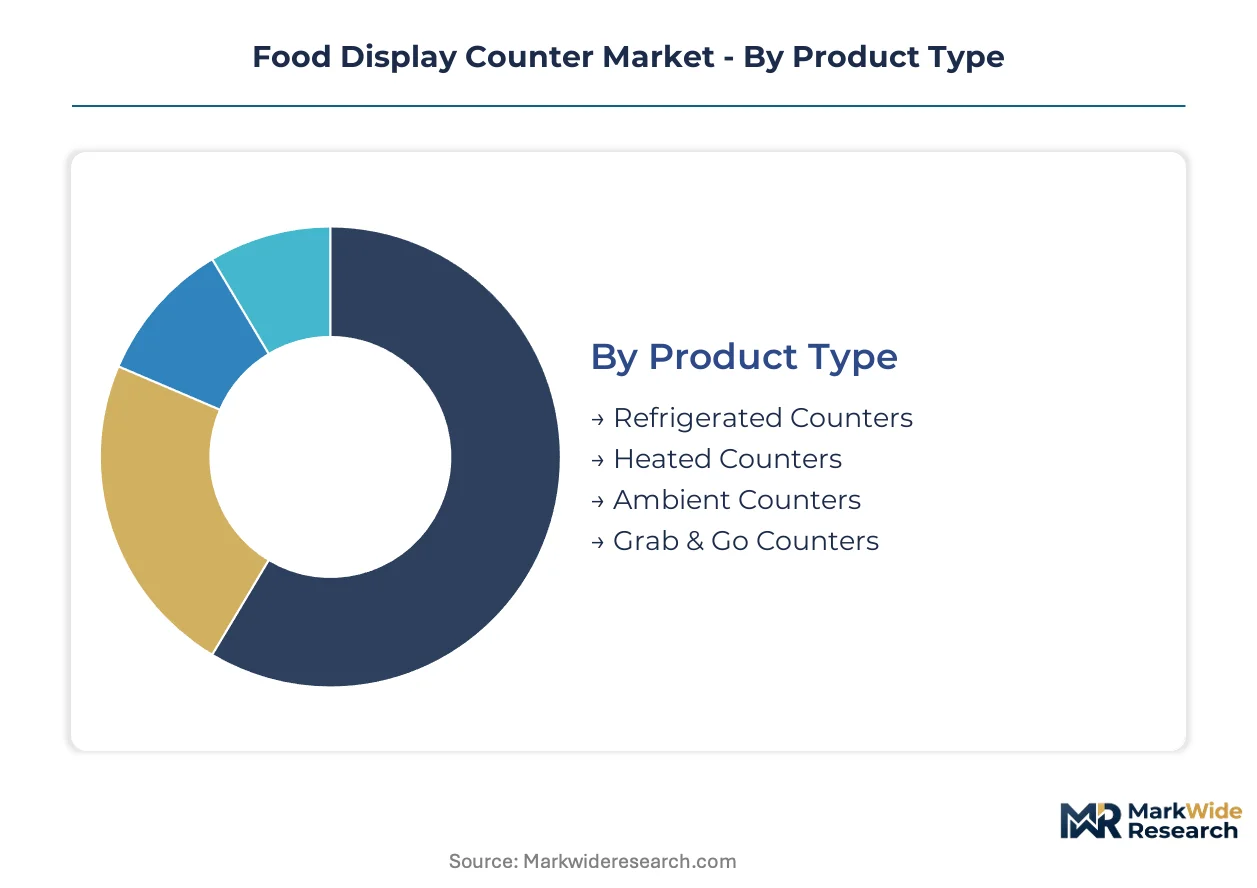
- Refrigerated Counters:Stainless steel enclosures with polyurethane foam insulation maintain thermal zones between minus two and plus eight degrees Celsius. Quick service restaurants in Vietnam and Thailand drive replacement demand as hydrocarbon refrigerant transitions accelerate under efficiency mandates. The US Department of Energy standards compress payback calculations for legacy HFC-based units.
- Grab & Go Counters:Self-service configurations with curved glass and LED illumination prioritize visible freshness merchandising over pure thermal performance. Convenience retail chains across Indonesia expand standardized chilled merchandise zones in petrol station forecourts and urban micro-formats. These units gain share fastest among independent operators seeking format flexibility.
- Heated Counters:Temperature-controlled holding between fifty and sixty degrees Celsius serves prepared food and hot buffet applications. Institutional canteens in Jakarta specify these for batch-cooked meal service.
- Ambient Counters:Non-refrigerated display for shelf-stable merchandise reduces electrical infrastructure requirements. Street food vendors in Ho Chi Minh City adopt compact ambient units for packaged goods presentation.
Most installed capacity flows through refrigerated counters. Expansion is steepest in grab and go configurations.
Application:
Margin profiles separate replacement-intensive segments from long-cycle installations. Bakery and confectionery applications command premium pricing through customization requirements, while cafeteria procurement standardizes around cost-engineered specifications.
- Foodservice:Full-service restaurants and institutional kitchens demand versatile thermal zoning with rapid temperature recovery during service peaks. Hotels in Bangkok and catering operators across Southeast Asia specify modular units for banquet and buffet flexibility. EPA refrigerant phase-down timelines accelerate equipment refresh decisions in this volume-heavy segment.
- Bakery:Curved glass configurations with humidity control preserve crust texture and visual appeal for artisan bread and pastry presentation. European operators prioritize display-optimized designs with shorter replacement cycles than utilitarian back-of-house alternatives. CE-marked, F-Gas-compliant systems dominate procurement specifications in EMA-monitored environments.
- Delicatessen:Dual-temperature requirements for sliced meats and prepared salads drive specification complexity. Independent operators favor compact footprints for space-constrained urban locations.
- Confectionery:Precise humidity control prevents sugar bloom and chocolate degradation. Specialty retailers specify premium illumination and glass clarity for impulse merchandising.
- Cafeteria:High-traffic self-service formats prioritize durability and standardized cleaning protocols. Procurement concentrates in multi-unit chains with centralized specification authority.
Foodservice captures the largest application share. Bakery applications post the steepest margin premiums.
End User:
Scale economies fragment across operator types. Multi-unit chains leverage centralized procurement and standardized configurations, while independent operators face higher per-unit costs and complex specification decisions.
- Quick Service Restaurants:Cold-chain display footprints consolidate as consumer preference for visible freshness forces equipment refresh cycles. Chains across North America and Europe displace traditional cafeteria procurement with standardized grab-and-go configurations. Hydrocarbon-based cooling systems gain traction under tightening efficiency standards.
- Hotels:Banquet and buffet operations demand flexible thermal zoning with rapid reconfiguration between service formats. Full-service properties in Jakarta and Bangkok specify premium display aesthetics for lobby and restaurant visibility.
- Catering Services:Mobile and temporary deployment requirements prioritize lightweight construction and rapid setup. Event operators in Vietnam seek rental-compatible durability.
- Institutional Canteens:Schools, hospitals, and corporate facilities emphasize total cost of ownership over display aesthetics. Procurement standardizes around energy efficiency certifications and extended service intervals.
Quick service restaurants anchor volume demand. Hotels command the highest specification premiums.
Sales Channel:
Channel economics reflect service intensity and customer scale. Direct relationships capture complex specification work, while distributors serve fragmented independent demand.
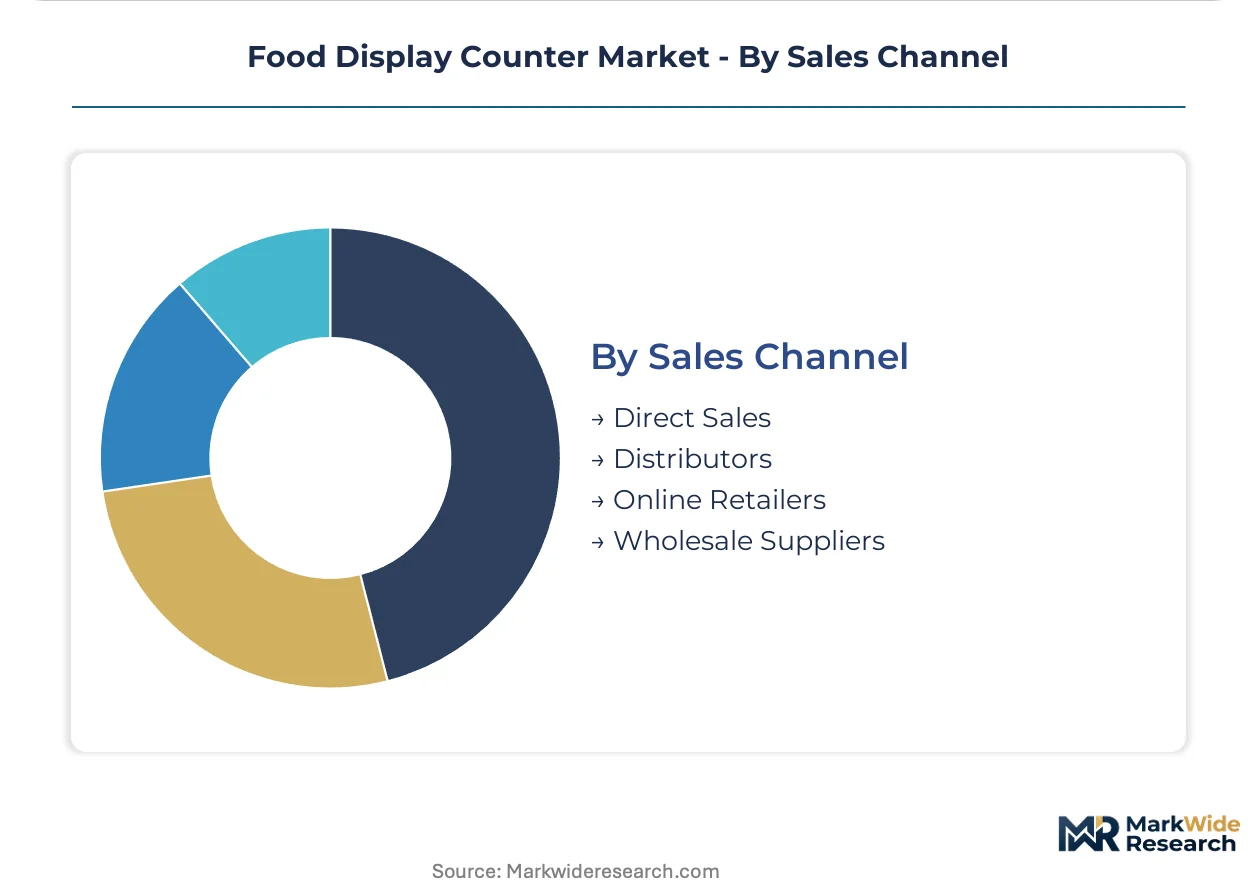
- Distributors:Regional inventory positions and field service capabilities support independent restaurant operators and small-format retailers. Distributors in Southeast Asia hesitate to stock transitional refrigerant models amid EPA and F-Gas regulatory uncertainty.
- Direct Sales:Manufacturer relationships with multi-unit chains handle complex specification, installation coordination, and fleet management. Large operators in North America negotiate centralized procurement with standardized configurations across hundreds of locations.
- Online Retailers:Specialized procurement portals enable independent operators to compare specifications and pricing without traditional distribution layers. Compact ambient and heated units move most readily through digital channels.
- Wholesale Suppliers:Volume aggregation serves contractor and project-based procurement for new construction and renovation. Infrastructure buildout in Vietnamese food processing drives wholesale specification activity.
Distributor networks handle the majority of unit volume. Direct sales capture the largest transaction values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting manufacturing investment toward jurisdictions with lower refrigerant compliance costs and faster certification timelines. Southeast Asian assembly operations capture displaced capacity from North American and European facilities facing stricter efficiency mandates.
United States
Quick service restaurant chains are consolidating cold-chain display footprints across thousands of locations. The EPA enforces HFC phase-down schedules that accelerate equipment refresh decisions. Missouri-based manufacturing complexes serve centralized procurement for multi-unit operators.
Germany
European bakery and prepared food operators prioritize display-optimized configurations with CE marking. The F-Gas Regulation mandates refrigerant transitions that create replacement demand for legacy units. Industrial clusters in Baden-Württemberg specialize in F-Gas-compliant system engineering.
Vietnam
Foreign direct investment flows into food processing and retail cold chain infrastructure buildout. The country's national standards body coordinates with import regulators on equipment certification. Ho Chi Minh City street food vendors adopt compact ambient and refrigerated displays as urban retail modernizes.
Thailand
Hotels in Bangkok specify premium display aesthetics for lobby and restaurant visibility. Energy efficiency labeling requirements shape procurement specifications for new construction. Bangkok-based distributors hesitate to stock transitional refrigerant models amid regulatory uncertainty.
Indonesia
Convenience retail chains expand standardized chilled merchandise zones in petrol station forecourts. The national food safety authority monitors cold chain compliance in urban micro-formats. Jakarta institutional canteens drive demand for heated counter configurations in high-traffic self-service formats.
Food Display Counter Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium thermal engineering concentrated among refrigeration-focused incumbents and cost-engineered units flowing through fabrication networks. The vendor base organizes into three tiers: hydrocarbon system specialists serving regulated North American and European markets, stainless steel fabricators leveraging Southeast Asian assembly partnerships, and modular platform providers targeting independent restaurant operators. Consolidation pressures favor multi-product refrigeration portfolios over single-line display specialists. Strategic moves center on refrigerant transition timing and direct-to-operator digital channel development.
Within the premium refrigeration tier, Hoshizaki and True Manufacturing exemplify divergent geographic anchoring strategies, while Turbo Air occupies a position in cost-engineered segments for fragmented independent demand. Hoshizaki leverages Japanese thermal engineering heritage across Asian market development. True Manufacturing sustains Missouri-based production scale for North American chain procurement. Turbo Air competes through standardized configurations that reduce specification complexity for small-format operators.
| Leading Market Players |
|---|
| Hoshizaki |
| True Manufacturing |
| Turbo Air |
| Alto-Shaam |
| Hatco |
| The Vollrath Company |
| Carrier Global Corporation |
| The Middleby Corporation |
| Epta Group |
| Others |
Supply & Pricing Matrix
Hydrocarbon refrigerant transitions are compressing manufacturing cost structures while redistributing pricing power toward suppliers with certified system engineering capabilities. Equipment manufacturers face simultaneous margin pressure from stainless steel volatility and premium capture opportunities from efficiency-compliant product lines.
Pricing Analysis
Distributor margin layers compress as direct-to-operator digital channels proliferate across Southeast Asian markets. Three-tier pricing structure across premium hydrocarbon systems, standard HFC transition units, and economy-grade ambient displays separates procurement specifications by end-user scale. Pricing pressure stems from commodity-linked raw material exposure in 304-grade stainless and tempered glass inputs. Independent restaurant operators exhibit highest price sensitivity, while multi-unit quick service chains absorb premiums for fleet-standardized configurations.
Supply Chain Analysis
Compressor supply rests on concentrated East Asian manufacturing clusters with limited alternative sourcing pathways. Critical refrigeration components originate from China, South Korea, and Japan, while stainless steel feedstock draws from Indonesian and Chinese metallurgical operations. Single-source vulnerability in hydrocarbon-compatible heat exchangers creates disruption exposure amid geopolitical friction. Distribution runs through regional inventory positions in Bangkok, Ho Chi Minh City, and Jakarta serving fragmented independent demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food display counter demand compounds steadily as urban foodservice infrastructure modernizes across Southeast Asian metropolitan corridors. Regulatory efficiency mandates ensure replacement-driven revenue visibility regardless of macroeconomic cycles.
For Market Incumbents: Hedge refrigerant transition timing by maintaining parallel HFC and hydrocarbon production lines until EPA phase-down clarity solidifies. Secure captive supply of 304-grade stainless through backward integration into Southeast Asian fabrication partnerships. Defensive patent positioning around modular plug-and-play compressor architectures protects against emerging cost-engineered competitors.
For New Entrants and Emerging Players: IoT-enabled temperature monitoring systems offer technology-first wedge into established foodservice chains with legacy control integration pain points. Target Vietnam's infrastructure buildout through local assembly partnerships reducing landed cost for imported refrigeration components. Deploy specialized procurement portals bypassing traditional distributor layers to capture independent operator price sensitivity.
For Investors and Strategic Acquirers: Valuations sit cheapest among stainless steel fabricators lacking hydrocarbon certification capabilities but possessing Southeast Asian assembly infrastructure. Five-to-ten year viability hinges on regulatory compliance transition execution rather than cyclical demand exposure. Watch EPA refrigerant phase-down timeline acceleration as primary inflection signal for stranded inventory risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocarbon System Certification Investment | EPA efficiency mandates force capital allocation toward flammable refrigerant handling capabilities and technician workforce development. |
| Southeast Asian Assembly Partnership | Vietnamese and Thai production hubs reduce landed costs for components serving regional modernization demand. |
| Direct-to-Operator Digital Channel Launch | Specialized procurement portals capture independent restaurant operators comparing specifications outside traditional distribution layers. |
| Modular Plug-and-Play Platform Development | Swappable compressor units minimize downtime for quick service chains calculating total cost of ownership. |
| Dual-Temperature Hybrid Unit Introduction | Converged heated holding and refrigerated display addresses space-constrained urban bakery and prepared food formats. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foodservice equipment procurement managers, refrigeration system engineers, distributor inventory planners, and aftermarket service technicians against secondary validation. Regulatory filings from the EPA and F-Gas Regulation databases, commercial refrigeration efficiency standard disclosures, and Southeast Asian import certification records anchored top-down market sizing. Bottom-up triangulation cross-checked manufacturer production disclosures with distributor shipment patterns across Vietnam, Thailand, and Indonesia.
Segment-weighting approaches distributed value across refrigerated, grab-and-go, heated, and ambient product configurations, with further disaggregation by quick service restaurant, hotel, catering, and institutional end-user archetypes. CAGRs derived from replacement cycle analysis, regulatory phase-down timelines, and urban foodservice infrastructure investment flows across the projection horizon. Hydrocarbon transition adoption curves and stainless steel price elasticity informed scenario boundaries.
The model holds under stable regulatory phase-down schedules and continued Southeast Asian foreign direct investment flows; deviation in EPA timeline acceleration or geopolitical disruption of East Asian compressor supply would shift volume and value trajectories. A small set of named triggers—refrigerant certification delays, commodity price spikes, and distributor inventory hesitation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Countertop Ice Dispensers Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Commercial Foodservice Equipment Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Used Restaurant Equipment Market