
 Commercial Rotisserie Equipment Market | 2026-2036
Commercial Rotisserie Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Rotisserie Equipment Market Analysis
Grocery chains and supermarket delis is redrawing the buyer landscape for commercial rotisserie equipment, pulling investment away from traditional restaurant-centric vendors. Middleby Corporation leverages its vertical manufacturing footprint to dominate the high-volume supermarket segment. Alto-Shaam Inc. differentiates through low-temperature cooking technology that extends hold times for prepared-food cases. Henny Penny Corporation anchors the gas-powered rotisserie niche with pressure-cooking integration for faster throughput.
Commercial rotisserie equipment comprises motorized spit assemblies, radiant or convection heat sources, and grease-management systems engineered to cook poultry, meat, and seafood in continuous batches at temperatures typically ranging from 250°F to 450°F. Electric rotisseries lead unit shipments in urban markets where ventilation restrictions limit gas installations, while gas rotisseries command stronger margins in high-throughput supermarket and catering environments. Floor-mounted designs occupy the majority of commercial kitchen layouts, though mobile units are gaining traction among food truck operators seeking flexible protein-cooking platforms.
The US Department of Energy sets minimum efficiency standards for commercial cooking equipment, while NSF International certifies sanitation and food-contact safety for rotisserie components sold into foodservice channels. The EPA regulates emissions from gas-fired equipment, pushing manufacturers toward infrared burner technologies that reduce nitrogen oxide output. Stakeholders must weigh electrification roadmaps against gas infrastructure durability as local building codes tighten fossil-fuel restrictions in new commercial construction.
Market Dynamics
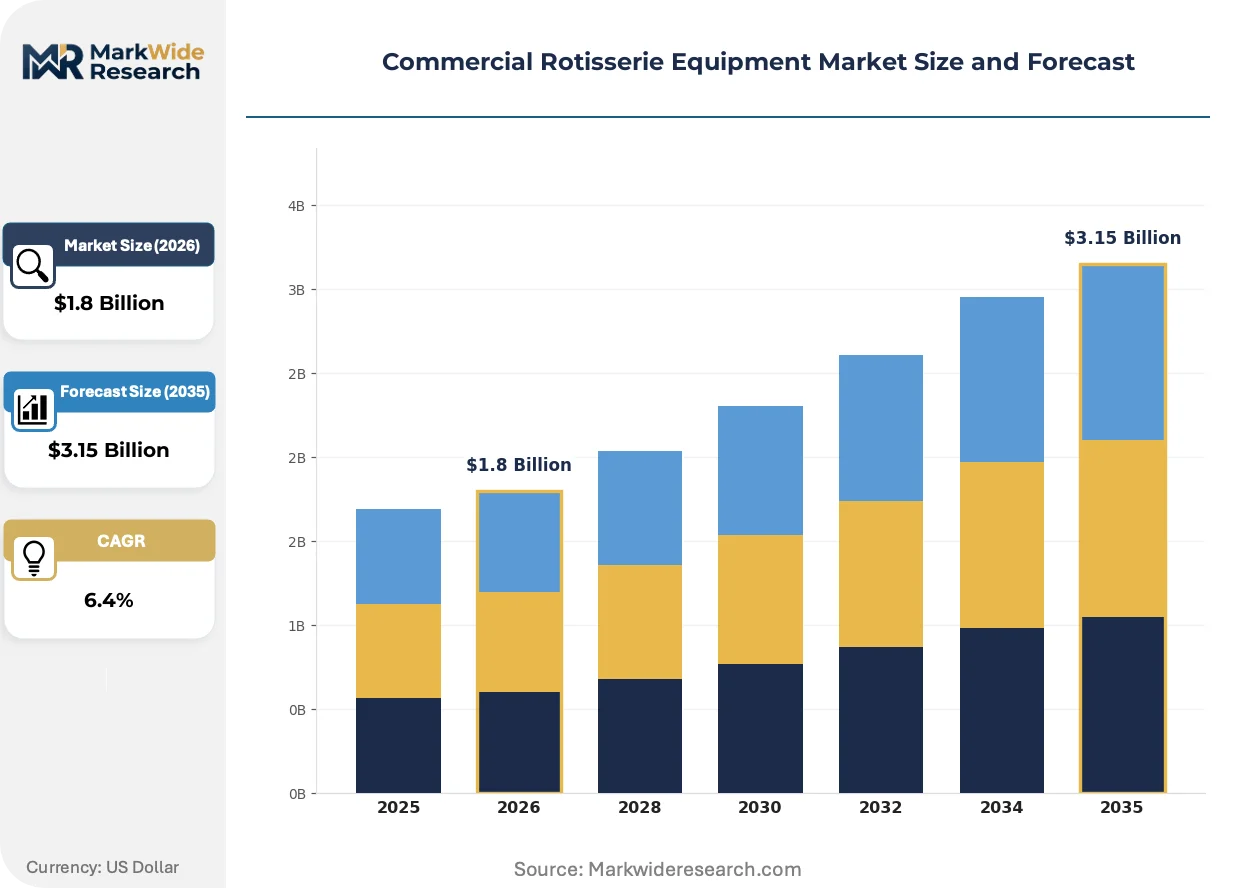
Supermarket deli expansion is compressing replacement cycles for commercial rotisserie equipment as grocers compete for prepared-meal traffic against quick-service restaurants. Equipment buyers now prioritize hold-time extension and energy compliance over raw throughput.
Growth Catalysts
- US Department of Energy commercial cooking standards:Federal efficiency mandates are forcing early retirement of pre-2023 gas and electric units across foodservice operations.
- Supermarket deli departments:Grocery chains are scaling rotisserie programs to capture evening meal traffic from time-constrained households.
- Infrared burner technology:Gas-fired equipment retrofits are accelerating as operators seek EPA-compliant nitrogen oxide reductions without full replacement.
Market Restraints
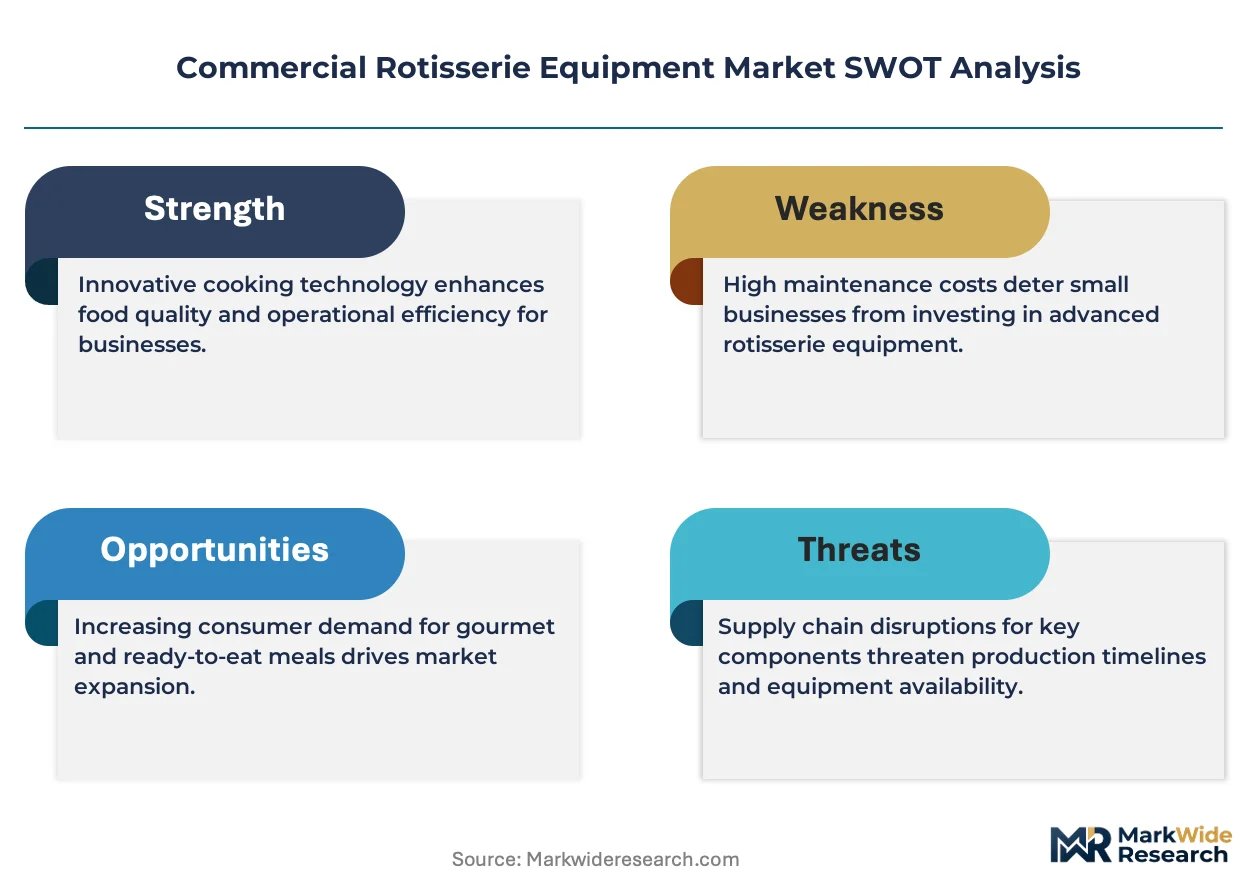
- Stainless steel input volatility:Equipment fabrication costs fluctuate with nickel and chromium pricing, squeezing margin predictability for mid-tier manufacturers.
- Ventilation infrastructure lock-in:Urban commercial kitchens face municipal codes restricting gas hookups, limiting addressable market for gas-powered rotisserie lines.
- Pressure-cooking integration complexity:Hybrid rotisserie-pressure systems require specialized maintenance protocols that many independent operators cannot support.
Strategic Opportunities
- Food truck mobile platforms:Compact electric rotisserie units with battery compatibility are opening addressable market among mobile protein-cooking operators.
- NSF International sanitation certification:Premium positioning through enhanced food-contact safety credentials commands pricing power in hospital and university cafeteria channels.
- Convection-radiant hybrid heat systems:Technology convergence is enabling single units to switch between roasting profiles for poultry, seafood, and plant-based alternatives.
Industry Challenges
- Commercial cooking equipment technician scarcity:Specialized repair talent for motorized spit assemblies and grease-management systems concentrates in major metropolitan areas.
- NSF certification timeline compression:Sanitation validation cycles for new rotisserie component designs are extending product launch windows by four to six months.
- Legacy kitchen layout retrofit friction:Floor-mounted unit dimensions often conflict with existing exhaust hood placements in renovated commercial spaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Rotisserie Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Rotisseries, Gas Rotisseries, Charcoal Rotisseries, Wood-Fired Rotisseries End User: Restaurants, Catering Services, Food Trucks, Supermarkets Capacity: Small, Medium, Large, Extra Large Design: Countertop, Floor-Mounted, Built-In, Mobile |
| Companies Covered | Middleby Corporation, Alto-Shaam Inc., Henny Penny Corporation, Electrolux Professional, Rotisol, Fri Jado B.V., Rational AG, Hickory Industries, Inc., The Vollrath Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Rotisserie Equipment Market Emerging Trajectories
Equipment intelligence and thermal engineering are converging to reshape how commercial kitchens manage protein throughput and energy consumption. Three developments are altering competitive positioning.
Infrared burner arrays with ceramic radiants are displacing traditional atmospheric gas burners in high-volume supermarket installations. Grocers operating 24-hour rotisserie programs are adopting these systems to maintain consistent surface temperatures while reducing gas consumption. The technology is displacing conventional burner retrofits as the default efficiency upgrade path for existing equipment fleets.
EPA emissions regulations for gas-fired commercial cooking equipment are tightening nitrogen oxide thresholds in new construction permits. Manufacturers are responding with pre-certified low-NOx burner configurations that streamline regulatory approval for foodservice operators. Gas-powered rotisserie lines face the steepest compliance burden in California and New York municipalities with local air quality districts.
Leasing arrangements bundled with preventive maintenance contracts are displacing outright equipment purchases among independent restaurant groups. Equipment finance firms are capturing margin that previously accrued to manufacturer sales channels. The shift is most visible in the casual dining segment where capital conservation outweighs long-term ownership preferences.
Commercial Rotisserie Equipment Market Segmentation
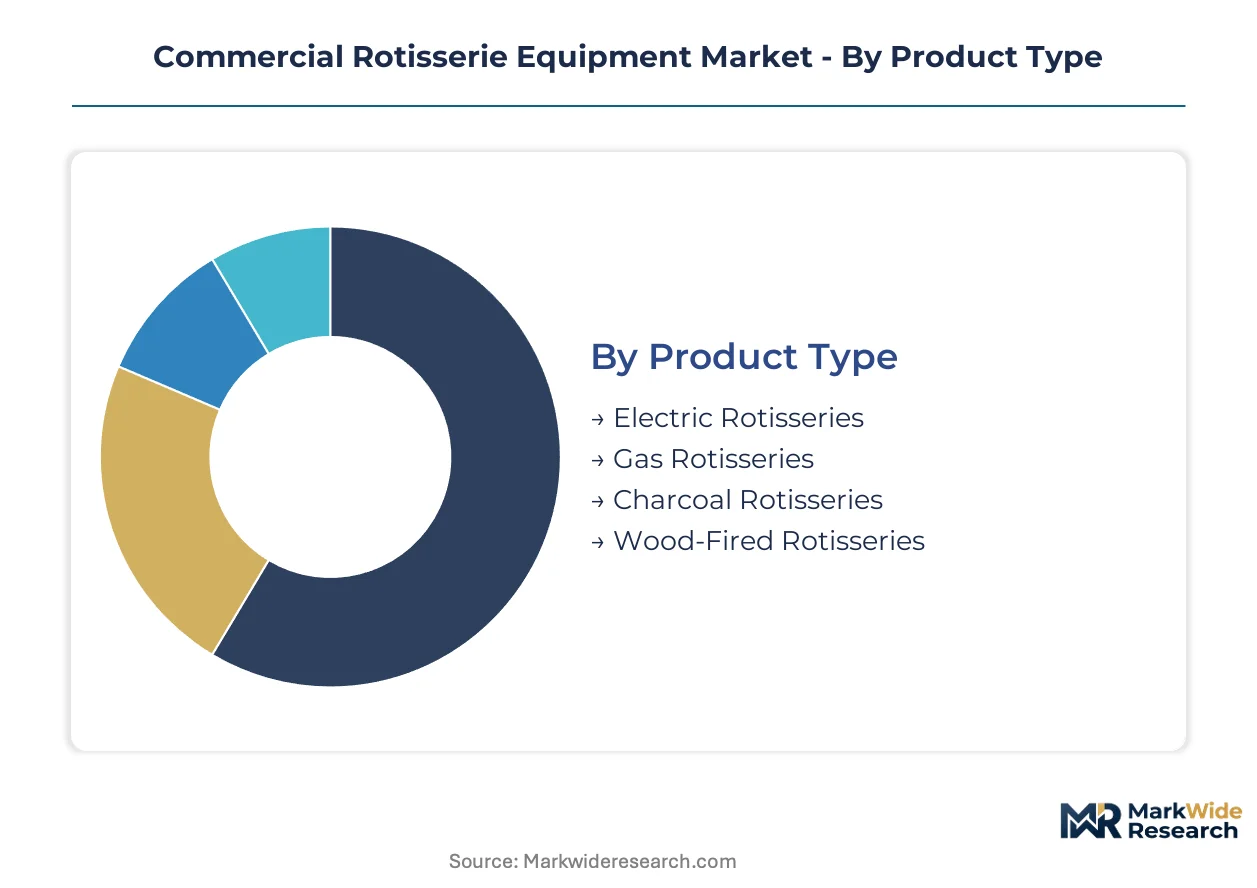
Channel strategy for commercial rotisserie equipment diverges sharply between supermarket chains seeking volume throughput and mobile operators prioritizing footprint flexibility. Equipment specifications, energy compatibility, and sanitation certifications vary systematically across these buyer profiles, creating distinct product-market fit requirements.
Product Type:
Supermarket deli departments and food truck fleets drive divergent channel flows for electric versus gas-powered rotisserie lines, with urban ventilation codes and rural propane access shaping regional penetration patterns.
- Electric Rotisseries:These units deploy enclosed convection or radiant heating elements rated between 208V and 480V, eliminating combustion ventilation requirements. Demand concentrates in urban restaurant clusters across California and New York municipalities where municipal building codes restrict new gas hookups in commercial construction.
- Gas Rotisseries:Atmospheric or infrared burner configurations deliver faster heat recovery for high-volume poultry processing. Supermarket deli departments in Texas, Florida, and Georgia anchor procurement volumes where gas infrastructure remains unrestricted and throughput economics dominate equipment selection criteria.
- Charcoal Rotisseries:Open-flame designs with manual spit rotation serve boutique barbecue concepts and artisanal poultry specialists seeking smoke-infused flavor profiles as a competitive differentiator.
- Wood-Fired Rotisseries:Refractory-lined combustion chambers accommodate hardwood fuel sources for Mediterranean and Latin American restaurant formats emphasizing traditional preparation methods.
By volume, gas rotisseries lead. By growth pace, electric rotisseries are expanding most quickly.
End User:
Procurement scale and replacement frequency separate institutional buyers from independent operators, with contract terms and service bundling varying accordingly.
- Restaurants:Full-service and fast-casual concepts deploy rotisserie equipment for protein-centric menu platforms, with independent operators favoring countertop units and multi-unit chains specifying floor-mounted configurations for kitchen standardization.
- Catering Services:High-volume event operators prioritize rapid batch turnaround and transport stability, driving demand for mobile units with reinforced chassis and quick-disconnect utilities.
- Food Trucks:Compact electric rotisseries with battery-compatible power systems are gaining adoption among mobile protein-cooking operators seeking menu differentiation without ventilation infrastructure.
- Supermarkets:Grocery chains operate the largest installed base of commercial rotisserie equipment, with deli departments specifying NSF-certified units for prepared-food case integration and extended hold-time performance.
Supermarkets command the largest installed base. Food trucks show the steepest expansion trajectory.
Capacity:
Batch size economics and kitchen footprint constraints create tiered addressable markets with distinct margin profiles.
- Small:Countertop units processing 4-8 birds per batch serve independent restaurants and specialty poultry shops with limited kitchen square footage.
- Medium:Floor-mounted systems accommodating 12-20 birds per cycle dominate mid-market casual dining and regional supermarket deli formats.
- Large:High-throughput configurations processing 30-50 birds per batch anchor major grocery chain rotisserie programs and institutional catering operations.
- Extra Large:Continuous-feed industrial systems serve centralized commissary operations supplying multiple retail locations or stadium concessions.
Medium capacity units generate the highest shipment volumes. Extra large systems command the strongest pricing power.
Design:
Installation permanence and spatial flexibility determine specification patterns across new construction and retrofit projects.
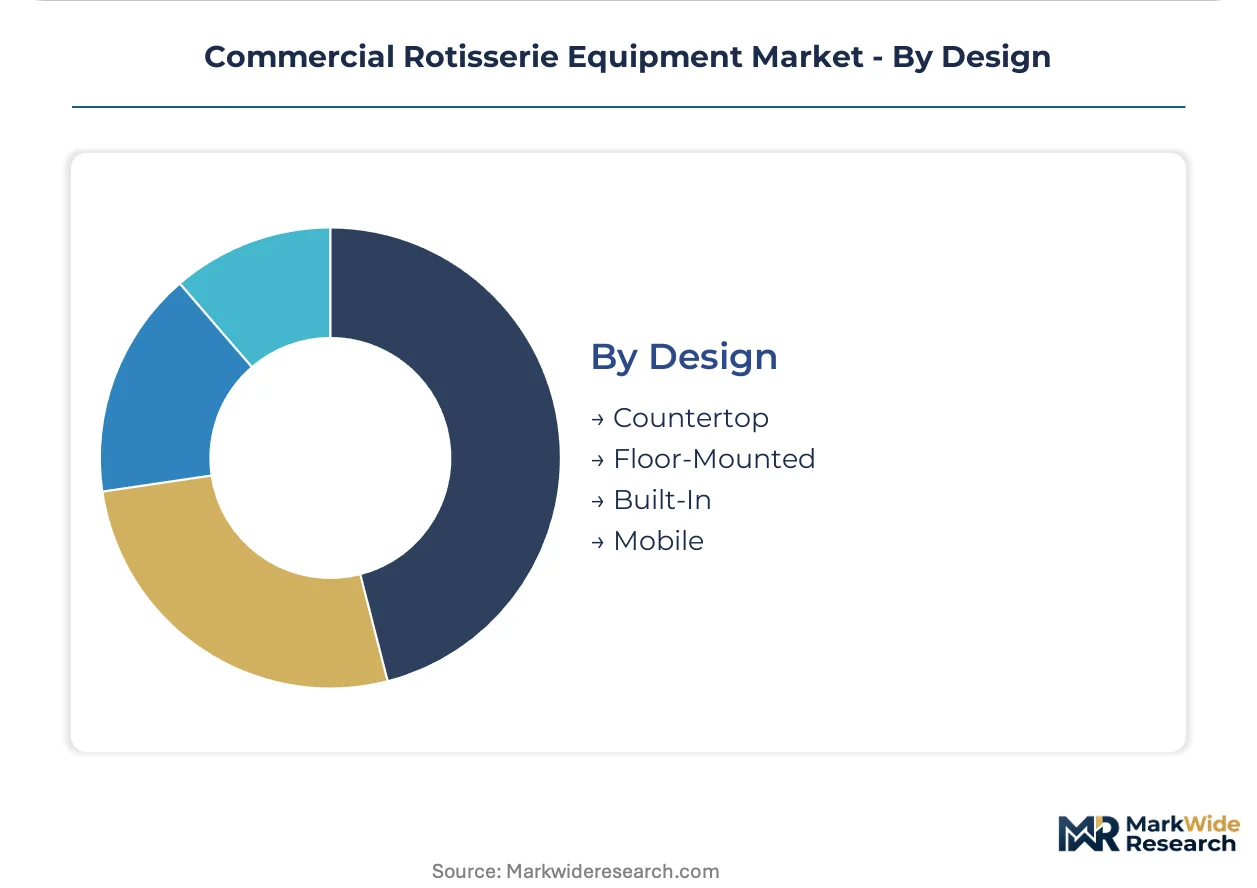
- Countertop:Compact electric units with front-facing controls occupy prep line surfaces in kitchens where floor space is constrained by existing exhaust hood placement.
- Floor-Mounted:Freestanding gas and electric configurations with caster or fixed base options constitute the majority of commercial kitchen layouts, offering access for maintenance and cleaning protocols.
- Built-In:Custom enclosure integration with surrounding cabinetry and serving counters appears in high-end supermarket deli renovations and flagship restaurant concepts.
- Mobile:Trailer-mounted or self-propelled units with onboard power generation serve outdoor event catering and temporary foodservice installations.
Floor-mounted designs dominate current installations. Mobile configurations are gaining share fastest among emerging food truck and pop-up dining formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-manufactured commercial rotisserie equipment flows primarily to Canadian supermarket chains and Mexican foodservice distributors serving the North American prepared-meal corridor.
United States
Kroger, Albertsons, and Publix operate the world's largest rotisserie chicken retail networks, driving procurement of high-throughput gas-powered units. The US Department of Energy commercial cooking standards mandate minimum efficiency thresholds that accelerate replacement of pre-2023 equipment across deli operations. Chicago-area manufacturing clusters supply motorized spit assemblies and infrared burner arrays to grocery chains throughout the Midwest and Southeast.
Canada
Loblaw Companies and Sobeys scale rotisserie programs to capture evening meal traffic in Toronto, Vancouver, and Montreal metro areas. Health Canada sanitation protocols align with NSF International certification requirements for food-contact safety in commercial cooking equipment. Ontario-based equipment distributors serve as the primary import channel for US-manufactured rotisserie lines entering the Canadian market.
Mexico
Walmart de México and Grupo La Comer expand prepared-food cases in Mexico City, Guadalajara, and Monterrey retail formats. The country's federal consumer protection agency enforces commercial equipment safety standards that parallel US UL certification benchmarks. Baja California and Nuevo León host assembly operations for gas-powered rotisserie units distributed throughout Central American foodservice channels.
Germany
Metro AG and REWE Group deploy rotisserie equipment in hypermarket deli departments across Berlin, Munich, and Hamburg metropolitan regions. The EU Ecodesign Directive establishes energy efficiency requirements for commercial cooking appliances sold throughout member states. Baden-Württemberg engineering firms specialize in convection-radiant hybrid heat systems for European supermarket chains.
United Kingdom
Tesco, Sainsbury's, and Morrisons compete for prepared-meal market share with expanded rotisserie offerings in Greater London, Manchester, and Birmingham retail locations. The UK Food Standards Agency regulates food-contact materials and equipment sanitation protocols for commercial kitchen installations. Midlands manufacturing centers produce compact electric rotisserie units for urban restaurant operators facing ventilation restrictions.
Commercial Rotisserie Equipment Market Vendor Landscape
Player mix skews toward diversified commercial kitchen equipment conglomerates with captive distribution networks and specialized thermal engineering boutiques focused on hold-time optimization. Market structure concentrates around three strategic tiers: vertically integrated multi-brand holding companies controlling supermarket procurement channels, mid-scale fabricators competing on NSF certification speed and customization flexibility, and regional specialists serving ethnic cuisine formats with charcoal and wood-fired configurations. Dominant competitive moves include backward integration into burner component manufacturing and strategic equipment leasing partnerships with foodservice finance firms.
Within the diversified equipment conglomerate tier, Middleby Corporation, Alto-Shaam Inc., and Henny Penny Corporation exemplify divergent specialization vectors. Middleby represents the holding-company archetype with multi-brand portfolio breadth spanning high-volume supermarket installations. Alto-Shaam occupies a position emphasizing low-temperature thermal engineering for extended hold-time performance. Henny Penny anchors the gas-powered equipment niche with pressure-cooking integration expertise. Electrolux Professional and Rational AG sit within the European engineering tradition of precision convection control. Fri Jado B.V. exemplifies the mid-scale specialist archetype with focused deli-case integration capabilities.
| Leading Market Players |
|---|
| Middleby Corporation |
| Alto-Shaam Inc. |
| Henny Penny Corporation |
| Electrolux Professional |
| Rotisol |
| Fri Jado B.V. |
| Rational AG |
| Hickory Industries, Inc. |
| The Vollrath Company LLC |
| Others |
Supply Flow & Price Mechanics
High-volume manufacturing scale in Midwest industrial corridors anchors pricing power for motorized spit assemblies and infrared burner arrays, compressing unit economics for mid-tier fabricators while elevating floor prices for NSF-certified configurations. This concentration of production capacity in Illinois and Ohio manufacturing clusters simultaneously shapes supply availability and establishes resistance levels for premium equipment tiers.
Pricing Analysis
Next-generation infrared burner configurations command 15-25% premiums over atmospheric gas predecessors, while legacy electric convection units face accelerating price erosion from energy-efficiency mandate displacement. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified supermarket installations from uncertified restaurant countertop units and refurbished equipment channels. Pricing pressure stems from stainless steel input volatility, with nickel and chromium spot movements squeezing margin predictability for independent fabricators. Independent restaurant operators exhibit highest price sensitivity, prioritizing capital conservation through leasing arrangements, while grocery chains absorb premium pricing for extended hold-time performance.
Supply Chain Analysis
Port congestion across Los Angeles-Long Beach and Savannah trade lanes elevates inbound logistics costs for European-sourced convection-radiant hybrid components and Asian-manufactured electronic control systems. Component sourcing concentrates in Germany for precision thermal engineering, China for motor drives and control electronics, and domestic Midwest clusters for fabricated stainless enclosures. Raw material dependencies rest on nickel-alloy sheet from Indonesian smelters, chromium from South African mines, and ceramic radiant elements from Japanese specialty ceramics producers. Single-source vulnerability concentrates in infrared burner ceramic substrate supply, where two German suppliers dominate global capacity. Distribution runs through manufacturer-direct channels for supermarket chains, regional equipment dealers for independent restaurants, and foodservice finance firms for leasing-bundled transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US Department of Energy commercial cooking standards are forcing a technology inflection that compresses replacement cycles and reconfigures competitive advantage around energy compliance rather than raw throughput.
For Market Incumbents: Shield market position through backward integration into burner component manufacturing, capturing margin that currently flows to third-party ceramic radiant suppliers. Prioritize captive production of low-NOx infrared configurations to preempt regulatory compliance bottlenecks in California and New York municipalities. Accelerate NSF certification pipeline investments to compress four-to-six month validation windows that delay product launches against nimbler competitors. For New Entrants and Emerging Players: Differentiate on battery-compatible electric rotisserie platforms for food truck operators, a segment where ventilation restrictions and mobility requirements create addressable white space. Target compact countertop configurations for urban ghost kitchen operators facing exhaust hood placement constraints in retrofitted commercial spaces. Pursue direct-to-operator digital sales channels bypassing incumbent dealer networks that concentrate on multi-unit grocery contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized thermal engineering boutiques with proprietary hold-time extension IP over diversified conglomerates facing portfolio complexity drag. Long-term viability hinges on electrification roadmap execution as municipal gas hookup restrictions tighten across new commercial construction. Acquisition target archetype: mid-scale fabricators with accelerated NSF certification capabilities and existing supermarket deli case integration relationships. The signal to watch is EPA nitrogen oxide threshold tightening in California Air Resources Board rulemaking, which would force premature replacement of installed gas-fired equipment fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Infrared Burner Technology Licensing | Low-NOx configurations streamline EPA compliance for gas-powered supermarket installations in California municipalities. |
| NSF Certification Acceleration Program | Compressed validation cycles reduce four-to-six month product launch delays against competitors with faster regulatory pathways. |
| Preventive Maintenance Contract Bundling | Recurring revenue capture from independent restaurant groups displaces outright purchase margin erosion. |
| Mobile Platform Battery Integration | Food truck electrification opens addressable market among operators lacking ventilation infrastructure. |
| Backward Integration into Ceramic Radiants | Captive supply of infrared burner substrates mitigates single-source vulnerability from German supplier concentration. |
Methodological Framework
A standing panel of supermarket deli operations directors, commercial kitchen equipment maintenance technicians, foodservice finance underwriters, and NSF International certification specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with procurement managers at Kroger, Albertsons, and Publix alongside secondary validation through US Department of Energy efficiency standard filings, EPA emissions compliance databases, and commercial cooking equipment trade association shipment data. Bottom-up unit shipment modeling triangulated against top-down grocery chain capital expenditure disclosures.
Consistency checks validated volume and value outputs against external benchmarks including supermarket prepared-food case expansion rates, commercial kitchen construction permit flows, and equipment replacement cycle surveys. The analytical framework segmented projections across product type, end user, capacity tier, and design configuration, with additional dimensioning by energy compliance status and NSF certification level. CAGRs were derived from installed base turnover rates, efficiency mandate phase-in schedules, and regional gas hookup restriction trajectories. Forecast inputs incorporated infrared burner adoption curves, battery-compatible electric unit penetration in mobile applications, and leasing arrangement growth in casual dining channels.
The analysis sits within stated boundaries; outcomes outside sustained supermarket deli expansion, stable stainless steel input pricing, and continued municipal electrification momentum would require recalibration. Forecasts reflect documented assumptions regarding replacement cycle compression, regulatory compliance cost pass-through rates, and technician availability for specialized maintenance protocols. Specific risks that could revise projections include accelerated EPA nitrogen oxide threshold tightening, supply disruption in ceramic radiant burner substrates, and prolonged technician scarcity in non-metropolitan service territories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Retail Cooler Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Commercial Cookers Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Global QSR Food Service Equipment Market