
 Global Commercial Dishwashers Market | 2026-2036
Global Commercial Dishwashers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Dishwashers Market Analysis
Stainless steel is restructuring product economics in commercial dishwashers as manufacturers substitute thicker-gauge alloys and hybrid polymer-steel drum assemblies to balance durability with weight reduction. Hobart leverages captive metallurgy partnerships to control input costs across its conveyor and door-type lines. Electrolux Professional anchors European institutional demand through modular rack systems designed for high-throughput cafeterias. MEIKO Maschinenbau differentiates via heat-recovery engineering that cuts rinse-cycle energy draw by capturing exhaust vapor.
Commercial dishwashers are industrial-grade sanitization machines engineered to process 200–1,000+ racks per hour through high-temperature wash zones (82°C minimum final rinse) or chemical sanitizing protocols, serving foodservice operators requiring health-code-compliant warewashing at scale. Conveyor systems dominate installed value in centralized kitchens and banquet facilities where throughput economics justify capital intensity. Water-efficient technology leads specification growth as operators face escalating utility tariffs and municipality-imposed consumption caps. Smart technology integration remains nascent but attracts development capital from vendors targeting predictive maintenance contracts and remote diagnostics revenue.
The U.S. Department of Energy and EPA ENERGY STAR program set mandatory efficiency floors that disqualify legacy models from federal procurement channels, while the EU Ecodesign Directive and REACH chemical restrictions constrain sanitizing agent formulations and material composition. China's SAMR enforces GB standards on imported commercial kitchen equipment, creating testing barriers for non-domestic manufacturers. Stakeholders must monitor how fragmented municipal water pricing across U.S. states and accelerating European F-Gas phase-down timelines reshape total-cost-of-ownership calculations for high-temperature versus chemical-sanitizing architectures.
Market Dynamics
Water scarcity mandates and escalating utility tariffs are compressing total-cost-of-ownership calculations for foodservice operators, forcing capital allocation toward heat-recovery architectures and low-consumption rinse technologies over legacy high-temperature systems.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency thresholds for commercial foodservice equipment are disqualifying legacy models from institutional procurement channels across Germany, France, and Italy.
- Full-service restaurant automation:North American and European chain operators are expanding automated dishroom investments to reduce labor dependency in high-turnover environments.
- Stainless steel drum assemblies:Thicker-gauge alloys and hybrid polymer-steel constructions are extending equipment lifespan while reducing unit weight for installation flexibility.
Market Restraints
- Nickel and chromium volatility:Input cost swings for austenitic stainless grades compress margin stability for manufacturers dependent on spot-market metallurgy.
- REACH chemical restrictions:Sanitizing agent formulations face compositional constraints that limit chemical-sanitizing architecture options in EU member states.
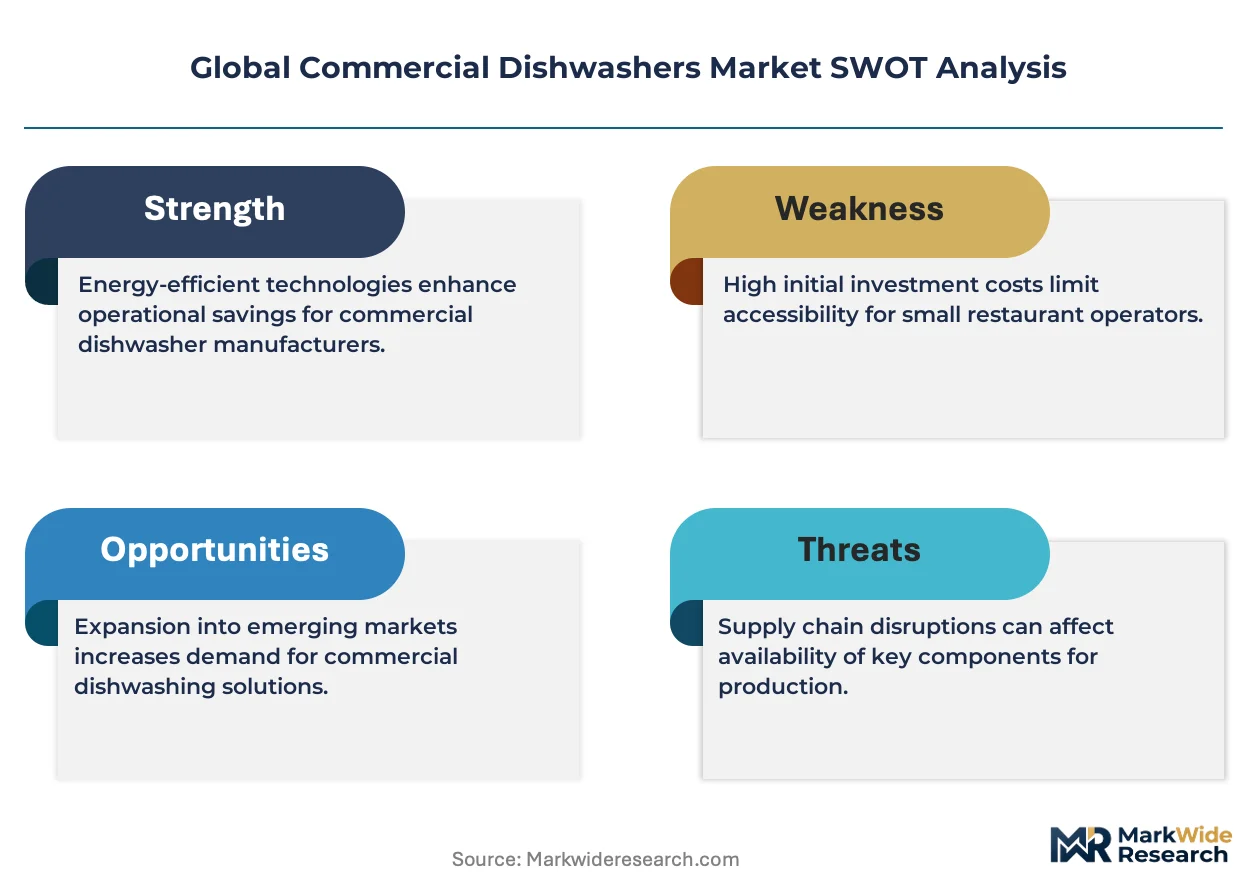
- Technical limitation of vapor capture:Heat-recovery engineering adds component complexity and maintenance burden that smaller operators struggle to justify.
Strategic Opportunities
- Underpenetrated India:Centralized procurement by institutional catering groups and quick-service chains creates pull for modular rack systems in urban clusters.
- Predictive maintenance contracts:Smart technology integration enables remote diagnostics revenue streams from vendors targeting multi-site foodservice operators.
- U.S. DOE efficiency standards:Mandatory floors disqualify legacy models from federal procurement, creating replacement demand across government and military foodservice facilities.
Industry Challenges
- Certification timeline compression:China's SAMR enforcement of GB standards on imported equipment creates testing barriers that delay market entry for non-domestic manufacturers.
- Integration complexity:Legacy kitchen management systems lack API compatibility with emerging IoT-enabled warewashing platforms, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Dishwashers Market |
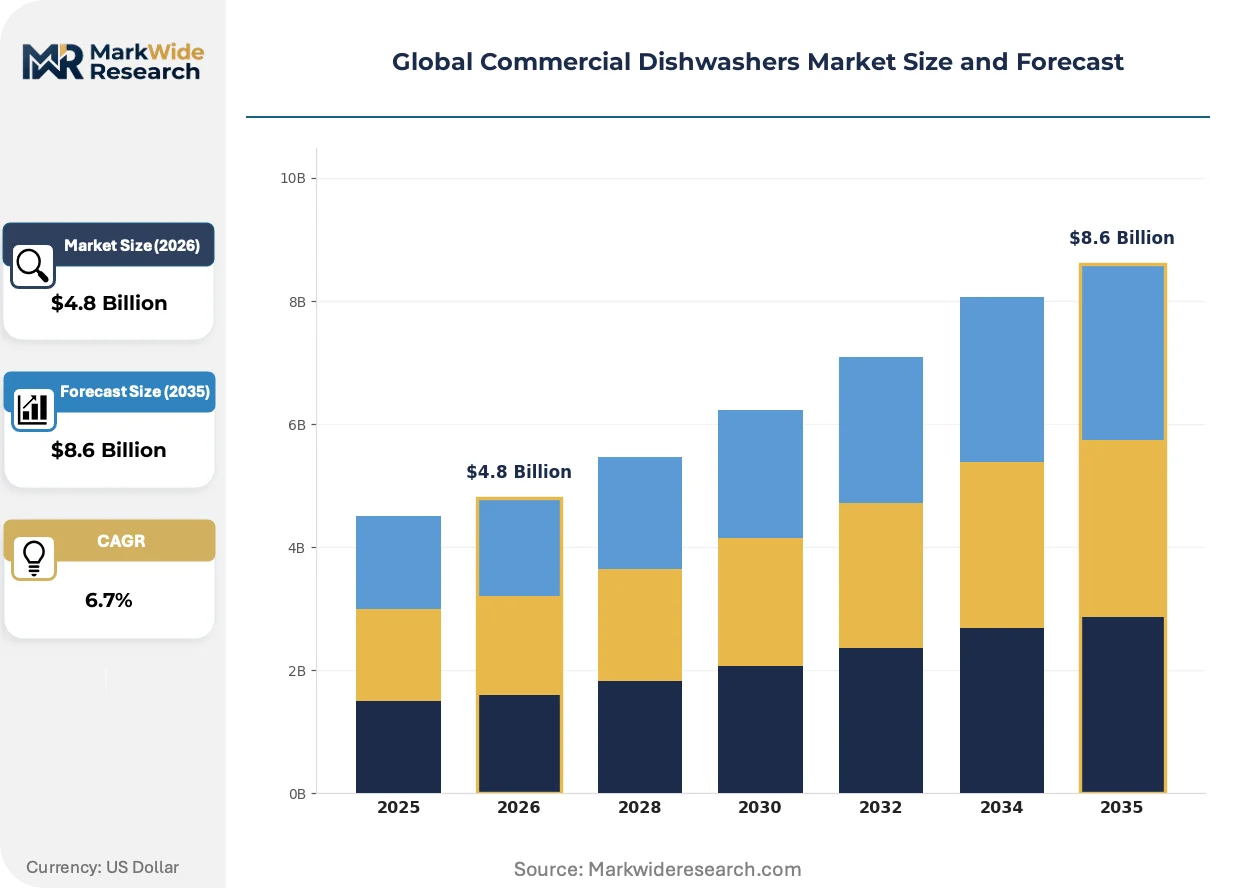
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Undercounter, Conveyor, Door-type, Continuous End User: Restaurants, Hotels, Cafeterias, Catering Services Technology: Water-Efficient, High-Temperature, Chemical Sanitizing, Smart Technology Installation Type: Built-In, Standalone, Portable, Custom |
| Companies Covered | Hobart, Electrolux Professional, Winterhalter Gastronom GmbH, MEIKO Maschinenbau, Miele, The Middleby Corporation, Blakeslee, Champion Industries, Jackson WWS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Dishwashers Market Emerging Trajectories
Equipment architecture is fragmenting into configurable subsystems as operators demand flexible throughput without full replacement cycles. Vendors are responding with componentized designs that permit field-upgradable capacity.
Heat-recovery engineering is modularizing commercial dishwasher design by capturing exhaust vapor to preheat incoming water. Institutional buyers in Germany and Scandinavia are specifying these systems for centralized kitchens where energy tariffs dominate operating economics. This architecture is compressing the payback period for premium conveyor installations.
The EU F-Gas Regulation is accelerating refrigerant-transition timelines for heat-pump-assisted warewashing systems. Equipment manufacturers face reformulation of working fluids or complete thermal-system redesign. High-temperature sanitizing architectures in Northern Europe are absorbing the largest compliance burden.
Centralized procurement by multi-site operators is consolidating vendor relationships and unbundling after-sales service from equipment purchase. Foodservice management companies are negotiating enterprise-wide maintenance contracts separate from capital expenditure. This pattern is most visible across U.S. hospital systems and university dining consortiums.
Global Commercial Dishwashers Market Segmentation
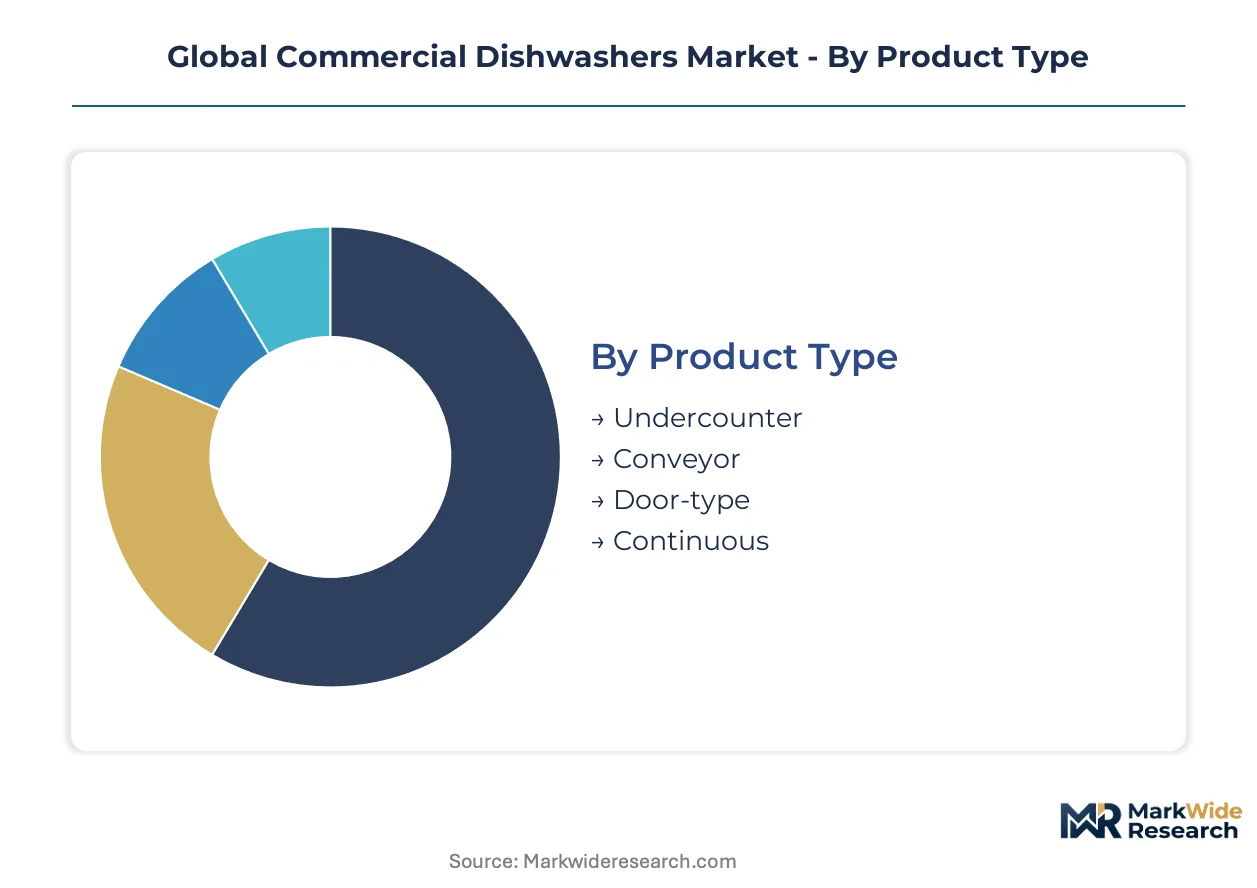
Commercial dishwasher segmentation reveals how equipment specifications align with operational scale and regulatory pressure. Product architecture, end-use intensity, and sanitizing technology each create distinct procurement patterns across foodservice verticals.
Product Type:
Supply concentration in conveyor systems reflects capital intensity barriers that filter smaller fabricators from high-throughput institutional contracts.
- Undercounter:Compact footprint units process 20-30 racks hourly through single-chamber wash cycles. Independent restaurants in France and Japan specify these for space-constrained kitchens where ventilation infrastructure limits high-temperature exhaust. Labor substitution pressures are accelerating specification upgrades to automated detergent dosing.
- Conveyor:Continuous-belt architectures handle 200-1,000+ racks hourly across multi-zone wash, rinse, and sanitizing tunnels. Centralized procurement by German hospital consortiums and U.S. university dining systems concentrates demand for heat-recovery configurations that capture exhaust vapor to preheat incoming water.
- Door-type:Rack-loaded chambers with vertical opening mechanisms serve mid-scale operators seeking throughput flexibility without conveyor footprint. Common in hotel banquet prep kitchens across Italy and Spain.
- Continuous:Flight-type systems integrate directly with kitchen workflow for uninterrupted ware processing. Specified by high-volume catering contractors in the United Kingdom for stadium and conference center operations.
Today's leader: Conveyor. Tomorrow's challenger: Undercounter.
End User:
Cost tier stratification separates capital-intensive institutional buyers from price-sensitive independent operators.
- Restaurants:Full-service chains across the United States deploy automated dishrooms to compress labor dependency in high-turnover markets. Quick-service operators in India are emerging as volume purchasers of modular rack systems for urban cluster expansion.
- Hotels:Integrated resort properties in the United Arab Emirates specify premium conveyor installations with remote diagnostics capability to minimize downtime during peak occupancy.
- Cafeterias:Institutional feeding facilities in Germany and Scandinavia dominate water-efficient technology procurement, driven by municipal consumption caps and energy tariff structures.
- Catering Services:Mobile and event-focused operators in Brazil favor portable configurations with rapid deployment specifications for temporary kitchen installations.
Institutional cafeterias anchor current procurement volume. Restaurant chains are climbing the fastest.
Technology:
Application intensity varies by sanitizing protocol, with heat-based systems facing F-Gas compliance burdens in Northern Europe.
- Water-Efficient:Low-consumption rinse architectures reduce per-cycle water draw through precision spray nozzles and recirculation filtration. California's municipal water pricing and Australia's drought-response tariffs are forcing retrofit specifications.
- High-Temperature:Final rinse zones maintain 82°C minimum for health-code compliance without chemical sanitizers. EU F-Gas Regulation is accelerating refrigerant-transition timelines for heat-pump-assisted variants in Sweden and Finland.
- Chemical Sanitizing:Chlorine or quaternary ammonium-based final rinse protocols suit installations with limited exhaust ventilation. REACH restrictions constrain formulation options across EU member states.
- Smart Technology:IoT-enabled platforms deliver predictive maintenance alerts and remote diagnostics. Development capital is concentrating on multi-site foodservice operators in the United States negotiating enterprise-wide service contracts.
Water-Efficient dominates specification growth. Smart Technology holds steepest expansion trajectory.
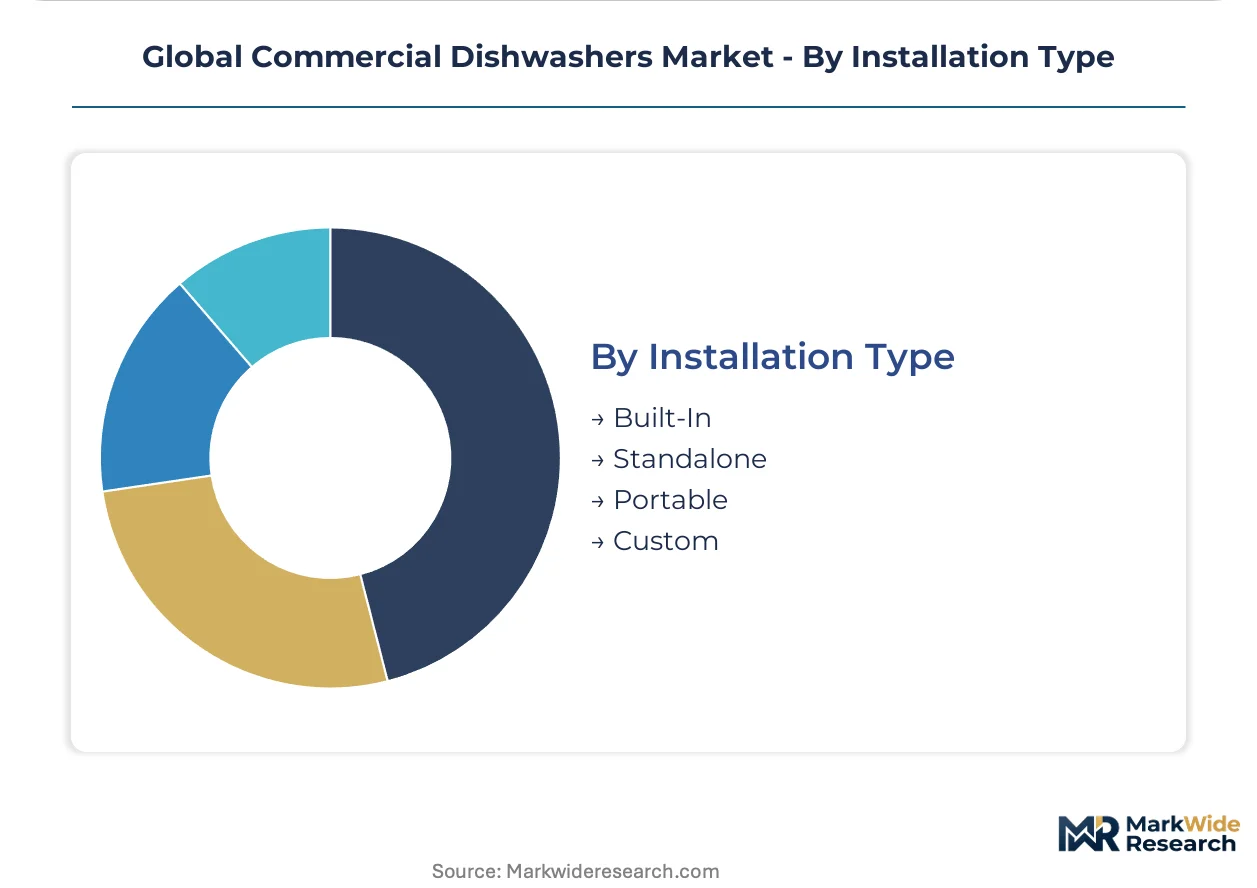
Installation Type:
Customer type segmentation separates permanent infrastructure investments from flexible deployment models.
- Built-In:Custom-integrated systems align with architectural specifications for new construction and major renovation projects. Common in luxury hotel developments across Saudi Arabia.
- Standalone:Self-contained units with independent utility connections serve retrofit markets and leased facilities. Standard specification for U.S. federal procurement channels under EPA ENERGY STAR mandates.
- Portable:Castor-mounted or skid-based configurations enable rapid relocation. Event catering contractors in South Korea specify these for convention center rotations.
- Custom:Engineered-to-order systems address non-standard spatial constraints or throughput requirements. Specified by centralized kitchen operators in the Netherlands for heritage building adaptations.
Standalone commands current volume. Portable is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German institutional procurement networks concentrate conveyor system demand across hospital consortiums and university dining systems, compressing vendor margins through centralized tendering while elevating specification floors for heat-recovery engineering.
United States
Full-service restaurant chains deploy automated dishrooms to reduce labor dependency in high-turnover markets. EPA ENERGY STAR mandates disqualify legacy models from federal procurement channels. California's municipal water pricing accelerates water-efficient retrofit specifications across Los Angeles and San Francisco foodservice clusters.
Germany
Centralized procurement by institutional catering groups favors premium conveyor systems with integrated heat recovery. EU Ecodesign Directive thresholds filter non-compliant equipment from public tenders. Berlin and Munich hospital consortiums dominate specification of modular rack systems for high-throughput cafeterias.
China
Quick-service chain expansion in urban clusters creates pull for standardized undercounter units. SAMR enforcement of GB standards on imported equipment creates testing barriers for non-domestic manufacturers. Shanghai and Beijing commercial kitchen equipment markets show concentration of domestic fabrication capacity.
India
Institutional catering groups and quick-service chains generate demand for modular rack systems in Delhi-Mumbai urban corridors. BIS certification requirements constrain import velocity for European and North American vendors. Bangalore and Hyderabad hotel development pipelines specify premium installations with remote diagnostics capability.
United Arab Emirates
Integrated resort properties specify premium conveyor installations to minimize downtime during peak occupancy periods. MOHAP facility standards align with international health-code benchmarks for warewashing equipment. Dubai hospitality development clusters concentrate demand for built-in custom configurations.
Global Commercial Dishwashers Market Vendor Landscape
Global majors compete with regional champions across metallurgy partnerships and heat-recovery engineering capabilities. Market structure tilts toward consolidated supply in conveyor systems where capital intensity filters smaller fabricators, while undercounter segments retain fragmentation. Three archetypes dominate: integrated metallurgy specialists, modular subsystem providers, and heat-recovery engineering houses. Competitive moves concentrate on captive stainless steel supply arrangements and predictive maintenance platform development.
Within the integrated engineering tier, Hobart and MEIKO Maschinenbau exemplify divergent approaches to thermal-system architecture. Hobart occupies a position anchored in North American institutional procurement channels. MEIKO Maschinenbau represents European heat-recovery specialization. Electrolux Professional sits within the modular subsystem archetype, serving high-throughput cafeteria operators through configurable rack platforms.
| Leading Market Players |
|---|
| Hobart |
| Electrolux Professional |
| Winterhalter Gastronom GmbH |
| MEIKO Maschinenbau |
| Miele |
| The Middleby Corporation |
| Blakeslee |
| Champion Industries |
| Jackson WWS |
| Others |
Supply Flow & Price Mechanics
Captive metallurgy partnerships anchor supply positioning and pricing power for conveyor system manufacturers serving German hospital consortiums and U.S. federal procurement channels. Hobart's backward integration into stainless steel sourcing insulates margin stability against nickel and chromium volatility while compressing competitor pricing floors.
Pricing Analysis
Input-cost pass-through from austenitic stainless grades operates with 6-9 month lag structures, forcing manufacturers to absorb spot-market spikes before contractual repricing. Pricing stratifies across premium heat-recovery configurations, standard door-type installations, and economy undercounter units. Cost compression in economy tiers is intensifying because Chinese domestic fabricators are flooding Southeast Asian export markets. Quick-service chains in India exhibit highest price sensitivity, while German institutional buyers prioritize lifecycle operating cost over capital expenditure.
Supply Chain Analysis
Dual-sourcing requirements mandated by U.S. hospital systems and EU institutional procurement rules force qualification of redundant stainless steel suppliers across Germany, Italy, and South Korea. Component dependencies center on precision spray nozzles from German engineering houses, heat-exchanger assemblies from Scandinavian specialists, and control systems from Taiwanese electronics fabricators. Single-source vulnerability concentrates in heat-recovery module engineering where MEIKO Maschinenbau and two Nordic specialists dominate proprietary vapor-capture architectures. Distribution runs through manufacturer-direct channels for conveyor systems, while undercounter units move through foodservice equipment distributors with regional service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement specifications harden around EU Ecodesign Directive thresholds and EPA ENERGY STAR mandates that filter sub-premium equipment from institutional channels.
For Market Incumbents: Lock in captive stainless supply arrangements with German and Italian metallurgy partners before nickel volatility triggers margin compression. Prioritize heat-recovery engineering patent filings in Scandinavia where energy tariffs accelerate specification upgrades. Defend against emerging Chinese fabricators by accelerating predictive maintenance platform deployment to capture enterprise-wide service contracts from U.S. hospital systems and university dining consortiums. For New Entrants and Emerging Players: The mid-tier pricing gap between premium heat-recovery conveyor systems and economy undercounter units creates white-space for modular rack configurations with field-upgradable capacity. Target quick-service chain expansion across Indian urban corridors where BIS certification barriers filter established European competitors. Pursue OEM private-label partnerships with domestic Chinese fabricators seeking export market credibility without SAMR testing investment. For Investors and Strategic Acquirers: Roll-up economics work for regional heat-recovery engineering specialists because institutional procurement consolidation favors vendors with multi-site service capabilities and captive metallurgy relationships. Five-to-ten year viability hinges on F-Gas Regulation compliance positioning for heat-pump-assisted architectures. Watch refrigerant-transition timelines in Sweden and Finland as inflection indicators for thermal-system redesign capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Recovery Engineering Patent Expansion | Captures value from EU Ecodesign Directive compliance requirements in German institutional procurement. |
| Predictive Maintenance Platform Development | Enables recurring revenue streams from U.S. hospital systems negotiating enterprise-wide service contracts. |
| Stainless Steel Supply Integration | Insulates margin stability against nickel volatility through captive metallurgy partnerships in Italy. |
| Modular Rack System Configuration | Addresses Indian quick-service chain demand for field-upgradable capacity without full replacement cycles. |
| F-Gas Regulation Compliance Investment | Positions for refrigerant-transition timelines in Scandinavian markets with accelerating heat-pump specifications. |
Methodological Framework
Direct dialogue with foodservice equipment procurement directors, commercial kitchen maintenance managers, OEM supply chain executives, and institutional catering group technical officers grounded qualitative findings. Secondary validation drew from EPA ENERGY STAR certification databases, EU Ecodesign Directive implementing measures, SAMR GB standard filings, and customs trade data for stainless steel alloy imports. Bottom-up and top-down triangulation reconciled equipment shipment volumes with end-use facility expansion pipelines.
Bottom-up modeling tracked unit economics across product architectures while top-down analysis calibrated aggregate market expansion against foodservice operator capital expenditure surveys. Segmentation dimensions included product type, end-use intensity, sanitizing technology, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and specification upgrade trajectories. Forecast inputs incorporated utility tariff escalation curves and municipal water consumption cap enforcement patterns.
Caveats apply where nickel price volatility, F-Gas Regulation phase-down acceleration, or SAMR certification timeline compression could materially shift the outlook. Deviation in EU institutional procurement consolidation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Used Restaurant Equipment Market
Food Service Equipment
UK Countertop Ice Makers Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Catering Equipment Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
North America and Europe Vending Machine Market