
 Commercial Foodservice Equipment Market | 2026-2036
Commercial Foodservice Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Foodservice Equipment Market Analytics
NSF/ANSI Standard 4 certification for commercial cooking equipment is unwinding the competitive landscape, as smaller fabricators without accredited testing capabilities lose access to institutional contracts. Middleby Corporation leverages vertical integration across its thermal technology portfolio to sustain margin control in premium oven categories. Ali Group anchors its position through geographic diversification across European and Asian manufacturing footprints, while Rational AG specializes in cloud-connected combi-steamer systems that dominate high-throughput institutional kitchens.
Commercial foodservice equipment encompasses electrically or gas-powered appliances designed for commercial food preparation, storage, and service, typically constructed from 304-grade stainless steel with insulation ratings exceeding 150°F surface temperature differentials to meet occupational safety thresholds. These systems enable standardized throughput in high-volume environments where residential-grade durability would fail under continuous duty cycles. Ovens and refrigerators capture the dominant share of replacement demand as operators prioritize energy recovery and precision temperature management. Fryers represent the fastest-growing equipment category among food trucks and quick-service formats where oil filtration automation reduces labor overhead. Griddles retain stable demand in diner and breakfast-focused chains where flat-top cooking speed determines table turnover economics.
The U.S. Department of Energy enforces minimum efficiency standards for commercial refrigerators and freezers under 10 CFR 431, while the EPA's ENERGY STAR program creates procurement preference hierarchies in federal and state institutional buying. The EU Ecodesign Directive and F-Gas Regulation constrain refrigerant selection and insulation foam chemistry, pushing manufacturers toward hydrocarbon and CO2-based cooling architectures. Stakeholders must monitor how pending amendments to commercial kitchen ventilation codes in California and New York reshape hood and fire suppression system bundling requirements.
Market Dynamics
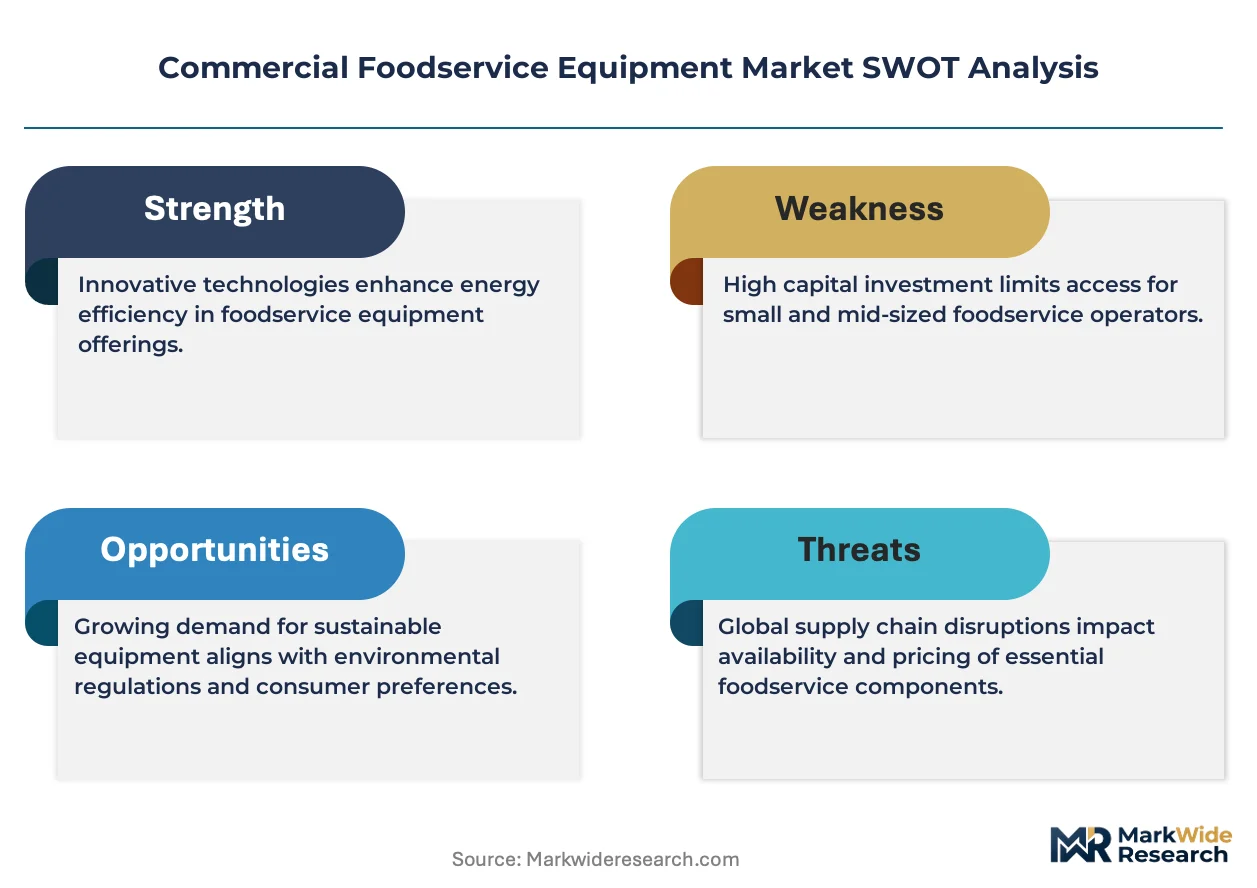
The U.S. Department of Energy's 10 CFR 431 efficiency mandates are forcing thermal system redesigns across refrigerator and freezer categories, compressing development timelines while elevating R&D spend thresholds for market access.
Growth Catalysts
- Ghost Kitchen Expansion:Full-service restaurant operators in the United States are doubling kitchen footprints to accommodate delivery-only production lines, generating incremental demand for compact, high-throughput cooking equipment.
- F-Gas Phase-Down:The EU F-Gas Regulation is accelerating hydrocarbon and CO2 refrigeration system adoption, creating replacement cycles for institutional buyers seeking compliant cold-storage infrastructure.
- Combi-Oven Technology:Precision-engineered combi-steamer systems are displacing conventional ovens in German institutional catering, driven by labor cost reduction and menu standardization imperatives.
Market Restraints
- 304-Grade Stainless Input Volatility:Nickel and chromium price swings in commodity markets are compressing fabricator margins, particularly for mid-scale equipment producers without long-term supply agreements.
- NSF/ANSI 4 Certification Barriers:The accreditation cost structure and testing timeline are excluding smaller fabricators from institutional procurement channels, concentrating supply among capital-rich incumbents.
- Electrification Infrastructure Gaps:Gas-to-electric equipment transitions in older commercial buildings face panel capacity constraints and utility upgrade delays, slowing replacement velocity in secondary markets.
Strategic Opportunities
- Food Truck Electrification:Battery-powered cooking and refrigeration systems are opening addressable demand among mobile food operators seeking generator-independent operations and municipal emission compliance.
- Cloud-Connected Asset Management:IoT-enabled predictive maintenance and remote diagnostics are creating recurring revenue streams for OEMs serving high-throughput institutional kitchens with uptime-critical operations.
- California Ventilation Code Amendments:Pending hood and fire suppression bundling requirements are reshaping specification standards, favoring integrated system suppliers over component-only vendors.
Industry Challenges
- Refrigerant Technician Scarcity:Hydrocarbon and CO2 system servicing requires specialized certification pathways that lag equipment deployment rates, constraining aftermarket service network expansion.
- Legacy Control System Integration:Cloud-connected combi-ovens and smart refrigerators face interoperability barriers with existing kitchen management platforms, complicating upgrade decisions for multi-site operators.
- Supply Chain Reconfiguration Costs:Nearshoring thermal component production from Asian manufacturing footprints to European or North American facilities demands capital outlays that strain mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Foodservice Equipment Market |
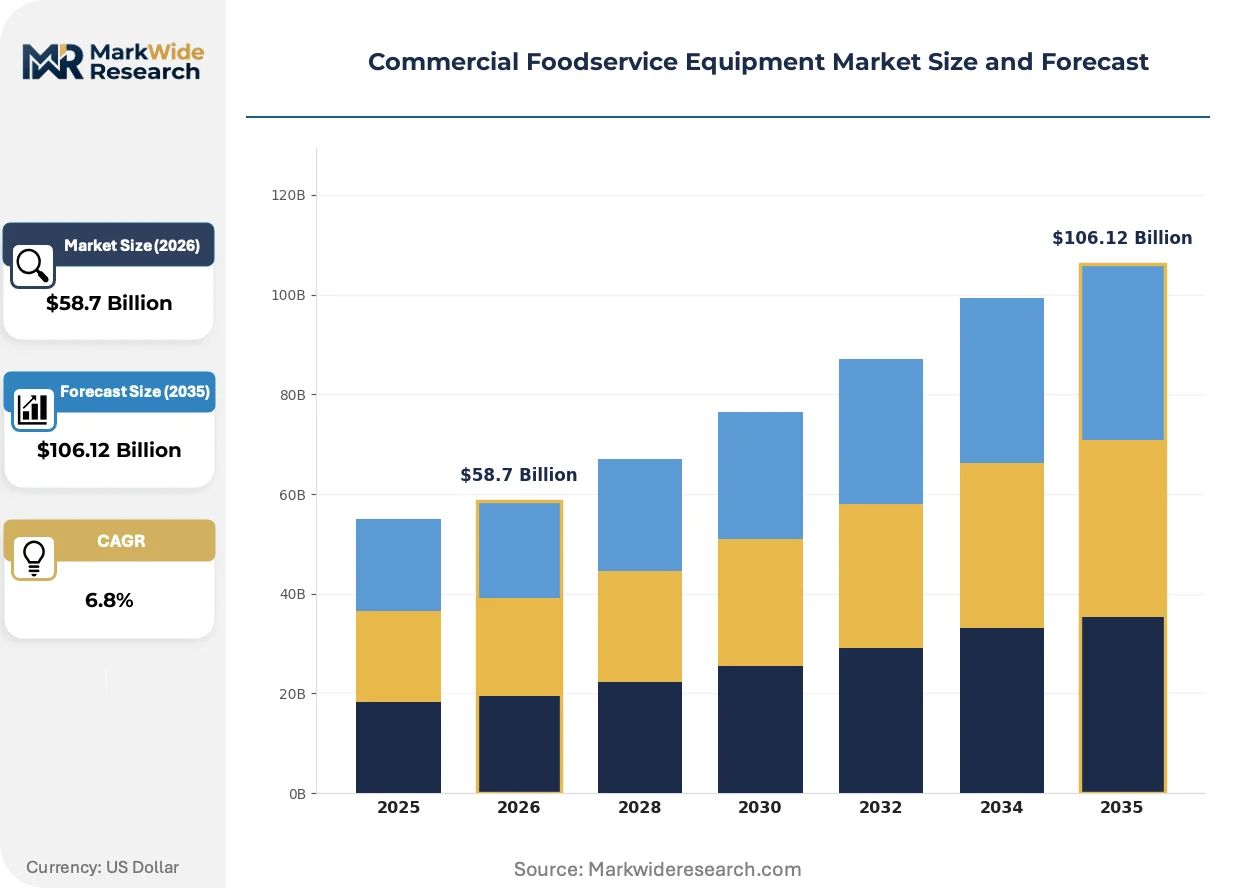
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Ovens, Refrigerators, Fryers, Griddles End User: Restaurants, Cafes, Caterers, Food Trucks Distribution Channel: Online, Retail, Direct Sales, Wholesalers Application: Food Processing, Cooking, Storage, Display |
| Companies Covered | Middleby Corporation, ITW Food Equipment Group, Ali Group, Welbilt, Rational AG, Electrolux Professional, Alto-Shaam, Hoshizaki Corporation, Henny Penny Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Foodservice Equipment Market Evolving Landscape
Equipment intelligence and energy architecture are converging to redefine competitive positioning, with connectivity and thermal efficiency emerging as the primary axes of product differentiation.
Induction cooking technology is fragmenting the traditional gas-dominated landscape in high-throughput kitchens. Fast-casual chains and institutional caterers in the United States are accelerating adoption to meet municipal electrification mandates and reduce ventilation infrastructure costs. The technology is fragmenting specification standards, forcing hood and fire suppression suppliers to redesign systems around lower thermal plume characteristics.
The EU Ecodesign Directive's expanded scope for commercial refrigeration is mandating minimum efficiency thresholds and refrigerant global warming potential limits. Manufacturers are reengineering insulation foam chemistry and compressor architectures to maintain market access. Cold-storage equipment categories face the steepest compliance curves, with German and French institutional buyers already screening procurements against 2027 benchmark requirements.
After-sales service unbundling is disrupting traditional OEM-captive maintenance relationships. Third-party service aggregators and independent technician networks are capturing preventive maintenance contracts through outcome-based pricing models. This shift is most visible in the United States, where multi-site restaurant operators are consolidating vendor relationships across equipment brands to reduce administrative overhead and standardize uptime guarantees.
Commercial Foodservice Equipment Market Segmentation
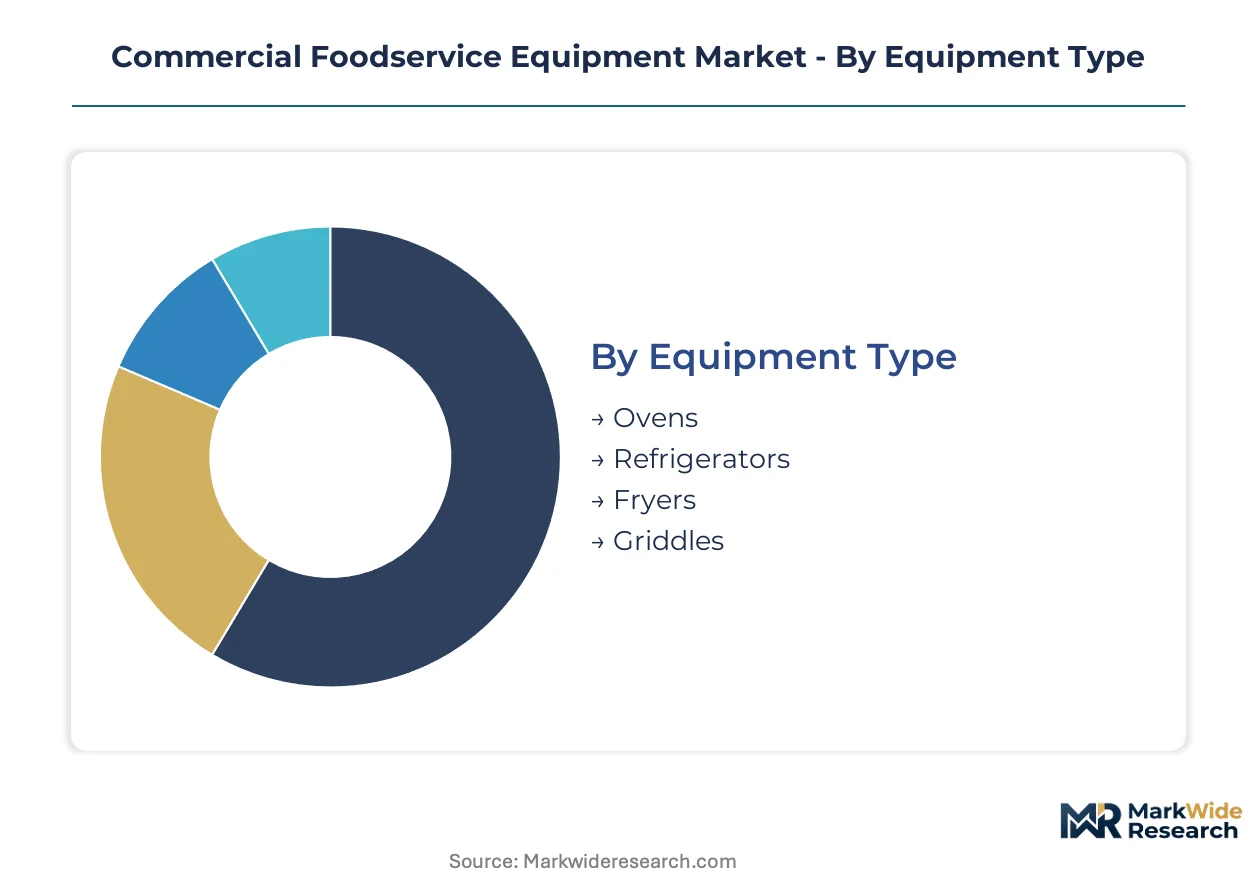
Equipment substitution pressures reshape procurement hierarchies across the commercial foodservice landscape. Operators prioritize segments where energy recovery and labor automation deliver measurable throughput economics.
Equipment Type:
Combi-steamer technology is displacing conventional thermal equipment in high-throughput environments, intensifying substitution pressure on legacy oven architectures.
- Ovens:Encompass convection, deck, and combi-steamer configurations with precision humidity control and multi-stage programming. German institutional kitchens drive specification upgrades as labor cost reduction mandates accelerate combi-oven deployment.
- Refrigerators:Include reach-in, walk-in, and undercounter cold-storage systems with hydrocarbon or CO2 refrigerant architectures. The EU F-Gas Regulation forces replacement cycles across French and Italian institutional buyers seeking compliant infrastructure.
- Fryers:Gas and electric models with automated oil filtration and temperature recovery systems. Food truck operators in California favor compact electric units for municipal emission compliance.
- Griddles:Flat-top cooking surfaces in gas, electric, or induction configurations. Breakfast-focused chains retain stable demand where surface thermal mass determines ticket speed.
Ovens retain volume leadership; fryers hold the steepest expansion curve.
End User:
Customer procurement scale determines service model attachment rates and preventive maintenance contract values.
- Restaurants:Full-service and quick-service operators with multi-site standardization requirements. Ghost kitchen expansion in the United States doubles equipment density per location.
- Cafes:Limited-menu formats prioritizing compact footprint and rapid beverage-cooking integration. Urban real estate costs drive specification toward undercounter refrigeration and ventless cooking.
- Caterers:Mobile and institutional foodservice operators with event-driven capacity spikes. German institutional catering facilities outpace broader European replacement rates for precision-engineered thermal systems.
- Food Trucks:Mobile operators requiring generator-independent electrical systems and municipal emission compliance. Battery-powered refrigeration and induction cooking open addressable demand in California and New York regulatory environments.
Restaurants dominate installed base; food trucks are climbing the fastest.
Distribution Channel:
Channel economics fragment based on specification complexity and installation service bundling requirements.
- Online:Digital procurement platforms for standardized smallwares and replacement components. Independent restaurant operators reduce administrative overhead through consolidated vendor relationships.
- Retail:Physical showrooms and dealer networks with demonstration capabilities. Mid-scale operators rely on tactile evaluation for first-time equipment purchases.
- Direct Sales:Manufacturer-captive sales organizations serving national accounts and institutional buyers. Multi-site operators negotiate outcome-based uptime guarantees across equipment brands.
- Wholesalers:Distributor networks with regional inventory positioning and technician certification programs. Hydrocarbon and CO2 system deployment lags specialized service network expansion.
Direct sales capture premium specification value; online channels gain share fastest in replacement parts.
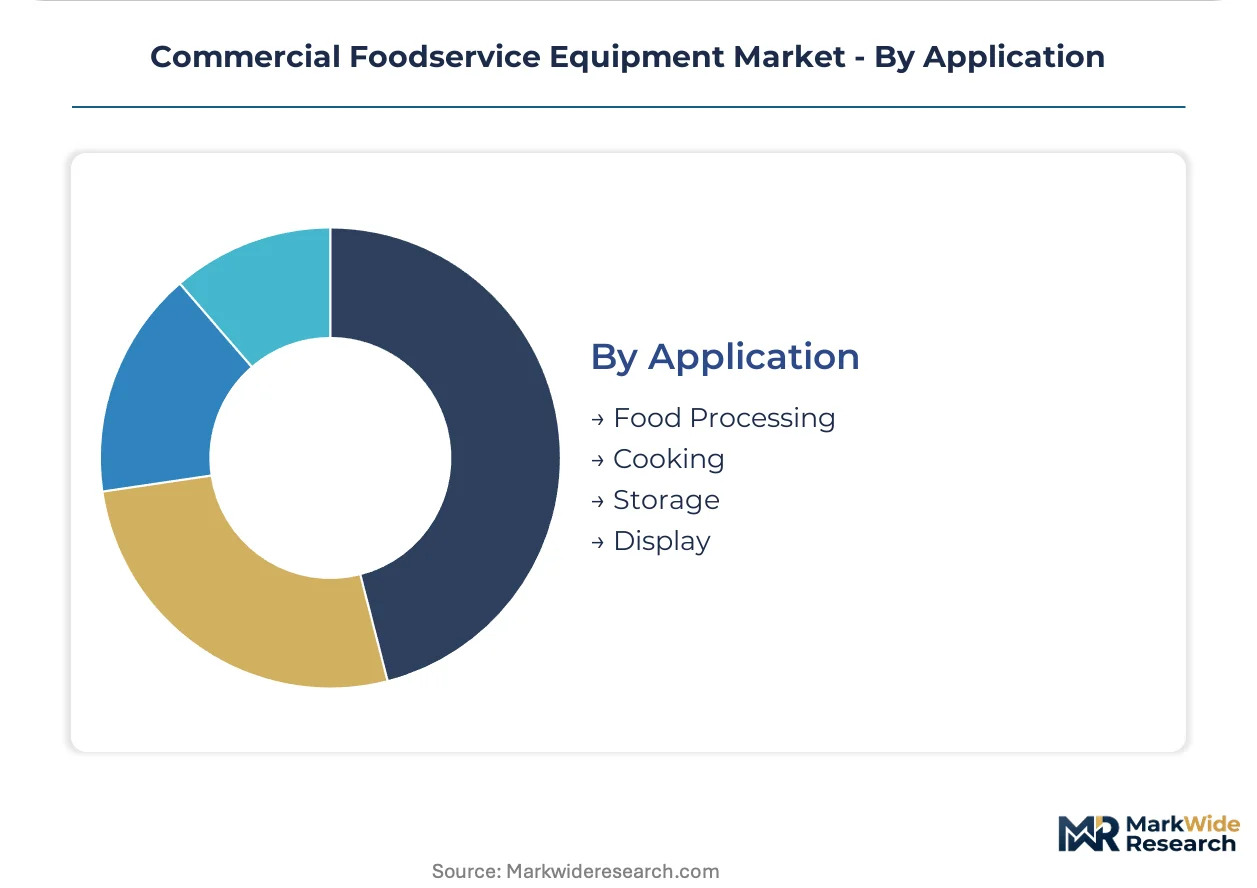
Application:
Functional workflow positioning determines equipment integration depth with kitchen management platforms.
- Food Processing:Preparation equipment including slicers, mixers, and food processors with safety interlocks. NSF/ANSI Standard 4 certification requirements exclude smaller fabricators from institutional contracts.
- Cooking:Thermal equipment generating direct heat transfer to food products. Induction technology fragments specification standards, forcing hood and fire suppression redesign.
- Storage:Cold-holding and dry storage systems with temperature monitoring and alarm integration. The U.S. Department of Energy's 10 CFR 431 mandates compress development timelines for thermal system redesigns.
- Display:Merchandising equipment combining temperature control with visual presentation. Quick-service formats prioritize this category for queue management and impulse transaction capture.
Cooking commands the largest equipment spend; storage faces the steepest regulatory compliance curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European distribution efficiency for commercial refrigeration equipment, while the Union Pacific rail network connects U.S. manufacturing clusters to institutional buyers across the interior.
United States
Ghost kitchen expansion in urban centers drives incremental demand for compact, high-throughput cooking systems. The Department of Energy's 10 CFR 431 efficiency mandates compress thermal system redesign timelines. Chicago's manufacturing corridor anchors fabrication capacity for institutional-grade combi-oven systems serving national restaurant chains.
Germany
Precision-engineered combi-steamer installations in institutional catering facilities outpace broader European replacement rates. The EU F-Gas Regulation accelerates hydrocarbon refrigeration system adoption across cold-storage infrastructure. Bavaria's industrial cluster concentrates thermal technology R&D for cloud-connected kitchen equipment serving high-throughput operators.
China
Rapid urbanization and quick-service restaurant proliferation generate volume demand for standardized cooking equipment. MIIT energy efficiency standards reshape domestic manufacturing specifications for commercial thermal systems. The Yangtze River Delta manufacturing belt scales production of 304-grade stainless components for export markets.
Japan
Space-constrained urban foodservice formats prioritize compact, multi-functional equipment with minimal footprint. METI commercial appliance efficiency guidelines drive induction technology penetration in high-throughput kitchens. The Kansai region's precision manufacturing base supplies advanced control systems for intelligent cooking equipment.
India
Organized foodservice expansion and cloud kitchen proliferation create addressable demand for durable, cost-optimized equipment. BIS certification requirements for commercial cooking appliances reshape procurement standards for institutional buyers. Maharashtra's industrial corridor scales fabrication capacity for mid-tier thermal equipment serving domestic quick-service chains.
Commercial Foodservice Equipment Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification capability dimensions. The market structure concentrates around capital-rich incumbents with accredited testing infrastructure, while mid-scale fabricators face exclusion from institutional procurement channels. Three archetypes dominate: vertically integrated thermal technology portfolios, geographic diversification platforms, and cloud-connected system specialists. Competitive moves center on M&A for certification capability acquisition and strategic partnerships for aftermarket service network expansion.
Within the listed-leader tier, Middleby Corporation and Rational AG exemplify contrasting strategic positions, while Ali Group occupies a position as a geographic diversification platform spanning European and Asian manufacturing footprints. These three anchors represent the capital intensity and certification capability thresholds that define institutional market access, with their collective positioning illustrating how thermal technology control and service infrastructure scale determine competitive viability in regulated procurement environments.
| Leading Market Players |
|---|
| Middleby Corporation |
| ITW Food Equipment Group |
| Ali Group |
| Welbilt |
| Rational AG |
| Electrolux Professional |
| Alto-Shaam |
| Hoshizaki Corporation |
| Henny Penny Corporation |
| Others |
Value Network & Pricing Analysis
Hydrocarbon refrigerant substitution for legacy F-gas architectures simultaneously redraws component sourcing geography toward German and Japanese compressor specialists while compressing margin structures for mid-tier cold-storage equipment fabricators lacking long-term supply agreements with certified foam chemistry suppliers.
Pricing Analysis
Certification level creates the primary spread between institutional-grade and commercial-tier equipment, with NSF/ANSI 4-accredited thermal systems commanding substantial premiums over non-certified alternatives in federal and state procurement channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by energy efficiency tier, after-sales service bundling, and geographic delivery logistics. Cost compression in the mid-tier segment is intensifying because nickel and chromium commodity volatility erodes fabricator margins. Quick-service restaurant chains exhibit the highest price sensitivity due to standardized equipment refresh cycles, while German institutional caterers prioritize performance specifications over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate among large-scale OEMs serving national restaurant chains, while strategic stockpiling of 304-grade stainless steel persists among fabricators with captive rolling mill relationships in China's Yangtze River Delta. Component concentration centers on Germany for precision thermal controls, Italy for combustion systems, and China for stainless steel fabrication. Raw material dependencies rest on Indonesian nickel ore, South African chromium, and specialized refrigerant gases from Japanese chemical producers. Single-source vulnerability in hydrocarbon compressor supply creates exposure for North American cold-storage equipment assemblers. Distribution runs through regional wholesaler networks with certified technician capabilities, though direct sales channels capture premium specification value in multi-site institutional contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ghost kitchen proliferation fragments demand across compact, high-throughput equipment categories, creating specialized niches for agile fabricators capable of rapid specification iteration outside legacy institutional procurement channels.
For Market Incumbents: Fortify certification infrastructure investments to maintain NSF/ANSI 4 accreditation as smaller competitors face exclusion from federal procurement channels. Deepen backward integration into thermal control component production to offset commodity volatility in 304-grade stainless inputs. Prioritize captive aftermarket service network expansion to capture recurring revenue streams as third-party aggregators erode traditional OEM maintenance relationships.
For New Entrants and Emerging Players: Aftermarket service coverage gaps in hydrocarbon and CO2 refrigeration systems present addressable white space where incumbent technician certification lags equipment deployment rates. Food truck electrification in California and New York regulatory environments offers the most penetrable segment for battery-powered cooking and refrigeration specialists. Pursue municipal fleet procurement relationships as the primary go-to-market angle, leveraging emission compliance mandates to displace generator-dependent legacy equipment.
For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors consolidation plays around certification capability and geographic manufacturing footprint diversification. Long-term viability over the extended analysis window hinges on exposure to institutional procurement channels with mandated efficiency standards. Target acquisition profiles center on mid-scale fabricators with established testing laboratory relationships and regional service infrastructure. Watch for F-Gas Regulation amendment timing as the critical inflection signal for refrigeration system replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Laboratory Acquisition | NSF/ANSI 4 testing capability secures institutional procurement channel access against excluded competitors. |
| Hydrocarbon Refrigeration Scale-Up | EU F-Gas compliance positions cold-storage portfolios for mandated replacement cycles across French and German buyers. |
| Cloud-Connected Platform Launch | IoT-enabled predictive maintenance creates recurring revenue attachment for Rational AG-style system specialists. |
| Regional Service Network Expansion | Technician certification programs for CO2 systems address aftermarket scarcity constraining equipment deployment velocity. |
| Compact Equipment Portfolio Development | Ghost kitchen footprint constraints drive specification demand for high-throughput, space-optimized thermal systems. |
Research Methodology
Cross-validation between primary interviews with commercial kitchen equipment procurement directors, aftermarket service network managers, and institutional catering facility operators anchors the qualitative findings against secondary validation from U.S. Department of Energy 10 CFR 431 filings, EU Ecodesign Directive implementation reports, and SEC disclosures from listed thermal technology manufacturers. Bottom-up equipment shipment analysis triangulates against top-down institutional spending estimates across restaurant, healthcare, and education verticals.
Sensitivity analysis around refrigerant phase-down timelines and efficiency standard implementation schedules shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment type, end-user category, distribution channel, and application workflow positioning. CAGRs derive from replacement cycle velocity analysis, regulatory compliance-driven upgrade timelines, and penetration rate assumptions for connected equipment platforms. Forecast inputs incorporate nickel and chromium commodity price trajectory scenarios and municipal electrification mandate adoption curves.
Forecasts assume regulatory continuity in U.S. Department of Energy efficiency regimes and EU F-Gas Regulation phase-down schedules; material policy shifts would require re-modeling of replacement cycle timing and cold-storage equipment demand trajectories. Revision becomes warranted when hydrocarbon refrigerant technician certification expansion crosses thresholds that eliminate aftermarket service bottlenecks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Global QSR Food Service Equipment Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Reach-In Refrigerators Market