
 Automatic Popcorn Machine Market | 2026-2036
Automatic Popcorn Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Popcorn Machine Market Insights
The capital-intensity divergence between automated kettle systems and basic countertop units is redrawing competitive tiers in the automatic popcorn machine landscape. Cretors leverages its century-long manufacturing heritage to sustain premium positioning in high-volume cinema installations. Gold Medal Products anchors the mid-market through broad distribution across concession channels. Paragon International differentiates through specialized event-rental configurations that occupy a defensible niche.
An automatic popcorn machine is a thermostatically controlled appliance that heats kernels to approximately 450°F via electric elements or gas burners, using oil or forced hot air to achieve pressure-driven expansion for commercial or residential foodservice output. Commercial-grade units with 8-ounce and 12-ounce kettle capacities dominate theater and concession installations where throughput requirements exceed 200 servings hourly. Hot air technology is gaining fastest in health-oriented segments by eliminating oil from the popping process, though oil-popped configurations retain stronger margin pools in traditional entertainment venues. Countertop formats serve homeowner demand with compact 1-ounce and 4-ounce capacities that sacrifice batch size for kitchen integration.
NSF International standards and FDA food-contact surface regulations govern equipment certification for commercial deployment across the United States, while CE marking under EU machinery directives shapes market access for European imports. California's Title 20 appliance efficiency standards and emerging DOE commercial kitchen equipment rules are tightening energy consumption benchmarks that manufacturers must satisfy for legal sale. Stakeholders should monitor evolving efficiency mandates and oil-free certification pathways that will determine which technology configurations retain channel placement in regulated environments.
Market Dynamics
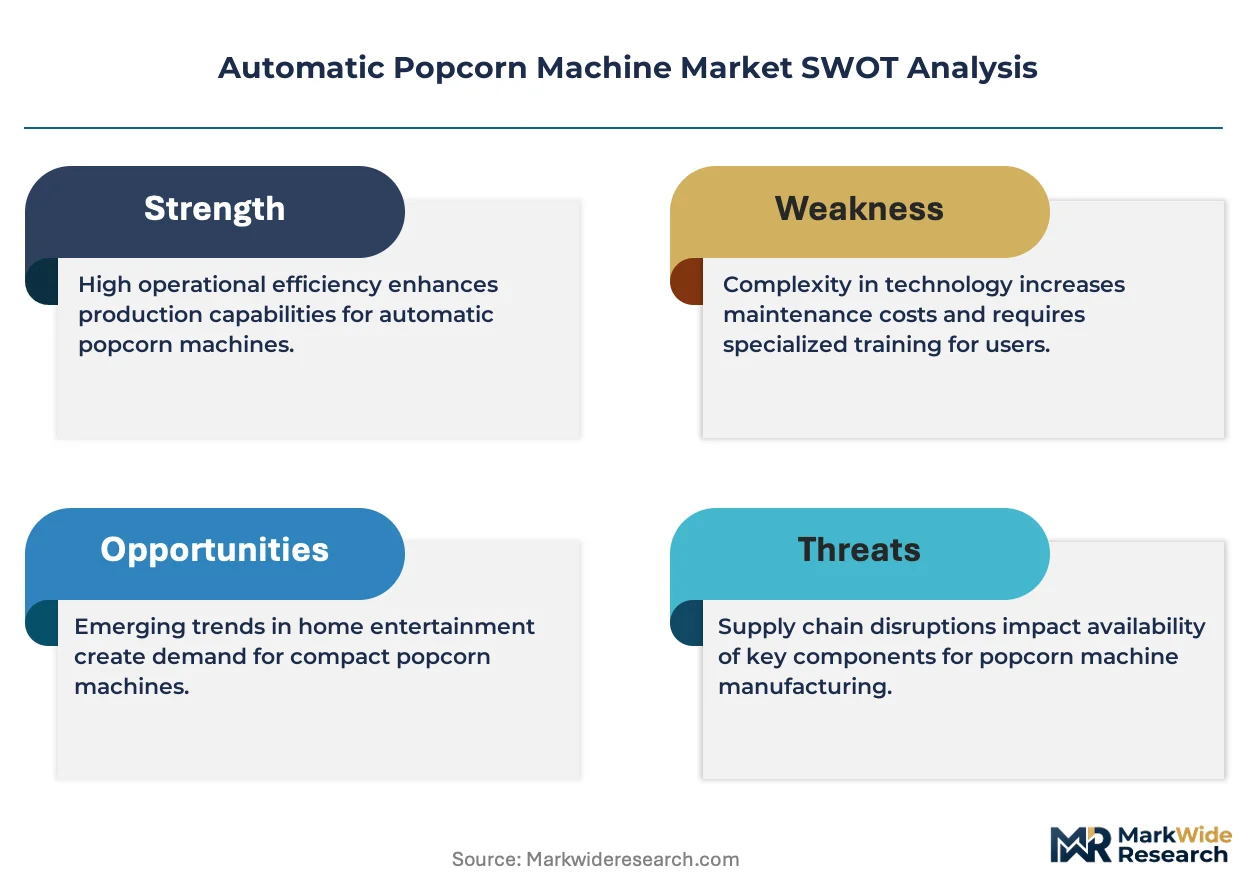
The automatic popcorn machine market is experiencing structural pressure from energy efficiency mandates and material certification requirements that are compressing replacement cycles and elevating capital thresholds for commercial deployment.
Growth Catalysts
- NSF International certification standards:Food-grade stainless steel requirements in the United States are accelerating equipment turnover as older units fail compliance audits, creating replacement demand across cinema and concession channels.
- Multiplex self-service formats:Theater operators in California, Texas, and Florida are installing automated kettle systems to reduce labor costs and accelerate concession throughput during peak attendance windows.
- Hot air popping technology:Health-oriented venues are adopting oil-free configurations to serve wellness-focused consumers, expanding addressable demand beyond traditional entertainment settings.
Market Restraints
- Food-grade stainless steel input costs:Volatility in nickel and chromium prices compresses manufacturer margins and elevates end-user equipment pricing, particularly for high-capacity kettle systems.
- CE marking complexity:European machinery directive compliance creates friction for North American manufacturers seeking EU market access, lengthening product launch timelines.
- Countertop unit substitution:Compact residential machines are capturing home entertainment demand that might otherwise flow to commercial rental channels, constraining event-service revenue pools.
Strategic Opportunities
- Japan cinema modernization:Aging theater infrastructure in Tokyo and Osaka corridors presents replacement demand for automated concession equipment with integrated payment systems.
- DOE commercial kitchen efficiency rules:Emerging federal energy standards will mandate next-generation heating elements and insulation, creating technology upgrade cycles for installed base replacement.
- IoT-enabled predictive maintenance:Sensor-integrated kettle systems are converging with cloud-based fleet management platforms to offer subscription service models to theater chains.
Industry Challenges
- NSF certification timeline compression:Accelerated testing protocols for modified equipment designs are straining manufacturer engineering resources and delaying product releases.
- Legacy gas-to-electric retrofit complexity:Theater operators seeking to comply with California Title 20 standards face integration challenges with existing ventilation and electrical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Popcorn Machine Market |
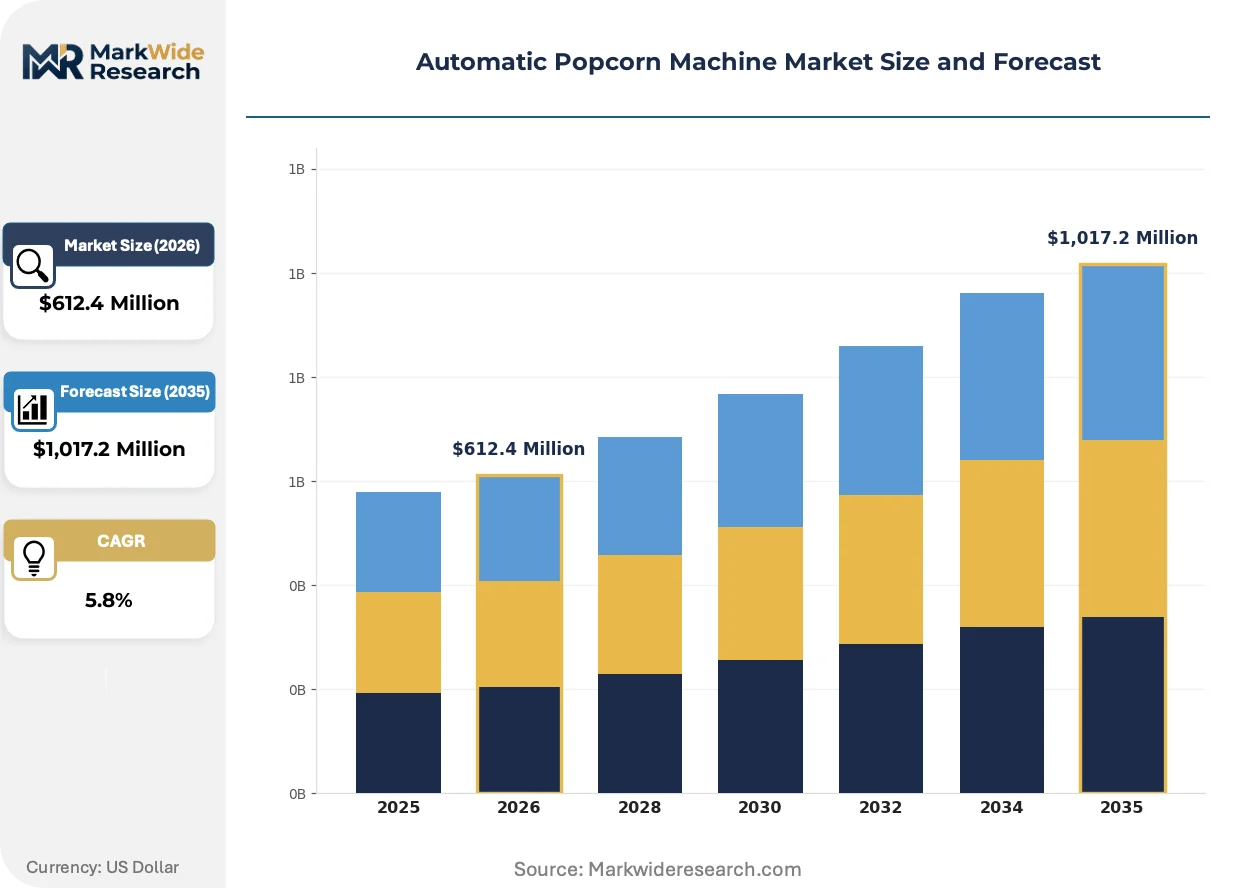
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Commercial, Household, Industrial End User: Theaters, Concessions, Homeowners, Events Technology: Electric, Manual, Oil-Popped, Hot Air Capacity: 1 Ounce, 4 Ounces, 8 Ounces, 12 Ounces |
| Companies Covered | Cretors, Gold Medal Products, Paragon International, Benchmark USA, Great Northern Popcorn Company, SunZee, Hamilton Beach, Cuisinart, West Bend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Popcorn Machine Market Trends and Innovations
Equipment intelligence and health-conscious consumption patterns are converging to reshape product development priorities and channel economics across commercial and residential segments.
Forced hot air popping technology is supplanting oil-based kettle systems in health-oriented venues such as corporate cafeterias and school foodservice operations. Wellness-focused procurement teams are specifying oil-free configurations to eliminate trans fat concerns and simplify cleaning protocols. This transition is compressing margin pools for traditional oil-popped equipment while opening premium pricing tiers for air-popped alternatives with flavor-dispensing modules.
California's Title 20 appliance efficiency standards are mandating reduced standby power consumption and improved heating element thermal transfer coefficients for commercial foodservice equipment. Manufacturers must redesign kettle insulation and control systems to achieve compliance certification. Theater operators in the state are prioritizing compliant models to avoid penalties and qualify for utility rebate programs.
Self-service concession formats are displacing full-service counter models in multiplex deployments, altering equipment specifications toward automated dispensing and integrated payment acceptance. Theater chains are unbundling equipment procurement from service contracts, shifting toward direct manufacturer relationships. This pattern is most visible in Germany, where labor cost pressures have accelerated unattended kiosk adoption in cinema lobbies.
Automatic Popcorn Machine Market Segmentation
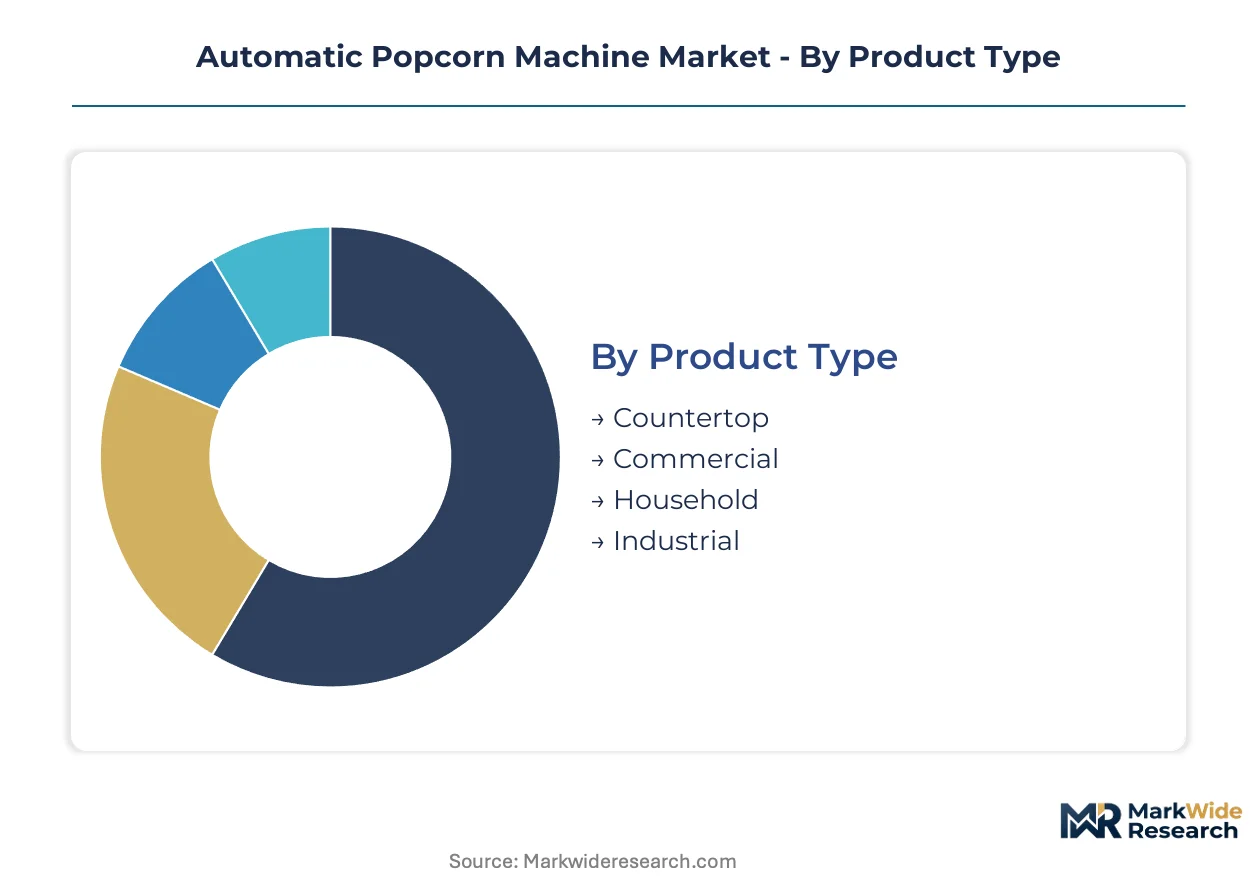
Automatic popcorn machine segmentation reveals divergent equipment specifications across venue types and throughput requirements. Product configuration choices directly determine compliance obligations, energy consumption profiles, and replacement cycle timing.
Product Type:
Commercial-grade equipment dominates export flows to theater chains across Germany and Japan, while countertop and household units serve primarily domestic retail channels in the United States.
- Commercial:High-volume kettle systems with 8-ounce and 12-ounce capacities serve multiplex operators in California, Texas, and Florida corridors. NSF certification requirements accelerate replacement demand as aging units fail food-contact surface audits.
- Countertop:Compact 1-ounce and 4-ounce configurations sacrifice batch throughput for kitchen integration flexibility. Demand concentrates in residential entertainment settings where space constraints override serving volume priorities.
- Household:Entry-level electric units target home theater enthusiasts with simplified operation and reduced price points. Sales volume peaks during holiday gift seasons through mass retail distribution.
- Industrial:Continuous-feed production systems supply packaged popcorn manufacturers with automated kernel handling and flavor coating integration. Food-grade stainless steel construction meets FDA food-contact regulations for co-packing operations.
Commercial holds the largest share; momentum sits with countertop units capturing home entertainment demand.
End User:
Theater operators command premium pricing tiers through volume procurement contracts, while event rental channels face margin compression from residential substitution.
- Theaters:Multiplex operators in the United States deploy automated kettle systems with integrated payment acceptance to accelerate concession throughput during peak attendance windows. Self-service format adoption reduces labor cost exposure.
- Concessions:Stadium and arena foodservice operators specify high-capacity equipment with rapid recovery heating elements. California Title 20 efficiency standards mandate compliant models for new installations.
- Homeowners:Residential demand favors compact countertop formats with simplified cleaning protocols. Hot air technology gains preference among wellness-focused consumers eliminating oil from preparation.
- Events:Rental service providers deploy portable kettle systems for temporary installations at festivals and corporate gatherings. Seasonal revenue concentration creates working capital intensity for equipment fleet operators.
Theaters anchor revenue concentration; events demonstrate the steepest expansion trajectory as experiential entertainment formats proliferate.
Technology:
Electric heating configurations align with California efficiency mandates, while gas burner systems face retrofit complexity in legacy theater infrastructure.
- Hot Air:Forced convection systems eliminate oil from the popping process, serving health-oriented venues including corporate cafeterias and school foodservice operations. Wellness procurement teams specify oil-free configurations to simplify cleaning protocols.
- Oil-Popped:Traditional kettle systems retain stronger margin pools in entertainment venues where flavor authenticity commands consumer preference. Nickel and chromium price volatility compress manufacturer margins on food-grade stainless steel construction.
- Electric:Thermostatically controlled heating elements dominate new installations with precise temperature management and reduced ventilation requirements. DOE commercial kitchen efficiency rules will mandate next-generation thermal transfer coefficients.
- Manual:Hand-cranked kettle systems persist in specialty retail and educational demonstration settings. Limited throughput relegates this configuration to niche heritage and craft positioning.
Oil-popped retains the largest installed base; hot air technology gains share fastest among health-conscious procurement specifications.
Capacity:
Throughput requirements stratify equipment selection, with 8-ounce and 12-ounce systems commanding premium positioning against compact residential alternatives.
- 8 Ounces:Mid-capacity kettle systems balance batch size with recovery speed for theater operators serving 200-plus servings hourly. This specification dominates multiplex concession retrofits across the United States.
- 12 Ounces:Maximum throughput configurations serve high-attendance venues with continuous production capability. Equipment footprint and ventilation requirements limit deployment flexibility.
- 4 Ounces:Reduced-capacity units target specialty concessions and secondary serving locations with moderate volume requirements. Price positioning enables broader channel penetration.
- 1 Ounce:Minimal batch sizes serve residential countertop applications and single-serve demonstration purposes. Limited commercial relevance outside home entertainment segments.
8-ounce systems hold the largest share; 12-ounce configurations climb fastest as theater operators maximize throughput per labor hour.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Theater chains in Germany and Japan absorb premium equipment costs for labor savings, while price-sensitive operators in emerging markets prioritize basic functionality over connected features and certification tiers.
United States
Multiplex operators across California, Texas, and Florida corridors drive replacement demand as NSF certification requirements accelerate equipment turnover. FDA food-contact surface regulations govern commercial deployment, with California's Title 20 appliance efficiency standards mandating reduced standby power consumption. Los Angeles and Dallas-Fort Worth metro areas concentrate self-service concession retrofits.
Germany
Labor cost pressures in cinema lobbies accelerate unattended kiosk adoption, with theater chains unbundling equipment procurement from service contracts. CE marking under EU machinery directives shapes market access for imported equipment, creating compliance friction for non-European manufacturers. Munich and Berlin corridors lead multiplex modernization programs.
Japan
Aging theater infrastructure in Tokyo and Osaka corridors presents replacement demand for automated concession equipment with integrated payment systems. METI efficiency guidelines influence procurement specifications for commercial kitchen equipment. Kanto and Kansai regions concentrate cinema chain consolidation activity.
Canada
Health Canada regulations align with FDA food-contact standards, enabling cross-border equipment certification reciprocity for US manufacturers. Provincial energy efficiency programs in Ontario and British Columbia incentivize equipment upgrades. Toronto and Vancouver metro areas anchor theater chain expansion.
Australia
TGA-aligned food safety standards govern commercial equipment deployment, with state-level energy efficiency programs varying across jurisdictions. Sydney and Melbourne corridors concentrate multiplex operator procurement activity. Seasonal event rental demand creates secondary equipment utilization cycles.
Automatic Popcorn Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with century-long manufacturing heritage conferring pricing power in high-volume cinema installations. The mid-market anchors through broad distribution across concession channels, while event-rental specialists occupy defensible niches through portable configurations. Strategic moves concentrate on direct manufacturer relationships with theater chains and technology licensing for IoT-enabled fleet management platforms.
Within the heritage-manufacturing tier, Cretors represents premium positioning sustained through cinema installation scale. Gold Medal Products Co. exemplifies mid-market breadth across concession channels. Paragon International occupies a position within specialized event-rental configurations. These three anchors illustrate how competitive positioning stratifies across equipment specification tiers rather than geographic coverage alone.
| Leading Market Players |
|---|
| Cretors |
| Gold Medal Products |
| Paragon International |
| Benchmark USA |
| Great Northern Popcorn Company |
| SunZee |
| Hamilton Beach |
| Cuisinart |
| West Bend |
| Others |
Pricing and Supply Chain Analysis
Kettle capacity utilization rates above 80% in high-volume cinema installations create scale economies that compress per-unit manufacturing costs and establish price floors for mid-market competitors. Food-grade stainless steel input concentration in Chinese and Indian foundries concentrates bargaining power among raw material processors, while NSF certification requirements in the United States elevate compliance premiums that tier equipment pricing across commercial and residential channels.
Pricing Analysis
After-sales service contracts and replacement parts revenue drive lifetime value in commercial installations, with theater chains negotiating multi-year maintenance agreements alongside initial equipment procurement. Three-tier pricing structure across premium, standard, and economy levels separates heritage manufacturers with cinema heritage from mid-market concessionaires and entry-level countertop suppliers. Cost compression in nickel and chromium alloys is intensifying because of mining supply constraints, pressuring margins on food-grade stainless steel construction. Homeowner segments demonstrate highest price sensitivity, while multiplex operators absorbing labor savings from self-service formats tolerate premium positioning for automated kettle systems with integrated payment modules.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Shanghai to Long Beach elevate inbound logistics costs for Asian-manufactured heating elements and control systems. Component sourcing draws from China for electric kettle assemblies, Italy for precision thermostats, and the United States for NSF-certified food-contact surfaces. Single-source vulnerability in specialized gas burner castings from German suppliers creates procurement risk for oil-popped equipment configurations. Distribution runs through manufacturer-direct relationships with theater chains, bypassing traditional concession equipment distributors in California, Texas, and Florida corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multiplex operators unbundling equipment procurement from service contracts, with three national theater chains now representing over 40% of commercial-grade automatic popcorn machine demand in the United States.
For Market Incumbents: Shield premium positioning in high-volume cinema installations by deepening backward integration into food-grade stainless steel component forging, securing supply continuity against nickel price volatility. Accelerate IoT-enabled predictive maintenance platform deployment to capture recurring service revenue and raise switching costs for theater chain customers facing California Title 20 retrofit requirements. For New Entrants and Emerging Players: Lead with hot air popping technology targeting corporate cafeteria and school foodservice procurement teams specifying oil-free configurations for wellness compliance. Japan's aging theater infrastructure in Tokyo and Osaka corridors presents the most penetrable geography for automated concession equipment with integrated payment systems. Pursue direct manufacturer relationships with regional cinema chains rather than distributor-dependent channel strategies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-as-a-service providers offering subscription-based fleet management platforms to theater chains. Long-term viability hinges on regulatory compliance capabilities across NSF, CE marking, and emerging DOE efficiency standards. Target acquisition archetypes include specialized event-rental configuration specialists with portable kettle system expertise and established seasonal revenue cycles. Monitor California Title 20 enforcement actions as an inflection indicator for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Fleet Management Platform Launch | Enables predictive maintenance subscriptions with theater chains in California and Texas corridors. |
| Backward Integration into Stainless Forging | Captures margin pool from nickel price volatility affecting food-grade kettle construction. |
| Hot Air Technology Certification Pathway | Opens wellness-focused procurement channels in corporate cafeterias and school foodservice operations. |
| Direct Manufacturer Relationship Expansion | Bypasses distributor margin capture as theater chains unbundle equipment from service contracts. |
| Japan Cinema Modernization Partnership | Positions automated concession equipment with integrated payment systems in Tokyo and Osaka corridors. |
Research Methodology
A spread of perspectives from theater operations directors, concession equipment procurement managers, NSF certification engineers, and aftermarket service heads converged on the working assumptions for commercial demand trajectories. Primary fieldwork combined structured interviews with secondary validation through FDA food-contact surface regulations, California Title 20 appliance efficiency filings, CE marking documentation under EU machinery directives, and customs trade data for food-grade stainless steel component flows. Bottom-up equipment shipment analysis triangulated against top-down theater construction and retrofit spending patterns.
Segmentation dimensions modeled include product type, end user category, heating technology configuration, and kettle capacity specification across the projection horizon. CAGRs were derived from installed base replacement cycles, new theater construction pipelines, and efficiency mandate compliance timelines. Forecast inputs incorporated nickel and chromium price volatility indices, multiplex attendance recovery patterns, and labor cost pressures driving self-service format adoption.
Forecasts assume regulatory continuity in NSF International standards, California Title 20 efficiency regimes, and EU machinery directive CE marking requirements; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Commercial Microwaves Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market