
 Countertop Griddle Market | 2026-2036
Countertop Griddle Market Size, Share, and Industry Trends Forecast 2026-2036
Countertop Griddle Market Outlook
Subscription-based maintenance and software-defined temperature calibration is hardening into a core revenue layer for countertop griddle vendors. Middleby Corporation leverages its service network to lock in multi-year kitchen equipment contracts. Hamilton Beach Brands anchors its position through direct-to-commercial channel control. ITW Food Equipment Group competes on R&D intensity in precision heating systems.
A countertop griddle is a flat metal cooking surface, typically constructed from stainless steel or cast iron with embedded heating elements or gas burners, designed to maintain uniform temperatures between 150°F and 450°F for commercial batch cooking of proteins, breakfast items, and sandwiches. Its primary purpose is to deliver consistent throughput in space-constrained foodservice environments. Gas griddles dominate installed base in legacy kitchens while induction griddles represent the fastest-expanding segment due to energy efficiency mandates and reduced ventilation requirements. Stainless steel construction leads material preference for durability and NSF compliance, though non-stick coating variants capture margin pools in light-duty cafe and home user channels.
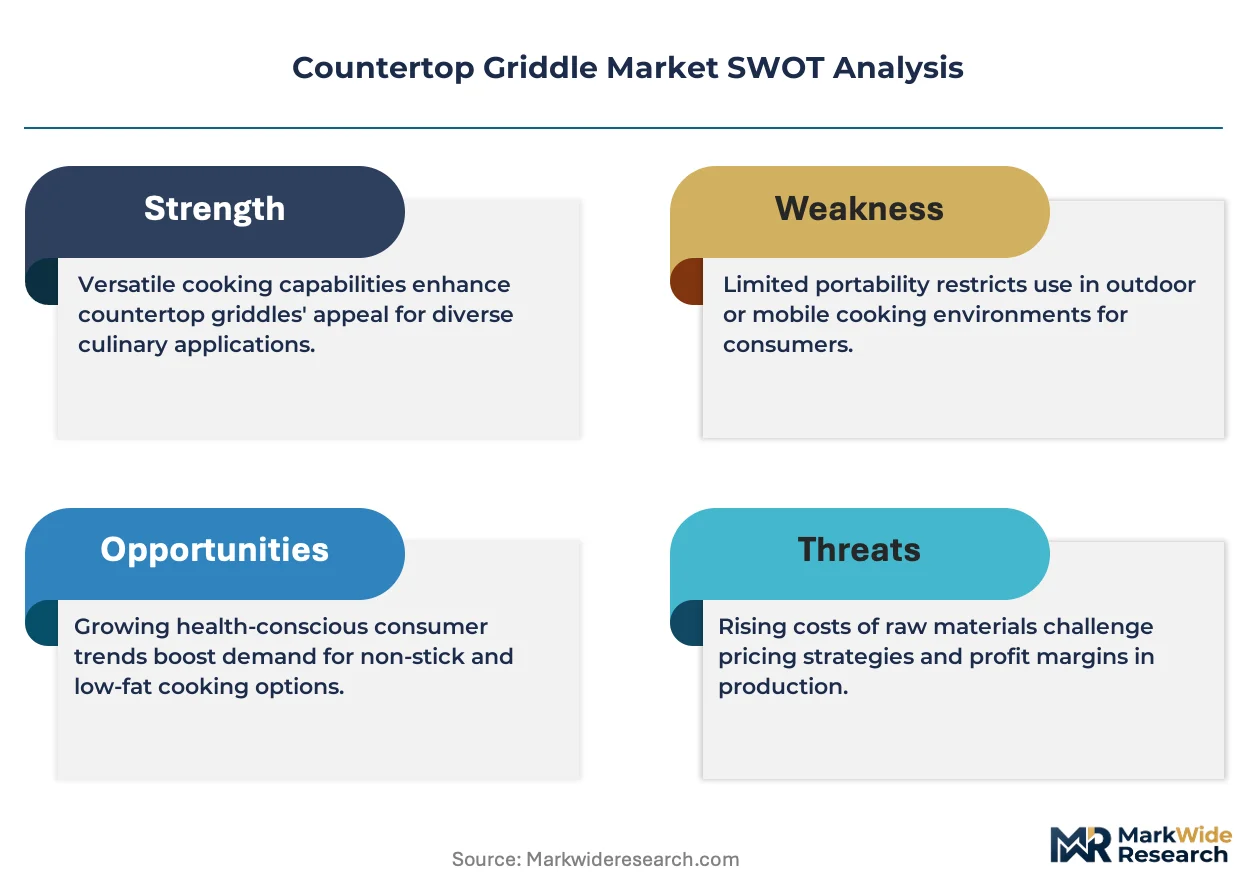
The U.S. FDA and NSF International set commercial food equipment sanitation standards that dictate surface material specifications and cleanability requirements for griddle manufacturers. The EPA's ENERGY STAR program shapes procurement criteria for electric and gas models in institutional buying. Stakeholders must monitor evolving electrification incentives and ventilation code changes that could accelerate induction griddle replacement cycles.
Market Dynamics
Electrification mandates in commercial kitchens are compressing replacement cycles for gas-powered equipment and forcing vendors to reengineer thermal systems around induction coil architectures.
Growth Catalysts
- Quick-service restaurant expansion:Burger chains and breakfast concepts prioritize compact, high-throughput cooking surfaces to maximize kitchen yield per square foot.
- EPA ENERGY STAR procurement criteria:Institutional buyers in school districts and hospital cafeterias now require certified electric griddles, redirecting capital toward efficient models.
- Reduced ventilation requirements:Induction griddles eliminate open flames and lower hood exhaust demands, enabling installation in space-constrained urban locations.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input costs fluctuate with mining supply disruptions, squeezing margin on NSF-compliant construction.
- Legacy kitchen infrastructure lock-in:Gas line retrofit costs deter independent restaurants from switching to electric alternatives despite operating savings.
- Induction equipment cost premium:Copper coil and power electronics assemblies run higher than cast-iron gas burner equivalents at equivalent cooking surface area.
Strategic Opportunities
- Cloud kitchen proliferation:Delivery-only foodservice operators in dense metropolitan clusters demand modular, ventless equipment for ghost kitchen deployments.
- Subscription calibration services:Software-defined temperature monitoring creates recurring revenue streams tied to food safety compliance.
- Non-stick coating variants:Light-duty cafe and home user channels accept lower durability for reduced oil usage and simplified cleaning protocols.
Industry Challenges
- NSF certification timelines:Surface material validation and cleanability testing extend product launch schedules by six to twelve months.
- Electrical infrastructure upgrades:Three-phase power requirements for high-capacity induction units complicate installation in older buildings with limited panel capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Countertop Griddle Market |
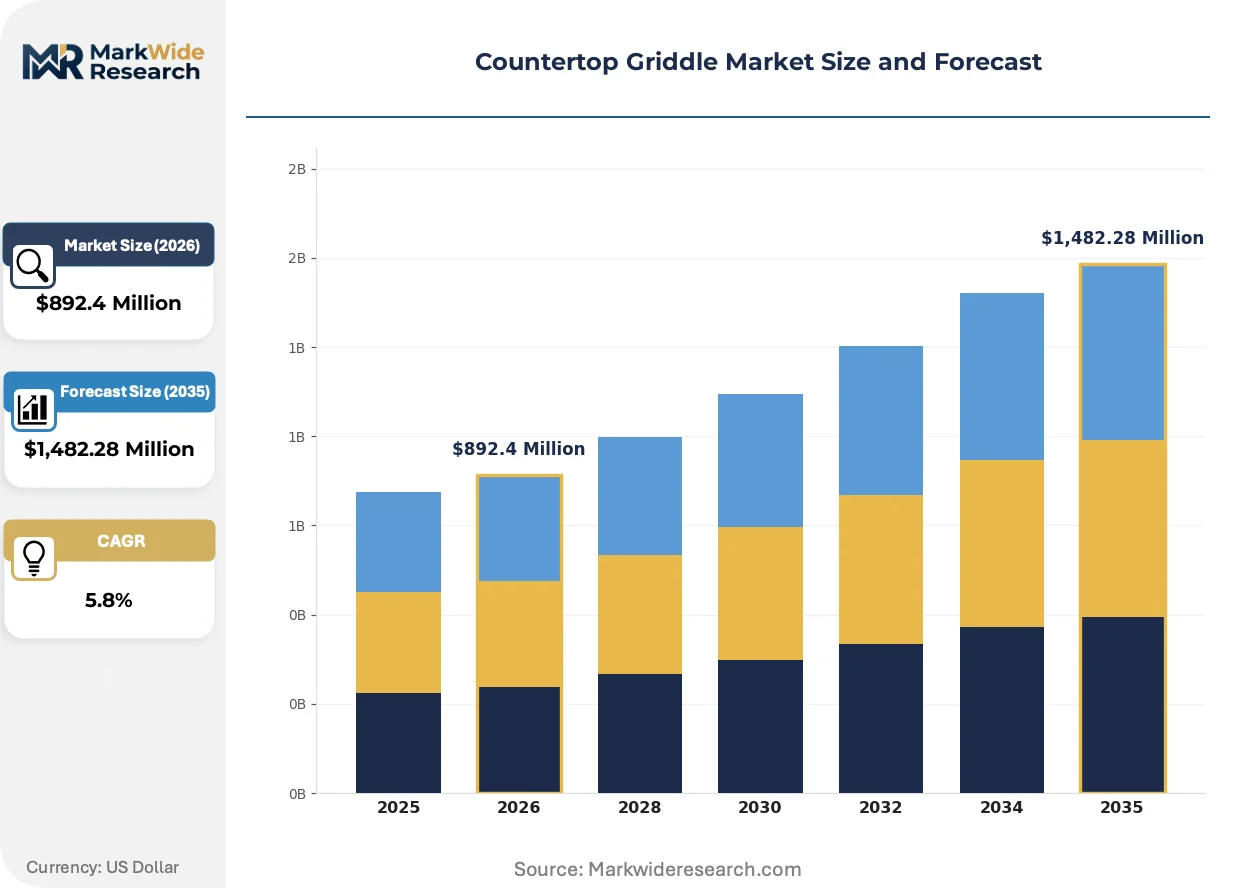
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,482.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Griddles, Gas Griddles, Induction Griddles, Combo Griddles End User: Restaurants, Cafes, Food Trucks, Home Users Application: Breakfast Cooking, Grilling, Searing, Warming Material: Stainless Steel, Aluminum, Non-Stick Coating, Cast Iron |
| Companies Covered | Middleby Corporation, Hamilton Beach Brands, ITW Food Equipment Group, Vulcan, Lang World, Garland Group, Star Manufacturing International, Blackstone Products, Equipex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Countertop Griddle Market Strategic Shifts
Intelligent thermal management and connected equipment architectures are redefining how operators monitor cooking consistency and manage energy consumption across distributed locations.
Precision induction heating with embedded temperature sensors is consolidating control over batch cooking outcomes. Full-service restaurants and institutional cafeterias adopt these systems to reduce energy waste and eliminate hot spots. The technology is consolidating vendor market position around integrated hardware-software platforms that lock in multi-year service relationships.
REACH substance restrictions in Europe limit perfluorinated compounds in non-stick coatings, forcing reformulation of surface treatments for export-bound equipment. Manufacturers must qualify alternative ceramic and silicone-based layers to maintain access to EU foodservice channels. This regulatory pressure concentrates R&D spending among firms with dedicated European compliance teams.
Direct-to-commercial channel strategies now bypass traditional foodservice equipment distributors. Hamilton Beach Brands and similar vendors build proprietary sales forces to capture margin and control specification conversations with end users. The United States quick-service segment shows the fastest channel compression as chains centralize procurement through approved vendor lists.
Countertop Griddle Market Segmentation
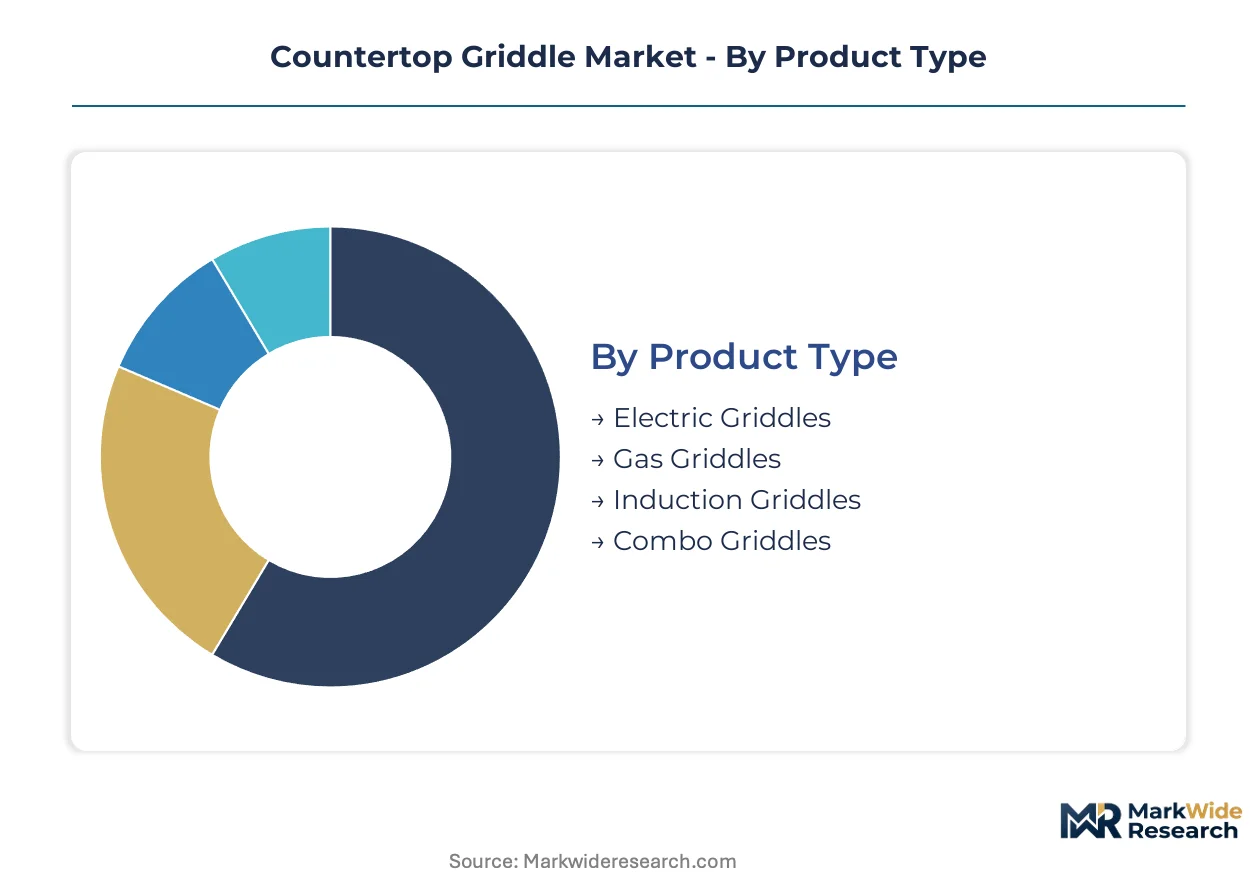
Countertop griddle segmentation reveals divergent equipment economics across power sources, end-use environments, and surface technologies. Vendors configure product lines around thermal system architecture, operator skill levels, and compliance requirements rather than pursuing universal designs.
Product Type:
Gas griddles dominate installed base through lower upfront capital requirements, while induction systems capture premium positioning via energy efficiency mandates and reduced ventilation infrastructure needs.
- Electric Griddles:Resistance-element heating systems embedded in cast iron or steel plates deliver steady thermal output for institutional cafeterias and school districts. Demand concentrates in United States K-12 foodservice operations where EPA ENERGY STAR procurement criteria redirect capital toward efficient electric models.
- Gas Griddles:Open-flame burner systems beneath steel or chrome cooking surfaces provide rapid temperature recovery for high-throughput breakfast concepts. Legacy kitchen infrastructure across United States independent restaurants perpetuates gas equipment dominance despite electrification mandates.
- Induction Griddles:Copper coil electromagnetic systems generate heat directly in ferromagnetic cookware, eliminating thermal lag and reducing hood exhaust requirements. United States urban ghost kitchen operators adopt these for ventless installation in space-constrained metropolitan clusters.
- Combo Griddles:Dual-zone configurations combine gas and electric heating or integrate griddle surfaces with charbroiler elements for menu flexibility. Full-service restaurants specify these for protein variety without equipment redundancy.
Today's leader: Gas Griddles. Tomorrow's challenger: Induction Griddles.
End User:
Commercial operator sophistication determines equipment specification depth, with quick-service chains centralizing procurement through approved vendor lists while independent operators prioritize flexibility over standardization.
- Restaurants:Full-service and limited-service establishments specify NSF-compliant stainless steel construction with embedded temperature controls for protein consistency. United States burger chains and breakfast concepts drive volume demand for compact, high-throughput surfaces.
- Cafes:Light-duty operations favor non-stick coated aluminum griddles for reduced oil usage and simplified cleaning protocols. Smaller footprint requirements in urban United States coffee shops push demand toward single-zone electric models.
- Food Trucks:Mobile operators require LP gas compatibility and reinforced chassis mounting for vibration resistance. United States metropolitan food truck clusters in Austin, Portland, and Los Angeles specify ruggedized gas griddles for off-grid operation.
- Home Users:Residential buyers purchase countertop electric units through retail channels, accepting lower durability for occasional use and price accessibility. Hamilton Beach Brands and similar vendors target this segment through direct-to-consumer distribution.
Commercial kitchens command specification authority. Residential channels expand volume reach.
Application:
Cooking task specificity determines surface temperature range requirements, with breakfast applications demanding precise low-temperature control while searing operations prioritize rapid thermal recovery.
- Breakfast Cooking:Eggs, pancakes, and breakfast meats require uniform 275°F-350°F surface temperatures with minimal hot spots. United States quick-service breakfast chains specify precision induction systems for consistent throughput during morning rushes.
- Grilling:Sandwich and protein preparation demands rapid temperature recovery between batches. Deli concepts and casual dining operators in United States urban centers prioritize steel plate thickness for thermal mass retention.
- Searing:High-heat protein caramelization requires 400°F+ surface temperatures with minimal temperature drop on product contact. Steakhouse and burger concepts specify heavy-duty gas or induction systems for Maillard reaction development.
- Warming:Holding applications utilize lower temperature zones or dedicated warming drawers integrated beneath primary cooking surfaces. Buffet and catering operators in United States institutional settings configure combo units for simultaneous cooking and holding.
Breakfast specialization anchors current demand. Searing capability differentiates premium tiers.
Material:
Surface material selection trades off durability, thermal conductivity, and cleanability compliance, with NSF certification requirements filtering construction options for commercial channels.
- Stainless Steel:Chromium-nickel alloy construction delivers corrosion resistance and meets NSF International cleanability standards for commercial food equipment. United States FDA sanitation requirements perpetuate stainless dominance in institutional procurement.
- Aluminum:Lightweight construction with superior thermal conductivity enables rapid heating for light-duty applications. United States cafe and home user channels accept aluminum for cost-sensitive positioning despite lower durability.
- Non-Stick Coating:Polymer or ceramic surface treatments reduce oil requirements and simplify cleaning for low-skill operators. REACH substance restrictions in Europe force reformulation of perfluorinated compounds for export-bound equipment.
- Cast Iron:Dense thermal mass provides exceptional heat retention for searing operations, though weight and maintenance requirements limit adoption. United States steakhouse concepts specify cast iron for signature crust development.
Stainless steel owns compliance-driven procurement. Non-stick coatings capture convenience premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium equipment specification authority, while Germany enforces the strictest energy efficiency mandates for commercial kitchen electrification. Japan's compact urban foodservice culture drives demand for ventless induction systems. China's rapid ghost kitchen proliferation creates modular equipment opportunities. Brazil's independent restaurant sector resists gas-to-electric conversion despite operating cost pressures.
United States
Quick-service restaurant chains and cloud kitchen operators anchor equipment procurement volume. The EPA's ENERGY STAR program mandates certified electric griddles for federal institutional purchasing. Urban foodservice clusters in New York City, Los Angeles, and Austin concentrate demand for ventless induction units in space-constrained ghost kitchen deployments.
Germany
Commercial kitchen electrification mandates accelerate replacement cycles for gas-powered equipment. The Ecodesign Directive and national building codes enforce strict ventilation and energy consumption thresholds. Industrial foodservice equipment manufacturers in Bavaria and North Rhine-Westphalia reengineer thermal systems around induction coil architectures for EU export markets.
Japan
Compact restaurant footprints and high urban real estate costs prioritize space-efficient cooking surfaces. METI's energy conservation standards promote induction heating adoption in commercial foodservice. Tokyo and Osaka metropolitan clusters drive specification of precision temperature control systems for high-throughput breakfast and ramen concepts.
China
Delivery-only foodservice operators proliferate in dense metropolitan districts, demanding modular kitchen equipment. The country's dual carbon goals pressure commercial sectors toward electrification, though enforcement varies by municipality. Yangtze River Delta and Pearl River Delta manufacturing hubs produce cost-optimized induction griddles for domestic and Southeast Asian export markets.
Brazil
Independent restaurant operators and street food vendors perpetuate gas griddle dominance through lower upfront capital requirements. ANVISA's commercial food equipment sanitation standards shape surface material specifications for formal sector procurement. São Paulo and Rio de Janeiro urban foodservice clusters show emerging interest in induction alternatives where electrical infrastructure permits.
Countertop Griddle Market Competitive Environment
Top-tier vendors anchor multi-brand portfolio strategies, while mid-scale fabricators compete on regional customization and price-accessible positioning. The vendor base stratifies across integrated kitchen equipment conglomerates, specialized thermal system developers, and contract manufacturers serving private-label retail channels. Dominant competitive moves include backward integration into heating element production and captive service network expansion to lock in recurring maintenance revenue.
Within the diversified equipment conglomerate tier, Middleby Corporation and ITW Food Equipment Group exemplify scale-driven competitive positioning through multi-brand portfolio breadth. Hamilton Beach Brands occupies a distinct position bridging commercial specification authority with direct-to-consumer retail channel control. Among specialized thermal system developers, Star Manufacturing International represents the precision heating segment focused on temperature calibration technology and connected equipment architectures.
| Leading Market Players |
|---|
| Middleby Corporation |
| Hamilton Beach Brands |
| ITW Food Equipment Group |
| Vulcan |
| Lang World |
| Garland Group |
| Star Manufacturing International |
| Blackstone Products |
| Equipex |
| Others |
Value Chain & Pricing Dynamics
Induction coil architecture migration simultaneously compresses manufacturing cost curves and concentrates supplier power among electromagnetic component specialists with certified NSF fabrication capabilities. Copper winding precision and power electronics integration favor vendors with captive heating element production, reshaping margin distribution across equipment tiers.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for induction power modules and copper coil assemblies. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified stainless construction with embedded sensors from basic electric plate models and imported aluminum variants. Pricing pressure stems from nickel and chromium volatility in stainless feedstock, squeezing margin on compliant commercial-grade equipment. Quick-service chains with centralized procurement show lowest price sensitivity, while independent restaurants and cafe operators prioritize upfront capital minimization over lifecycle operating costs.
Supply Chain Analysis
Dual-sourcing requirements from institutional buyers in the United States and Germany mandate qualified secondary suppliers for critical heating elements and control electronics. Manufacturing concentrates in China for cost-optimized induction assemblies, the United States for NSF-certified stainless fabrication, and Italy for premium gas burner systems. Raw material dependencies center on copper cathodes, nickel-chromium alloys, and ferritic steel plates. Single-source vulnerability runs through specialized electromagnetic coil suppliers with ENERGY STAR testing accreditation. Distribution runs through foodservice equipment distributors with specification authority, though direct-to-commercial channels are compressing traditional markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on induction technology cost-down curves and premium-tier software subscription attach rates. Energy efficiency mandates and cloud kitchen proliferation create structural uplift in average selling prices.
For Market Incumbents: Cement multi-year service contracts through temperature calibration software platforms that lock in institutional accounts. Deepen backward integration into copper coil winding and power electronics assembly to defend margin against commodity volatility. The EPA's evolving ENERGY STAR criteria and emerging electrification incentives threaten equipment obsolescence for vendors without induction-ready portfolios. For New Entrants and Emerging Players: Enter via ventless induction systems for United States ghost kitchen operators in space-constrained urban clusters where legacy gas infrastructure cannot deploy. Target light-duty cafe channels with ceramic-coated aluminum variants that trade durability for price accessibility and simplified maintenance. Direct-to-commercial channel development bypasses distributor margin capture and enables specification conversations with emerging cloud kitchen chains. For Investors and Strategic Acquirers: Roll-up economics work for regional thermal equipment fabricators with NSF certification infrastructure and established service networks because electrification mandates are accelerating replacement cycles and fragmenting procurement across local operators. Five-to-ten year viability favors vendors with software-defined equipment architectures and recurring revenue streams over pure hardware plays. Watch for inflection in three-phase electrical infrastructure investment rates in older United States commercial buildings, which gates high-capacity induction adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive copper coil production insulates margin from commodity volatility and supplier concentration. |
| Software-Defined Temperature Calibration Launch | Connected monitoring platforms create recurring revenue tied to FDA food safety compliance requirements. |
| Direct-to-Commercial Channel Expansion | Proprietary sales forces capture distributor margin and control specification with quick-service chains. |
| NSF Certification Investment | Surface material validation unlocks institutional procurement in United States school and hospital cafeterias. |
| Ventless Induction Product Line Extension | Reduced hood exhaust requirements enable installation in space-constrained urban ghost kitchen deployments. |
Study Parameters
Bottom-up foodservice operator modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with quick-service chain procurement directors, commercial kitchen design consultants, NSF certification engineers, and foodservice equipment distributors were validated against secondary sources including EPA ENERGY STAR certified product listings, FDA commercial food equipment sanitation guidelines, and NSF International registration databases. Trade flow analysis of stainless steel and copper component imports supplemented domestic production estimates across the analysis window.
Historical trendline analysis of griddle equipment shipments by power source and end-use channel established baseline growth patterns. The projection framework segments volume and value across electric, gas, induction, and combo thermal systems; restaurant, cafe, food truck, and home user end-use categories; and stainless steel, aluminum, non-stick, and cast iron material tiers. CAGRs were derived from equipment replacement cycle compression rates tied to electrification mandates and cloud kitchen proliferation metrics.
Inputs from EPA procurement databases and NSF certification registries were available through the study window; gaps in real-time foodservice operator capital expenditure reporting introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions regarding ENERGY STAR criteria stability, nickel price volatility ranges, and three-phase electrical infrastructure upgrade rates. Deviation in federal electrification incentive implementation timing or state-level ventilation code changes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Catering Equipment Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Global QSR Food Service Equipment Market