
 Commercial Bar Equipment Market | 2026-2036
Commercial Bar Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Bar Equipment Market Outlook
Independent craft cocktail lounges is collapsing the historical dominance of hotel chains in premium equipment procurement. The Middleby Corporation leverages its vertical manufacturing footprint to control component costs across refrigeration and dispensing lines. Ali Group S.r.l. sustains broad geographic coverage through decentralized brand portfolios serving regional bar equipment preferences. Hoshizaki Corporation anchors its position in precision ice production systems where technical specifications command specification-driven purchasing.
Commercial bar equipment encompasses electrically powered and plumbed fixtures engineered for beverage service environments, typically constructed from 300-series stainless steel with NSF-certified food-contact surfaces and operating on 115-208V electrical systems designed for continuous-duty cycles in high-humidity conditions. The primary commercial purpose centers on temperature-controlled storage, precise portion dispensing, and sanitary ice generation to support regulated foodservice operations. Ice makers and draft beer systems concentrate margin pools where compressor efficiency and glycol cooling specifications differentiate premium from standard tiers. Bar blenders compete on motor torque ratings and noise dampening as mixology-focused concepts elevate equipment performance requirements. Cocktail shakers occupy a mature segment where manual and automated variants serve divergent operational scale needs across independent bars and multi-unit restaurant groups.
NSF International standards govern food-contact surface compliance and electrical safety certification for equipment deployed in U.S. commercial kitchens, while the EU's CE marking and Ecodesign Directive regulate energy efficiency thresholds for refrigeration systems sold across European member states. China's SAMR enforces GB standards for electrical appliance safety and energy labeling that constrain import eligibility for foreign manufacturers. Stakeholders must monitor evolving refrigerant phase-down schedules under the EU F-Gas Regulation and corresponding EPA SNAP program adjustments in the United States, as compressor technology transitions will reshape supplier qualification requirements and retrofit demand cycles.
Market Dynamics
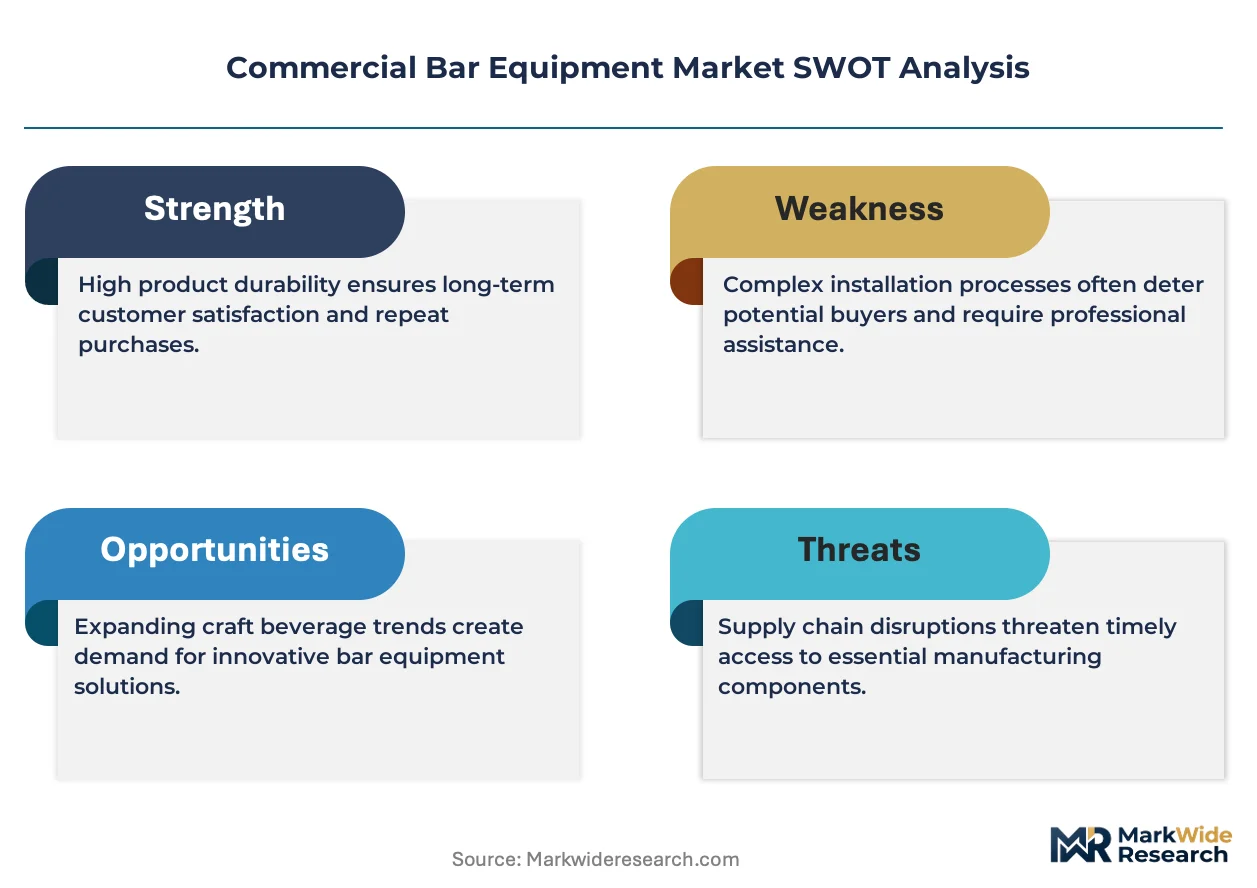
Experiential drinking formats are compressing equipment replacement cycles as boutique cocktail lounges demand precision-controlled ice production and draft dispensing systems that support theatrical beverage preparation. The FDA's Food Code sanitation updates are forcing simultaneous redesigns across refrigeration and dispensing product lines.
Growth Catalysts
- NSF Food Code Compliance Mandates:U.S. state health departments are accelerating equipment replacement timelines through tightened surface-sanitation specifications. Bar operators face procurement deadlines tied to permit renewal cycles.
- China Tier-One City Premiumization:Shanghai and Beijing hospitality investors are specifying imported glycol-cooled draft systems and precision ice makers for high-end cocktail concepts. Municipal commercial zoning favors licensed beverage operations in repurposed industrial districts.
- Refrigerant Transition Requirements:The EPA SNAP program and EU F-Gas Regulation are synchronizing compressor technology upgrades across export markets. Equipment manufacturers qualify new product lines against dual regulatory frameworks simultaneously.
Market Restraints
- Stainless Steel Input Volatility:300-series alloy pricing swings compress margin stability for fabrication-heavy equipment categories. Chinese mill supply concentration amplifies cost transmission lags.
- Compressor Technology Lock-In:Legacy refrigeration architectures constrain retrofit compatibility with low-GWP refrigerant chemistries. Equipment owners face full-system replacement versus component upgrade decisions.
- Certification Timeline Friction:NSF International and CE marking convergence testing extends new product introduction cycles. Dual-market launches require sequential rather than parallel approval pathways.
Strategic Opportunities
- India Hospitality Infrastructure Buildout:Mumbai and Delhi luxury hotel developments are specifying integrated bar systems for rooftop beverage concepts. Import duty structures favor CKD assembly partnerships with domestic fabricators.
- IoT-Enabled Predictive Maintenance Convergence:Connected compressor diagnostics and automated ice-level sensing are creating subscription service revenue streams. Equipment-as-a-service models reduce capital barriers for independent operators.
- EU Ecodesign Directive Energy Labeling:A++ efficiency tier requirements are segmenting premium refrigeration pricing. First-mover certification creates specification advantages in Nordic and German procurement.
Industry Challenges
- Specialized Service Technician Scarcity:Glycol system diagnostics and sealed refrigeration repair require certifications that training pipelines have not scaled to match installed base growth. OEMs are captive to authorized service network expansion rates.
- Legacy Electrical Infrastructure Mismatch:115-208V continuous-duty specifications conflict with aging building electrical in urban core locations. Retrofit projects face panel upgrade costs that distort equipment selection toward lower-draw alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Bar Equipment Market |
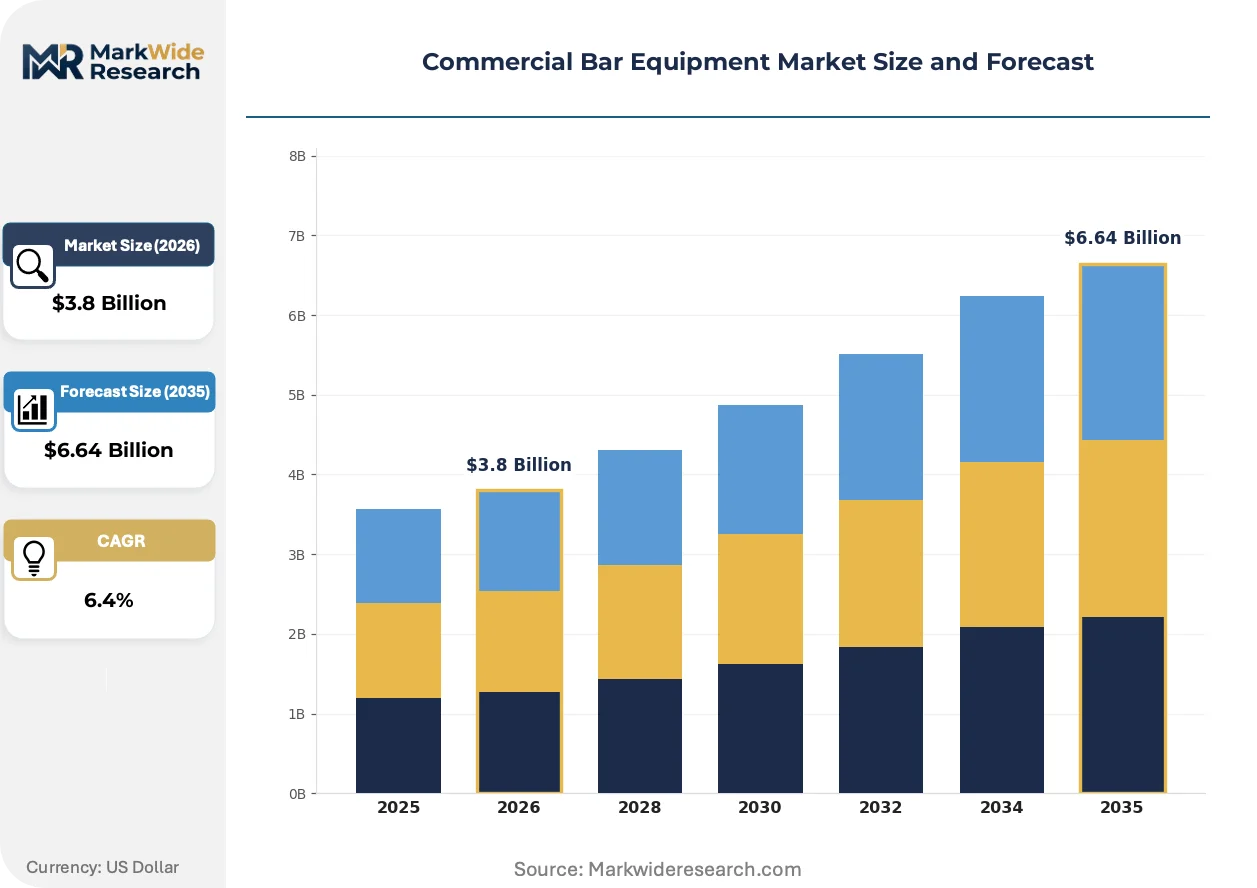
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bar Blenders, Cocktail Shakers, Ice Makers, Draft Beer Systems End User: Restaurants, Nightclubs, Bars, Hotels Application: Mixology, Beverage Dispensing, Ice Production, Food Preparation Distribution Channel: Online Retailers, Direct Sales, Wholesale Distributors, Specialty Stores |
| Companies Covered | The Middleby Corporation, Ali Group S.r.l., Welbilt, Inc., Hoshizaki Corporation, Perlick Corporation, Krowne Metal Corporation, True Manufacturing Co., Inc., Glastender, Inc., Continental Refrigerator, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Bar Equipment Market Strategic Shifts
Modular equipment architectures are enabling rapid format reconfiguration as operators pivot between cocktail service, draft beverage programs, and non-alcoholic concepts within single footprints. Component standardization across ice production, refrigeration, and dispensing systems is compressing supplier qualification requirements.
Precision ice production technology is decomposing the traditional ice supplier relationship in high-end cocktail operations. Spec-driven lounges in New York and London are installing Hoshizaki-specified machines producing directional-freeze clear cubes and compressed spheres. The capital shift from outsourced ice delivery to captive production is reallocating working capital toward equipment finance structures.
The EU F-Gas Regulation's refrigerant phase-down schedule is accelerating compressor platform obsolescence across European refrigeration equipment. Manufacturers are requalifying entire product lines against R290 and R600a hydrocarbon alternatives ahead of 2030 service restrictions. Export-oriented suppliers are bifurcating production between F-Gas-compliant EU variants and EPA SNAP-aligned North American configurations.
Boutique cocktail lounge buyers are consolidating vendor relationships through single-source equipment packages spanning ice, refrigeration, and dispensing. Independent operators in Los Angeles and Sydney prefer integrated procurement that bundles installation, training, and maintenance under unified service agreements. Channel concentration is elevating specification influence for vertically integrated suppliers that control multiple equipment categories.
Commercial Bar Equipment Market Segmentation
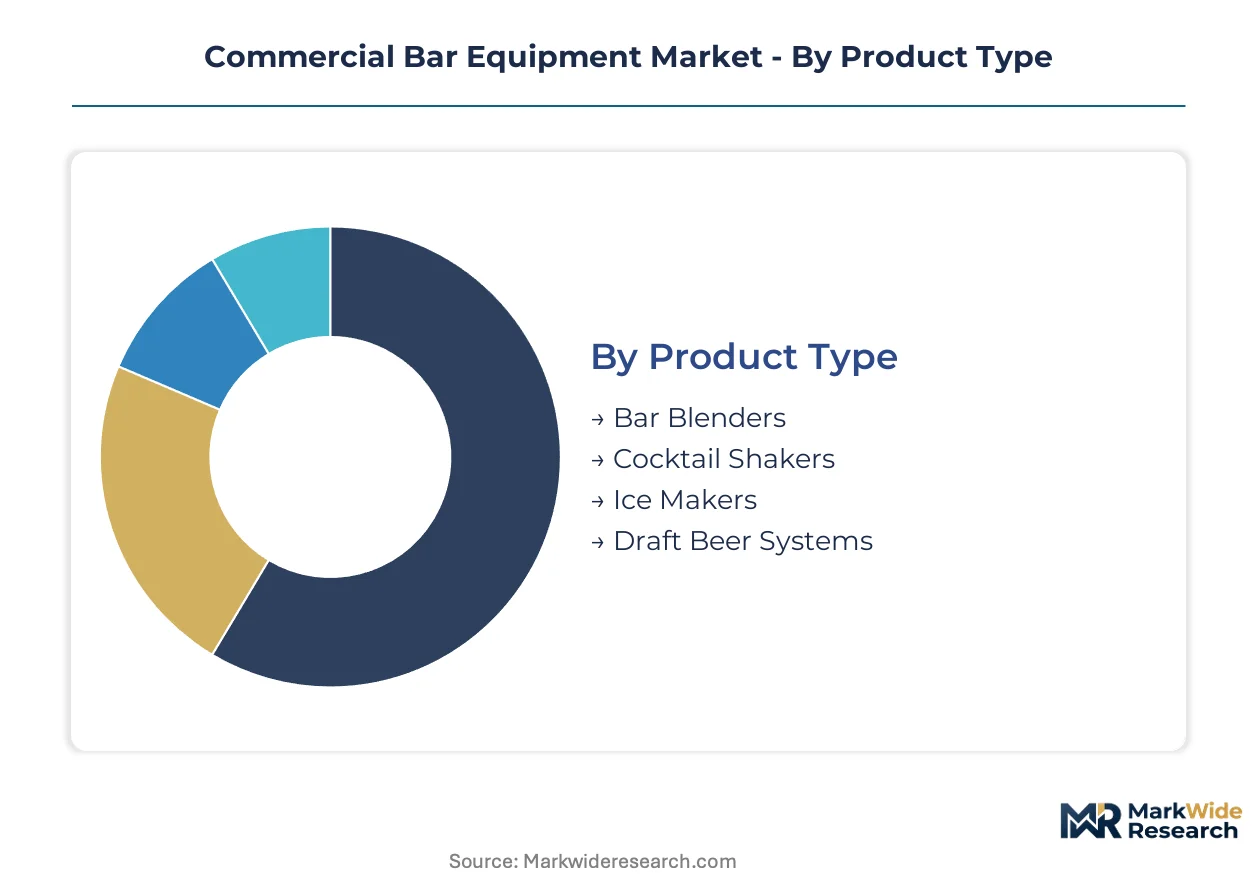
Equipment specification varies sharply across venue types and operational scales. Segmentation reveals where compressor efficiency, portion precision, and sanitation compliance create divergent procurement priorities for suppliers and operators.
Product Type:
Ice makers and draft systems dominate export-led demand from European and North American manufacturers, while blenders and shakers see stronger domestic fabrication across Asian markets.
- Ice Makers:Precision clear-cube and directional-freeze systems use sealed refrigeration circuits with NSF-certified food-contact surfaces. Demand concentrates in Shanghai, New York, and London cocktail lounges where specification-driven purchasing rewards technical performance over unit cost.
- Draft Beer Systems:Glycol-cooled and direct-draw configurations operate on 115-208V continuous-duty cycles with stainless steel contact surfaces. Tier-one Chinese cities and Australian craft beer concepts are specifying imported systems for rooftop and basement bar installations.
- Bar Blenders:High-torque motor systems with noise-dampening enclosures serve high-volume mixology operations.
- Cocktail Shakers:Manual and automated variants span independent bars through multi-unit restaurant groups with divergent throughput requirements.
Ice makers hold the largest share; momentum sits with draft systems as craft beverage programs expand.
End User:
Cost tier stratification separates premium specification buyers from price-sensitive volume purchasers across venue categories.
- Bars:Independent craft cocktail lounges and boutique concepts drive precision ice and draft system procurement with specification-heavy purchasing. These operators prioritize NSF compliance and glycol cooling performance over capital cost minimization.
- Hotels:Chain properties historically dominated premium equipment procurement but are ceding share to independent venues with faster replacement cycles and experiential format demands.
- Restaurants:Full-service and casual dining concepts balance equipment versatility against footprint constraints in multi-purpose beverage stations.
- Nightclubs:High-throughput venues prioritize durability and rapid service capacity over precision features in ice and dispensing systems.
Bars command specification influence; hotels retain volume scale despite share erosion.
Application:
Volume concentration aligns with operational intensity—mixology and beverage dispensing absorb premium equipment spend while food preparation anchors standard-tier procurement.
- Beverage Dispensing:Draft systems and portion-controlled liquor dispensers integrate temperature management with sanitary design for regulated foodservice environments. Nightclubs and hotel bars deploy these systems at highest throughput.
- Mixology:Precision ice production and high-performance blending support theatrical preparation formats in craft cocktail lounges. This application demands equipment with rapid recovery cycles and consistent output specifications.
- Ice Production:Captive clear-cube and sphere generation replaces outsourced delivery in premium venues, reallocating working capital to equipment finance.
- Food Preparation:Secondary bar kitchen equipment supports garnish and small-plate production with lower specification intensity than core beverage systems.
Beverage dispensing generates margin concentration; mixology shows steepest expansion trajectory as experiential formats proliferate.
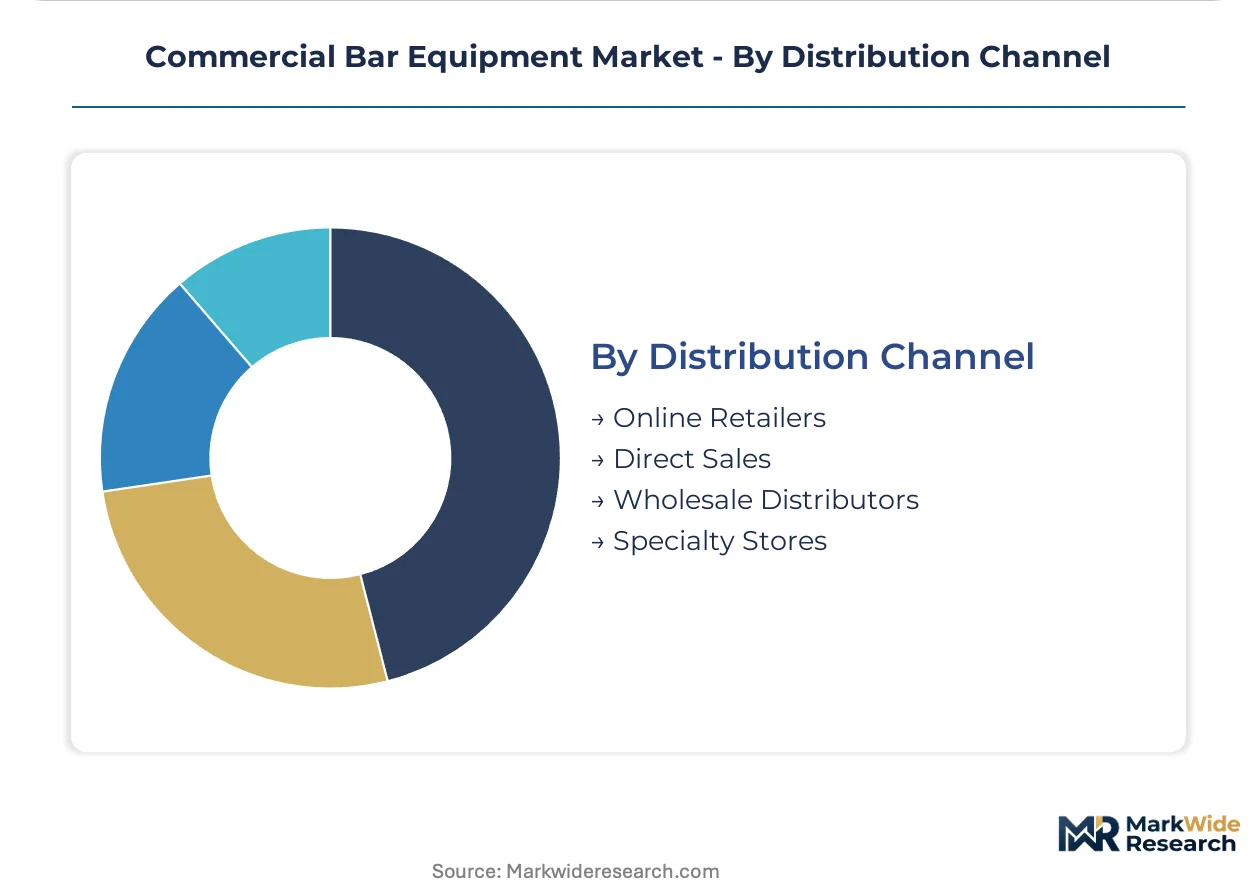
Distribution Channel:
Supply concentration favors wholesale distributors with service networks, while direct sales capture integrated package deals for multi-unit operators.
- Wholesale Distributors:Regional equipment houses bundle installation, maintenance, and certification support for independent bars and restaurants. These intermediaries control specification influence through technician relationships and spare parts availability.
- Direct Sales:Manufacturers sell integrated equipment packages spanning ice, refrigeration, and dispensing to multi-unit groups and hotel chains. Unified service agreements reduce procurement complexity for buyers with standardized formats.
- Online Retailers:E-commerce platforms serve replacement part procurement and standard-tier equipment for cost-sensitive operators.
- Specialty Stores:Regional showrooms demonstrate equipment performance for boutique operators prioritizing hands-on evaluation before purchase.
Wholesale distributors retain volume leadership; direct sales channels are gaining specification control through bundled service offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian and German manufacturers export glycol-cooled draft systems and precision ice makers to tier-one Chinese cities, while U.S. fabricators supply NSF-certified refrigeration equipment to hospitality developments across India and the Middle East.
United States
Boutique cocktail lounges in New York and Los Angeles drive specification-heavy procurement of clear-cube ice systems and draft infrastructure. The FDA's Food Code updates on equipment sanitation standards force simultaneous redesigns across refrigeration and dispensing product lines. Miami and Austin hospitality clusters absorb premium equipment imports for rooftop beverage concepts.
China
Shanghai and Beijing investors specify imported glycol-cooled draft systems for licensed operations in repurposed industrial districts. SAMR enforces GB standards for electrical appliance safety and energy labeling that constrain import eligibility for foreign manufacturers. Guangzhou and Shenzhen bar clusters prioritize precision ice production systems for experiential drinking formats.
Germany
Craft beer concepts in Berlin and Munich demand A++ efficiency-tier refrigeration under EU Ecodesign Directive requirements. The EU F-Gas Regulation's refrigerant phase-down schedule accelerates compressor platform obsolescence across domestic manufacturing. Hamburg hospitality developments specify integrated bar systems for waterfront beverage operations.
India
Mumbai and Delhi luxury hotel developments specify integrated bar systems for rooftop concepts with CKD assembly partnerships reducing import duty exposure. BIS certification requirements for electrical appliance safety extend equipment qualification timelines for foreign suppliers. Bangalore hospitality clusters absorb draft system imports for craft beverage programs.
Australia
Sydney and Melbourne independent operators prefer single-source equipment packages bundling installation and maintenance under unified service agreements. The country's national electrical safety regulator enforces continuous-duty cycle specifications for high-humidity commercial environments. Perth bar clusters concentrate procurement of noise-dampening blenders for high-volume mixology operations.
Commercial Bar Equipment Market Competitive Environment
Listed leaders compete with private specialists across certification breadth and geographic coverage. The vendor base concentrates around refrigeration and ice production specialists with NSF and CE marking capabilities, while fabrication-heavy categories sustain regional mid-tier competitors. Three archetypes dominate: vertically integrated conglomerates controlling multiple equipment categories, precision-focused specialists anchoring specification-driven segments, and regional fabricators serving cost-sensitive replacement demand. M&A activity concentrates on acquiring service network density, while portfolio diversification moves target integrated equipment packages spanning ice, refrigeration, and dispensing.
Within the conglomerate tier, The Middleby Corporation and Ali Group S.r.l. represent diversified equipment portfolios with multi-brand geographic coverage. Hoshizaki Corporation exemplifies the precision-specialist archetype, occupying a position in technical specification-driven purchasing for ice production systems. These three entities anchor competitive dynamics across premium procurement channels where bundled service agreements and certification breadth determine specification influence.
| Leading Market Players |
|---|
| The Middleby Corporation |
| Ali Group S.r.l. |
| Welbilt, Inc. |
| Hoshizaki Corporation |
| Perlick Corporation |
| Krowne Metal Corporation |
| True Manufacturing Co., Inc. |
| Glastender, Inc. |
| Continental Refrigerator |
| Others |
Value Chain & Pricing Dynamics
Long-term equipment offtake agreements with tier-one Chinese hospitality developers lock in both stainless steel component access and fixed-price visibility for refrigeration and ice production systems, insulating manufacturers from 300-series alloy volatility while constraining margin flexibility for spot-market purchasers.
Pricing Analysis
Compressor-generation pricing gaps separate R290 hydrocarbon-compliant systems from legacy HFC architectures and emerging CO₂ transcritical platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by NSF certification grade and glycol cooling efficiency, with boutique cocktail lounges absorbing premium tiers while hotel chains negotiate volume discounts. Price erosion runs through standard-tier draft systems as Chinese domestic fabrication scales. Nightclubs exhibit highest price sensitivity, prioritizing durability over precision specifications.
Supply Chain Analysis
Strategic stockpiling of 300-series stainless steel dominates procurement strategy among U.S. and European fabricators facing Chinese mill supply concentration. Component sourcing draws from China for electrical assemblies, Italy for precision dispensing hardware, and Germany for compressor platforms. Single-source vulnerability in sealed refrigeration circuits constrains equipment availability during platform transitions. Distribution runs through authorized service networks with spare parts warehousing, bypassing direct-to-operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multi-unit boutique cocktail lounge groups, fragmenting procurement influence away from hotel chains and elevating specification leverage for integrated equipment packages.
For Market Incumbents: Compound certification breadth across NSF and CE marking to defend specification control as the EU F-Gas Regulation and EPA SNAP program synchronize refrigerant transition timelines. Deepen backward integration into compressor manufacturing to capture margin pools threatened by Chinese domestic competition. Channel control through authorized service network density remains the critical lever against independent technician scarcity. For New Entrants and Emerging Players: Differentiate on IoT-enabled predictive maintenance subscriptions, targeting independent bars in Mumbai and Delhi where capital barriers favor equipment-as-a-service models. White-space concentration sits with CKD assembly partnerships in India, where import duty structures disadvantage fully-built imports. A direct sales approach bundling installation and training penetrates faster than wholesale distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward precision ice production specialists with specification-driven purchasing loyalty and technical moats in directional-freeze clear-cube systems. Long-term viability centers on refrigerant-transition readiness and dual-market certification capabilities. The signal to watch is EPA SNAP program acceleration compressing legacy equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | R290 and R600a hydrocarbon qualification ahead of EU F-Gas 2030 restrictions locks in export eligibility. |
| IoT Predictive Maintenance Launch | Connected compressor diagnostics create recurring revenue streams reducing capital barriers for independent operators. |
| CKD Assembly Partnership | Domestic fabrication in India circumvents BIS certification delays and import duty exposure for foreign suppliers. |
| Single-Source Equipment Packaging | Unified procurement spanning ice, refrigeration, and dispensing captures specification influence from boutique lounge consolidation. |
| Authorized Service Network Expansion | Technician certification pipelines address scarcity constraining aftermarket revenue capture from glycol system maintenance. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with equipment procurement directors at multi-unit bar groups, NSF certification engineers, and refrigeration service technicians; and secondary validation against SAMR GB standard filings, EU Ecodesign Directive energy labeling databases, and EPA SNAP program refrigerant approval records. Bottom-up equipment shipment estimates triangulated against top-down hospitality construction permits across tier-one Chinese cities and Indian luxury hotel developments.
Across the analysis window, forecasts model product type segmentation by ice maker, draft system, blender, and shaker categories; end-user stratification across bars, hotels, restaurants, and nightclubs; and application intensity across beverage dispensing, mixology, ice production, and food preparation. CAGRs derive from equipment replacement cycle compression tied to regulatory compliance deadlines and experiential format proliferation. Compressor efficiency tier adoption curves and refrigerant transition timelines anchor projection sensitivity.
The analysis sits within stated boundaries; outcomes outside synchronized EPA-EU refrigerant phase-down schedules or sustained tier-one Chinese hospitality investment would require recalibration. Forecasts reflect assumptions regarding certification timeline friction and stainless steel input cost transmission. Revision becomes warranted when technician training pipeline scaling crosses thresholds enabling faster aftermarket service network expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Commercial Kitchen Knife Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Countertop Ice Dispensers Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market
Food Service Equipment
Used Commercial Kitchen Equipment Market
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
North America Commercial Dishwashers Market