
 Slow Cooker and Sous Vide Market | 2026-2036
Slow Cooker and Sous Vide Market Size, Share, and Industry Trends Forecast 2026-2036
Slow Cooker and Sous Vide Market Analytics
Online retail is fragmenting as the primary channel for small kitchen appliance sales, forcing manufacturers to balance direct-to-consumer platforms with legacy wholesale relationships. Instant Brands leverages its digital-native origin to sustain strong e-commerce margins. Hamilton Beach Brands anchors shelf presence through dominant placement in mass-market retail chains. Groupe SEB competes across multiple price tiers through portfolio breadth spanning premium and entry-level thermal cooking equipment.
Slow cookers and sous vide machines are countertop thermal cooking appliances that maintain precise low-temperature environments over extended periods, typically operating between 50°C and 99°C through controlled heating elements and water circulation pumps for sous vide configurations. Their primary commercial purpose centers on labor reduction, menu consistency, and energy efficiency in both residential and professional food preparation environments. Combo devices that merge slow cooking with sous vide functionality are capturing the fastest expansion as consumers seek versatile equipment that minimizes counter space requirements. Programmable settings and Bluetooth connectivity features are concentrating margin pools in the premium tier, where temperature precision and remote monitoring command price premiums over manual cooker alternatives.
The EU F-Gas Regulation and CE marking requirements govern refrigerant and energy efficiency standards for appliances sold across European member states, directly influencing thermal insulation specifications and heating element certifications. The US FDA and USDA provide food safety guidance on time-temperature controls that manufacturers reference in product documentation and warranty terms. Stakeholders must monitor evolving energy labeling frameworks and smart appliance cybersecurity standards as connected kitchen equipment becomes subject to broader digital product regulation.
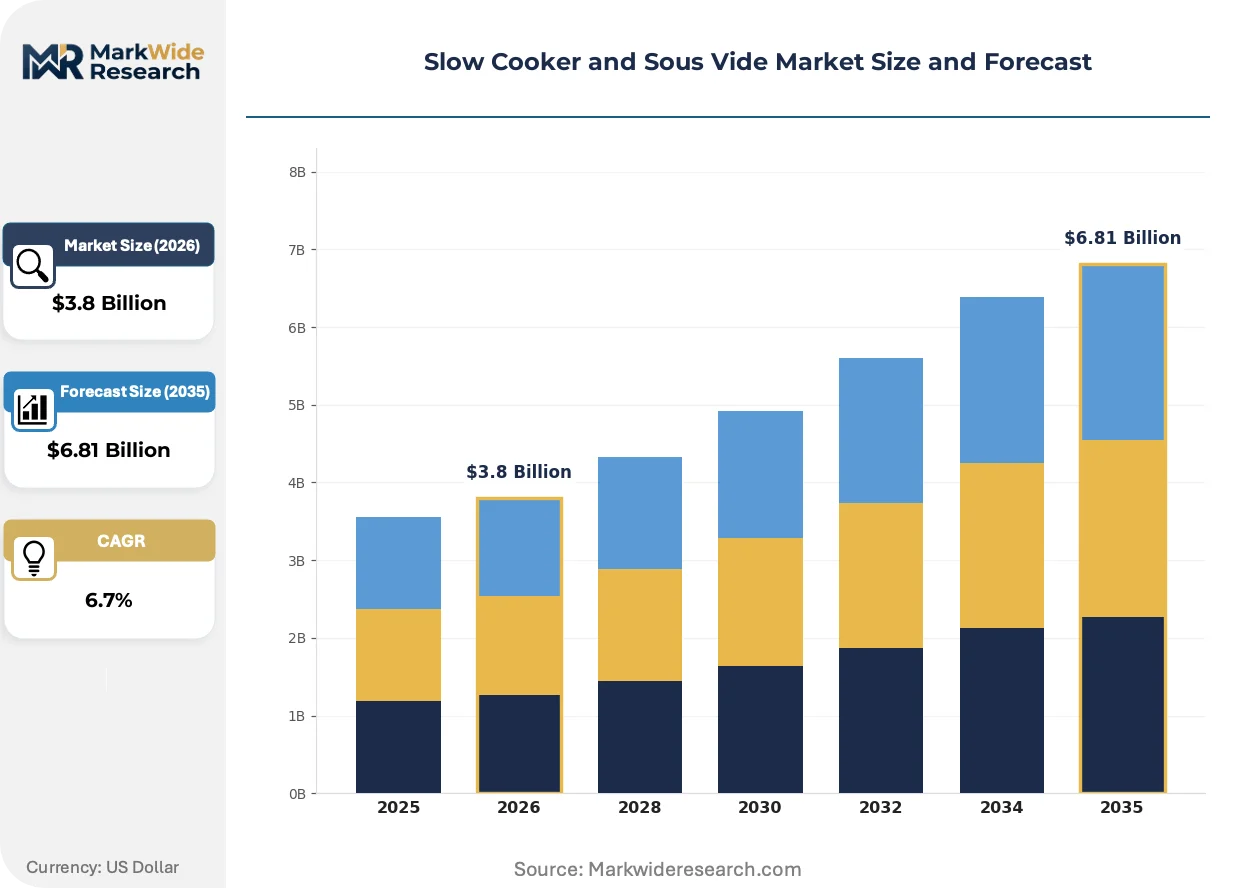
Market Dynamics
Precision thermal equipment is hybridizing across commercial and residential segments as combo slow cooker-sous vide devices compress capital expenditure for hospitality chains and home cooks alike. The EU F-Gas Regulation and energy efficiency mandates are forcing redesign cycles that favor insulated heating systems over conventional resistive elements.
Growth Catalysts
- EU F-Gas Regulation:Appliance manufacturers are accelerating R&D into low-global-warming-potential refrigerant alternatives and improved thermal insulation to meet phasedown schedules through 2030.
- Hospitality labor automation:Restaurant groups in Germany, France, and the United Kingdom are deploying programmable thermal cookers to reduce back-of-house staffing ratios during extended service windows.
- Bluetooth-enabled precision control:Remote temperature monitoring via smartphone applications is commanding price premiums in the premium residential tier, expanding margin pools for connected device portfolios.
Market Restraints
- Heating element supply concentration:Ceramic and stainless-steel heating component manufacturing clusters in East Asia create vulnerability to input cost volatility and logistics disruption.
- Technical precision ceiling:Sous vide water circulation pumps face reliability degradation in high-mineral-content water supplies, limiting deployment in hard-water regions without filtration infrastructure.
- Substitution by combi-ovens:Commercial kitchens with capital budgets for multi-function equipment are redirecting spend toward steam-convection hybrids that replicate low-temperature thermal functions.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden, Norway, and Denmark exhibit low slow cooker household penetration relative to Southern Europe, presenting whitespace for entry-level and mid-tier positioning.
- Smart appliance cybersecurity standards:Emerging IEC and ISO frameworks for connected kitchen equipment create first-mover advantage for manufacturers certifying products ahead of mandatory compliance deadlines.
- Meal-kit subscription bundling:Direct-to-consumer thermal cooker partnerships with prepared-ingredient delivery services are opening channel access beyond traditional retail and e-commerce platforms.
Industry Challenges
- CE marking timeline compression:Evolving energy labeling and electromagnetic compatibility certification requirements in Europe are extending product launch cycles and straining regulatory affairs capacity.
- Integration with legacy kitchen management systems:Commercial buyers demand API connectivity and data export compatibility with existing inventory and temperature logging software, complicating firmware development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slow Cooker and Sous Vide Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slow Cookers, Sous Vide Machines, Combo Devices, Manual Cookers Feature: Programmable Settings, Temperature Control, Timer Function, Bluetooth Connectivity End User: Home Cooks, Professional Chefs, Culinary Institutions, Catering Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Breville Group, Hamilton Beach Brands, Instant Brands, Cuisinart, SharkNinja, Anova Culinary, Groupe SEB, Gourmia, PolyScience Culinary, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slow Cooker and Sous Vide Market Evolving Landscape
Equipment functionality is converging as manufacturers respond to space constraints and capital efficiency pressures across both commercial and residential buyer segments. Three developments are restructuring competitive positioning and technical requirements.
Combo slow cooker-sous vide devices are hybridizing thermal cooking methods into single-countertop units. Restaurant groups in the United Kingdom are piloting these dual-function systems to reduce equipment footprint in compact urban kitchen layouts. The convergence is compressing demand for standalone single-purpose appliances and redirecting procurement toward versatile platforms.
The EU F-Gas Regulation is mandating refrigerant phase-downs that indirectly affect thermal appliance insulation specifications and heating element efficiency certifications. Manufacturers serving European markets are redesigning product enclosures to meet stricter thermal performance thresholds. Germany and France are experiencing the fastest compliance-driven replacement cycles as hospitality chains preempt regulatory deadlines.
Direct-to-consumer subscription bundling is displacing traditional retail attachment selling for small kitchen appliances. Meal-kit services in France and the United Kingdom are partnering with equipment makers to include thermal cookers in long-term ingredient delivery contracts. This channel innovation is most visible in urban residential markets where counter space constraints favor compact multi-function devices over full appliance suites.
Slow Cooker and Sous Vide Market Segmentation
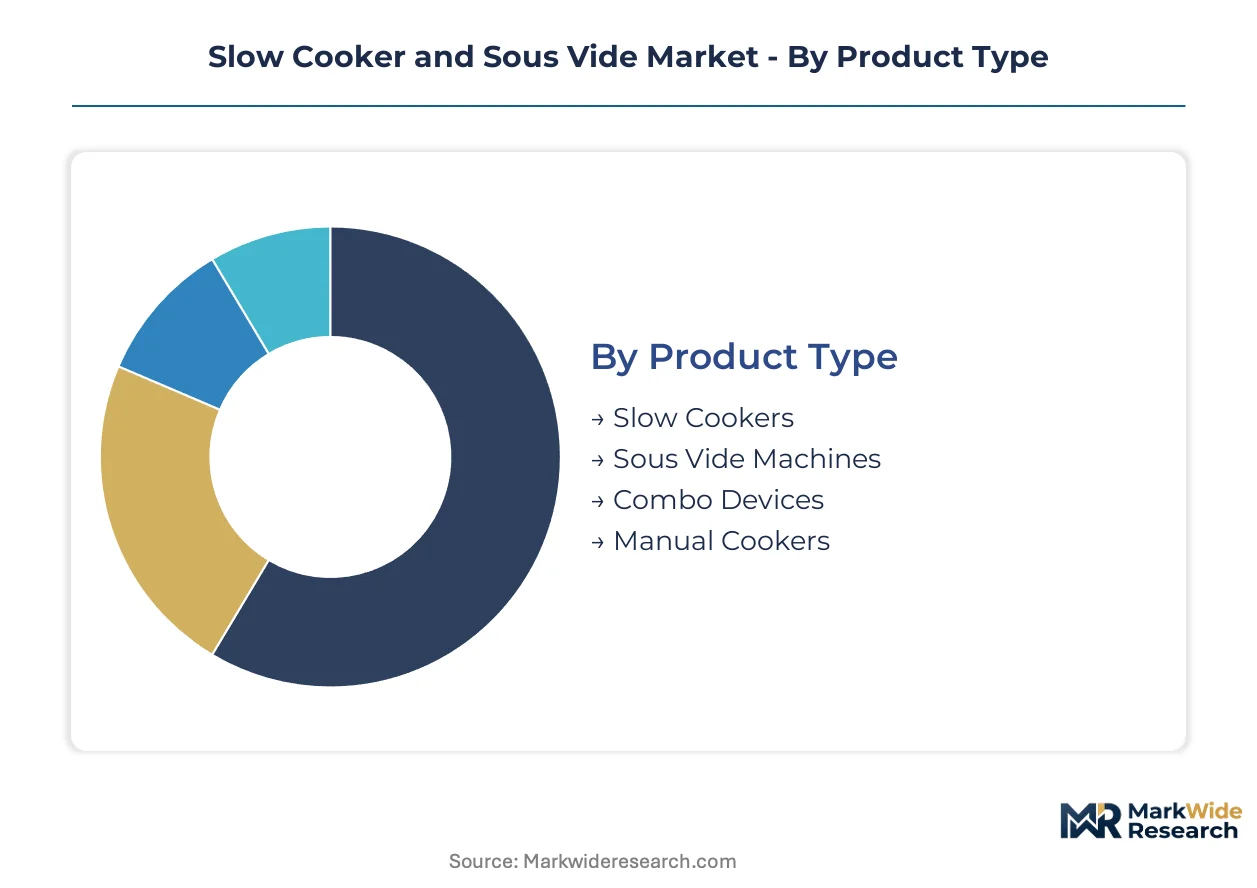
Thermal cooking equipment segments exhibit divergent replacement cycles driven by technology obsolescence, durability differentials, and connectivity upgrade patterns. Understanding these cadences helps manufacturers align inventory planning with demand pulses across residential and commercial buyer bases.
Product Type:
Replacement frequency varies dramatically across product types, with connected combo devices turning over fastest as firmware and app compatibility drive upgrade cycles, while manual cookers persist longest in household inventories.
- Combo Devices:Hybrid slow cooker-sous vide units integrate dual thermal methods into single enclosures with programmable switching between moist-heat and precision water-bath modes. Hospitality chains in the United Kingdom and Germany are standardizing on these platforms to compress kitchen footprints during back-of-house renovations, though higher component density elevates failure rates versus single-purpose alternatives.
- Slow Cookers:Conventional ceramic-crock or stainless-steel vessels with resistive heating elements dominate residential installed base in France and the United States, where established cooking traditions sustain demand for set-and-forget meal preparation without precision requirements.
- Sous Vide Machines:Immersion circulators and water ovens with PID temperature control and sub-0.1°C stability serve professional kitchens and enthusiast home cooks seeking precise protein texture outcomes.
- Manual Cookers:Basic dial-controlled thermal vessels without digital interfaces persist in price-sensitive segments and developing markets where electricity reliability concerns favor mechanical simplicity.
Manual cookers dominate installed base. Combo devices are where expansion concentrates.
Feature:
Feature stratification tracks buyer sophistication and willingness to pay for precision, with connectivity premiums commanding widest spreads in urban residential markets.
- Bluetooth Connectivity:Smartphone-integrated thermal cookers enable remote temperature monitoring, recipe library access, and push notifications for cycle completion. Residential buyers in Germany and France absorb 40-60% price premiums for these capabilities, expanding margin pools for manufacturers with mature app ecosystems.
- Programmable Settings:Multi-stage cooking profiles with automatic transitions between temperature phases support unattended preparation of complex dishes. Professional kitchens in the United Kingdom deploy these features to reduce labor touchpoints during extended service windows.
- Temperature Control:PID or thermistor-based feedback systems maintaining ±0.5°C or tighter stability form the technical foundation of sous vide functionality and premium slow cooker positioning.
- Timer Function:Basic delay-start and automatic shutoff capabilities represent minimum viable electronics for mid-tier residential positioning.
Timer function dominates installed base. Bluetooth connectivity is where expansion concentrates.
End User:
End user segmentation reflects divergent performance requirements, with commercial buyers prioritizing durability certifications and API integration while residential segments emphasize ease of use and counter space efficiency.
- Professional Chefs:Restaurant and hotel kitchen operators specify thermal equipment with NSF International certification, stainless-steel construction, and compatibility with HACCP temperature logging protocols. Procurement concentrates in Germany, France, and the United Kingdom as hospitality chains upgrade back-of-house infrastructure.
- Catering Services:Mobile and event-focused food service operators demand portable thermal cookers with robust transit tolerance and rapid heat recovery after lid opening.
- Home Cooks:Residential buyers prioritize compact footprints, dishwasher-safe components, and intuitive interfaces for weeknight meal preparation.
- Culinary Institutions:Cooking schools and training programs require equipment with transparent construction for instructional visibility and standardized performance across student stations.
Home cooks dominate installed base. Professional chefs are where expansion concentrates.
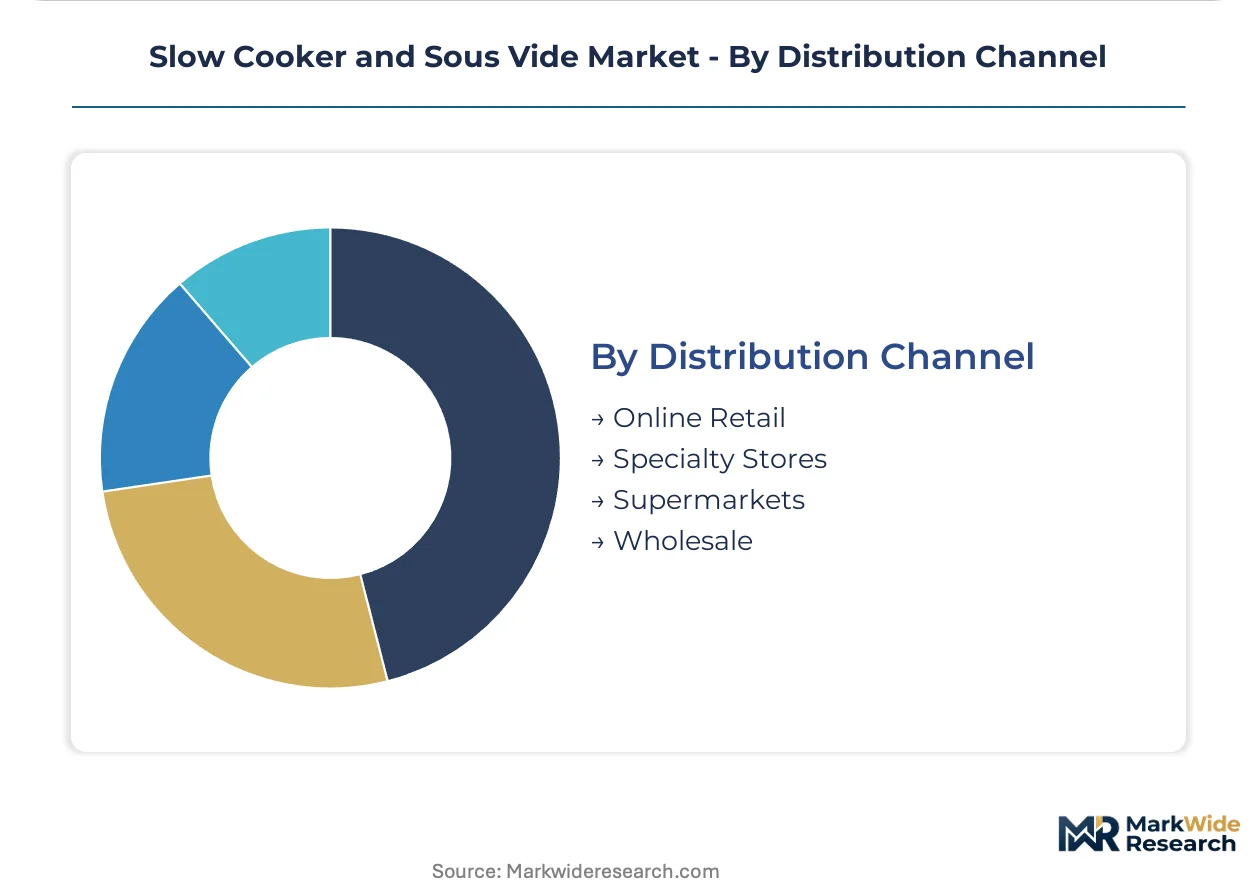
Distribution Channel:
Channel mix is shifting as direct-to-consumer platforms capture share from legacy wholesale relationships, though mass retail retains anchoring power for entry-tier volume.
- Online Retail:E-commerce platforms and manufacturer-direct storefronts enable specification-rich purchasing journeys with review aggregation and comparison tools. Digital-native brands leverage this channel to sustain margin structures unavailable through wholesale intermediaries.
- Wholesale:Hospitality supply distributors and group purchasing organizations dominate commercial procurement, offering volume pricing and consolidated delivery logistics for multi-unit restaurant operators.
- Specialty Stores:Kitchenware boutiques and restaurant supply showrooms provide tactile evaluation and staff consultation for premium residential and small commercial buyers.
- Supermarkets:Mass-market retail chains anchor entry-tier and seasonal promotional volume, particularly for manual cookers and gift-oriented packaging.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospitality chains command 15-20% price premiums for precision thermal equipment versus comparable French procurement, reflecting tighter labor markets and faster regulatory compliance cycles. This asymmetry concentrates manufacturer R&D investment toward German certification standards.
Germany
Restaurant groups in Berlin and Munich are deploying combo slow cooker-sous vide systems to reduce back-of-house staffing ratios during extended service windows. The EU F-Gas Regulation is accelerating replacement cycles for thermal insulation specifications ahead of 2030 phasedown deadlines. Bavaria's commercial kitchen equipment cluster is hosting pilot programs for Bluetooth-enabled inventory integration.
France
Meal-kit subscription services in Paris and Lyon are bundling compact thermal cookers with long-term ingredient delivery contracts. ANSM and DGCCRF enforcement of smart appliance cybersecurity standards is creating pre-certification advantages for connected device portfolios. The Île-de-France region is concentrating hospitality chain procurement for urban kitchen footprint reduction.
United Kingdom
Hospitality operators in London and Manchester are standardizing on dual-function thermal platforms to compress equipment footprints during back-of-house renovations. CE marking timeline compression for electromagnetic compatibility is extending product launch cycles. Scotland's culinary training institutions are requiring transparent-construction equipment for instructional visibility.
United States
Residential buyers in California and New York Metro absorb 40-60% price premiums for Bluetooth-connected precision cookers. FDA and USDA time-temperature control guidance shapes manufacturer warranty documentation. The Pacific Northwest is emerging as a testbed for sous vide water circulation reliability in high-mineral-content supply zones.
Japan
Professional kitchens in Tokyo and Osaka specify thermal equipment with METI energy efficiency labeling and JIS construction standards. Compact countertop footprints dominate residential demand in dense urban markets. The Kansai region is hosting firmware development for API compatibility with legacy kitchen management systems.
Slow Cooker and Sous Vide Market Competitive Landscape
Digital-native specialists and legacy mass-market manufacturers split the market into divergent margin structures. The vendor base concentrates around three strategic archetypes: e-commerce-anchored direct-to-consumer platforms, mass-retail shelf-dominant conglomerates, and precision-equipment specialists serving commercial kitchens. Competitive moves center on portfolio diversification into combo-function devices and geographic expansion through meal-kit subscription bundling partnerships.
Within the digital-native tier, Instant Brands exemplifies direct-to-consumer margin sustainability through app ecosystem maturity. Hamilton Beach Brands anchors mass-market retail presence through dominant shelf placement in North American chains. Groupe SEB occupies a position spanning multiple price tiers through portfolio breadth. These three archetypes represent the competitive tension between e-commerce agility and wholesale scale efficiency.
| Leading Market Players |
|---|
| Breville Group |
| Hamilton Beach Brands |
| Instant Brands |
| Cuisinart |
| SharkNinja |
| Anova Culinary |
| Groupe SEB |
| Gourmia |
| PolyScience Culinary |
| Others |
Value Network & Pricing Analysis
Overcapacity in East Asian heating element manufacturing clusters is compressing supplier margins while simultaneously expanding procurement leverage for branded appliance assemblers in Germany and France. This utilization asymmetry allows manufacturers to extract volume discounts on ceramic resistive components while maintaining premium positioning for Bluetooth-enabled precision cookers in residential markets.
Pricing Analysis
The customization-premium spread separates configured-to-order commercial units with API integration and HACCP logging from standard manual cookers sold through mass retail. Three-tier pricing structure across premium, standard, and economy levels tracks connectivity sophistication and certification grade, with NSF-certified stainless-steel construction commanding widest spreads. Cost compression in entry-tier manual cookers is intensifying because supermarket private-label expansion redirects volume away from branded alternatives. Hospitality procurement teams exhibit lowest price sensitivity due to labor-cost arbitrage calculations, while residential buyers in developing markets absorb minimal premiums for connectivity features.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for manufacturers sourcing PID controllers and water circulation pumps. Component manufacturing concentrates in China, South Korea, and Vietnam, with final assembly gravitating toward Poland and Mexico to satisfy regional content requirements. Thermal insulation materials and precision thermistors draw from petrochemical feedstocks concentrated in Middle Eastern and North American production hubs. Single-source vulnerability persists for sub-0.1°C stability sensors used in professional sous vide equipment. Distribution runs through hospitality supply distributors for commercial volume and e-commerce platforms for residential direct-to-consumer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as hospitality group purchasing organizations consolidate procurement across multi-unit restaurant operators in the United Kingdom and Germany. This consolidation fragments pricing power away from equipment manufacturers toward consolidated buyers with volume leverage.
For Market Incumbents: Build switching-cost moats through app ecosystem maturity and firmware-locked recipe libraries that raise replacement barriers for connected device users. Defensive moves center on preemptive CE marking for electromagnetic compatibility ahead of timeline compression and backward integration into heating element supply to reduce East Asian input volatility. The combi-oven substitution threat from commercial kitchen equipment rivals demands continuous precision-feature differentiation. For New Entrants and Emerging Players: Build out meal-kit subscription bundling partnerships as a channel bypass for retail shelf-access barriers, targeting urban residential markets in France and the United Kingdom where counter space constraints favor compact combo devices. The most penetrable segment lies in underpenetrated Nordic markets—Sweden, Norway, and Denmark—where slow cooker household penetration trails Southern Europe. Direct-to-consumer digital-native positioning with sustainability certification alignment offers viable go-to-market entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital-native brands with established app ecosystems and subscription-enabled firmware update revenue streams. Long-term viability across the analysis window favors manufacturers with dual commercial-residential exposure that buffers segment-specific downturns. Acquisition targets should demonstrate CE marking readiness and API compatibility with legacy kitchen management systems. The signal to watch is hospitality capital expenditure intention surveys from Germany and France as inflection indicators for professional-grade equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Combo Device Portfolio Expansion | Captures hospitality footprint reduction demand in United Kingdom urban kitchen renovations. |
| Smart Appliance Cybersecurity Certification | Creates first-mover advantage under emerging IEC and ISO frameworks for connected kitchen equipment. |
| Meal-Kit Subscription Bundling | Opens channel access beyond traditional retail through partnerships with prepared-ingredient delivery services in France. |
| Thermal Insulation Redesign | Accelerates compliance with EU F-Gas Regulation phasedown schedules through 2030. |
| API Integration Development | Addresses commercial buyer demands for compatibility with existing inventory and temperature logging software. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with equipment procurement directors at hospitality chains, product development leads at appliance manufacturers, regulatory affairs specialists, and meal-kit service operations managers; and secondary validation through customs records, EU energy labeling databases, SEC filings of listed appliance manufacturers, and hospitality industry capital expenditure surveys. Bottom-up triangulation against top-down market sizing ensured consistency across volume and value estimates.
Forecast inputs considered replacement cycle dynamics across product types, regulatory compliance-driven replacement waves under EU F-Gas Regulation timelines, and connectivity upgrade patterns in residential segments. Segmentation dimensions modeled include product type, feature tier, end-user category, and distribution channel, with geographic adoption patterns calibrated against regional regulatory frameworks. CAGRs were derived from installed base turnover rates and expansion coefficients for emerging segments such as combo devices and Bluetooth-enabled units.
Practitioners should monitor regulatory timeline shifts for CE marking and cybersecurity standards, raw material cost volatility in ceramic and stainless-steel components, and hospitality labor market tightness in Germany and France for early signals of demand revision. Forecasts reflect assumptions about sustained regulatory enforcement and stable input cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Coffee Equipment and Supplies Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Commercial Foodservice Equipment Market
Food Service Equipment
Multi Cooker Market