
 Ice Cube Tray Market | 2026-2036
Ice Cube Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cube Tray Market Insights
Single-source reliance on Asian contract manufacturers is restructuring as brands diversify mold-production across Vietnam, Mexico, and domestic U.S. facilities to reduce lead-time exposure. Tovolo leverages in-house silicone formulation labs in Colorado to control material consistency across its novelty-shaped lines. OXO sustains premium positioning through engineered release mechanisms that differentiate its stackable designs from commodity alternatives. Rubbermaid anchors mass-market volume through big-box retail partnerships and standardized cavity dimensions that dominate American freezer compatibility.
An ice cube tray is a molded container, typically fabricated from silicone, polypropylene, thermoplastic elastomer, or stainless steel, designed to freeze water into discrete geometric or custom shapes for beverage cooling and food preservation; cavity dimensions generally range from 20 mm to 60 mm per cell, with wall thicknesses optimized for thermal transfer efficiency and mechanical release. Silicone and stainless-steel formats command expanding margin pools as consumers migrate away from legacy plastics amid chemical-safety scrutiny, while specialty shapes including spheres and oversized cubes capture disproportionate value in the mixology segment despite representing smaller unit volumes. Plastic remains structurally dominant in absolute shipment terms but sits in a mature, price-compressed tier where stackable utility designs with integrated lids sustain baseline replacement demand.
The U.S. FDA maintains food-contact substance regulations that govern polymer additives in freezer-safe plastics, while the EPA tracks per- and polyfluoroalkyl substance concerns affecting non-stick coatings in some tray variants; REACH compliance in Europe bars certain phthalates and bisphenol derivatives, compelling reformulation across export-bound product lines. China's SAMR enforces GB standards for silicone products that constrain cross-border sourcing flexibility for brands without certified supply-chain documentation. Stakeholders must monitor evolving state-level chemical disclosure laws in California and New York that could fragment compliance requirements beyond federal baselines, and calibrate material portfolios accordingly before shelf-access restrictions materialize.
Market Dynamics
REACH chemical-safety mandates are accelerating material substitution across European supply chains, forcing simultaneous reformulation of silicone catalysts and elimination of legacy plasticizers while Asian contract manufacturers scramble to retain export access.
Growth Catalysts
- Mixology Culture Maturation:Craft cocktail bars in the United States and Western Europe now specify sphere and oversized cube formats as standard equipment, creating pull-through demand for premium silicone molds in adjacent home entertaining segments.
- EuP Efficiency Standards:Energy-using product directives incentivize freezer-optimized designs that reduce thermal mass and electricity draw, rewarding manufacturers with thinner-wall stainless-steel and advanced elastomer formulations.
- Silicone Chemistry Advances:Platinum-cured silicone systems now achieve food-grade purity thresholds without post-curing residue, unlocking direct-to-consumer positioning previously blocked by odor and taste concerns.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and thermoplastic elastomer input costs fluctuate with naphtha cracking margins, compressing mass-market tray margins during energy price spikes.
- Zhejiang Province Concentration:Mold fabrication and silicone compounding capacity clusters in eastern China, exposing brands to single-point disruption from port congestion or regional power rationing.
- Thermal Conductivity Tradeoffs:Silicone's insulating properties extend freeze times versus metal alternatives, limiting adoption in commercial foodservice settings where speed governs workflow.
Strategic Opportunities
- Mexico Nearshoring Expansion:Monterrey and Tijuana industrial parks offer tariff-advantaged production for U.S. bound shipments, with silicone formulation expertise deepening through cross-border technical partnerships.
- Smart Appliance Integration:Connected freezer systems from appliance OEMs create data-layer opportunities for trays with embedded RFID or temperature-responsive indicators that signal optimal release timing.
- California SB 54 Implementation:Extended producer responsibility for plastic packaging creates competitive opening for durable, multi-decade lifespan stainless-steel and silicone alternatives in the state's premium retail channels.
Industry Challenges
- Platinum Catalyst Sourcing:Food-grade silicone vulcanization depends on scarce precious metal supply concentrated in South African and Russian mining operations, creating formulation cost unpredictability.
- Multi-Jurisdiction Certification Lag:Simultaneous FDA, EFSA, and SAMR material approvals require 18-24 month validation cycles, delaying new product launches behind formulation innovation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cube Tray Market |
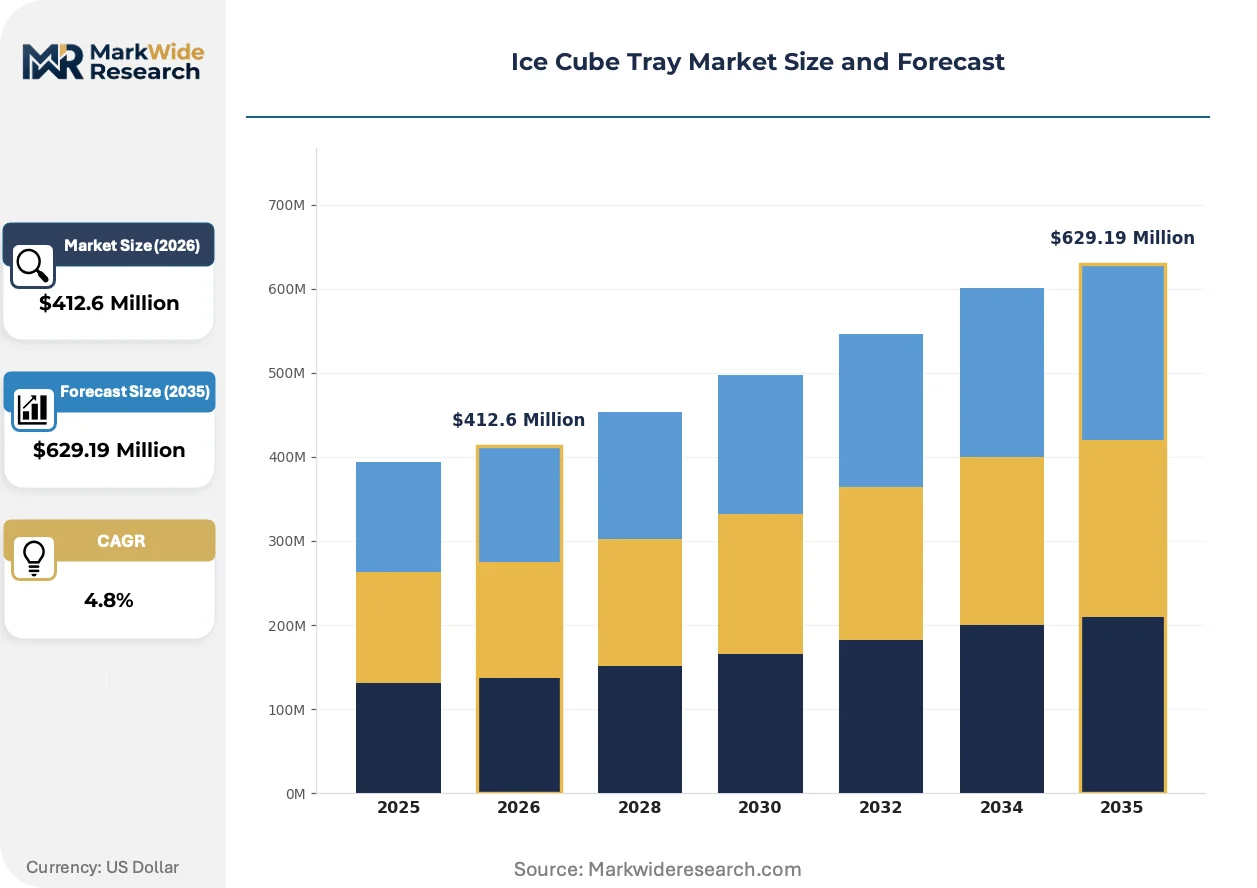
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Silicone, Stainless Steel, Rubber Shape: Cube, Sphere, Nugget, Specialty Capacity: Standard, Large, Mini, Flexi Design: Regular, Stackable, Novelty, Stackable with Lid |
| Companies Covered | Tovolo, OXO, Rubbermaid, Lekue, Glacio, W&P Design, Samuelworld, The Original Whiskey Ball, Onyx Containers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cube Tray Market Trends and Innovations
Material science breakthroughs and regulatory chemistry constraints are converging to redefine product architecture, with functional performance and compliance certification now inseparable design variables rather than sequential development stages.
Platinum-cured liquid silicone rubber is overtaking peroxide-cured alternatives in premium tray manufacturing due to elimination of volatile byproducts. Home mixology enthusiasts and boutique hospitality suppliers are adopting these formulations within single purchase cycles. The technology is overtaking commodity silicone positioning by enabling direct mouth-contact safety claims that justify 3-4x price multiples over legacy alternatives.
REACH Annex XVII restrictions on phthalates and bisphenol-A derivatives are compelling wholesale polymer reformulation across export-bound product lines. Manufacturers serving EU markets must now certify entire supply chains from catalyst to finished goods, not merely final articles. Small-batch artisan brands without dedicated compliance infrastructure are ceding shelf space to scaled competitors with in-house regulatory affairs functions.
Specialty beverage retailers now curate ice preparation as a distinct equipment category alongside bar tools and glassware, unbundling trays from general kitchenware merchandising. This channel evolution elevates discovery and education touchpoints that commodity big-box placement cannot replicate. The shift concentrates in coastal U.S. metropolitan markets where independent kitchenware boutiques anchor neighborhood retail corridors.
Ice Cube Tray Market Segmentation
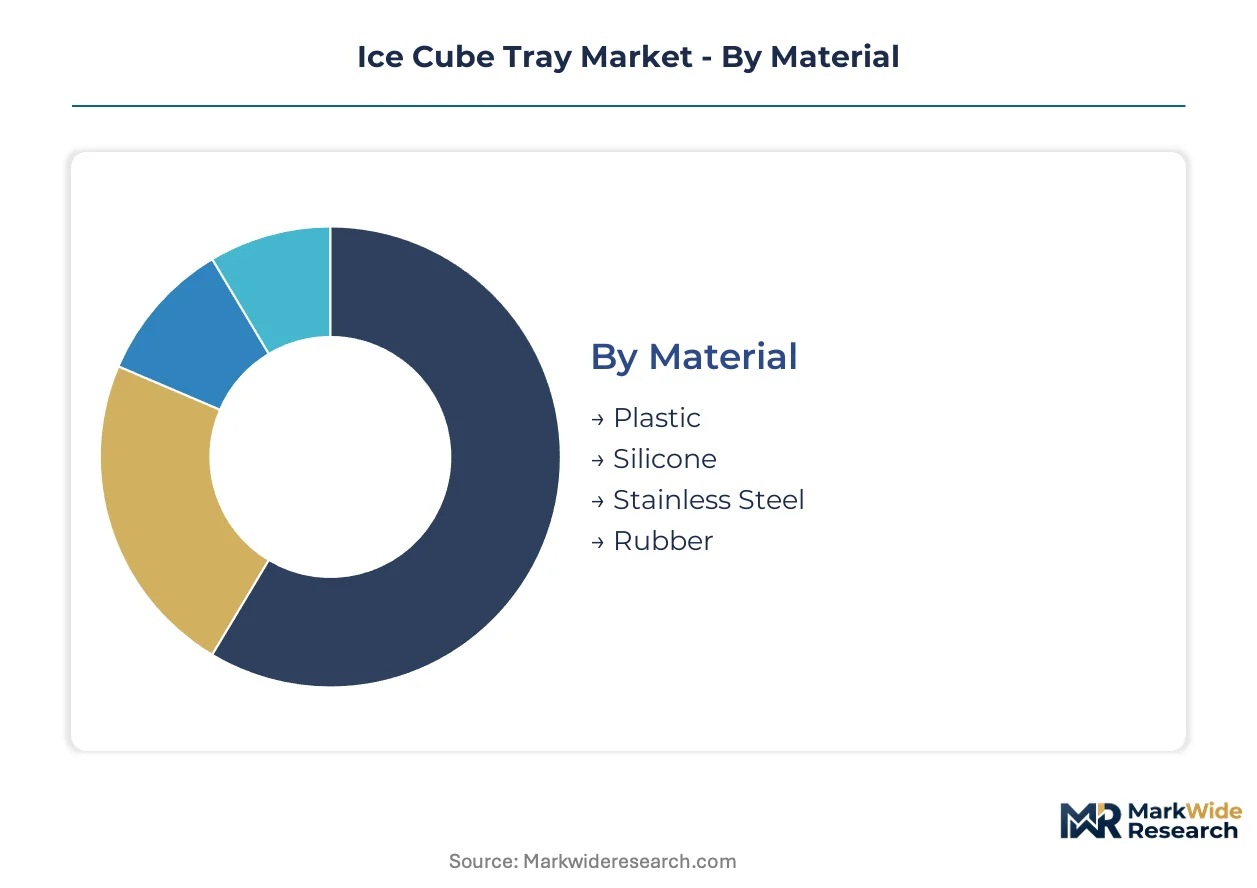
Material chemistry and cavity geometry determine thermal performance, release mechanics, and compliance pathways in ice cube tray manufacturing. Segment boundaries increasingly blur as hybrid constructions and multi-format product lines respond to fragmented end-use requirements.
Material:
Silicone and stainless steel function as standalone premium formats with distinct supply chains, while plastic and rubber remain embedded in mass-market utility systems with tighter retail integration.
- Silicone:Platinum-cured liquid silicone rubber achieves food-grade purity without post-curing residue. Demand concentrates in United States coastal metropolitan markets where craft cocktail culture drives adoption of sphere and oversized cube molds.
- Stainless Steel:Thin-wall stamped or welded construction optimizes thermal conductivity for rapid freeze cycles. Commercial foodservice settings in Western Europe favor this format despite higher unit costs, prioritizing workflow speed over capital expenditure.
- Plastic:Polypropylene homopolymer dominates freezer-safe injection molding with standardized cavity dimensions compatible with American appliance specifications.
- Rubber:Thermoplastic elastomer compounds offer intermediate flexibility at lower price points than silicone, serving replacement demand in big-box retail channels.
Plastic leads volumes today; silicone is gaining share fastest.
Shape:
Cost tiers separate commodity geometric formats from precision-engineered specialty molds commanding 3-4x price multiples through mixology channel positioning.
- Cube:Orthogonal cavity arrays with 20-60 mm cell dimensions remain the baseline reference format. Mass-market replacement cycles sustain volume across United States big-box retail partnerships where freezer compatibility governs purchase decisions.
- Sphere:Single or dual-cavity spherical molds require advanced silicone formulation for seamless release. Boutique hospitality suppliers in Western Europe specify this format as standard equipment, creating pull-through demand in adjacent home entertaining segments.
- Nugget:Small irregular cavities produce chewable ice fragments favored by soft-drink enthusiasts. This format occupies a mid-tier pricing position between commodity cubes and premium spheres.
- Specialty:Custom geometric or branded shapes serve promotional and gift-market applications with seasonal demand concentration.
Cube configurations dominate absolute shipment terms; sphere formats exhibit the steepest expansion trajectory.
Capacity:
Application context determines optimal cell count, with commercial foodservice requiring rapid batch production and residential use prioritizing storage efficiency.
- Standard:12-16 cavity arrays balance freeze time against output volume for typical household consumption patterns.
- Large:24+ cell configurations serve high-throughput commercial environments or extended entertaining occasions.
- Mini:32-48 small cavities accelerate cooling surface area for blended beverages and rapid-chill applications.
- Flexi:Modular or expandable systems allow user-configurable capacity adjustment based on seasonal demand fluctuations.
Standard capacity maintains the largest installed base; mini formats are climbing the fastest in unit growth.
Design:
Customer type stratification separates price-sensitive utility purchasers from design-conscious premium buyers seeking aesthetic integration with kitchen décor.
- Regular:Basic cavity arrays without ancillary features occupy entry-level pricing tiers with minimal differentiation.
- Stackable:Interlocking vertical profiles maximize freezer storage density. This format anchors Rubbermaid's mass-market positioning through engineered dimensional standardization.
- Novelty:Thematic shapes and colors target gift-market and seasonal purchase occasions with higher margin structures but irregular demand patterns.
- Stackable with Lid:Integrated cover systems prevent spillage and odor absorption during freeze cycles. OXO sustains premium positioning through patented release mechanisms in this configuration.
Stackable designs lead current volume; stackable-with-lid variants show the strongest share gain momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang Province concentration in mold fabrication and silicone compounding anchors Asia-Pacific supply capacity, while demand generation concentrates in North American and European metropolitan markets where craft beverage culture penetrates deepest. Regulatory divergence between FDA food-contact substance rules and REACH chemical-safety mandates is fragmenting material certification pathways across export destinations. Production diversification into Vietnam and Mexico is accelerating as brands reduce single-source exposure to eastern Chinese industrial clusters.
United States
Craft cocktail bars in New York, Los Angeles, and Chicago now specify sphere and oversized cube formats as standard equipment, creating pull-through demand for premium silicone molds in adjacent home entertaining segments. The FDA maintains food-contact substance regulations that govern polymer additives in freezer-safe plastics, while California's SB 54 extended producer responsibility law creates competitive openings for durable stainless-steel alternatives. Tovolo operates in-house silicone formulation labs in Colorado to control material consistency across novelty-shaped product lines.
China
Domestic consumption of specialty ice formats is rising in Shanghai and Beijing as Western beverage culture penetrates tier-one urban centers. The State Administration for Market Regulation enforces GB standards for silicone products that constrain cross-border sourcing flexibility for brands without certified supply-chain documentation. Mold fabrication and silicone compounding capacity clusters in Zhejiang Province, exposing brands to single-point disruption from Ningbo port congestion or regional power rationing.
Germany
Commercial foodservice settings in Berlin, Munich, and Hamburg favor thin-wall stainless-steel trays despite higher unit costs, prioritizing workflow speed over capital expenditure in high-throughput bar operations. ECHA's REACH Annex XVII restrictions on phthalates and bisphenol-A derivatives compel wholesale polymer reformulation across export-bound product lines. Industrial parks in North Rhine-Westphalia host specialized metal-stamping operations serving premium kitchenware brands with EU-certified fabrication.
United Kingdom
Independent kitchenware boutiques in London and coastal metropolitan corridors now curate ice preparation as a distinct equipment category alongside bar tools and glassware. The UK's post-Brexit regulatory alignment with EU chemical-safety standards maintains REACH-equivalent constraints on food-contact materials. Specialty beverage retailers in Shoreditch and Notting Hill anchor neighborhood retail corridors where discovery-driven purchasing elevates premium silicone positioning.
Mexico
Nearshoring expansion into Monterrey and Tijuana industrial parks offers tariff-advantaged production for U.S.-bound shipments as brands diversify mold-production away from Asian contract manufacturers. Mexico's federal consumer protection agency enforces NOM standards for food-contact articles that align with FDA baselines, easing cross-border certification. Silicone formulation expertise is deepening through cross-border technical partnerships with Colorado-based material science operations.
Ice Cube Tray Market Competitive Landscape
Global majors compete with regional champions across material science capabilities and regulatory compliance infrastructure, producing a tiered structure where scaled silicone compounders face off against specialized metal fabricators and mass-market plastic molders. The vendor base separates into three strategic archetypes: platinum-cured silicone specialists commanding 3-4x price multiples through mixology channel positioning, stainless-steel stampers serving commercial foodservice workflow requirements, and polypropylene injection molders anchoring big-box retail volume through dimensional standardization. Dominant competitive moves include geographic diversification of mold-production capacity and vertical integration into in-house material formulation laboratories.
Within the platinum-cured silicone tier, Tovolo and W&P Design exemplify premium positioning through controlled material science and design-forward cavity geometries. Among mass-market utility providers, Rubbermaid anchors volume through engineered dimensional standardization and big-box retail penetration. OXO occupies a position between these tiers, sustaining above-commodity pricing through patented release mechanisms and stackable-with-lid configurations that differentiate from baseline alternatives.
| Leading Market Players |
|---|
| Tovolo |
| OXO |
| Rubbermaid |
| Lekue |
| Glacio |
| W&P Design |
| Samuelworld |
| The Original Whiskey Ball |
| Onyx Containers |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Zhejiang Province anchor mold fabrication capacity, their conservative balance sheets limiting aggressive pricing even as platinum catalyst costs fluctuate. This ownership pattern concentrates supply discipline in eastern China while pricing power accrues to brands with captive silicone formulation labs in Colorado or North Rhine-Westphalia.
Pricing Analysis
Petrochemical feedstock volatility in naphtha cracking margins passes through to polypropylene tray pricing within one to two quarters, compressing mass-market margins during energy price spikes. Three-tier pricing structure across premium, standard, and economy levels separates platinum-cured silicone specialists from thermoplastic elastomer intermediates and commodity polypropylene injection molders. Price differentiation rests on FDA certification tier and geographic delivery cost, with California and New York buyers absorbing premium logistics. Pricing pressure stems from REACH compliance investments in European-bound product lines. Mass-market plastic buyers exhibit highest price sensitivity; boutique hospitality suppliers in coastal U.S. metropolitan markets show least.
Supply Chain Analysis
Skilled silicone compounding technicians are scarcest in Monterrey and Tijuana industrial parks, constraining nearshoring expansion velocity despite tariff advantages. Geographic supply concentration clusters in China, Vietnam, and Mexico, with mold fabrication drawing from Zhejiang while secondary forming shifts southward. Raw material dependencies center on platinum catalysts from South African mining operations, medical-grade silicone polymers, and food-contact-certified polypropylene resins. Single-source vulnerability in eastern Chinese industrial clusters exposes brands to Ningbo port congestion or regional power rationing. Distribution runs through big-box retail partnerships for mass-market volume and specialty beverage retailers for premium silicone positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ice cube tray market functions as a stable compounder, with craft cocktail culture penetration in coastal U.S. metropolitan markets generating replacement-cycle demand that smooths revenue volatility.
For Market Incumbents: Cement platinum-cured silicone formulation capabilities through in-house laboratory investment or technical partnership with Colorado-based material science operations. Acquire certified supply-chain documentation for SAMR GB standards compliance before shelf-access restrictions materialize in cross-border channels. Defend against Zhejiang Province concentration risk by qualifying secondary mold-production capacity in Monterrey or Tijuana industrial parks.
For New Entrants and Emerging Players: Capture independent kitchenware boutique channels in London, New York, and Los Angeles where discovery-driven purchasing elevates premium positioning beyond big-box price compression. Target sphere and oversized cube formats in adjacent home entertaining segments, the most penetrable white space behind established craft cocktail bar specifications. Pursue direct-to-consumer launch with educational content on platinum-curing purity thresholds to justify 3-4x price multiples.
For Investors and Strategic Acquirers: Valuations sit cheapest among mass-market polypropylene molders facing margin compression from petrochemical feedstock volatility and REACH compliance investment requirements. Long-term viability favors platinum-cured silicone specialists with in-house formulation labs and multi-jurisdiction certification infrastructure across FDA, EFSA, and SAMR pathways. Watch California SB 54 implementation pace as inflection indicator for durable stainless-steel and silicone alternative demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platinum-Cured Silicone Lab Investment | Tovolo's Colorado formulation control enables 3-4x price multiples through purity claims. |
| Nearshoring Capacity Qualification | Monterrey industrial park expansion reduces lead-time exposure from Ningbo port congestion. |
| Multi-Jurisdiction Certification Buildout | Simultaneous FDA, EFSA, and SAMR approvals delay new launches 18-24 months without dedicated infrastructure. |
| Specialty Retail Channel Entry | Independent kitchenware boutiques in Shoreditch and Notting Hill anchor discovery-driven premium positioning. |
| REACH-Compliant Material Reformulation | ECHA Annex XVII restrictions on phthalates compel wholesale polymer substitution across export-bound lines. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region's manufacturing clusters and demand centers. The analysis combines primary interviews with silicone formulation chemists, specialty beverage retail buyers, commercial foodservice procurement managers, and regulatory affairs specialists with secondary validation from FDA food-contact substance filings, ECHA REACH Annex XVII updates, SAMR GB standard documentation, and customs trade data. Bottom-up shipment estimates by material, shape, and capacity tier triangulate against top-down market sizing derived from big-box retail partnership disclosures and platinum catalyst import records.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with mix-shift toward premium silicone and stainless-steel formats modeled independently from baseline replacement demand. Segmentation dimensions include material chemistry, cavity geometry, capacity configuration, and design complexity, cross-referenced against regional regulatory cluster and channel archetype. CAGRs derive from regression analysis of historical shipment patterns and elasticity estimates around craft cocktail culture penetration and REACH compliance investment cycles. Forecast inputs incorporate platinum catalyst price volatility indices and freezer appliance specification standardization trends.
Feedstock cost spikes, regulatory enforcement acceleration, and port congestion events are the dominant revision risks to modeled trajectories. Forecasts reflect assumptions about continued mixology culture maturation and silicone chemistry advance timelines without guarantee. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Multi Cooker Market
Food Service Equipment
Commercial Convection Ovens Market