
 Prebiotic Fiber Market | 2026-2036
Prebiotic Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Prebiotic Fiber Market Outlook
Direct-to-manufacturer ingredient supply contracts is reshaping how prebiotic fiber reaches end-product formulation labs. BENEO leverages its Belgian chicory root processing infrastructure to dominate European inulin supply chains. Tate & Lyle sustains North American market presence through corn-derived soluble fiber technology leadership. Cargill competes across multiple prebiotic categories with integrated agricultural sourcing that controls raw material cost volatility.
Prebiotic fiber comprises non-digestible carbohydrate compounds—typically inulin, fructooligosaccharides, and galactooligosaccharides—fermented selectively by host gastrointestinal microbiota to produce short-chain fatty acids. These ingredients must achieve minimum purity thresholds and demonstrate bifidogenic activity through validated in vitro fermentation protocols to qualify for functional food applications. Inulin and galacto-oligosaccharides command the largest volume positions due to decades of clinical substantiation and infant formula regulatory acceptance. Xylo-oligosaccharides represent the fastest-expanding product type as Chinese and Japanese producers scale agricultural waste conversion technologies. Functional foods and nutritional bars concentrate margin pools because brand owners pay ingredient premiums for substantiated digestive health positioning.
FDA dietary fiber definition updates under the Nutrition Facts Label rule determine which isolated fibers qualify for gram declarations on U.S. packaged foods. EFSA health claim authorization pathways under Regulation 1924/2006 gate European market access for prebiotic positioning statements. Japan's Foods for Specified Health Uses system administered by the Consumer Affairs Agency creates a separate premium pathway for FOSHU-approved prebiotic ingredients. Stakeholders must monitor evolving microbiome characterization standards and jurisdiction-specific substantiation thresholds to allocate R&D and regulatory affairs resources effectively.
Market Dynamics
Clean-label formulation mandates from retail buyers are compressing conventional additive margins and forcing ingredient suppliers to demonstrate microbiome substantiation through validated in vitro protocols. This pressure cascades through supply chains as manufacturers seek bifidogenic fibers with regulatory pre-approval in multiple jurisdictions.
Growth Catalysts
- EFSA Article 13.1 Health Claims:Authorized prebiotic positioning statements under Regulation 1924/2006 create premium pricing power for substantiated inulin and galacto-oligosaccharide suppliers in European functional foods.
- Infant Formula Fortification:Regulatory acceptance of GOS in early-life nutrition drives volume commitments from multinational dairy processors seeking gut microbiome differentiation.
- Chinese XOS Scale-Up:Agricultural waste conversion technologies for xylo-oligosaccharides expand feedstock access beyond chicory root and corn starch dependencies.
Market Restraints
- Chicory Root Concentration:European inulin supply chains depend on Belgian and Dutch agricultural processing infrastructure vulnerable to climate-induced root yield volatility.
- FDA Definition Uncertainty:Evolving isolated fiber qualification standards under Nutrition Facts Label updates create compliance risk for non-digestible carbohydrate declarations.
- Enzyme Cost Exposure:Fructosyltransferase and galactosyltransferase biocatalysts for oligosaccharide synthesis face biomanufacturing input price instability.
Strategic Opportunities
- Japan FOSHU Pathway:Consumer Affairs Agency approval for Foods for Specified Health Uses creates premium market access for clinically substantiated prebiotic ingredients.
- Sports Nutrition Infusion:Endurance and recovery beverage formulators seek fermentable fibers for gut-permeability and immune modulation claims during heavy training loads.
- Precision Fermentation Convergence:Cell-culture-derived oligosaccharides bypass agricultural feedstock constraints and enable custom chain-length tailoring for specific microbiome targets.
Industry Challenges
- Microbiome Characterization Talent Gap:Formulation labs lack computational biologists capable of translating 16S rRNA sequencing data into product-specific health claim substantiation.
- Multi-Jurisdiction dossier Burden:Simultaneous FDA GRAS notification, EFSA health claim preparation, and FOSHU application timelines strain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prebiotic Fiber Market |
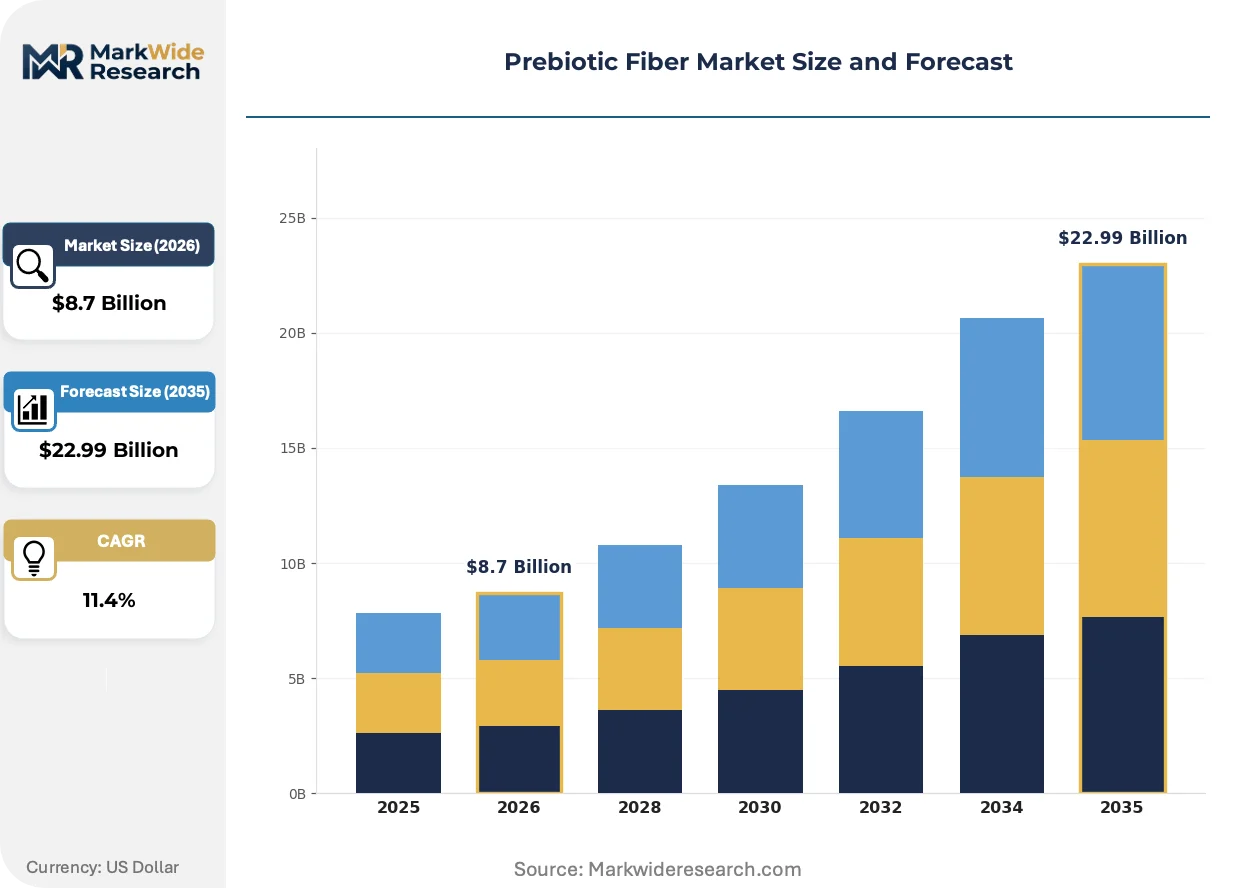
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligofructose, Galacto-Oligosaccharides, Xylo-Oligosaccharides End User: Food & Beverage, Bakery, Dairy, Supplements Packaging Type: Bags, Boxes, Tubs, Sachets Application: Functional Foods, Nutritional Bars, Infant Formula, Beverages |
| Companies Covered | BENEO, Tate & Lyle, Ingredion, FrieslandCampina Ingredients, Roquette Frères, Cargill, ADM, Cosucra Groupe Warcoing, Clasado Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prebiotic Fiber Market Strategic Shifts
Bioprocess automation and regulatory science convergence are compressing development cycles for microbiome-targeted ingredients. Suppliers now compete on fermentation characterization speed and cross-border dossier efficiency rather than commodity scale alone.
High-throughput in vitro gut simulation platforms are digitizing prebiotic screening workflows. Contract research organizations deploy SHIME and TIM-2 systems to accelerate bifidogenic activity validation for ingredient suppliers. European functional food manufacturers now demand standardized short-chain fatty acid metabolite profiles before contract commitment. This digitization is compressing the 18-month traditional substantiation timeline into 6-month competitive windows.
EFSA's 2023 updated guidance on gut health claims tightens the correlation required between microbiome modulation and measurable physiological benefit. Ingredient suppliers must now demonstrate sustained SCFA production rather than transient bacterial population shifts. Infant formula and senior nutrition segments face the steepest evidentiary upgrade requirements. Companies are responding by funding longitudinal human intervention trials rather than relying on in vitro data packages.
Direct-to-manufacturer ingredient supply contracts are displacing traditional distributor intermediaries in North American and Western European markets. Large functional food processors now negotiate multi-year volume commitments with chicory root and corn fiber processors in exchange of exclusive formulation collaboration. This consolidation concentrates procurement leverage among buyers with sufficient scale to justify dedicated R&D support. The shift is most visible in nutritional bar and ready-to-drink beverage categories where margin pressure demands supply chain cost extraction.
Prebiotic Fiber Market Segmentation
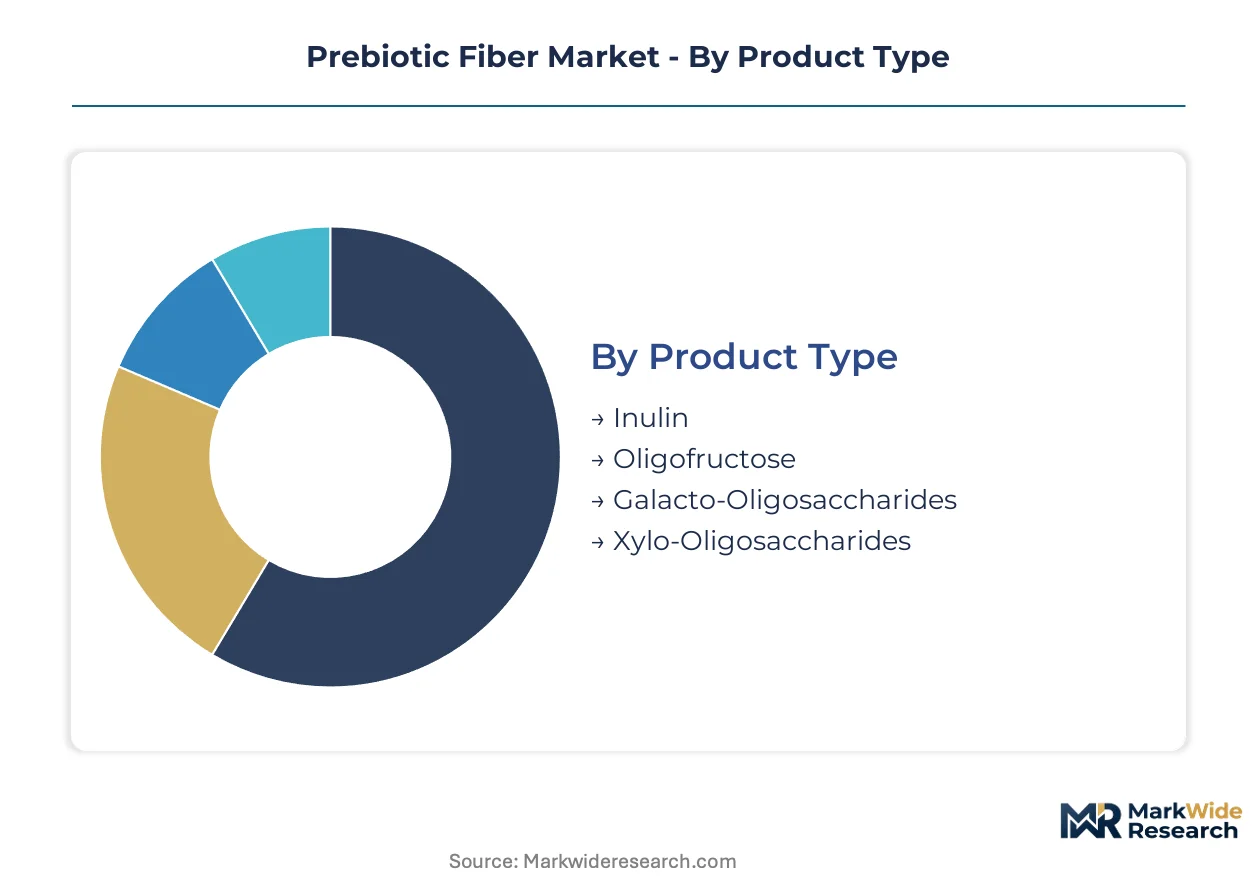
Prebiotic fiber segmentation reveals how technical specifications, end-use requirements, and packaging formats create distinct margin pools. Manufacturers configure supply chains differently for each category, with formulation complexity and regulatory substantiation demands driving supplier selection criteria.
Product Type:
After-sales service intensity varies sharply across prebiotic fiber types, with clinical substantiation support and regulatory dossier maintenance creating divergent supplier relationship models.
- Inulin:Long-chain fructan extracted from chicory root through hot water diffusion and spray drying. Food & Beverage manufacturers in Germany and the United States pay premiums for EFSA Article 13.1 authorized grades with validated bifidogenic activity documentation.
- Galacto-Oligosaccharides:Disaccharide to octasaccharide mixtures synthesized from lactose via enzymatic transgalactosylation. Dairy processors demand infant formula regulatory pre-approval across multiple jurisdictions, requiring intensive supplier technical support.
- Oligofructose:Shorter-chain fructooligosaccharide with enhanced solubility and milder sweetness profile.
- Xylo-Oligosaccharides:Xylose-based oligomers from agricultural waste hydrolysis, gaining traction in Asian markets for cost-competitive gut health applications.
Inulin holds the largest share; momentum sits with Xylo-Oligosaccharides.
End User:
Cost tier differentiation separates premium-positioned end users from commodity buyers, with regulatory compliance burden and formulation sophistication determining supplier margin capture.
- Food & Beverage:Broad category spanning clean-label reformulation projects and functional positioning initiatives. Clean-label mandates from retail buyers in Western Europe compress conventional additive margins and accelerate prebiotic substitution.
- Dairy:Infant formula and fermented milk applications require the most stringent microbiome substantiation. Multinational processors negotiate multi-year volume commitments with GOS suppliers for gut microbiome differentiation claims.
- Bakery:Fiber fortification in bread and pastry applications, balancing water-binding capacity with dough rheology requirements.
- Supplements:Capsule and powder formats targeting digestive health and immune modulation positioning.
Food & Beverage commands the deepest volume; Supplements generate the steepest price premiums.
Packaging Type:
Volume throughput and handling automation requirements shape packaging selection, with industrial scale operations favoring formats that minimize labor and contamination risk.
- Bags:Multi-layer laminated sacks with moisture barriers for bulk inulin and oligosaccharide powders. Functional food manufacturers in Belgium and the Netherlands specify FIBC configurations with nitrogen flushing for hygroscopic fiber stability.
- Tubs:Rigid polyethylene containers for consumer-facing supplement and infant formula ingredient shipments.
- Boxes:Corrugated fiberboard with inner liners for mid-volume bakery and beverage processor deliveries.
- Sachets:Single-serve foil laminates for sample distribution and clinical trial material deployment.
Bags dominate industrial procurement; sachets are climbing fastest on clinical trial material demand.
Application:
Customer type stratification separates multinational processors with dedicated R&D support from regional formulators relying on supplier technical service.
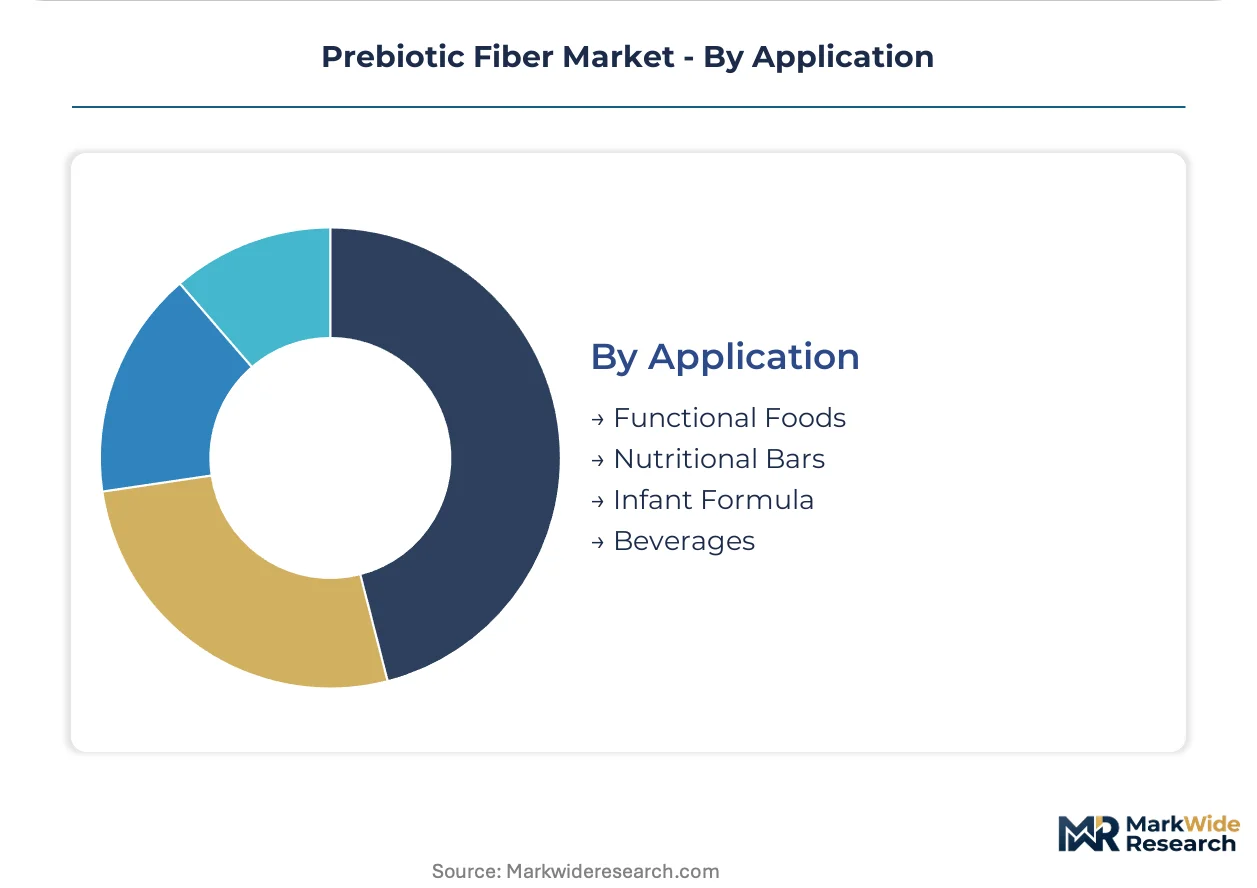
- Functional Foods:Yogurt, spreads, and cereals with substantiated digestive health claims. EFSA's tightened gut health guidance demands sustained SCFA production evidence rather than transient bacterial population shifts.
- Infant Formula:Early-life nutrition with the most rigorous global regulatory acceptance requirements. Longitudinal human intervention trials replace in vitro data packages under upgraded evidentiary standards.
- Nutritional Bars:High-protein, high-fiber meal replacement formats where prebiotic inclusion supports texture and shelf-life alongside microbiome benefits.
- Beverages:Ready-to-drink and powder mixes targeting sports recovery and daily wellness positioning.
Functional Foods capture the largest revenue pool; Infant Formula faces the steepest substantiation upgrade requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Antwerp-Bruges liquid bulk terminals anchor European chicory root concentrate flows, while Union Pacific's refrigerated rail network underwrites U.S. corn-derived fiber distribution to formulation labs.
United States
Clean-label mandates from Walmart and Target procurement teams drive prebiotic substitution in packaged foods. FDA Nutrition Facts Label updates under the 2016 rule continue reshaping isolated fiber qualification standards. Chicago-area formulation clusters host Tate & Lyle technical service labs supporting sports nutrition and beverage developers.
Germany
EFSA Article 13.1 authorized inulin grades command premium positioning in functional yogurt and spread applications. Germany's national food regulator (BfR) coordinates with EFSA on gut health claim substantiation thresholds. Hamburg's port infrastructure handles bulk chicory root shipments from Belgian processors for redistribution across Central Europe.
China
Agricultural waste conversion technologies for xylo-oligosaccharides expand feedstock access beyond traditional root and starch dependencies. SAMR's evolving functional food registration pathways create compliance complexity for prebiotic positioning claims. Shandong Province bioprocessing clusters scale enzymatic hydrolysis of corn cob and wheat straw residues.
Japan
Consumer Affairs Agency FOSHU approvals sustain premium pricing for clinically substantiated prebiotic ingredients in aging-population nutrition. METI's functional food industry support programs accelerate microbiome-targeted product development. Tokyo-Osaka corridor hosts concentrated infant formula and senior nutrition R&D facilities seeking bifidogenic fiber partnerships.
Belgium
BENEO's integrated chicory root processing infrastructure dominates European inulin supply chains through captive agricultural sourcing. EFSA health claim dossier preparation services cluster around Brussels regulatory affairs consultancies. Flanders' biotech corridor houses specialized fermentation characterization labs serving pan-European ingredient suppliers.
Prebiotic Fiber Market Competitive Environment
On the supply side, the industry is consolidating around multi-category carbohydrate specialists with captive agricultural sourcing and integrated regulatory affairs capabilities. Three archetypes dominate: chicory root processors with European agricultural infrastructure, corn-derived soluble fiber technologists with North American starch supply chains, and dairy-aligned galacto-oligosaccharide producers leveraging lactose feedstock access. Competitive moves center on multi-year direct-to-manufacturer supply contracts and cross-border dossier filing consortia to share EFSA and FDA substantiation costs.
Within the European infrastructure tier, BENEO and Roquette Frères exemplify agricultural-integrated positioning through Belgian and French chicory root processing networks. Tate & Lyle occupies the North American technology leadership position for corn-derived soluble fiber applications. Cargill and ADM represent diversified agribusiness archetypes competing across multiple prebiotic categories through scale procurement and global distribution infrastructure.
| Leading Market Players |
|---|
| BENEO |
| Tate & Lyle |
| Ingredion |
| FrieslandCampina Ingredients |
| Roquette Frères |
| Cargill |
| ADM |
| Cosucra Groupe Warcoing |
| Clasado Biosciences |
| Others |
Value Chain & Pricing Dynamics
Belgian chicory root processing overcapacity during the 2023-2024 harvest cycle compressed inulin spot pricing while simultaneously forcing BENEO and Roquette Frères into longer-term contract structures to lock volume commitments. This utilization imbalance cascaded through European supply chains as manufacturers traded price premiums for supply security amid climate-induced yield volatility.
Pricing Analysis
Volume-discount tiering structures dominate prebiotic fiber procurement, with three-tier pricing separating EFSA-authorized pharmaceutical grades from standard food-grade inulin and economy-tier xylo-oligosaccharide imports. Price differentiation rests on certification level and bifidogenic activity documentation, with dairy processors least sensitive due to infant formula regulatory requirements and bakery formulators most price-elastic. Cost compression in economy tiers intensifies because Chinese XOS producers scale agricultural waste conversion capacity.
Supply Chain Analysis
Export-control regime scrutiny over enzyme manufacturing technologies limits fructosyltransferase and galactosyltransferase biocatalyst flows from European suppliers to Asian producers. Geographic supply concentration centers on Belgium, the Netherlands, and China, with raw material dependencies spanning chicory root, corn starch, and wheat straw residues. Single-source vulnerability concentrates in Belgian hot water diffusion infrastructure. Distribution runs through direct-to-manufacturer contracts displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement leverage is concentrating among multinational functional food processors capable of justifying dedicated R&D support, fragmenting price-setting power away from ingredient suppliers. This buyer-power shift rewards scale and regulatory sophistication over commodity volume.
For Market Incumbents: Insulate margin position through captive chicory root sourcing in Flanders and accelerated FOSHU dossier preparation for Japanese market access. Precision fermentation R&D partnerships bypass agricultural feedstock constraints threatening traditional extraction economics. Multi-year direct supply contracts with infant formula manufacturers lock volume against XOS price erosion. For New Entrants and Emerging Players: Pursue white-space opportunities in sports nutrition beverages seeking gut-permeability claims and senior nutrition formats requiring sustained SCFA evidence under EFSA's tightened guidance. The most penetrable segment sits with endurance beverage formulators lacking established prebiotic supplier relationships. A go-to-market angle emphasizing rapid SHIME-based substantiation protocols differentiates against incumbent 18-month validation timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among galacto-oligosaccharide producers with multi-jurisdiction infant formula regulatory pre-approval and locked dairy processor volume commitments. Long-term viability over a 5-10 year window favors precision fermentation platforms enabling custom chain-length oligosaccharide production. The acquisition target archetype combines regulatory affairs bandwidth with high-throughput in vitro characterization infrastructure. The signal to watch is EFSA authorization velocity for novel microbiome-targeted ingredients.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Cell-culture-derived oligosaccharides bypass Belgian chicory root yield volatility and enable custom microbiome targeting. |
| Multi-Jurisdiction Dossier Consortia | Shared EFSA and FDA substantiation costs reduce regulatory affairs bandwidth strain for mid-tier suppliers. |
| Direct-to-Manufacturer Supply Contracts | Walmart and Target clean-label mandates accelerate prebiotic substitution through exclusive formulation collaboration. |
| Agricultural Waste Conversion Expansion | Shandong Province XOS producers scale wheat straw hydrolysis, diversifying beyond chicory and corn dependencies. |
| High-Throughput In Vitro Platform Investment | SHIME and TIM-2 systems compress bifidogenic validation from 18 months to 6-month competitive windows. |
Study Parameters
The analysis maps inulin, galacto-oligosaccharides, xylo-oligosaccharides, and emerging precision fermentation platforms, each validated through regulatory affairs directors at ingredient suppliers, procurement leads at multinational dairy processors, and technical service heads at functional food manufacturers. Secondary sources include EFSA health claim registers, FDA GRAS notifications, FOSHU approval databases, and customs trade flows for chicory root concentrate. Bottom-up volume triangulation against top-down market sizing ensures segment-level consistency.
Assumption sets held regulatory pathway timelines and microbiome characterization standards fixed while varying agricultural yield scenarios and enzyme input cost trajectories across the projection horizon. Segmentation dimensions modeled include product type chain length, end-use regulatory tier, packaging format automation compatibility, and regional claim substantiation requirements. CAGRs derive from volume commitment trajectories in locked supply contracts and capacity expansion announcements. Industry-specific inputs incorporate SHIME platform adoption rates and EFSA guidance revision frequency.
Sensitivities concentrate around FDA isolated fiber definition updates, climate-induced chicory root yield volatility, and precision fermentation cost parity achievement. Forecasts reflect documented assumptions without claiming predictive certainty. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Fermented Protein Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Functional Tea Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
APAC Functional Food Ingredients Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Health and Wellness Foods Market
Functional Food and Beverage
Global CBD Beverages Market