
 Low Fat Beef Market | 2026-2036
Low Fat Beef Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Beef Market Analytics
Grass-fed and USDA Select grade differentiation is collapsing the gap between conventional and premium lean beef positioning. JBS S.A. leverages its integrated feedlot-to-retail infrastructure to standardize fat-content consistency across North American operations. Tyson Foods Inc. anchors its low-fat portfolio through controlled-environment finishing programs that reduce external fat deposition. Cargill Meat Solutions differentiates via proprietary trim optimization systems that hit precise lean-point targets for foodservice buyers.
Low fat beef denotes muscle tissue from cattle bred and finished to achieve sub-10% fat content in retail cuts, typically through controlled grain rations, selective genetics, and precision trimming to meet USDA Select or leaner grade thresholds. Ground beef commands the largest volume position due to its formulation flexibility and price accessibility, while beef tenderloin captures concentrated margin pools in premium foodservice channels. Health food stores and dedicated butcher shops represent the fastest-growing distribution nodes as consumers seek provenance transparency and custom grind specifications unavailable in conventional retail.
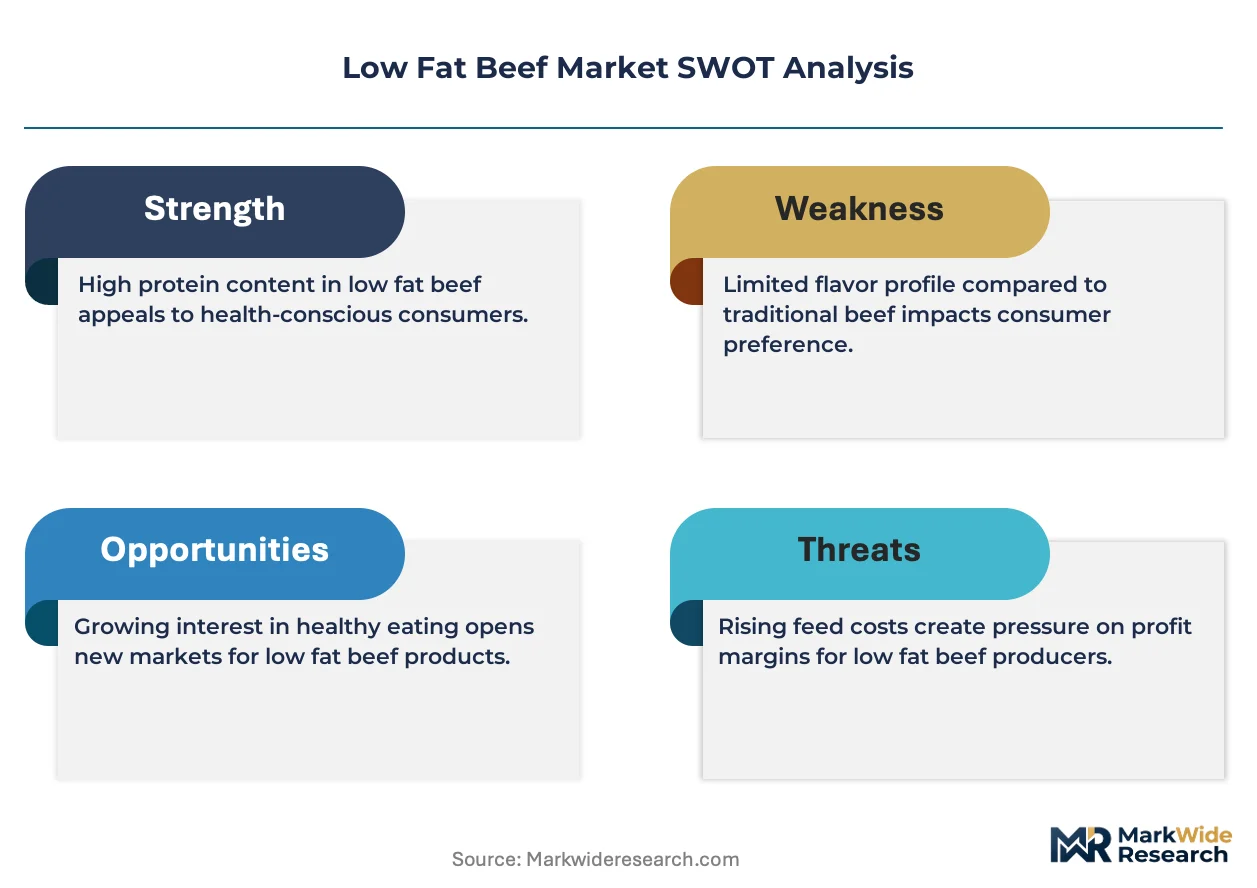
The USDA grading protocols and FSIS labeling standards govern fat-content claims and nutritional panel accuracy, while the FDA oversees health claim substantiation on packaged products. State-level agricultural extension services in Nebraska, Kansas, and Texas enforce cattle finishing protocols that directly affect achievable lean yields. Stakeholders must monitor evolving dietary guideline revisions and alternative protein labeling disputes that threaten to redefine competitive boundaries for lean animal proteins.
Market Dynamics
USDA grading protocol revisions and meal kit subscription penetration are compressing traditional retail margins while elevating lean beef premiums through direct-to-consumer channels.
Growth Catalysts
- Meal Kit Channel Expansion:Health-conscious consumers in the United States subscribe to curated lean protein boxes that specify sub-10% fat content. Foodservice operators now contract directly with packers for custom grind specifications.
- FSIS Labeling Enforcement:Stricter nutritional panel accuracy requirements validate fat-content claims at retail. Packaged low-fat beef products gain shelf space as verified lean-point data satisfies retailer compliance departments.
- Controlled-Environment Finishing:Precision climate systems in Nebraska and Kansas feedlots standardize external fat deposition. Genetics programs targeting leanness heritability accelerate throughput of Select-grade carcasses.
Market Restraints
- Feed Cost Volatility:Corn and soybean meal price swings in the Midwest directly compress finishing margins. Cattle feeders cannot pass input spikes through to fixed-price retail contracts.
- Concentrated Packing Capacity:Four firms control 85% of federally inspected steer and heifer slaughter. Bottlenecks at specific plants create regional supply disruptions during equipment maintenance cycles.
- Alternative Protein Substitution:Plant-based ground products from Beyond Meat and Impossible Foods capture trial among flexitarian households. Lean beef must differentiate on complete amino acid profiles and bioavailable heme iron.
Strategic Opportunities
- Direct-to-Consumer Butcher Shops:Independent cutters in Austin, Denver, and Portland offer custom grind ratios and provenance transparency unavailable in conventional grocery. These shops command 40-60% premiums over commodity ground beef.
- USDA Select Grade Positioning:Updated dietary guidelines emphasizing saturated fat reduction create tailwinds for leaner grade certifications. Retailers merchandise Select as a health-forward tier between Choice and grass-fed premium.
- Blockchain Traceability Convergence:Distributed ledger systems paired with RFID ear tags verify grass-fed and antibiotic-free claims. Early adopters in the Pacific Northwest use this data to secure foodservice contracts with hospital and university systems.
Industry Challenges
- Certification Timeline Compression:Third-party audits for grass-fed and animal welfare claims require 90-180 day verification cycles. Smaller producers struggle to maintain cash flow during documentation gaps.
- Precision Trimming Labor Scarcity:Skilled fabricators who can consistently hit 90/10 or 93/7 lean-point targets command wage premiums. Meat science programs at land-grant universities graduate insufficient numbers to replace retiring cutters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Beef Market |
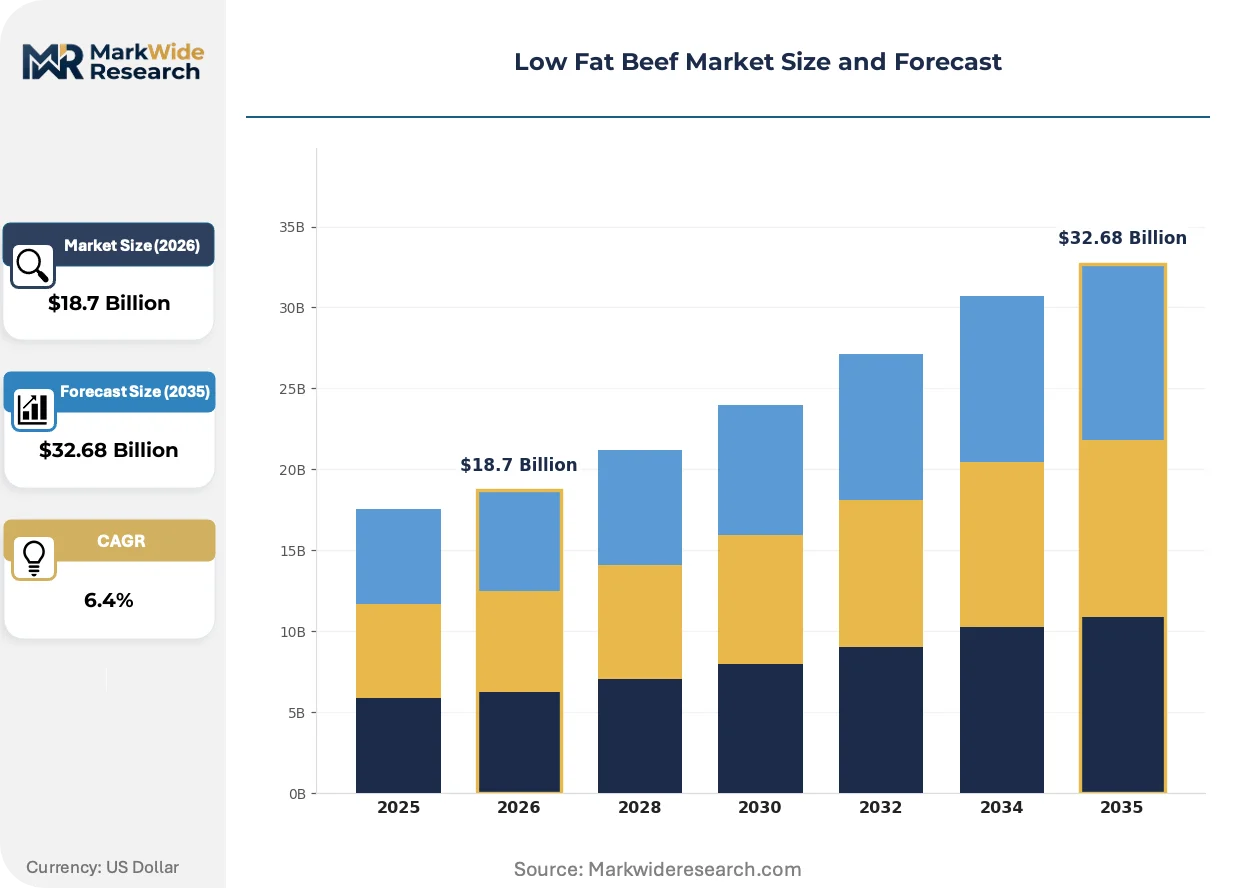
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Beef, Beef Steak, Beef Ribs, Beef Tenderloin Distribution Channel: Supermarkets, Online Retailers, Butcher Shops, Health Food Stores End User: Restaurants, Meal Kit Services, Retail Consumers, Food Manufacturers Packaging Type: Vacuum Sealed, Tray Packs, Canned, Bulk Packaging |
| Companies Covered | JBS S.A., Tyson Foods Inc., Cargill Meat Solutions, Marfrig Global Foods, National Beef Packing Company, Danish Crown, Minerva Foods, NH Foods Ltd., Hormel Foods Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Beef Market Evolving Landscape
Digital traceability platforms and precision livestock monitoring are collapsing information asymmetries between producers and end-buyers. These tools enable specification-grade contracting that was previously impossible at scale.
Blockchain-enabled carcass tracking is fragmenting the traditional commodity beef supply chain into identity-preserved streams. Ranchers in Montana and Wyoming attach immutable records to individual animals. Hospital foodservice buyers now source specific lots with complete antibiotic and hormone documentation. This granularity compresses the price premium between commodity Select and verified lean programs.
The FDA's updated guidance on nutrient content claims for "lean" and "extra lean" beef is tightening substantiation requirements for packaged products. Manufacturers must maintain analytical records supporting fat percentages on nutrition facts panels. Smaller processors in the Intermountain West are investing in rapid near-infrared testing equipment to preempt regulatory scrutiny.
Subscription-based protein procurement is displacing spot-market purchasing among millennial households. Meal kit operators like ButcherBox and Crowd Cow aggregate demand for specific lean-point ground beef and ship direct. This channel concentrates in coastal metropolitan areas where conventional retail beef cases carry limited sub-15% fat options.
Low Fat Beef Market Segmentation
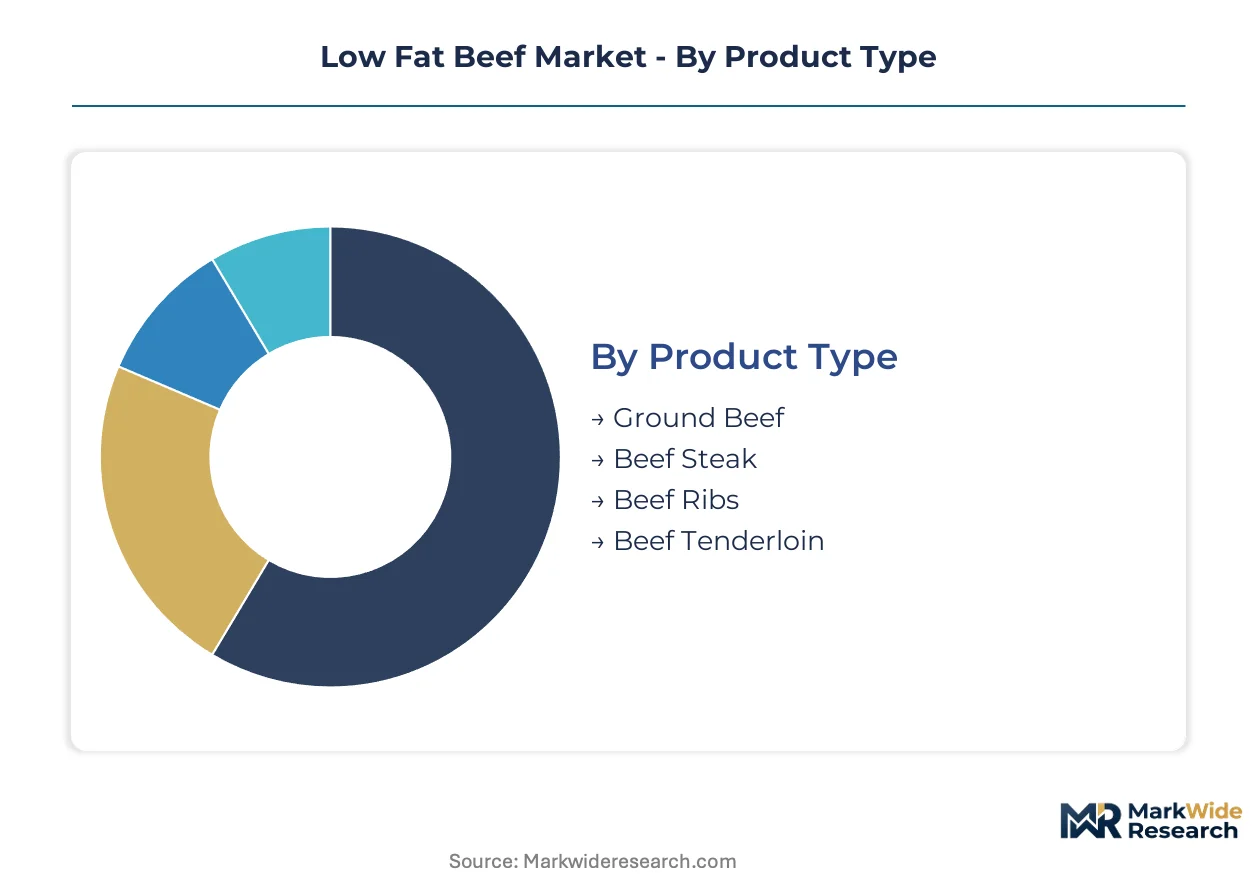
Channel differentiation in low fat beef is accelerating as direct-to-consumer platforms fragment traditional retail dominance. Specification-grade requirements vary sharply across end-use applications, forcing packers to maintain parallel production streams with distinct fat-content tolerances and documentation protocols.
Product Type:
Ground beef and whole-muscle cuts flow through fundamentally different channel architectures, with grind products dominating foodservice contract volumes while steaks concentrate in premium retail and direct-to-consumer butcher operations.
- Ground Beef:Formulation flexibility allows precise lean-point targeting from 90/10 to 93/7 ratios through controlled trim selection. Meal kit services in the United States specify sub-10% fat content for subscription boxes, creating dedicated grind programs that bypass conventional retail distribution.
- Beef Steak:External fat trimming to 0.25-inch or less differentiates Select-grade loin and rib cuts for health-conscious households. Retail merchandising programs in Texas and Nebraska position these steaks between commodity Choice and premium grass-fed tiers, capturing margin through USDA grade certification.
- Beef Ribs:Lean-point optimization challenges limit penetration in low-fat positioning; back ribs see selective placement in barbecue-focused meal kits requiring visible fat cap removal.
- Beef Tenderloin:Naturally lean muscle tissue commands concentrated margin pools in white-tablecloth foodservice; custom aging programs in Kansas City and Omaha supply hospital and university systems with verified antibiotic documentation.
By volume, Ground Beef leads. By growth pace, Beef Tenderloin is ahead.
Distribution Channel:
Margin capture varies inversely with supply chain length, with shortest-path channels commanding premium realization despite smaller throughput.
- Supermarkets:Conventional retail cases carry limited sub-15% fat options due to inventory velocity constraints; dedicated lean beef sections in Texas and Florida chains use Select-grade certification to justify price premiums over commodity ground.
- Online Retailers:Subscription platforms aggregate demand for specific lean-point specifications unavailable in brick-and-mortar; ButcherBox and Crowd Cow ship direct to coastal metropolitan households, compressing traditional distributor margins.
- Butcher Shops:Independent cutters in Austin, Denver, and Portland offer custom grind ratios with complete provenance transparency; these shops realize 40-60% premiums over commodity pricing through specification-grade service.
- Health Food Stores:Grass-fed and antibiotic-free claims concentrate in this channel; the Pacific Northwest cluster uses blockchain-verified documentation to secure placement with wellness-focused retail buyers.
Supermarkets move the most tonnage. Health Food Stores are climbing the fastest.
End User:
Procurement specifications diverge sharply between foodservice operators seeking consistency at scale and retail consumers prioritizing transparency and customization.
- Restaurants:White-tablecloth operators contract directly with packers for tenderloin and strip loin with precise external fat limits; quick-service chains specify 90/10 grind for burger platforms with standardized cook times.
- Meal Kit Services:Curated protein boxes represent the fastest-expanding demand channel; operators specify sub-10% fat content with lot-traceable documentation for health-conscious subscription households.
- Retail Consumers:Supermarket purchasers show price sensitivity that limits premium positioning; direct-to-consumer butcher shop patrons accept higher price points for custom specifications and provenance verification.
- Food Manufacturers:Processed meat applications require consistent lean-point inputs for nutritional label accuracy; rapid near-infrared testing equipment validates fat percentages to preempt FDA scrutiny on "lean" claims.
Restaurants absorb the highest absolute volume. Meal Kit Services are gaining share fastest.
Packaging Type:
Packaging selection directly determines shelf-life extension and channel suitability, with vacuum technologies enabling specification-grade distribution beyond regional boundaries.
- Vacuum Sealed:Oxygen exclusion extends case-ready shelf life to 21-28 days, enabling Select-grade product distribution from Nebraska and Kansas feedlots to coastal metropolitan markets without intermediaries.
- Tray Packs:Modified atmosphere systems dominate conventional retail presentation; overwrap configurations balance visibility requirements with lean-point label compliance for supermarket meat cases.
- Canned:Shelf-stable formats capture limited low-fat positioning through drained lean content claims; institutional procurement for emergency food programs represents primary demand concentration.
- Bulk Packaging:Foodservice grind moves in 10-40 pound chubs or combo bins for high-volume operators; lot coding enables traceback to specific feedlot finishing groups for contract compliance.
Tray Packs dominate retail volume. Vacuum Sealed shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and Argentina exhibit acute price sensitivity to feed cost fluctuations, while Japanese and European purchasers absorb premiums for verified lean-point documentation without volume elasticity shifts.
United States
Meal kit subscription penetration and hospital foodservice contracting drive specification-grade demand. The USDA enforces updated Select-grade certification protocols that tighten fat-content tolerances. Nebraska and Kansas feedlots deploy precision climate finishing systems to standardize external fat deposition for retail compliance.
Brazil
Export-oriented packers pivot toward lean-point optimization for Middle Eastern and Asian halal markets. The Ministry of Agriculture enforces SIF inspection standards that govern fat-content labeling for international shipments. São Paulo and Minas Gerais processing clusters invest in trim optimization automation to hit 90/10 grind targets for foodservice contracts.
China
Urban middle-class households in Shanghai and Beijing prioritize lean beef for home cooking as dietary guidelines emphasize saturated fat reduction. The SAMR oversees nutritional label accuracy for imported chilled beef products. Yangtze River Delta cold-chain distributors build dedicated low-fat beef sections for premium supermarket placements.
Germany
Discounter retail chains demand consistent lean-point ground beef for private-label positioning against plant-based alternatives. The BfR coordinates with EFSA on health claim substantiation for "lean" beef packaging. North Rhine-Westphalia meat processors develop rapid near-infrared testing protocols to validate fat percentages for export documentation.
Australia
Grass-fed certification programs capture premiums in Japanese and South Korean import markets requiring complete antibiotic documentation. The Department of Agriculture adminulates export registration and lot-traceability requirements. Queensland and New South Wales cattle operations integrate RFID ear tags with blockchain platforms to verify finishing protocols for hospital system contracts.
Low Fat Beef Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the low fat beef supply chain. Integrated packers with captive feedlot operations dominate volume throughput and grade standardization, while specialized processors command premium positioning through custom fabrication and provenance verification. Three archetypes define competitive positioning: vertically integrated multinationals controlling slaughter-to-retail pipelines, regional specialists with specification-grade flexibility, and direct-to-consumer platforms collapsing distributor layers. Dominant competitive moves center on feedlot capacity expansion for grade consistency and strategic partnerships with meal kit operators for dedicated supply agreements.
Among Brazil-based packers, JBS S.A. and Marfrig Global Foods occupy positions exemplifying scale-driven integration archetypes. Tyson Foods Inc. represents the North American vertically integrated model with controlled-environment finishing infrastructure. Cargill Meat Solutions anchors the specification-grade specialist tier through proprietary trim optimization systems serving foodservice contract buyers.
| Leading Market Players |
|---|
| JBS S.A. |
| Tyson Foods Inc. |
| Cargill Meat Solutions |
| Marfrig Global Foods |
| National Beef Packing Company |
| Danish Crown |
| Minerva Foods |
| NH Foods Ltd. |
| Hormel Foods Corporation |
| Others |
Value Network & Pricing Analysis
USDA Select-grade certification gates both packer qualification for retail shelf placement and the price premiums that separate commodity Choice from health-positioned lean beef tiers. Packers lacking verified lean-point documentation cannot access meal kit contracts or hospital foodservice accounts regardless of cost position.
Pricing Analysis
After-sales service revenue from custom grind programs and subscription fulfillment contracts drives lifetime value for direct-to-consumer operators. Three-tier pricing structure across premium grass-fed, standard Select-grade, and economy commodity tiers reflects certification investment and traceability documentation depth. Cost compression in the standard tier is intensifying because feedlot operators cannot pass corn price volatility through to fixed-price retail contracts. Quick-service chains show highest price sensitivity due to standardized burger platform economics, while hospital systems absorb premiums for verified antibiotic documentation.
Supply Chain Analysis
Midwest packing capacity concentration in Nebraska, Kansas, and Texas underwrites national lean beef availability but creates regional vulnerability during equipment maintenance cycles. Production draws from captive feedlot finishing, precision trim optimization systems, and RFID-enabled lot traceability infrastructure. Single-source vulnerability concentrates in four firms controlling federally inspected steer and heifer slaughter. Distribution runs through direct-to-consumer subscription platforms, foodservice contract channels, and conventional retail case-ready programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability platforms are transforming low fat beef into an interoperability-driven ecosystem where data verification replaces commodity spot trading. Ranchers, packers, and meal kit operators now share immutable records that compress information asymmetries.
For Market Incumbents: Fortify feedlot-to-retail infrastructure against alternative protein substitution by embedding controlled-environment finishing systems that standardize Select-grade output consistency. Capture channel control through exclusive supply agreements with meal kit operators specifying sub-10% fat content with lot-traceable documentation.
For New Entrants and Emerging Players: Lead with specification-grade flexibility in direct-to-consumer butcher shop formats, offering custom grind ratios and provenance transparency unavailable from integrated packers. Target health food store placements in the Pacific Northwest where blockchain-verified grass-fed claims secure wellness-focused retail buyers.
For Investors and Strategic Acquirers: FDA updated guidance on "lean" and "extra lean" nutrient content claims reshapes the acquisition landscape toward processors with rapid near-infrared testing capabilities and analytical record-keeping infrastructure. Long-term viability favors regional specialists with specification-grade fabrication expertise and verified supply chain documentation. Monitor alternative protein labeling disputes as the signal indicating potential competitive boundary redefinition for lean animal proteins.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | RFID ear tags paired with distributed ledgers verify grass-fed claims for hospital foodservice contracts. |
| Controlled-Environment Finishing Expansion | Precision climate systems in Nebraska and Kansas feedlots standardize Select-grade carcass throughput. |
| Meal Kit Supply Partnership | Dedicated grind programs with ButcherBox and Crowd Cow bypass conventional retail distributor margins. |
| Rapid Near-Infrared Testing Deployment | Intermountain West processors preempt FDA scrutiny on fat percentage substantiation requirements. |
| Direct-to-Consumer Butcher Shop Network | Austin, Denver, and Portland independents capture 40-60% premiums through custom specification service. |
Research Methodology
The analysis maps ground beef formulation tiers, whole-muscle cut specifications, and distribution channel architectures, each validated through feedlot operations managers, retail meat category buyers, foodservice procurement directors, and meal kit supply chain leads. Primary interview findings triangulate against USDA grading protocol documentation, FDA labeling guidance, FSIS enforcement records, and packer SEC filings. Bottom-up volume modeling from feedlot capacity and slaughter data converges with top-down market sizing from retail scan and foodservice contract values.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product type, distribution channel, end user, and packaging format, with regional regulatory clusters and feedlot geography as cross-cutting dimensions. CAGRs derive from historical trajectory analysis and demand driver elasticity assessment. Forecast inputs incorporate meal kit subscription penetration curves, corn futures price volatility bands, and alternative protein market share assumptions.
The analysis sits within stated boundaries; outcomes outside sustained Select-grade certification compliance and stable Midwest feed cost conditions would require recalibration. Practitioners should keep alternative scenarios live as dietary guideline revision timelines and plant-based labeling regulatory outcomes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Lab-Grown Meat Market
Meat Products
Oman Poultry Meat Market
Meat Products
Brazil Meat Products Market
Meat Products
Global Canned Meat Market
Meat Products
North America Canned Meat Market
Meat Products
Organic Beef Meat Market
Meat Products
Low Fat Sausage Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Europe Edible Meat Market
Meat Products
Ham Slicers Market
Meat Products
South Africa Processed Meat Market
Meat Products
Europe Animal Protein Market
Meat Products
Europe Poultry Meat Market
Meat Products
Organic Eggs Market
Meat Products
US Meat Market
Meat Products
North America Edible Meat Market