
 Tetramethyl Orthosilicate Market | 2026-2036
Tetramethyl Orthosilicate Market Size, Share, and Industry Trends Forecast 2026-2036
Tetramethyl Orthosilicate Market Analytics
The capital-intensity gap between integrated silane producers and merchant chemical suppliers is collapsing as purification technology becomes commoditized. Evonik Industries AG leverages its integrated organosilicon platform to sustain captive supply chains for specialty coatings. Wacker Chemie AG anchors European production with backward integration into chlorosilane feedstocks. Nantong Chengua Chemical Co., Ltd. competes on regional logistics density, serving Jiangsu-based electronics manufacturers with just-in-time drum deliveries.
Tetramethyl orthosilicate, Si(OCH₃)₄, functions as a liquid silica precursor that hydrolyzes to form high-purity silicon dioxide layers via sol-gel or chemical vapor deposition processes at temperatures below 400°C. Electronics applications dominate structural value, where atomic-layer deposition requirements for semiconductor dielectrics command specification-grade material at purity thresholds exceeding 99.999%. Coatings and adhesives segments absorb volume at lower purity tiers, with sealants representing the fastest-growing product category as construction markets specify moisture-cured silicone systems. Solvent-grade material occupies a mature position with thinner margin pools, constrained by substitution from alternative alkoxysilanes.
EPA hazardous air pollutant standards and REACH substance restrictions shape formulation chemistry, pushing manufacturers toward closed-loop handling systems and reduced volatile organic compound emissions. China's MIIT enforces GB standards for chemical purity in electronics-grade materials, creating dual certification burdens for exporters. Japan's METI chemical management framework adds a third compliance layer for suppliers serving Shin-Etsu Chemical's domestic fabrication customers. Stakeholders must monitor divergence between regional purity specifications and assess whether dedicated production lines or flexible batch systems offer superior returns as regulatory thresholds tighten.
Market Dynamics
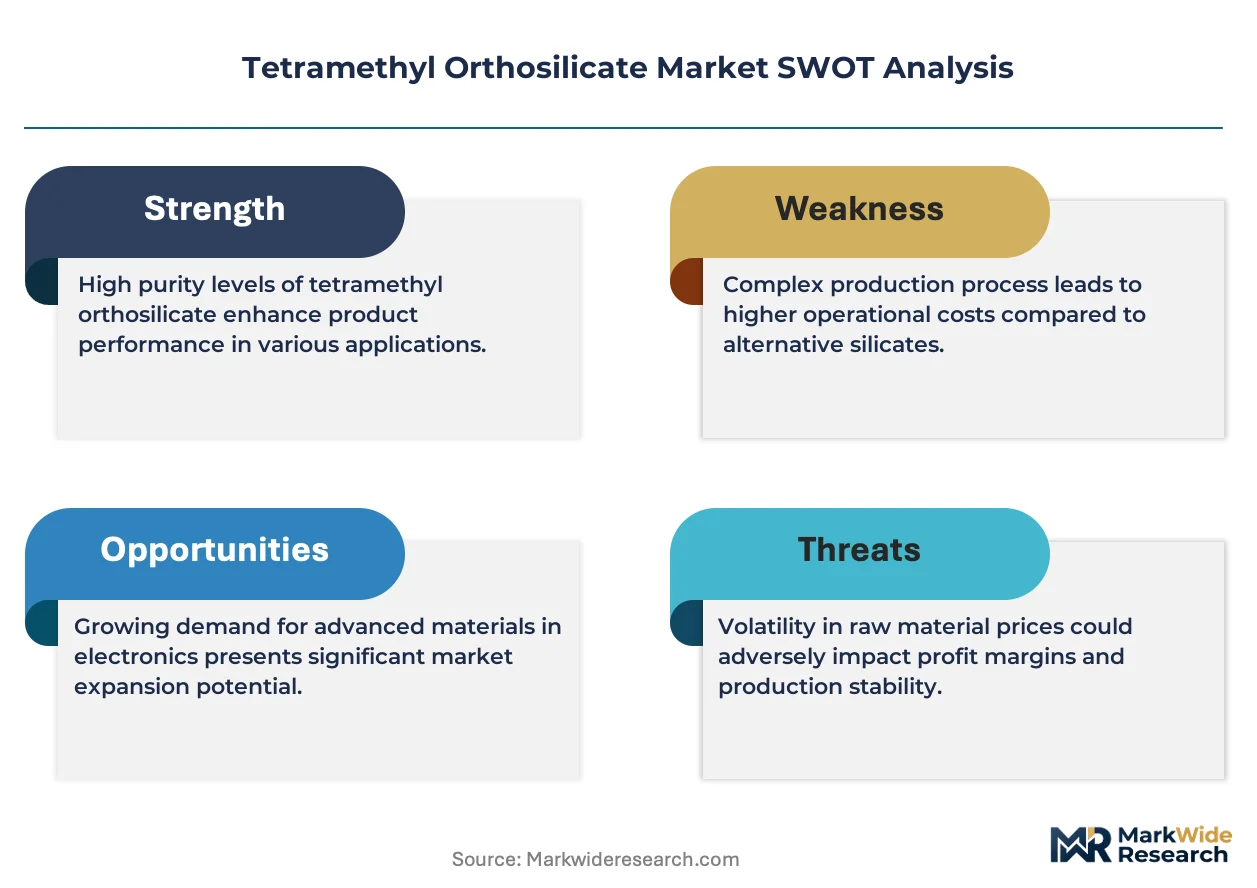
Purification technology commoditization is collapsing the capital-intensity gap between integrated silane producers and merchant chemical suppliers, forcing specialty coating manufacturers to reassess captive versus outsourced precursor sourcing.
Growth Catalysts
- Semiconductor dielectric demand:Atomic-layer deposition requirements for sub-7nm node fabrication pull specification-grade tetramethyl orthosilicate at purity thresholds exceeding 99.999%. Electronics manufacturers in Jiangsu province anchor this demand.
- REACH substance restrictions:Tightened purity requirements for chemical intermediates in Europe push formulators toward closed-loop handling systems and higher-grade material certification.
- Moisture-cured silicone sealants:Construction markets specify these systems for infrastructure durability, absorbing volume at mid-tier purity grades and expanding the addressable application base.
Market Restraints
- Chlorosilane feedstock volatility:Backward-integrated producers face input cost pressure from energy-intensive chlorosilane production, compressing margin pools for non-integrated merchant suppliers.
- Alternative alkoxysilane substitution:Tetraethyl orthosilicate and other alkoxysilanes displace solvent-grade material in mature coating applications where purity requirements remain relaxed.
- EPA hazardous air pollutant standards:Emissions compliance adds capital burden to drum-handling and storage infrastructure, particularly constraining small-batch formulators.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication create new demand clusters in Gujarat and Tamil Nadu for electronics-grade silica precursors.
- Closed-loop handling systems:Regulatory pressure on volatile organic compound emissions creates service-attach revenue streams for equipment and logistics providers serving coating formulators.
- Photovoltaic dielectric coatings:Passivation layer requirements for heterojunction solar cells converge with existing semiconductor purification capabilities, opening adjacent demand.
Industry Challenges
- Dual certification burden:Exporters to China must satisfy both REACH compliance and MIIT GB standards for electronics-grade purity, extending qualification timelines and freezing batch flexibility.
- Atomic-layer deposition technician scarcity:Semiconductor fabs report gaps in precursor handling and chamber maintenance expertise, constraining throughput at new fabrication facilities.
- Legacy solvent-grade asset stranding:Mid-tier purification equipment faces obsolescence as customer specifications bifurcate toward either commodity solvent or ultra-high-purity electronics grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetramethyl Orthosilicate Market |
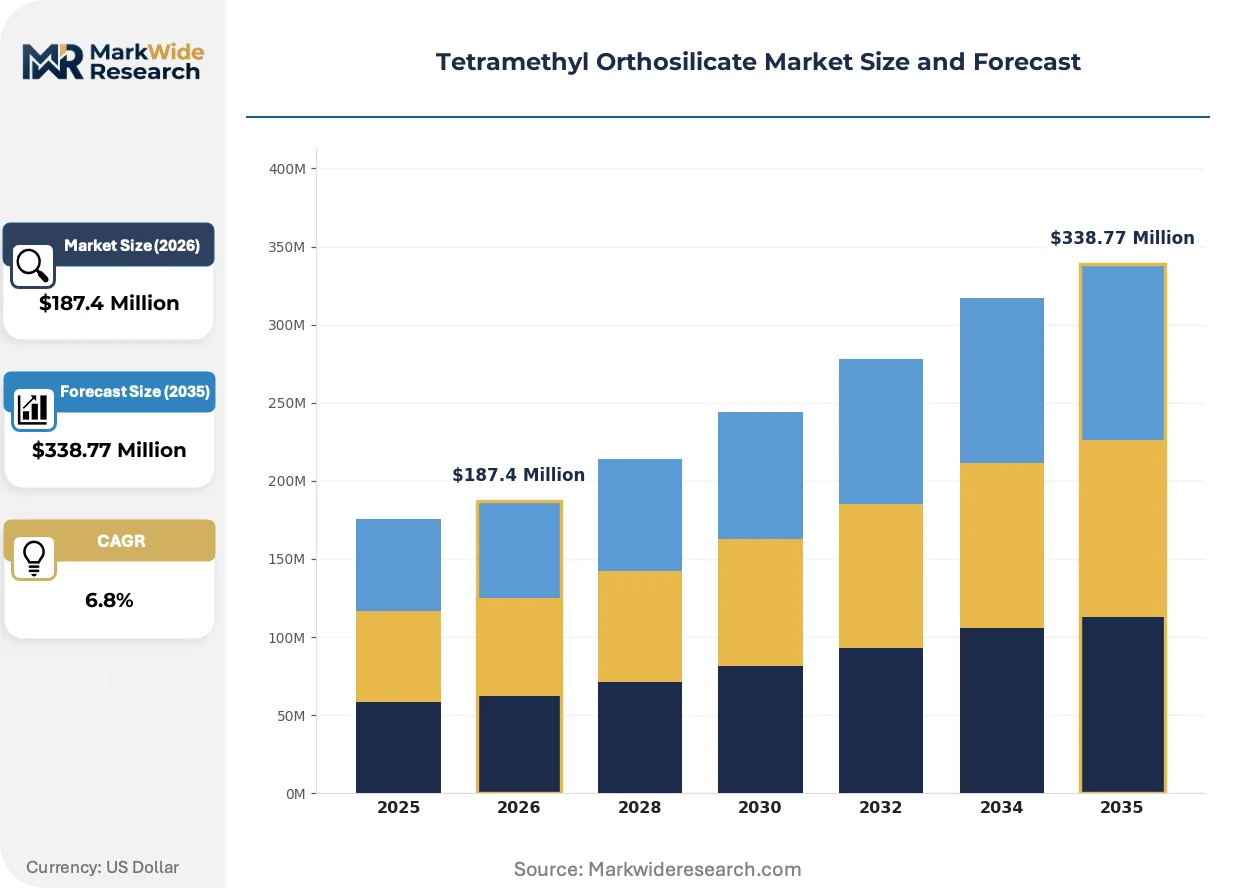
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Coatings, Adhesives, Sealants Application: Electronics, Pharmaceuticals, Agriculture, Construction End User: Manufacturers, Researchers, Distributors, Retailers Packaging Type: Drums, Bottles, Bulk Containers, Pails |
| Companies Covered | Evonik Industries AG, Wacker Chemie AG, Nantong Chengua Chemical Co., Ltd., Zhangjiagang Xinya Chemical Co., Jiangxi Chenguang New Materials Co., Qufu Chenguang Chemical Co., Ltd., Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials Inc., Dalian Jiarui Chemical Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetramethyl Orthosilicate Market Evolving Landscape
Purification and deposition technologies are actively reshaping competitive positioning in tetramethyl orthosilicate supply, with specification-grade production separating from commodity solvent operations.
Continuous-flow purification systems are bifurcating the producer landscape. These systems enable real-time impurity monitoring and reduced batch-to-batch variation. Integrated silane manufacturers deploy them for captive electronics-grade supply. Merchant suppliers without this capability retreat toward solvent-grade margins or exit.
REACH substance restrictions and evolving EPA hazardous air pollutant standards tighten purity thresholds for chemical intermediates. Formulators face reformulation costs to meet closed-loop handling mandates. Electronics-grade material absorbs disproportionate compliance investment as semiconductor customers refuse specification relaxation.
Buyer concentration among East Asian semiconductor fabs compresses switching cycles for precursor qualification. Procurement teams now demand dual-source redundancy with identical specification profiles. This pattern concentrates volume among producers with demonstrated METI and MIIT certification history, marginalizing newer entrants regardless of technical capability.
Tetramethyl Orthosilicate Market Segmentation
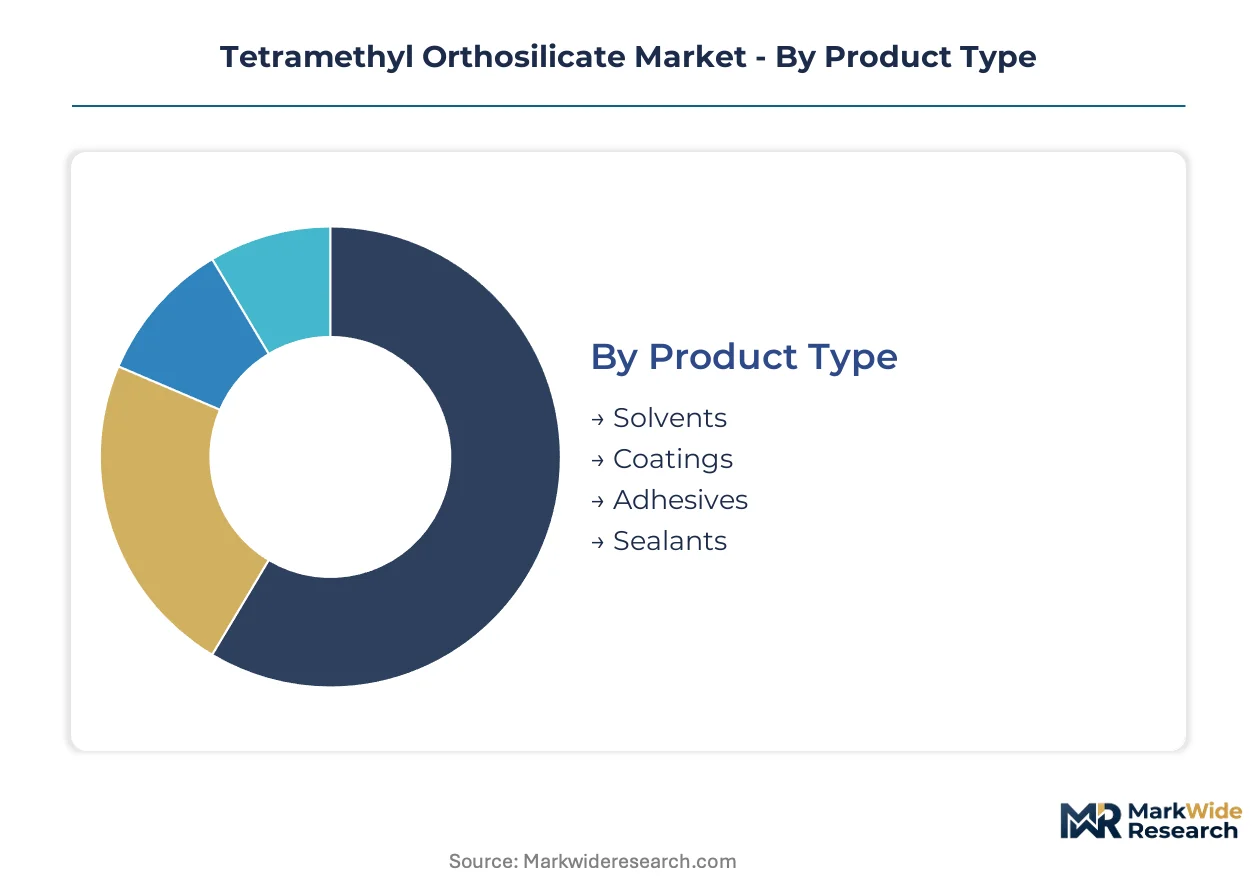
Segmentation in tetramethyl orthosilicate markets reveals how purity gradients and handling requirements split value capture across electronics-grade specification material and commodity solvent applications. Understanding these fault lines exposes where integrated producers defend margin pools against merchant competitors.
Product Type:
Electronics-grade specification material commands the widest margin spreads, while solvent-grade volumes compete on logistics density and drum-handling efficiency.
- Sealants:Moisture-cured silicone systems for infrastructure durability absorb mid-tier purity grades between 99.9% and 99.99%. Construction specifications in Jiangsu province and Tamil Nadu drive this segment as contractors specify long-life jointing compounds for commercial buildings.
- Coatings:Sol-gel derived silica layers for optical and protective films require controlled hydrolysis rates. Semiconductor fabrication facilities in Japan's Kansai region and Germany's Saxony cluster pull material with tight moisture-content specifications for dielectric deposition processes.
- Adhesives:Structural bonding applications for electronics assembly use alkoxysilane coupling at lower purity thresholds than deposition-grade material.
- Solvents:Mature application base faces displacement from tetraethyl orthosilicate and alternative silanes in cleaning and carrier applications.
The dominant share belongs to Sealants, while Coatings is closing the gap fastest as optical film demand expands.
Application:
End-use concentration follows regional manufacturing specialization, with electronics fabrication anchoring premium pricing and construction absorbing volume.
- Electronics:Atomic-layer deposition for sub-7nm semiconductor nodes demands 99.999%+ purity with metallic impurity controls below parts-per-billion. Shin-Etsu Chemical's domestic supply chain and China's Yangtze Memory Technologies cluster represent the primary demand anchors for this specification tier.
- Construction:Infrastructure sealant and coating formulators in China's Shandong province and India's Gujarat state consume material at relaxed purity grades where REACH and BIS compliance costs dominate specification discussions.
- Pharmaceuticals:Sol-gel encapsulation for controlled-release formulations uses pharmaceutical-grade handling protocols with dedicated batch documentation.
- Agriculture:Silica-based carrier systems for agrochemical delivery represent a thin margin pool with limited specification differentiation.
Electronics maintains the dominant value position, though Construction expands most quickly as moisture-cured systems penetrate emerging market infrastructure buildouts.
End User:
Procurement sophistication bifurcates between integrated manufacturers with captive specification teams and merchant distributors managing multi-product portfolios.
- Manufacturers:Integrated silane producers and specialty chemical formulators with backward integration into chlorosilane feedstocks command supply security advantages. Evonik Industries and Wacker Chemie anchor European captive consumption for coating precursors.
- Distributors:Regional logistics specialists in China's Jiangsu province and India's Maharashtra state manage drum-handling infrastructure and just-in-time delivery for mid-tier formulators.
- Researchers:Academic and national laboratory procurement operates at small batch scales with elevated documentation requirements for publication-grade reproducibility.
- Retailers:Limited direct participation given hazardous material handling restrictions and EPA emissions compliance burdens.
Manufacturers capture the dominant procurement volume, while Distributors gain share fastest as merchant chemical suppliers outsource logistics infrastructure.
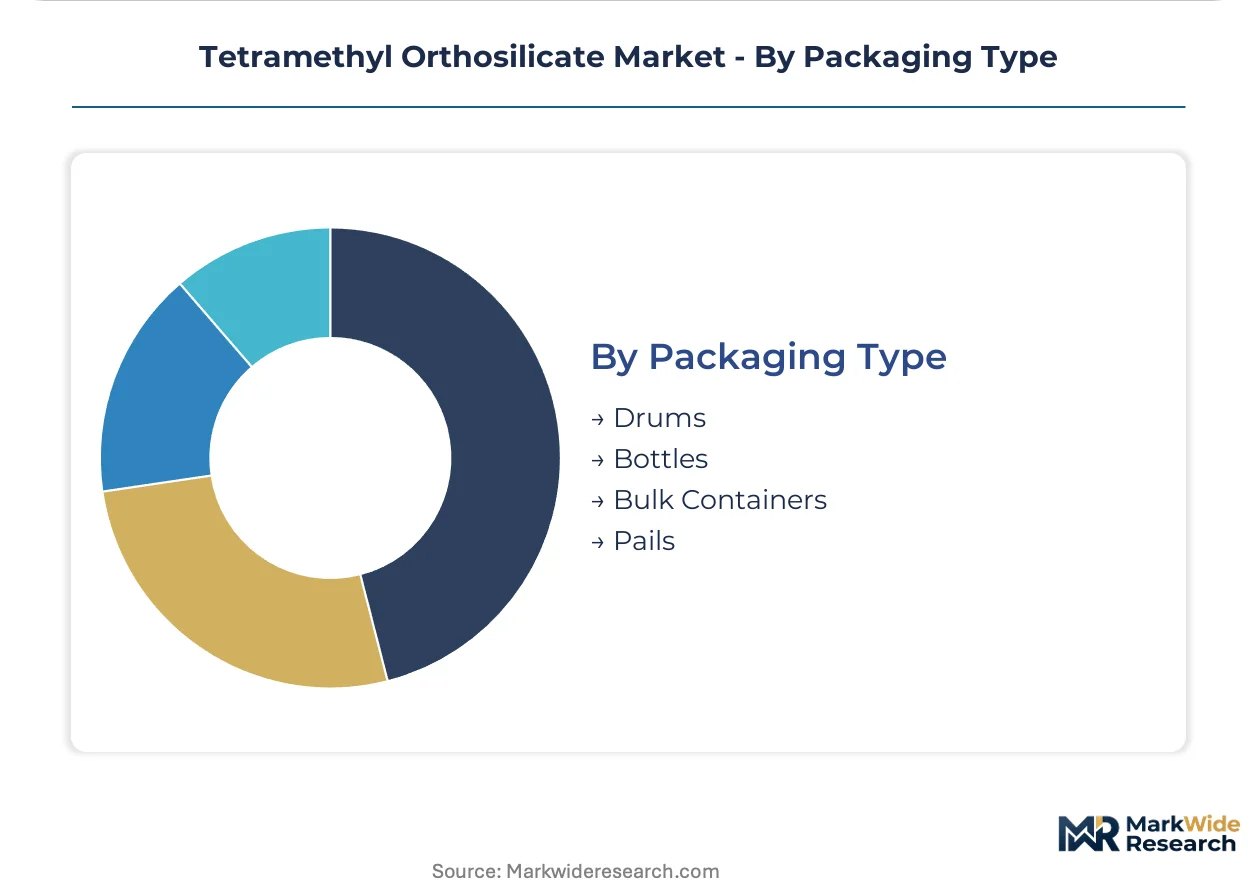
Packaging Type:
Handling infrastructure investment separates producers capable of electronics-grade contamination control from commodity suppliers.
- Drums:Standard 200-liter steel containers dominate mid-tier coating and adhesive formulator deliveries. Nantong Chengua Chemical competes on regional drum-return logistics density in Jiangsu province.
- Bulk Containers:ISO tank and flexitank systems for integrated semiconductor fabs enable closed-loop handling with nitrogen blanket protection against moisture ingress.
- Pails:Smaller-volume construction sector deliveries for sealant compounding with shorter shelf-life requirements.
- Bottles:Laboratory and research-scale packaging with amber glass or fluoropolymer lining for analytical reagent stability.
Drums retain the dominant shipment volume, though Bulk Containers climb the fastest as new semiconductor fabs in India and China commission dedicated precursor storage infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes tetramethyl orthosilicate predominantly for electronics-grade deposition, while Germany and the United States allocate larger shares to coatings and adhesive formulations. This consumption-mix differential shapes regional investment patterns and regulatory compliance burdens.
China
Semiconductor fabrication facilities in Jiangsu and Shandong provinces drive specification-grade demand for atomic-layer deposition processes. MIIT enforces GB standards for electronics-grade chemical purity, creating dual certification requirements for exporters. Yangtze Memory Technologies in Wuhan anchors domestic consumption of ultra-high-purity material.
Germany
Specialty coating formulators in Saxony and Bavaria absorb mid-tier purity grades for sol-gel optical films. REACH substance restrictions tighten handling requirements for volatile organic compound emissions. Wacker Chemie's Burghausen complex maintains backward integration into chlorosilane feedstocks for captive precursor supply.
United States
EPA hazardous air pollutant standards constrain drum-handling infrastructure for small-batch adhesive compounders. Construction sealant demand concentrates in Texas and California infrastructure markets. Momentive Performance Materials serves domestic electronics assemblers with specification-grade material certified for sub-7nm node compatibility.
Japan
Shin-Etsu Chemical's domestic fabrication customers pull material through METI-managed chemical supply chains. Atomic-layer deposition technician scarcity constrains throughput at new fabrication facilities in the Kansai region. Osaka-based formulators specify tighter moisture-content controls than competing Asian markets.
India
PLI scheme incentives for semiconductor and display fabrication create emerging demand clusters in Gujarat and Tamil Nadu. BIS compliance requirements for chemical intermediates extend qualification timelines for imported material. Ahmedabad-based coating formulators trial moisture-cured silicone systems for commercial building specifications.
Tetramethyl Orthosilicate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with purification capability separating premium electronics-grade suppliers from solvent-grade commodity players. The producer landscape bifurcates between backward-integrated silane manufacturers with captive chlorosilane supply and merchant chemical suppliers dependent on spot feedstock markets. Three strategic archetypes dominate: integrated organosilicon platforms, regional logistics specialists, and research-scale niche suppliers. Competitive moves concentrate on certification stacking for multi-jurisdiction compliance and closed-loop handling system deployment.
Within the integrated platform tier, Evonik Industries AG and Wacker Chemie AG exemplify European producers with upstream control over chlorosilane feedstocks. Nantong Chengua Chemical Co., Ltd. represents the regional logistics specialist archetype, competing on drum-return density and just-in-time delivery proximity to Jiangsu-based electronics manufacturers.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Wacker Chemie AG |
| Nantong Chengua Chemical Co., Ltd. |
| Zhangjiagang Xinya Chemical Co. |
| Jiangxi Chenguang New Materials Co. |
| Qufu Chenguang Chemical Co., Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials Inc. |
| Dalian Jiarui Chemical Co. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for electronics-grade material lock in supply access and price visibility for semiconductor fabs in Jiangsu province, insulating qualified suppliers from spot chlorosilane volatility while exposing non-integrated merchants to margin compression.
Pricing Analysis
After-sales service revenue from drum-return logistics and closed-loop handling systems drives lifetime value for regional distributors serving mid-tier formulators. Three-tier pricing structure across electronics-grade, sealant-grade, and solvent-grade material reflects certification burden divergence, with EPA emissions compliance and REACH substance restrictions intensifying cost compression in the solvent tier. Merchant suppliers without MIIT GB certification face the steepest price sensitivity from Chinese electronics assemblers.
Supply Chain Analysis
China and Germany anchor organosilicon production, with Jiangsu province hosting purification clusters for semiconductor-grade output and Saxony maintaining coating-grade formulation capabilities. Chlorosilane feedstock, methanol, and metallic catalyst inputs draw from energy-intensive upstream operations concentrated in Shandong and Burghausen. Single-source vulnerability runs through Shin-Etsu Chemical's captive supply chain for Japanese domestic fabs. Distribution runs through ISO tank systems for integrated electronics manufacturers and drum-return networks for construction sector formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through multi-jurisdiction certification stacking creates prohibitive switching costs for buyer procurement teams.
For Market Incumbents: Consolidate backward integration into chlorosilane feedstocks to defend against merchant supplier margin erosion from purification technology commoditization. Deepen certification stacking across METI, MIIT, and REACH frameworks to extend qualification timelines that freeze out emerging competitors. Prioritize capacity expansion in Gujarat and Tamil Nadu to capture PLI-scheme electronics manufacturing demand. For New Entrants and Emerging Players: BIS fast-track certification for imported material creates entry pathways into India's emerging semiconductor clusters before domestic production scales. Target moisture-cured silicone sealant formulators in Ahmedabad and Chennai as the most penetrable segment, where purity requirements remain relaxed and logistics proximity outweighs brand heritage. Deploy project-based qualification partnerships with display fabrication pilot lines to build certification history. For Investors and Strategic Acquirers: Capital is best deployed toward regional logistics specialists with demonstrated drum-return density and just-in-time delivery infrastructure. Over a five-to-ten year horizon, acquisition targets should exhibit captive chlorosilane supply or established MIIT certification history. Watch for inflection when atomic-layer deposition technician training programs in the Kansai region resolve throughput constraints at new fabrication facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Feedstocks | Wacker Chemie's Burghausen complex demonstrates margin defense against energy input volatility. |
| Multi-Jurisdiction Certification Stacking | Dual REACH and MIIT compliance extends qualification timelines for Yangtze Memory Technologies suppliers. |
| Closed-Loop Handling System Deployment | EPA hazardous air pollutant standards drive service-attach revenue for drum-handling infrastructure providers. |
| Regional Logistics Density Expansion | Nantong Chengua Chemical's Jiangsu drum-return network anchors just-in-time delivery for electronics assemblers. |
| Photovoltaic Dielectric Adjacency Entry | Heterojunction solar cell passivation requirements converge with existing semiconductor purification capabilities. |
Research Methodology
Operator-level perspectives from plant managers at chlorosilane production facilities, procurement leads at Jiangsu-based electronics manufacturers, distribution channel partners in Maharashtra, and technical R&D directors at coating formulators anchored the qualitative base. Primary interview findings triangulated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and MIIT GB standard documentation. Bottom-up volume estimates from end-use consumption patterns reconciled with top-down production capacity assessments across the analysis window.
Sensitivity analysis tested forecast robustness against chlorosilane feedstock price volatility, regulatory divergence scenarios, and alternative alkoxysilane substitution rates. The analytical framework modeled grade tier, end-use industry, packaging format, and regional production hub segmentation throughout the projection horizon. CAGRs derived from regression against semiconductor fabrication capital expenditure cycles and construction sector sealant specification trends. Photovoltaic dielectric coating adoption and atomic-layer deposition technician supply constraints served as industry-specific demand modifiers.
Decision-makers should treat outputs as directional under base assumptions of sustained semiconductor node shrinkage and stable REACH substance restriction enforcement; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in EPA hazardous air pollutant standards, MIIT GB specification updates, and PLI scheme incentive modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Vaterite Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Ceramic Additives Market
Ceramics
Glazed Bricks Market
Ceramics
India Kaolin Market
Ceramics
Calcium Silicate Boards Market
Ceramics
Global Ceramic Balls Market
Ceramics
Calcined Alumina Market
Ceramics
Ceramic Frit Market
Ceramics
Calcium Oxide Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Global Barium Carbonate Market
Ceramics
Ball Clay Market
Ceramics
Strontium Carbonate Market
Ceramics
Ceramic Setter Plate Market
Ceramics
Brazil Ceramic Tiles Market