
 Multichannel Reagent Reservoir Market | 2026-2036
Multichannel Reagent Reservoir Market Size, Share, and Industry Trends Forecast 2026-2036
Multichannel Reagent Reservoir Market Foresight
ISO 13485 certification is reorganizing competitive access in the multichannel reagent reservoir supply base, forcing contract manufacturers and brand holders alike to recalibrate quality management systems against medical device-grade expectations. Thermo Fisher Scientific leverages its diagnostic division's existing ISO 13485 infrastructure to anchor reservoir production within regulated end-use channels. INTEGRA Biosciences specializes in multichannel pipetting ecosystems and extends its reservoir offerings through tightly coupled consumable strategies. Corning competes on material science leadership, drawing on its glass and advanced polymer portfolios to differentiate reservoir performance in high-throughput screening environments.
Multichannel reagent reservoirs are precision-molded liquid containment vessels engineered with multiple parallel channels to enable simultaneous dispensing across 8-, 12-, or 96-channel pipetting heads, typically manufactured from virgin polypropylene or optically clear polystyrene with tight dimensional tolerances of ±0.1 mm to ensure tip seal integrity during automated liquid handling. Their primary purpose is to reduce cross-contamination risk and improve dispensing accuracy in high-volume screening, diagnostic, and genomic workflows where reagent waste minimization directly impacts operational economics. Standard reservoirs remain the volume backbone for routine clinical diagnostics, while high-throughput reservoirs capture expanding demand from pharmaceutical research operations running round-the-clock automated screens. Polypropylene dominates material selection due to its chemical resistance and low extractable profile, though polycarbonate variants gain traction in environmental testing applications requiring optical clarity for visual volume verification.
FDA 21 CFR Part 820 quality system regulations and the EU In Vitro Diagnostic Regulation (IVDR) impose design control and post-market surveillance obligations on reservoir suppliers serving diagnostic device OEMs, effectively raising barriers for undifferentiated commodity producers. ISO 8655 pipetting accuracy standards and CLSI liquid handling guidelines further shape product specifications by defining acceptable volumetric performance thresholds that reservoir geometry must support. Stakeholders must monitor evolving IVDR technical documentation requirements and assess whether backward integration into certified cleanroom molding or forward partnerships with notified bodies offers more defensible positioning as regulatory scrutiny intensifies.
Market Dynamics
ISO 13485 certification requirements are restructuring supplier qualification criteria across diagnostic device supply chains, forcing reservoir manufacturers to rebuild quality management systems around medical device-grade traceability and post-market surveillance obligations.
Growth Catalysts
- High-throughput screening expansion:Pharmaceutical R&D clusters in the United States, Germany, and China are deploying round-the-clock automated liquid handling workflows that demand multichannel-compatible reservoir systems with tight dimensional tolerances.
- EU IVDR implementation:The In Vitro Diagnostic Regulation's technical documentation and design control mandates are filtering out undifferentiated commodity producers, creating volume consolidation opportunities for certified suppliers serving diagnostic OEMs.
- Polypropylene material dominance:Virgin polypropylene's chemical resistance and low extractable profile continue displacing alternative materials in genomic and clinical diagnostic applications where reagent integrity is paramount.
Market Restraints
- Petrochemical input volatility:Virgin polypropylene and polystyrene resin prices fluctuate with crude oil markets, compressing margin stability for precision-molded consumable producers operating on fixed-price hospital contracts.
- Cleanroom molding concentration:ISO 14644 Class 7 certified injection molding capacity concentrates among specialized contract manufacturers in Germany and Switzerland, creating single-source dependencies for diagnostic device OEMs.
- Dimensional tolerance limits:±0.1 mm sealing surface specifications require cavity-to-cavity consistency that legacy multi-cavity tooling cannot achieve without substantial retooling investment.
Strategic Opportunities
- Environmental testing vertical:Polycarbonate reservoir variants with optical clarity are capturing workflow share in water quality and soil analysis laboratories requiring visual volume verification during field sample processing.
- India biopharma manufacturing:CDSCO's streamlined medical device registration pathways and PLI scheme incentives are attracting reservoir suppliers to serve emerging contract research and manufacturing organizations in Hyderabad and Bangalore clusters.
- Digital traceability integration:Convergence of molded-in 2D datamatrix codes with laboratory information management systems enables lot-level reagent tracking that differentiates premium reservoir positioning.
Industry Challenges
- ISO 13485 audit backlog:Notified body capacity constraints in Europe and North America are extending certification timelines from 12 to 24 months, delaying market entry for new reservoir product lines.
- Automated liquid handling integration:Tip seal geometry variations across pipetting platform OEMs force reservoir suppliers to maintain multiple cavity tooling configurations, inflating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multichannel Reagent Reservoir Market |
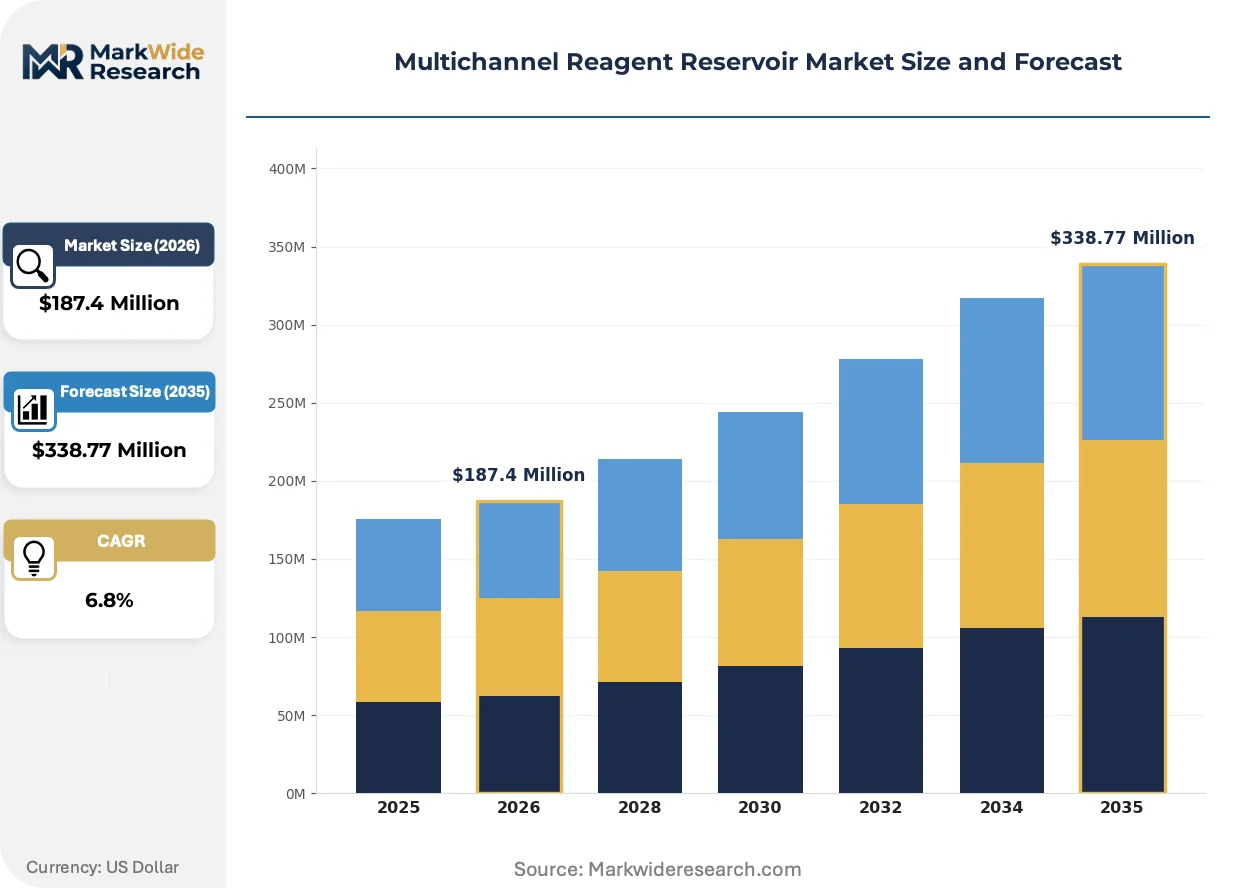
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Reservoirs, High-Throughput Reservoirs, Low-Volume Reservoirs, Custom Reservoirs Material: Polypropylene, Polystyrene, Polycarbonate, Glass Application: Clinical Diagnostics, Pharmaceutical Research, Environmental Testing, Biotechnology End User: Laboratories, Research Institutions, Academic Institutions, Hospitals |
| Companies Covered | Thermo Fisher Scientific, Corning, INTEGRA Biosciences, Merck, Bio-Rad, Heathrow Scientific, VISTALAB Technologies, Argos Technologies, Hirschmann Laborgeräte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multichannel Reagent Reservoir Market Shifts & Advancements
Modular reservoir architectures are displacing fixed-format designs as pharmaceutical screening operations demand rapid reconfiguration between 8-channel, 12-channel, and 96-channel pipetting protocols without workflow interruption.
Stackable polypropylene reservoir systems with shared base geometries are decomposing traditional single-use consumption patterns in high-throughput screening facilities. Contract research organizations running 24-hour automated compound libraries are adopting nestable designs that reduce storage footprint and waste disposal costs. This standardization is compressing supplier differentiation around ancillary features like graduated volume markings and pour spout geometries rather than fundamental channel configurations.
The EU In Vitro Diagnostic Regulation's post-market surveillance requirements are mandating design history files and risk management documentation that reservoir suppliers previously reserved for Class II medical devices. Diagnostic device OEMs in Germany and the Netherlands are now requiring supplier quality agreements with defined change notification protocols. Medium-volume reservoir producers without established regulatory affairs functions are exiting the European diagnostic channel rather than absorbing compliance infrastructure costs.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships in United States hospital laboratory networks. IDN-affiliated clinical diagnostics departments in California and Massachusetts are mandating sole-source contracts with ISO 13485-certified suppliers who can demonstrate lot traceability back to virgin resin certificates of analysis. This channel compression is favoring reservoir producers with existing diagnostic division infrastructure over pure-play consumable specialists.
Multichannel Reagent Reservoir Market Segmentation
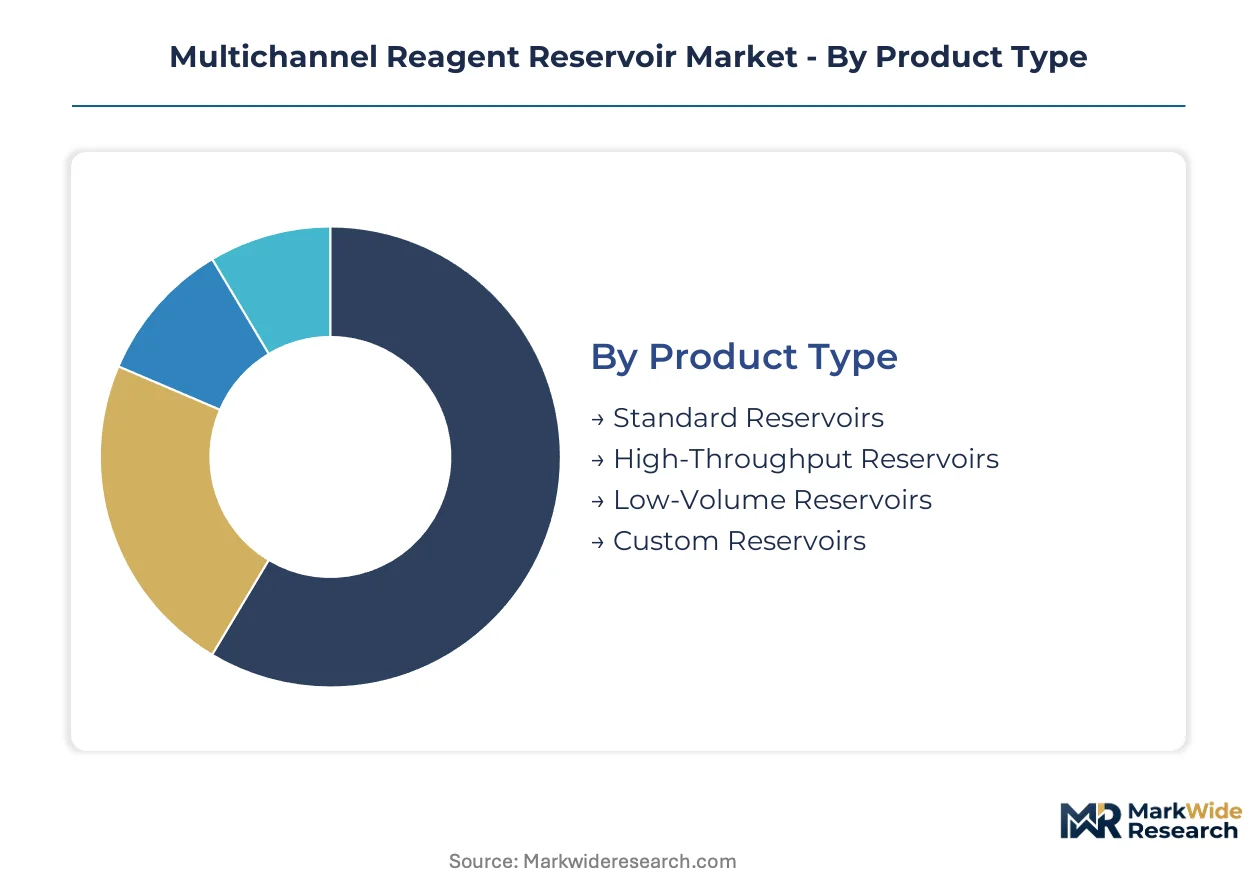
Segmentation in the multichannel reagent reservoir market reveals how regulatory requirements, material science capabilities, and workflow automation intensity create distinct procurement patterns across end-use channels. Understanding these divides enables suppliers to align certification investments with addressable volume pools.
Product Type:
Standard reservoirs dominate domestic procurement in the United States and Germany where hospital laboratory networks prioritize supply security over customization. High-throughput variants drive export-led demand from Swiss and Singaporean contract manufacturers serving global pharmaceutical screening operations.
- Standard Reservoirs:Virgin polypropylene construction with fixed 8-channel and 12-channel geometries serves routine clinical chemistry and immunoassay workflows. Demand concentrates in United States hospital IDNs and German hospital networks where ISO 13485 certification is mandatory for vendor qualification; procurement runs through sole-source contracts with demonstrated lot traceability.
- High-Throughput Reservoirs:Precision-molded 96-channel configurations with ±0.1 mm sealing surface tolerances support round-the-clock automated compound screening. Export-led demand from Swiss contract research organizations and Singaporean biopharma manufacturing hubs drives volume; these facilities prioritize nestable designs that minimize storage footprint and waste disposal costs.
- Low-Volume Reservoirs:Specialized geometries for genomic and proteomic applications requiring microliter-scale dispensing accuracy.
- Custom Reservoirs:Application-specific channel configurations and proprietary base geometries developed under exclusive supply agreements with diagnostic device OEMs.
Standard reservoirs hold the largest share; momentum sits with high-throughput variants.
Material:
Material selection stratifies across cost tiers and performance requirements, with polypropylene commanding premium positioning in regulated diagnostic channels while optical-grade alternatives capture specialized environmental applications.
- Polypropylene:Virgin resin with low extractable profiles and broad chemical resistance dominates clinical diagnostics and pharmaceutical research. United States and German diagnostic device OEMs mandate certificates of analysis tracing back to resin batch; this specification tier commands pricing premiums over regrind alternatives.
- Polystyrene:Optically clear amorphous polymer enables visual volume verification in colorimetric assays. Demand clusters in academic research institutions and smaller biotechnology operations where cost sensitivity outweighs extractable concerns; these segments source through distribution rather than direct manufacturer relationships.
- Polycarbonate:High-impact transparency supports field-based environmental testing workflows requiring ruggedized containment.
- Glass:Borosilicate and soda-lime variants serve legacy analytical protocols and solvent-intensive applications where polymer extractables are unacceptable.
Polypropylene anchors volume procurement; polycarbonate is climbing the fastest on environmental testing expansion.
Application:
Application segmentation tracks the divergence between regulated diagnostic workflows with mandatory quality documentation and research environments where flexibility outweighs compliance overhead.
- Clinical Diagnostics:FDA 21 CFR Part 820 and EU IVDR design control requirements govern reservoir supply to in vitro diagnostic device manufacturers. United States hospital laboratories and German clinical diagnostics departments drive procurement through consolidated IDN contracts; ISO 13485 certification is non-negotiable for vendor inclusion.
- Pharmaceutical Research:High-throughput screening operations in Massachusetts and Basel biopharma clusters demand multichannel-compatible systems with rapid protocol reconfiguration. These facilities prioritize workflow throughput over regulatory documentation, enabling faster supplier onboarding.
- Environmental Testing:Field and laboratory water quality analysis requiring optical clarity for visual verification.
- Biotechnology:Cell culture and molecular biology applications spanning research-grade and GMP-adjacent workflows.
Clinical diagnostics commands the highest certification barriers; pharmaceutical research shows the steepest expansion trajectory.
End User:
End-user segmentation exposes a procurement divide between consolidated institutional buyers with formal vendor qualification programs and fragmented academic purchasers operating through distributor channels.
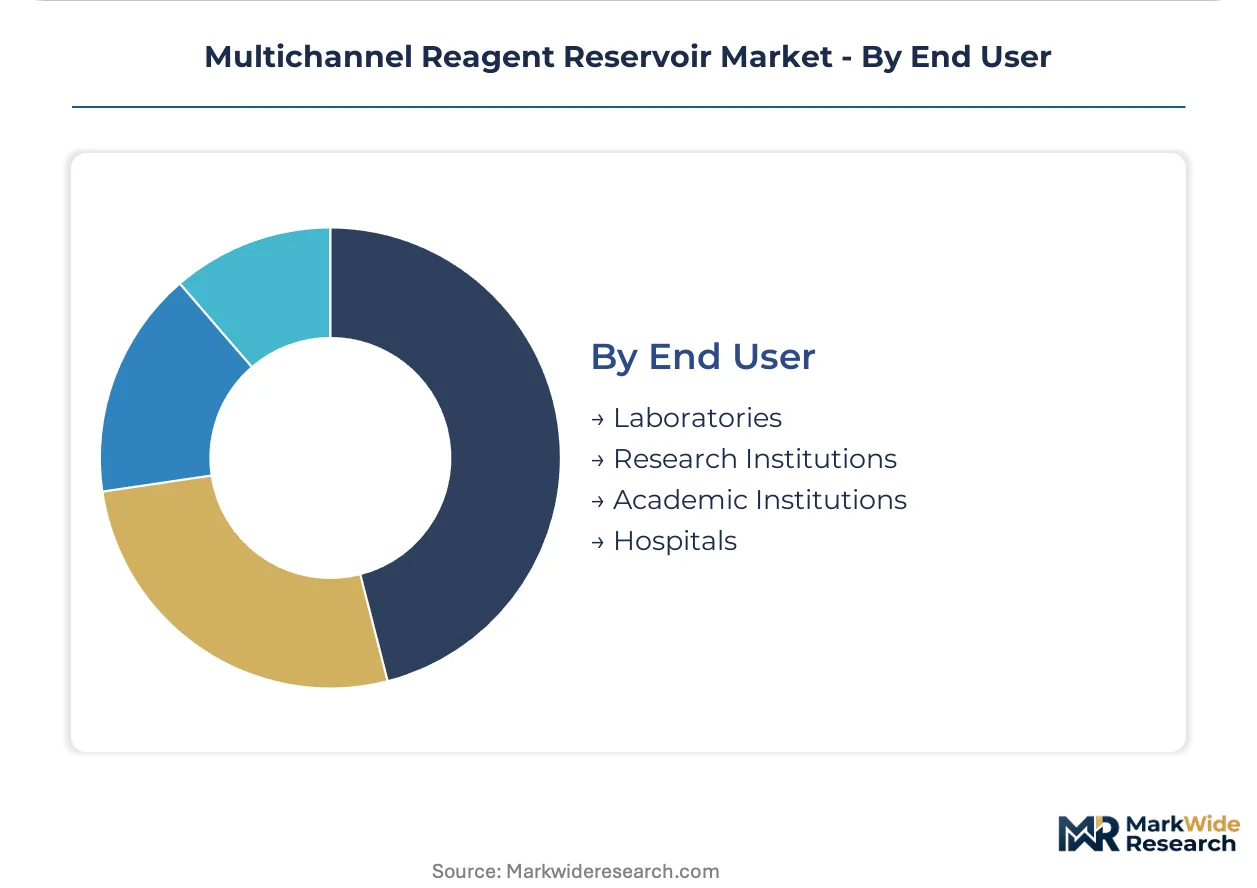
- Laboratories:Commercial and hospital-affiliated testing facilities with standardized automated liquid handling platforms. United States and German laboratory networks concentrate purchasing through group purchasing organizations; these entities mandate ISO 13485 certification and documented change control protocols.
- Research Institutions:Contract research organizations and government research facilities with project-based procurement flexibility. Singaporean and Swiss CROs drive demand for modular reservoir architectures supporting rapid reconfiguration between screening protocols.
- Academic Institutions:University research laboratories with decentralized purchasing authority and price-sensitive procurement patterns.
- Hospitals:Integrated delivery network clinical diagnostics departments with enterprise-level supply agreements.
Laboratories represent the deepest volume pool; research institutions are gaining share fastest on CRO expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital integrated delivery networks and pharmaceutical R&D clusters concentrate procurement power across three dominant geographies. United States IDNs, German hospital networks, and Chinese biopharma manufacturing hubs drive volume demand for ISO 13485-certified reservoir systems. These buyer archetypes prioritize supply security, regulatory documentation, and automated workflow compatibility over unit cost minimization.
United States
Massachusetts and California biopharma clusters deploy round-the-clock high-throughput screening operations requiring multichannel-compatible reservoir geometries. FDA 21 CFR Part 820 quality system regulations govern supply relationships with diagnostic device OEMs. IDN-affiliated clinical laboratories in California and Massachusetts mandate sole-source contracts with demonstrated lot traceability back to virgin resin certificates of analysis.
Germany
Hospital laboratory networks in Bavaria and North Rhine-Westphalia prioritize supply security for routine clinical chemistry workflows. EU IVDR technical documentation and design control mandates filter out undifferentiated commodity producers. ISO 14644 Class 7 certified injection molding capacity concentrates in southern German manufacturing zones serving diagnostic device OEMs with mandatory change notification protocols.
China
Biopharma contract manufacturing organizations in Shanghai and Suzhou industrial parks expand automated liquid handling infrastructure for export-oriented pharmaceutical production. NMPA medical device registration pathways align with international quality standards for IVD component suppliers. Yangtze River Delta manufacturing clusters attract reservoir producers seeking to serve both domestic diagnostic device makers and multinational pharmaceutical operations.
Switzerland
Basel-based contract research organizations drive demand for nestable high-throughput reservoir designs minimizing storage footprint in 24-hour screening facilities. Swissmedic medical device oversight requires supplier quality agreements with defined post-market surveillance obligations. Precision molding specialists in the Basel biopharma corridor maintain multiple cavity tooling configurations to serve diverse pipetting platform geometries.
India
Contract research and manufacturing organizations in Hyderabad and Bangalore clusters expand procurement of multichannel-compatible consumables for global pharmaceutical clients. CDSCO streamlined medical device registration pathways and PLI scheme incentives attract reservoir suppliers establishing local production. Telangana and Karnataka biopharma manufacturing zones prioritize ISO 13485-certified component sourcing for export-oriented diagnostic device assembly.
Multichannel Reagent Reservoir Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with existing diagnostic division infrastructure and specialized liquid handling consumable producers. The supplier base stratifies into three tiers: ISO 13485-certified manufacturers serving regulated diagnostic channels, research-grade specialists capturing pharmaceutical R&D volume, and undifferentiated commodity producers facing channel compression. Strategic moves concentrate on regulatory certification investments, cleanroom molding capacity expansion, and exclusive supply agreements with diagnostic device OEMs requiring design history file documentation.
Among diversified life science conglomerates, Thermo Fisher Scientific anchors the premium-regulated tier through its diagnostic division's existing quality management infrastructure. Corning occupies a position exemplifying material science-led differentiation, drawing on glass and advanced polymer portfolios. INTEGRA Biosciences sits within the specialized liquid handling ecosystem tier, extending reservoir offerings through tightly coupled consumable strategies aligned with multichannel pipetting platforms.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Corning |
| INTEGRA Biosciences |
| Merck |
| Bio-Rad |
| Heathrow Scientific |
| VISTALAB Technologies |
| Argos Technologies |
| Hirschmann Laborgeräte |
| Others |
Supply & Pricing Matrix
Ninety-day resin inventory buffers at German ISO 14644 Class 7 molding facilities concentrate pricing power among certified suppliers serving FDA and IVDR-regulated diagnostic channels, while spot-market purchasers absorb petrochemical volatility through quarterly renegotiation cycles. This inventory-service trade-off stratifies the supplier base into locked-in contract manufacturers with indexed raw material pass-throughs versus research-grade distributors exposed to spot resin swings.
Pricing Analysis
Fixed-price annual contracts with virgin polypropylene indexation dominate procurement relationships between reservoir producers and United States hospital IDNs, insulating certified suppliers from crude oil volatility while locking in margin stability. Price differentiation rests on ISO 13485 certification tier and lot-traceability documentation depth, with diagnostic-grade reservoirs commanding substantial premiums over research-grade alternatives. Cost compression in the academic and biotechnology distributor channel intensifies as polystyrene alternatives displace polypropylene in non-regulated workflows. Academic institutions exhibit the highest price sensitivity, prioritizing per-unit cost over extractable profiles, while German hospital networks demonstrate the lowest sensitivity, mandating supply security through sole-source agreements with full documentation.
Supply Chain Analysis
Just-in-time resin procurement prevails among Swiss and Singaporean contract research organizations running 24-hour screening operations, whereas German and United States diagnostic device OEMs maintain strategic stockpiles of certified virgin polypropylene to ensure uninterrupted production. Geographic supply concentration centers on southern Germany, Switzerland, and the Yangtze River Delta manufacturing corridor, with precision molding capacity anchored in ISO 14644 Class 7 facilities. Raw material dependencies include virgin polypropylene resin, optical-grade polycarbonate, and precision-machined multi-cavity tooling. Single-source vulnerability concentrates in specialized cleanroom injection molding, where retooling timelines extend certification delays. Distribution runs through group purchasing organizations in United States hospital networks and direct manufacturer relationships in pharmaceutical R&D clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multichannel pipetting platform interoperability is reshaping reservoir procurement from standalone consumable transactions toward ecosystem-locked subscription models, as diagnostic device OEMs prioritize tip-seal geometry standardization across automated liquid handling fleets.
For Market Incumbents: Shield diagnostic division revenue streams by accelerating ISO 13485 certification coverage across all production facilities, then deepen backward integration into virgin resin compounding to capture margin from petrochemical volatility. The priority lever sits with exclusive supply agreements mandating design history file documentation, locking out research-grade specialists attempting IVDR channel entry. For New Entrants and Emerging Players: Anchor in the environmental testing vertical, where polycarbonate optical clarity requirements and lower regulatory documentation burdens create accessible procurement pathways outside diagnostic OEM qualification programs. Target water quality analysis laboratories in North America and Europe with field-ruggedized reservoir geometries, then build distributor relationships rather than direct sales infrastructure to minimize working capital requirements. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because IVDR technical documentation mandates and ISO 13485 audit backlogs are structurally filtering out mid-volume producers, concentrating volume among diversified conglomerates with established regulatory affairs functions. The signal to watch is notified body capacity expansion announcements in Europe and North America, which would accelerate certification timelines and temporarily reopen competitive entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Expansion | Unlocks IVDR-regulated diagnostic OEM procurement channels previously closed to research-grade suppliers. |
| Backward Integration into Resin Compounding | Captures margin from petrochemical volatility and secures virgin polypropylene supply for medical-grade production. |
| Modular Reservoir Architecture Development | Enables rapid reconfiguration between 8-channel, 12-channel, and 96-channel pipetting protocols without workflow interruption. |
| Digital Traceability Integration | Converges molded-in 2D datamatrix codes with laboratory information management systems for lot-level reagent tracking. |
| Exclusive Supply Agreement Negotiation | Locks in diagnostic device OEM relationships through design history file documentation and change notification protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU IVDR technical documentation databases, and SEC 10-K disclosures from diversified life science conglomerates, with bottom-up and top-down triangulation across product type, material grade, and end-use channel segmentation. Primary interviews engaged diagnostic device OEM procurement managers, ISO 13485 quality systems directors at contract manufacturers, and laboratory operations heads at contract research organizations in Massachusetts, Basel, and Singapore. Secondary validation drew from hospital group purchasing organization contract databases, cleanroom molding capacity registries, and virgin polypropylene resin certificate-of-analysis repositories.
Segmentation dimensions modeled include product configuration, material specification, application workflow, and end-user procurement authority, with volume and value outputs derived from cross-referencing automated liquid handling platform installation bases against per-platform reservoir consumption rates. CAGRs were constructed from annual procurement surveys and platform deployment tracking across pharmaceutical R&D clusters. Industry-specific forecast inputs incorporated ISO 13485 certification timeline projections and notified body capacity constraints.
Material uncertainties — petrochemical price volatility, IVDR implementation enforcement variance, and cleanroom molding capacity expansion delays — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory compliance timeline stability and diagnostic device OEM vendor qualification protocol continuity. Revision becomes warranted when ISO 13485 audit backlog durations cross thresholds that materially alter competitive entry dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Anti-Static Control Products Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Middle East and Africa Amino Acids Market
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Gallic Acid Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Dimethicone Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Barium Derivatives Market
Specialty Chemicals
Cellulose Esters and Ethers Market