
 Long Term Post-Acute Care Software Market | 2026-2036
Long Term Post-Acute Care Software Market Size, Share, and Industry Trends Forecast 2026-2036
Long Term Post-Acute Care Software Market Foresight
Subscription-based financing and software-as-a-service leasing is narrowing the competitive field for capital-constrained post-acute operators. PointClickCare leverages cloud-native architecture to sustain dominance in skilled nursing EHR integration. WellSky anchors its position through specialized home health workflow tools. MatrixCare differentiates via assisted living-specific revenue cycle management.
Long term post-acute care software encompasses clinical documentation, care coordination, billing, and compliance management platforms engineered to support patients transitioning from hospital to community settings, typically operating across HL7 FHIR interoperability standards and CMS-driven assessment protocols. EHR Integration and Care Coordination product segments lead current deployment volumes, while Analytics Tools represents the fastest-expanding margin pool as risk-bearing contracts proliferate. Cloud-Based deployment now outpaces On-Premise installations among new buyers, though Hybrid architectures persist in regions with intermittent connectivity.
FDA oversight of clinical decision support modules, HIPAA security rule enforcement by HHS, and CMS Conditions of Participation for skilled nursing facilities collectively elevate software validation requirements and data governance standards. These frameworks compel vendors to embed audit trails, encryption, and interoperability certification directly into platform architecture. Stakeholders must evaluate whether their technology stacks can absorb pending interoperability mandates without disrupting existing revenue cycle workflows.
Market Dynamics
Value-based reimbursement mandates from CMS are compressing margins across skilled nursing operators, forcing software procurement toward platforms that bundle clinical documentation with real-time quality metrics and automated compliance reporting.
Growth Catalysts
- CMS Conditions of Participation:Federal mandates for electronic health record interoperability in skilled nursing facilities are accelerating replacement of paper-based assessment workflows with integrated digital platforms.
- Hospital-at-home programs:Medicare waiver expansions for acute-level care in residential settings are extending software demand beyond traditional facility boundaries into home health monitoring ecosystems.
- HL7 FHIR R4:Standardized API protocols are reducing integration friction between post-acute EHRs and hospital systems, lowering switching costs for multi-site provider networks.
Market Restraints
- Cloud infrastructure concentration:AWS and Azure dominance in healthcare-compliant hosting creates single-supplier vulnerability for SaaS vendors serving rural post-acute operators with limited connectivity alternatives.
- HIPAA Security Rule enforcement:HHS Office for Civil Rights audit frequency is elevating compliance insurance premiums and legal review costs for software implementations.
- Legacy mainframe persistence:State Medicaid systems running COBOL-based claims processing impose format-translation burdens that delay real-time eligibility verification for newer platforms.
Strategic Opportunities
- Behavioral health integration:Unmet demand for substance use disorder and psychiatric care coordination within skilled nursing creates white space for specialized workflow modules.
- Remote patient monitoring convergence:Wearable device data streams combined with predictive analytics are enabling early-intervention protocols that reduce 30-day readmission penalties.
- Rural Health Clinic designation:CMS facility-type expansions in underserved counties are opening addressable markets previously excluded from enterprise software sales coverage.
Industry Challenges
- Interoperability engineer scarcity:Healthcare IT labor markets lack sufficient talent versed in both FHIR implementation and legacy HL7 v2 message transformation.
- Revenue cycle reconfiguration:Skilled nursing operators must retrain billing staff on PDPM (Patient-Driven Payment Model) case-mix calculations while maintaining legacy RUG-IV parallel systems during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long Term Post-Acute Care Software Market |
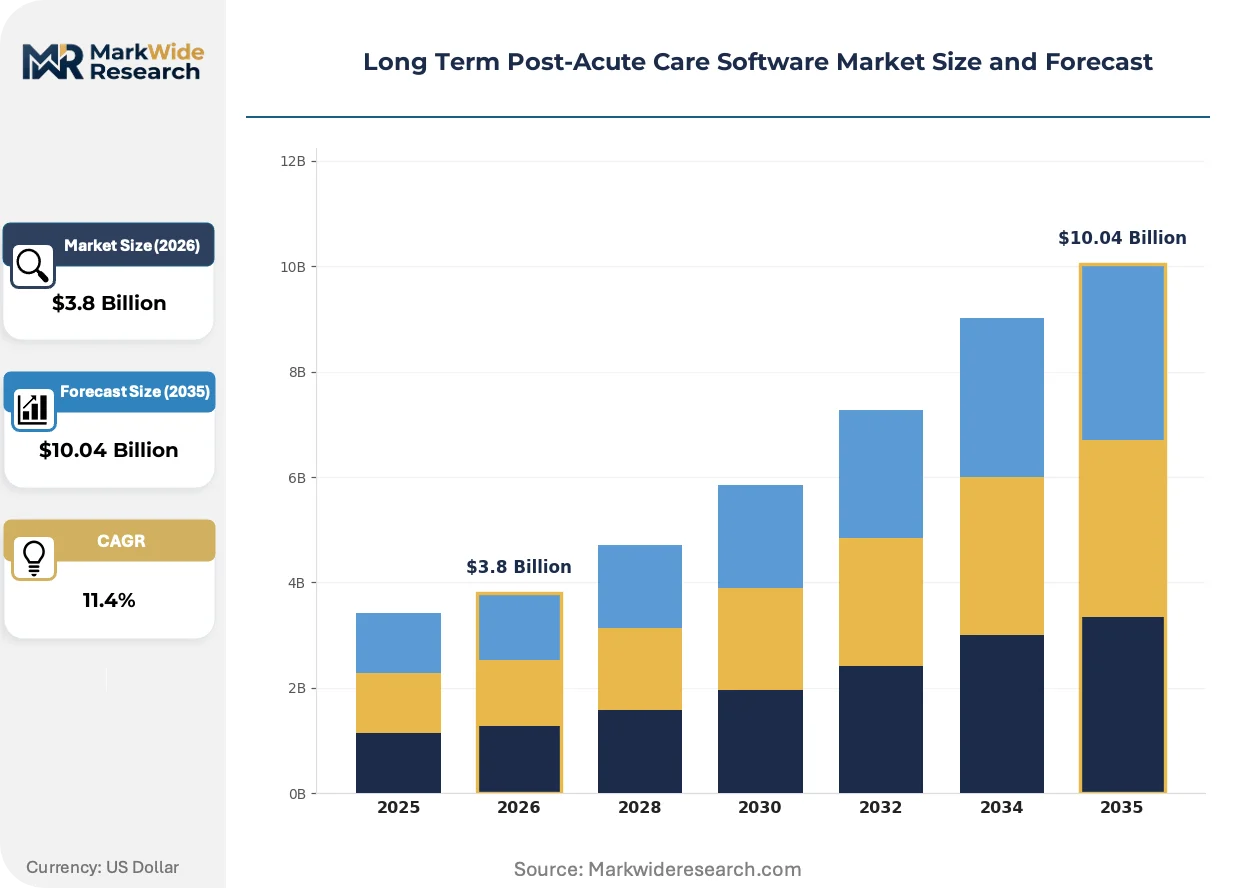
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Care Coordination, EHR Integration, Patient Management, Analytics Tools End User: Skilled Nursing Facilities, Home Health Agencies, Rehab Centers, Assisted Living Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Solutions Service Type: Implementation, Training, Maintenance, Support |
| Companies Covered | PointClickCare, MatrixCare, Netsmart Technologies, Epic Systems Corporation, Oracle Health, Allscripts Healthcare Solutions, McKesson Corporation, Veradigm, WellSky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long Term Post-Acute Care Software Market Shifts & Advancements
Artificial intelligence is penetrating clinical decision support at the point of care, shifting software value propositions from documentation efficiency toward predictive risk stratification and automated care plan generation.
Natural language processing is migrating from retrospective coding assistance to real-time clinical documentation capture. Skilled nursing facilities with high staff turnover are deploying voice-enabled EHR interfaces to reduce training burdens. This compression of documentation time is enabling higher patient-to-staff ratios without regulatory penalty exposure.
CMS interoperability mandates under the 21st Century Cures Act are compelling EHR vendors to expose standardized APIs for patient data exchange. Post-acute operators face civil monetary penalties for information blocking, accelerating procurement of certified platforms. Smaller home health agencies are consolidating vendor relationships to reduce compliance audit surface area.
Subscription financing is displacing perpetual license purchases among capital-constrained operators. Private equity-backed post-acute chains are prioritizing opex-aligned SaaS contracts that preserve leverage ratios. This shift is visible most acutely in the Southeast, where rural facility acquisitions have concentrated ownership under regional platforms with standardized technology stacks.
Long Term Post-Acute Care Software Market Segmentation
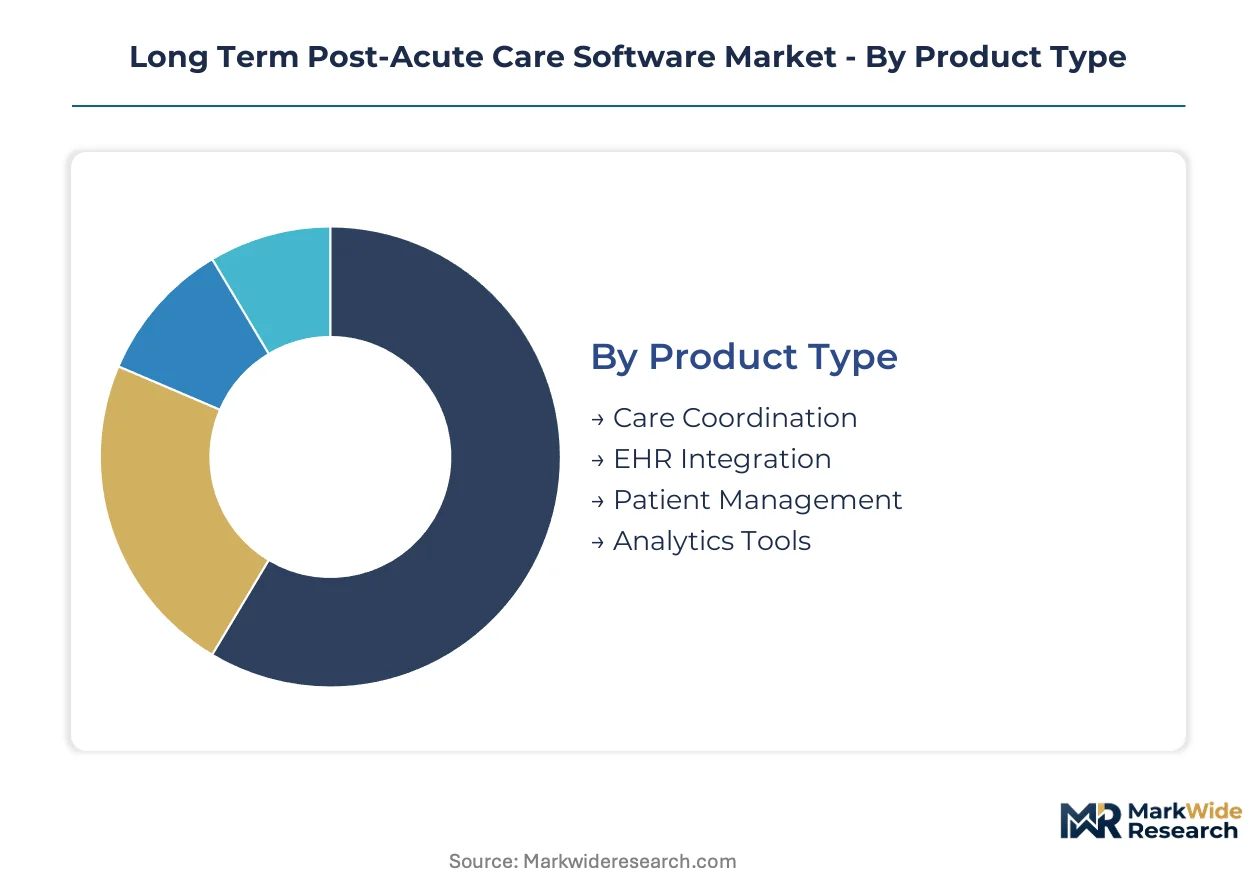
Segmentation in post-acute care software reflects divergent clinical workflows and capital constraints across facility types. Procurement patterns vary sharply between enterprise chains seeking unified platforms and independent operators prioritizing modular point solutions.
Product Type:
Use cases span from real-time clinical documentation to retrospective quality analytics, with each product category serving distinct operational pain points across the post-acute continuum.
- EHR Integration:Platforms embedding HL7 FHIR APIs to synchronize patient records between hospital discharge systems and skilled nursing admission workflows. Demand concentrates in multi-site skilled nursing chains across Texas and Florida facing CMS interoperability penalties.
- Care Coordination:Multi-disciplinary communication hubs connecting physicians, therapists, and home health nurses through shared care plans. Home health agencies in California and New York are driving deployment to manage hospital-at-home patient handoffs under Medicare waiver expansions.
- Patient Management:Scheduling, medication administration, and mobility tracking modules for frontline nursing staff.
- Analytics Tools:Predictive risk stratification engines identifying readmission probability and length-of-stay optimization opportunities.
The dominant share belongs to EHR Integration, while Analytics Tools is closing the gap fastest.
End User:
Facility licensing and reimbursement complexity creates tiered software requirements, with Medicare-certified providers facing stricter documentation mandates than residential care operators.
- Skilled Nursing Facilities:Medicare-certified sites requiring PDPM-compliant assessment workflows, MDS submission automation, and quality measure reporting. Operators in Illinois and Ohio are replacing legacy systems to meet CMS Conditions of Participation deadlines.
- Home Health Agencies:Mobile-first platforms supporting OASIS-E assessments and remote patient monitoring integration. Agencies in Arizona and North Carolina are expanding into rural counties previously excluded from managed care network contracts.
- Rehab Centers:Inpatient rehabilitation facilities tracking functional improvement metrics for IRF-PPS reimbursement.
- Assisted Living:Non-medical residential operators prioritizing resident engagement and family communication portals over clinical documentation depth.
Skilled Nursing Facilities command the largest procurement budgets, though Home Health Agencies are expanding their addressable software spend most rapidly.
Deployment:
Infrastructure choices reflect connectivity reliability, IT staffing levels, and private equity ownership structures that favor operational expenditure alignment.
- Cloud-Based:Multi-tenant SaaS architectures with automatic CMS compliance updates and AWS or Azure hosting. New buyers in Georgia and Tennessee are defaulting to cloud deployments to avoid capital-intensive server procurement.
- Hybrid:Local edge computing for clinical documentation with cloud synchronization for analytics and reporting. Rural operators in Montana and Idaho with intermittent broadband rely on hybrid stacks to maintain operations during connectivity outages.
- On-Premise:Self-hosted installations retaining full data custody for compliance-averse operators.
- Mobile Solutions:Tablet-native interfaces for point-of-care documentation by roaming nursing staff.
Cloud-Based deployment leads new installations, while Hybrid architectures are gaining traction fastest among rural and frontier facility networks.
Service Type:
Post-implementation support structures determine long-term platform stickiness, with labor-intensive training and change management representing the highest-margin vendor revenue streams.
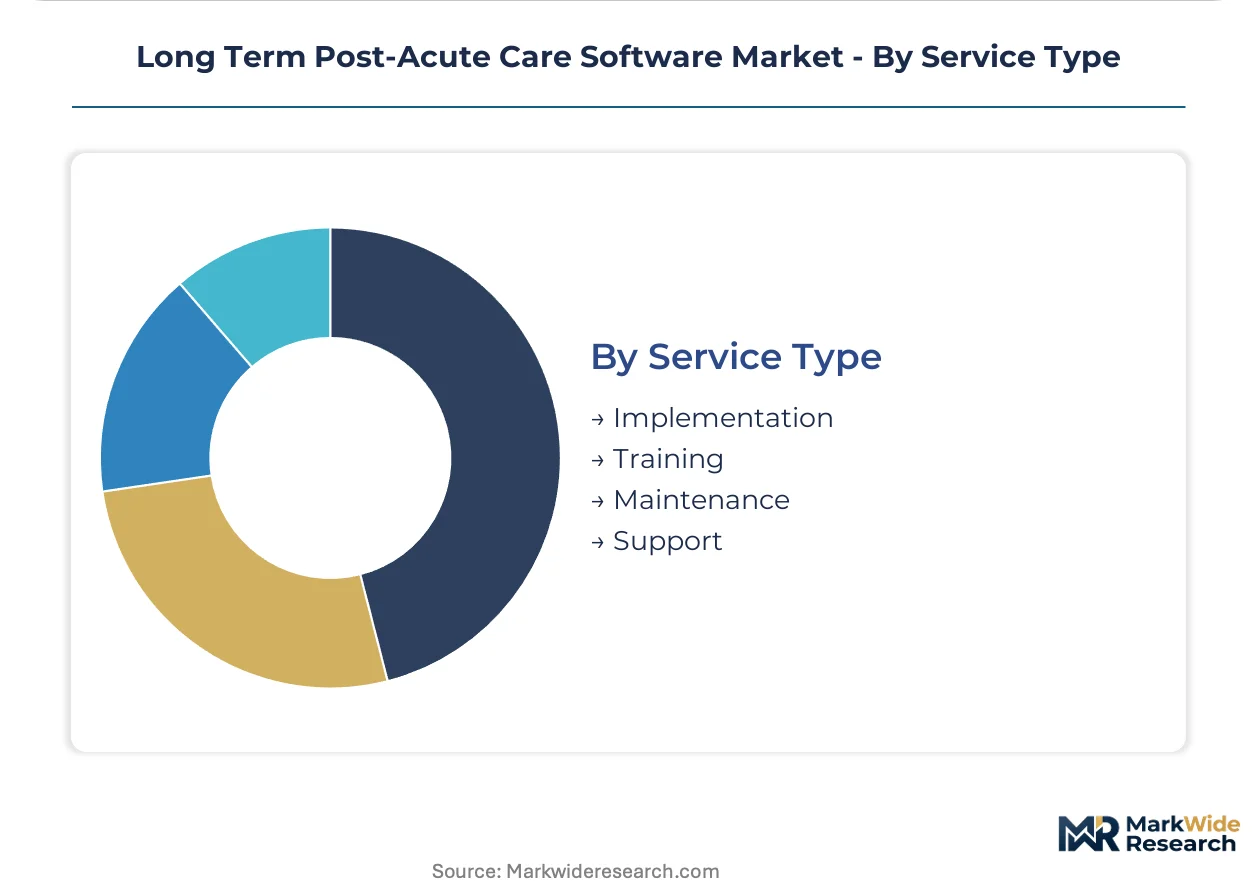
- Implementation:Data migration, workflow configuration, and legacy system decommissioning services. Skilled nursing chains in Pennsylvania and Michigan are demanding fixed-fee implementation contracts to cap transition risk.
- Training:Role-based certification programs for nursing staff, billing personnel, and administrators. High-turnover environments in Texas and Florida are prioritizing train-the-trainer models to reduce recurring vendor dependency.
- Maintenance:Scheduled updates, security patching, and regulatory compliance refresh cycles.
- Support:Tiered helpdesk access with escalation paths for critical system downtime.
Implementation services generate the highest upfront revenue, while Training contracts are extending their recurring revenue contribution fastest as staff churn persists industry-wide.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS reimbursement mandates and value-based payment reforms are concentrating software procurement in markets with the densest post-acute provider networks and strictest compliance burdens. Federal interoperability deadlines are forcing facility operators to consolidate vendor relationships ahead of civil monetary penalty enforcement.
United States
Hospital-at-home waiver expansions and PDPM reimbursement recalibration are driving demand for integrated EHR platforms across multi-site skilled nursing chains. HHS Office for Civil Rights HIPAA enforcement actions are elevating data governance requirements for SaaS vendors. Texas and Florida facility operators are replacing legacy assessment systems to avoid CMS Conditions of Participation penalties.
Germany
Digital Care Act (Digitale-Versorgung-Gesetz) reimbursement codes for telemedicine-enabled post-acute monitoring are expanding addressable software markets beyond traditional facility boundaries. BfArM medical device software classification guidance is extending validation timelines for clinical decision support modules. Bavarian hospital networks are piloting HL7 FHIR-connected discharge planning tools with regional nursing home associations.
United Kingdom
NHS England integrated care board procurement frameworks are consolidating software spend under standardized platform contracts for community-based rehabilitation services. MHRA Software as a Medical Device guidance is compelling algorithmic risk stratification tools through enhanced clinical validation pathways. Greater Manchester and West Midlands health systems are deploying shared care record infrastructure across acute-post-acute boundaries.
Japan
METI Society 5.0 aging-in-place initiatives are extending software demand into home-based medical management for post-stroke and post-fracture recovery. PMDA Software as a Medical Device notification requirements are elevating documentation burdens for predictive analytics vendors. Kanto region metropolitan hospitals are integrating long-term care insurance claim systems with acute discharge planning workflows.
Australia
Department of Health and Aged Care Star Ratings transparency mandates are forcing residential aged care providers toward quality metrics automation. TGA medical device software framework updates are capturing clinical decision support modules under regulatory scope. New South Wales and Victorian aged care chains are consolidating point solutions under unified vendor contracts to reduce audit preparation overhead.
Long Term Post-Acute Care Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where scale advantages in compliance certification create defensive moats. Consolidation pressure from private equity-backed facility chains favors vendors with multi-tenant SaaS architectures and automated regulatory update delivery. Two strategic archetypes dominate: cloud-native platform consolidators bundling clinical and financial workflows, and vertical specialists anchoring specific care settings through purpose-built assessment tools. Competitive moves concentrate on M&A-driven capability expansion and strategic partnerships with hospital EHR incumbents to secure discharge workflow integration.
Within the cloud-native consolidator tier, PointClickCare and WellSky occupy positions representing divergent specialization strategies—one anchoring skilled nursing facility penetration, the other exemplifying home health workflow depth. MatrixCare sits within the assisted living-focused specialist archetype, demonstrating how revenue cycle management differentiation can sustain competitive position against broader-platform rivals.
| Leading Market Players |
|---|
| PointClickCare |
| MatrixCare |
| Netsmart Technologies |
| Epic Systems Corporation |
| Oracle Health |
| Allscripts Healthcare Solutions |
| McKesson Corporation |
| Veradigm |
| WellSky |
| Others |
Supply & Pricing Matrix
Single-source dependency on AWS and Azure healthcare-compliant hosting determines both pricing tier spreads and supply chain shape in post-acute care software, as vendor concentration in cloud infrastructure elevates switching costs for rural operators while compressing margins across SaaS tiers.
Pricing Analysis
Certification level (ONC Health IT Certification/FDA-grade) creates the primary spread between premium and standard SaaS tiers. Subscription-based financing dominates, with price differentiation driven by interoperability certification depth and after-sales implementation support. Cost compression in the standard tier is intensifying because private equity-backed facility chains demand opex-aligned contracts. Independent skilled nursing operators exhibit highest price sensitivity, while multi-site chains prioritize compliance bundling over unit cost.
Supply Chain Analysis
Extended payment terms from cloud hyperscalers to SaaS vendors shape working capital structures across the vendor base. Software development concentrates in the United States, India, and Ireland. Raw material dependencies include semiconductor components for edge computing devices, encryption modules for HIPAA compliance, and API gateway infrastructure. Single-source vulnerability in AWS GovCloud and Azure Government regions exposes rural post-acute operators to service continuity risk. Distribution runs through direct enterprise sales teams and value-added resellers serving regional facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors face substitution pressure from hospital EHR incumbents extending into post-acute workflows, requiring defensive capability investments to preserve installed-base relationships.
For Market Incumbents: Pre-empt hospital EHR displacement by embedding predictive analytics modules that reduce 30-day readmission penalties for skilled nursing operators. Fortify FHIR R4 certification depth to maintain technical moats against Epic and Oracle Health discharge workflow extensions. Vertical integration into remote patient monitoring device data streams anchors platform stickiness against point-solution fragmentation.
For New Entrants and Emerging Players: Behavioral health integration modules within skilled nursing facilities represent the most penetrable entry point, as substance use disorder coordination remains underserved by incumbent platforms. Rural Health Clinic designation expansions in underserved counties offer addressable markets previously excluded from enterprise sales coverage. A train-the-trainer implementation model reduces customer acquisition costs in high-staff-turnover environments.
For Investors and Strategic Acquirers: CMS interoperability mandate enforcement reshapes the acquisition landscape by elevating compliance certification to primary valuation driver. Long-term viability centers on vendors with automated regulatory update delivery and multi-tenant SaaS architectures serving private equity-consolidated facility chains. Watch FDA Software as a Medical Device guidance expansion as the signal indicating which predictive analytics capabilities will face enhanced clinical validation burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | FHIR R4 API embedding reduces hospital discharge friction for multi-site skilled nursing chains. |
| Acquisition of Specialist Firm | Behavioral health workflow modules fill white space in substance use disorder care coordination. |
| Strategic Partnership | Hospital EHR incumbent alliances secure preferred discharge planning workflow positioning. |
| Product Launch | Voice-enabled clinical documentation interfaces address nursing staff turnover pain points. |
| Geographic Expansion | Rural Health Clinic designation targeting opens previously excluded county markets. |
Research Methodology
Desk research of FDA 510(k) filings, CMS Medicare cost reports, and hospital procurement databases preceded structured interviews with skilled nursing facility CIOs, home health agency operations directors, and EHR integration specialists. Primary fieldwork with post-acute care software vendors and private equity-backed facility chain executives was cross-validated against secondary sources including HHS Office for Civil Rights enforcement actions and ONC Health IT Certification records. Bottom-up deployment volume estimates were triangulated with top-down reimbursement flow analysis.
Assumptions held fixed across the modeling period include CMS Conditions of Participation interoperability deadlines, PDPM reimbursement methodology stability, and cloud infrastructure cost trajectories. Segmentation dimensions modeled encompass deployment model, facility type, integration complexity, and regional adoption pattern. CAGRs were derived from fitted growth curves anchored to documented procurement volumes and reimbursement policy implementation timelines. Forecast inputs incorporated HL7 FHIR adoption rates and private equity facility consolidation velocity.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting private equity leverage ratios or Medicaid funding allocations would shift the trajectory. Technological disruption from generative AI documentation tools or regulatory deviation in HIPAA enforcement intensity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Heart Failure Software Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Global Behavioral/Mental Health Software Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Pregnancy Tracking and Postpartum Care Apps Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Global Health Kiosk Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
US Real World Evidence Solutions Market
Digital Health Solutions
Global Metaverse in Healthcare Market