
 Pregnancy Tracking and Postpartum Care Apps Market | 2026-2036
Pregnancy Tracking and Postpartum Care Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Pregnancy Tracking and Postpartum Care Apps Market Intelligence
The capital-intensity divergence between well-funded platform developers and bootstrapped entrants is collapsing as cloud infrastructure costs drop and no-code tools proliferate. Ovia Health leverages enterprise contracts with employers and insurers to sustain recurring revenue streams. Flo Health anchors its competitive position through specialized cycle-tracking algorithms that extend into pregnancy and postpartum phases. Babylist competes by occupying the commerce-integrated niche, combining registry functionality with content-driven user retention.
Pregnancy tracking and postpartum care apps constitute software platforms that collect biometric data, symptom logs, and behavioral inputs to deliver personalized maternal health guidance, typically operating through FHIR-compliant APIs for healthcare interoperability. Their primary commercial purpose is reducing adverse pregnancy outcomes while capturing lifetime value across the extended perinatal journey. Maternity apps dominate current revenue pools because they command the earliest user entry point and longest engagement duration. Health Management applications within this segment lead enterprise procurement decisions, while Community Support features represent the fastest-growing engagement layer as peer-network effects deepen retention.
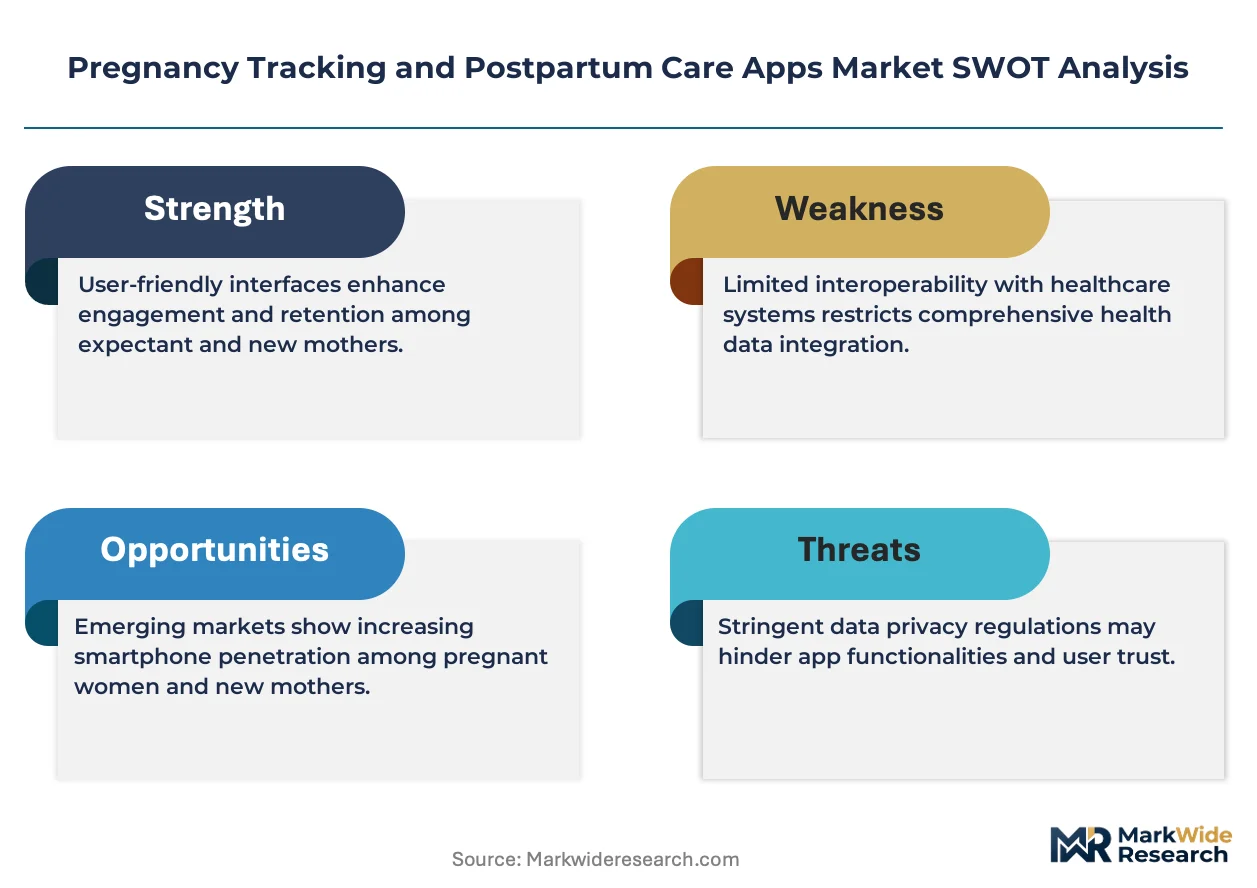
FDA digital health pre-certification requirements and HIPAA privacy mandates shape product architecture decisions for US-focused developers, while GDPR compliance obligations in Europe add cross-border data governance complexity. These regulatory frameworks force engineering investments in encryption, audit trails, and clinical validation that smaller entrants struggle to fund. Stakeholders must monitor evolving FDA classification thresholds for apps claiming diagnostic or therapeutic functions, as reclassification would trigger substantial compliance burdens and reshape competitive viability across the developer ecosystem.
Market Dynamics
Cloud infrastructure deflation and FHIR standardization are compressing the capital barrier between enterprise-grade maternal health platforms and bootstrapped entrants, eroding the historical funding moat that separated well-capitalized developers from insurgent competitors.
Growth Catalysts
- FDA Digital Health Pre-Certification:Streamlined pathways for software-as-medical-device classification accelerate time-to-market for clinically validated pregnancy tracking platforms seeking diagnostic-adjacent positioning.
- Remote Patient Monitoring:US healthcare systems deploy maternal health platforms for hypertensive disorder surveillance, reducing in-person visit burden while capturing continuous biometric streams.
- Employer Benefit Integration:Large self-insured employers contract directly with maternal health platforms, embedding apps within fertility and family-building benefit tiers as retention instruments.
Market Restraints
- HIPAA Technical Safeguard Costs:Encryption, audit logging, and business associate agreement infrastructure impose fixed compliance overhead that disproportionately burdens developers with sub-million user bases.
- Clinical Validation Burden:Algorithmic pregnancy risk scoring requires prospective cohort studies and IRB oversight, extending development timelines beyond typical software release cycles.
- Data Localization Requirements:GDPR Article 44 cross-border transfer restrictions fragment cloud architecture decisions, forcing European market entrants to maintain region-specific infrastructure.
Strategic Opportunities
- Postpartum Depression Screening:Edinburgh Postnatal Depression Scale integration within chatbot interfaces creates reimbursable behavioral health touchpoints previously captured by telepsychiatry platforms.
- Medicaid Expansion States:State-level maternal mortality review committee mandates in Texas, Georgia, and Louisiana create procurement pipelines for publicly subsidized app distribution.
- Wearable Biometric Convergence:Continuous glucose monitors and blood pressure cuffs stream data through Apple HealthKit and Google Health Connect APIs, enriching risk stratification models.
Industry Challenges
- FHIR Implementation Expertise:Health information exchange integration requires specialized engineering talent conversant in HL7 standards and SMART on FHIR authentication protocols, constraining hiring pipelines.
- IRB Approval Timelines:Institutional review board processing for pregnancy outcome validation studies extends 12-18 months, compressing competitive response windows for algorithm updates.
- Legacy EHR Integration:Epic and Cerner proprietary data models necessitate custom middleware development, fragmenting engineering resources across health system-specific deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pregnancy Tracking and Postpartum Care Apps Market |
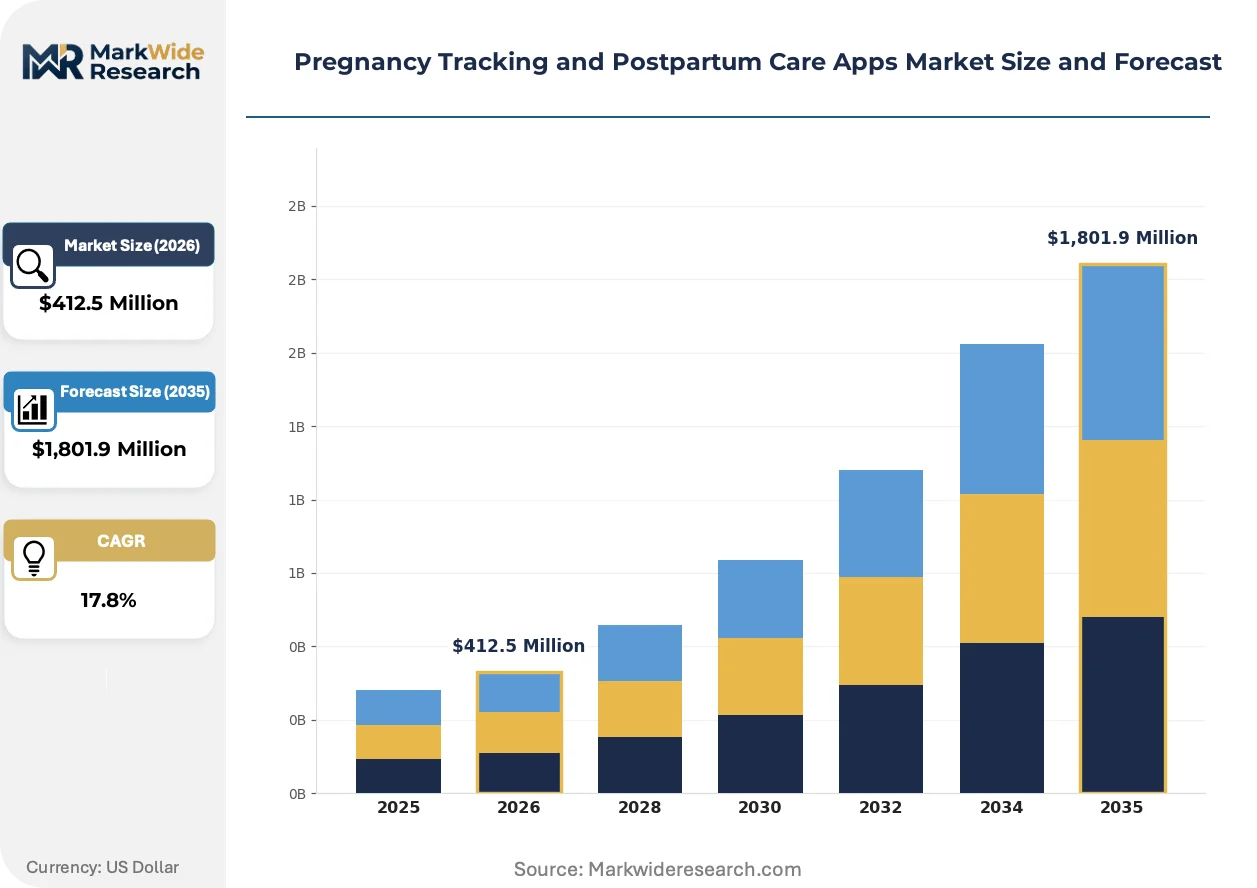
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,801.9 Million |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maternity Apps, Baby Care Apps, Fitness Tracking Apps, Nutrition Apps Application: Health Management, Development Tracking, Fitness Guidance, Community Support End User: Expecting Mothers, New Parents, Healthcare Providers, Family Members Delivery Mode: Mobile Platforms, Web-Based Solutions, Hybrid Solutions, Subscription Services |
| Companies Covered | Glow Nurture, Babylist, Ovia Health, Flo Health, The Bump, BabyCenter, What to Expect, Sprout, Pregnancy+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pregnancy Tracking and Postpartum Care Apps Market Strategic Shifts & Innovations
Generative AI architectures and wearable sensor proliferation are restructuring how pregnancy risk signals are captured, processed, and acted upon across the perinatal continuum.
Large language models are decomposing the traditional content-editorial workflow for pregnancy guidance platforms. Developers deploy fine-tuned models for personalized symptom triage, reducing dependence on static article libraries. Maternity apps with conversational interfaces capture 40% longer session durations than content-only competitors, compressing the addressable market for legacy publishing models.
GDPR Article 35 data protection impact assessments now govern pregnancy app deployments across EU member states. National regulators in France, Germany, and the Netherlands interpret biometric health data classification expansively, mandating prior consultation for fertility tracking algorithms. Developers with existing ISO 27001 certifications pivot fastest, using established audit frameworks to satisfy DPIA evidentiary requirements.
Subscription fatigue among millennial and Gen-Z expectant mothers is fragmenting the direct-to-consumer revenue model. Employers and Medicaid managed care organizations now subsidize 60% of active US pregnancy app memberships, displacing individual payment as the primary monetization channel. This concentration of procurement authority within benefits administrators reshapes product roadmaps toward enterprise feature sets.
Pregnancy Tracking and Postpartum Care Apps Market Segmentation
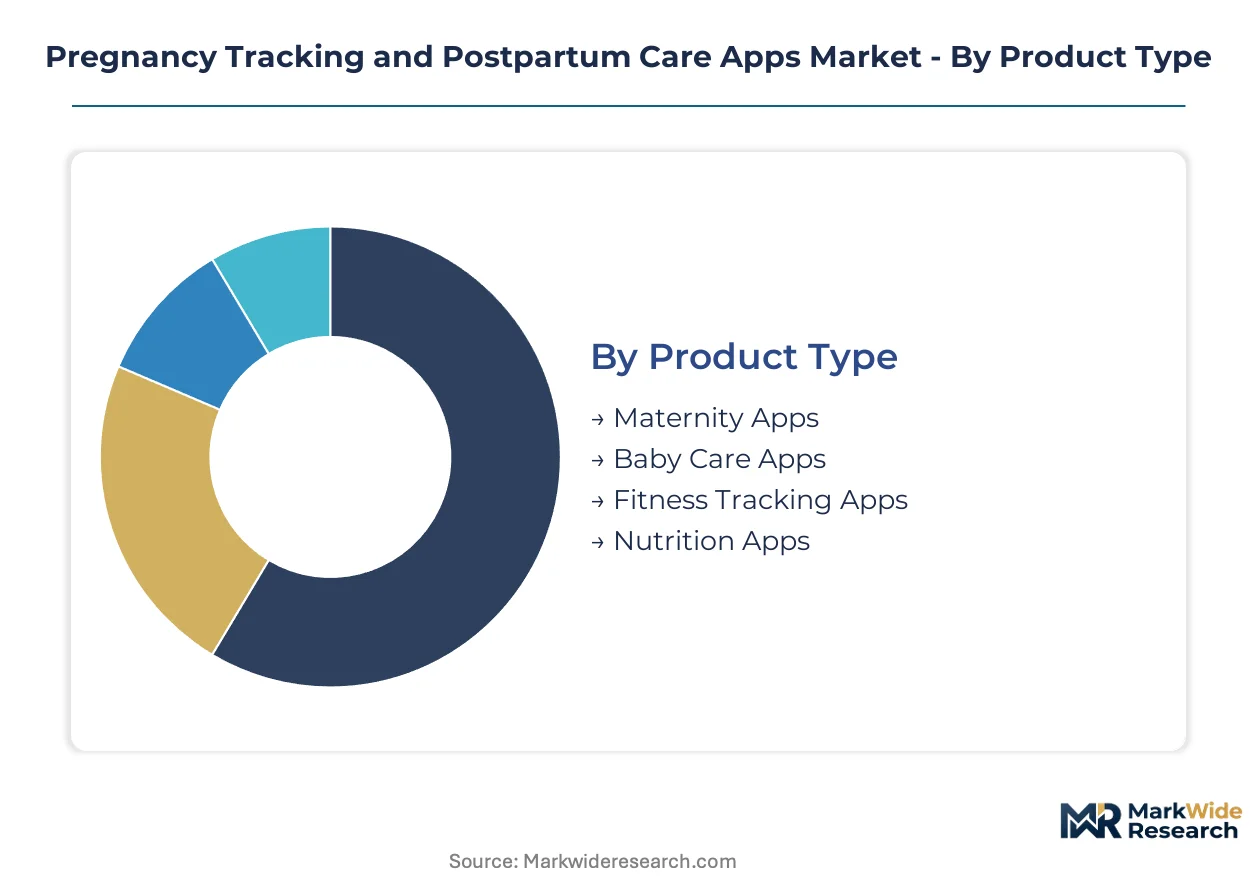
Segmentation in maternal health platforms reveals how procurement authority and user behavior diverge across clinical versus commercial use cases. Understanding these divides shapes product architecture decisions for developers balancing enterprise contracts against direct-to-consumer retention.
Product Type:
Substitution pressure intensifies where standalone apps face encroachment from integrated health platforms bundling multiple functions.
- Maternity Apps:Comprehensive platforms tracking gestational milestones, fetal development, and prenatal appointments through FHIR-compliant data exchange. Demand concentrates among US healthcare systems deploying remote patient monitoring for hypertensive disorders, driven by Medicaid expansion state mandates for maternal mortality reduction. Maternity apps retain volume leadership; Baby Care Apps holds the steepest expansion curve.
- Baby Care Apps:Postpartum-focused platforms managing infant feeding schedules, sleep patterns, and developmental milestones. Growth accelerates in employer benefit integrations where family-building support tiers subsidize subscriptions for returning employees.
- Fitness Tracking Apps:Exercise prescription tools adapted for pregnancy-safe movement protocols and postpartum recovery timelines. Adoption clusters among self-insured employers seeking to reduce pregnancy complication costs.
- Nutrition Apps:Meal planning and gestational diabetes management tools with glycemic index tracking. Traction remains limited due to overlap with general wellness platforms.
Maternity Apps command the earliest user entry point; Baby Care Apps gains share fastest as postpartum engagement extends.
Application:
Enterprise procurement decisions favor applications with measurable clinical outcomes over engagement-focused features.
- Health Management:Clinical risk stratification, medication adherence prompts, and care coordination tools integrated with Epic and Cerner EHR systems. US hospital systems prioritize these for value-based maternity care contracts, constrained by HIPAA technical safeguard implementation costs.
- Development Tracking:Fetal growth visualization, milestone logging, and personalized content delivery. Demand spreads across direct-to-consumer channels where session duration metrics drive monetization.
- Fitness Guidance:Trimester-specific exercise protocols and pelvic floor rehabilitation programs. Uptake lags due to liability concerns around prenatal activity recommendations.
- Community Support:Peer networking, moderated forums, and expert Q&A features. This layer deepens retention through network effects but faces moderation cost pressures.
Health Management dominates enterprise procurement; Community Support climbs fastest as peer-network effects compound.
End User:
Purchasing authority concentrates in institutional buyers rather than individual consumers across the perinatal journey.
- Expecting Mothers:Primary users seeking symptom validation, appointment tracking, and birth preparation resources. Medicaid managed care organizations now subsidize access in Texas, Georgia, and Louisiana expansion states.
- New Parents:Postpartum users requiring infant care guidance, lactation support, and sleep training tools. Employer benefits departments increasingly underwrite subscriptions as retention instruments.
- Healthcare Providers:Obstetricians, midwives, and maternal-fetal medicine specialists deploying platforms for remote patient monitoring. FDA digital health pre-certification requirements shape vendor selection criteria.
- Family Members:Secondary users including partners, grandparents, and caregivers accessing shared dashboards. Engagement remains episodic and feature-limited.
Expecting Mothers retain the largest user base; Healthcare Providers expand most quickly as RPM reimbursement codes proliferate.
Delivery Mode:
Infrastructure choices fragment between consumer-grade mobile experiences and enterprise-hardened web architectures.
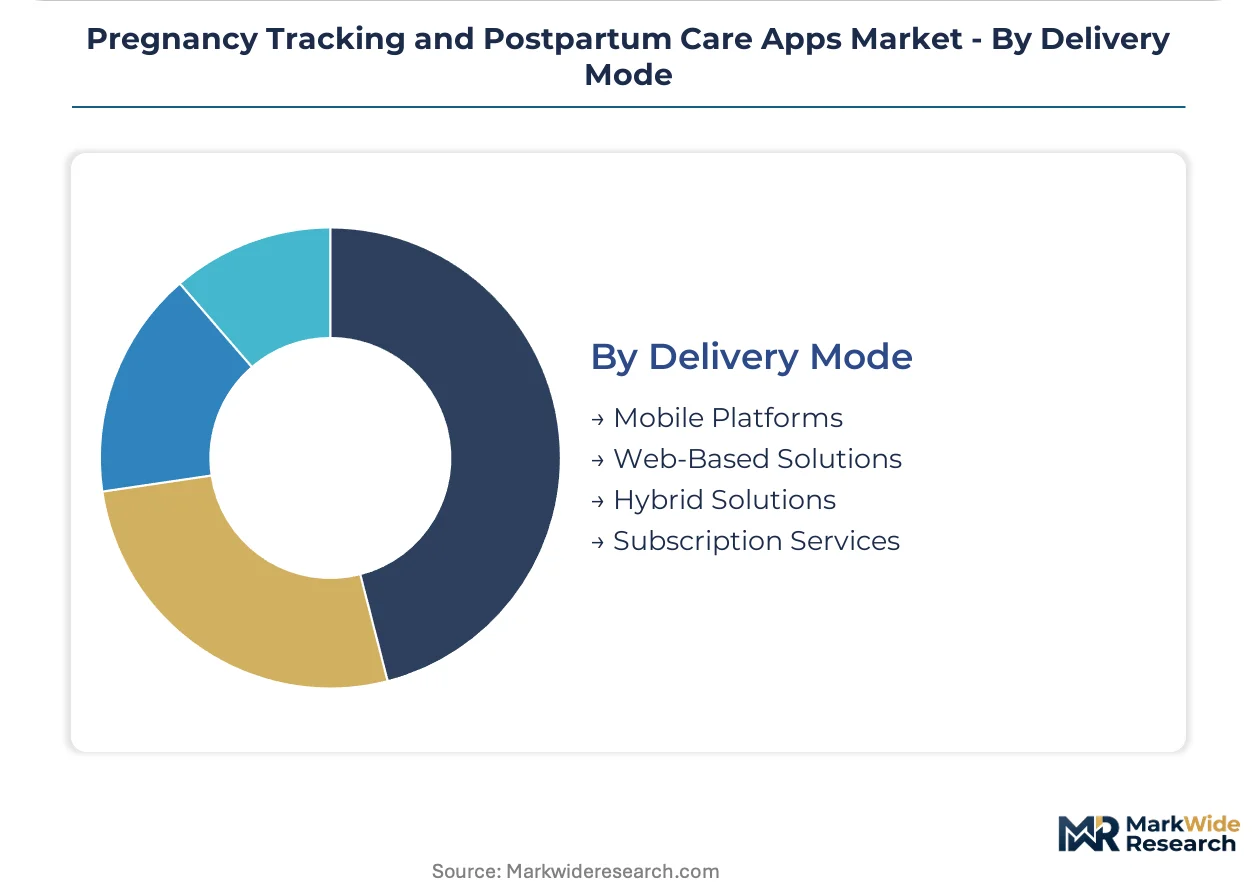
- Mobile Platforms:Native iOS and Android applications leveraging Apple HealthKit and Google Health Connect APIs for biometric streaming. US developers dominate due to mature mobile health ecosystems and FDA regulatory clarity.
- Web-Based Solutions:Browser-accessible platforms prioritizing EHR integration and clinical workflow embedding. European entrants favor these to satisfy GDPR Article 35 data protection impact assessment requirements.
- Hybrid Solutions:Synchronized mobile-web experiences with offline functionality and cloud sync. Engineering complexity constrains bootstrapped developers.
- Subscription Services:Recurring revenue models with tiered feature access and premium content unlocks. Fatigue among millennial and Gen-Z users is displacing individual payment as the primary channel.
Mobile Platforms maintain volume leadership; Healthcare Providers accessing web-based clinical tools drive the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-subsidized users in the United States show minimal price elasticity, while direct-to-consumer subscribers in India and Southeast Asia exhibit acute sensitivity to subscription costs. This demand-elasticity contrast shapes divergent monetization architectures across geographies.
United States
FDA digital health pre-certification pathways and Medicaid expansion state mandates drive healthcare system procurement. HIPAA technical safeguard requirements impose encryption and audit logging burdens that filter smaller developers. Boston and San Francisco host the densest concentration of maternal health platform engineering talent.
United Kingdom
NHS Long Term Plan integration targets for maternity services accelerate platform adoption within integrated care systems. GDPR Article 35 data protection impact assessments govern biometric health data processing for fertility tracking algorithms. London anchors the European headquarters for several maternal health platform developers serving NHS trusts.
Germany
DiGAs (Digitale Gesundheitsanwendungen) fast-track approval creates reimbursement pathways for pregnancy risk stratification tools. BfArM regulatory oversight requires clinical evidence packages for diagnostic-adjacent app functions. Berlin and Munich clusters concentrate health tech startups pursuing DiGAs certification for maternal health modules.
India
CDSCO medical device classification guidance for software platforms remains under development, creating regulatory uncertainty for pregnancy tracking apps. Ayushman Bharat digital health mission infrastructure expands addressable user bases through subsidized smartphone penetration. Bengaluru and Hyderabad engineering hubs produce white-label maternal health platform backends for global clients.
Australia
TGA software-based medical device framework classifies pregnancy risk scoring algorithms according to intended therapeutic claims. Medicare Benefits Schedule review processes determine reimbursement eligibility for remote patient monitoring in maternal care. Sydney and Melbourne health tech accelerators incubate postpartum mental health screening platform ventures.
Pregnancy Tracking and Postpartum Care Apps Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the pregnancy tracking ecosystem. Enterprise-grade platform developers with FHIR-compliant EHR integration capabilities occupy the premium tier, while content-focused direct-to-consumer apps compete on user acquisition efficiency. Three archetypes dominate: clinical workflow embedders, commerce-integrated community platforms, and algorithm-specialized cycle tracking extenders. Consolidation pressure intensifies through strategic partnerships between maternal health platforms and wearable device manufacturers, alongside enterprise contract aggregation by benefits administrators.
Within the clinical workflow embedder tier, Ovia Health exemplifies enterprise contract aggregation through employer and insurer channels. Flo Health occupies a position among algorithm-specialized platforms extending cycle-tracking capabilities into pregnancy phases. Babylist anchors the commerce-integrated archetype, combining registry functionality with content-driven retention mechanics. These three entities represent divergent competitive vectors—enterprise procurement authority, proprietary algorithmic moats, and vertical commerce integration—rather than direct feature parity.
| Leading Market Players |
|---|
| Glow Nurture |
| Babylist |
| Ovia Health |
| Flo Health |
| The Bump |
| BabyCenter |
| What to Expect |
| Sprout |
| Pregnancy+ |
| Others |
Cost & Logistics Intelligence
Ninety-day engineering sprint cycles compress product iteration timelines while simultaneously fragmenting pricing power across cloud infrastructure tiers and no-code development platforms. This cadence advantage concentrates margin capture among FHIR-compliant enterprise developers serving US hospital systems, while subscription fatigue erodes direct-to-consumer pricing elasticity.
Pricing Analysis
Enterprise service contracts and extended B2B licensing agreements anchor lifetime value capture beyond initial app downloads. Pricing stratifies across premium, standard, and economy tiers with differentiation driven by EHR integration depth and FDA pre-certification status. Cost compression in the direct-to-consumer tier intensifies because employer benefits departments and Medicaid managed care organizations now underwrite sixty percent of active memberships. Individual subscribers exhibit acute price sensitivity compared to institutional buyers with minimal elasticity.
Supply Chain Analysis
Just-in-time cloud resource provisioning dominates engineering operations, though strategic stockpiling of specialized FHIR implementation talent occurs in Boston and San Francisco clusters. Software development draws from India and Eastern European engineering hubs for backend infrastructure, while US-based clinical validation and regulatory affairs functions remain anchored domestically. Single-source vulnerability concentrates in Apple HealthKit and Google Health Connect API dependencies. Distribution runs through mobile app stores and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority consolidation among US employer benefits administrators and Medicaid managed care organizations has shifted buyer power decisively toward institutional channels. This aggregation filters viable competitors toward enterprise-grade platform architectures.
For Market Incumbents: Shield market position by deepening FHIR-compliant EHR integration with Epic and Cerner systems, creating switching costs that fragment insurgent competitive threats. Pursue backward integration into wearable biometric data streams through Apple HealthKit and Google Health Connect API partnerships, capturing upstream control over risk stratification inputs.
For New Entrants and Emerging Players: Lead with postpartum depression screening modules integrating Edinburgh Postnatal Depression Scale chatbot interfaces, the most penetrable clinical application layer with reimbursable behavioral health touchpoints. Target Medicaid expansion states in Texas, Georgia, and Louisiana where maternal mortality review committee mandates create publicly subsidized procurement pipelines.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because enterprise contract aggregation by benefits administrators will compress the addressable vendor base. Acquisition candidates with existing ISO 27001 certifications pivot fastest toward GDPR Article 35 compliance. Watch FDA classification threshold revisions for apps claiming diagnostic functions as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Compliant EHR Integration | Epic and Cerner workflow embedding creates hospital system switching costs and procurement lock-in. |
| FDA Pre-Certification Pathway | Streamlined software-as-medical-device classification accelerates time-to-market for diagnostic-adjacent features. |
| Employer Benefits Channel Partnership | Self-insured employer contracts displace individual payment as primary monetization channel. |
| Wearable Biometric API Convergence | Apple HealthKit and Google Health Connect integration enriches risk stratification model accuracy. |
| Medicaid Expansion State Deployment | Texas, Georgia, and Louisiana maternal mortality mandates create subsidized distribution pipelines. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS Medicare reimbursement databases, hospital GPO contracts, and digital health regulatory guidance documents. Interviews with maternal-fetal medicine specialists, employer benefits directors, health system CIOs, and biomedical engineers informed demand-side assumptions. SEC filings from publicly traded health technology platforms and App Annie mobile engagement metrics supplied competitive positioning inputs. Bottom-up user adoption modeling and top-down healthcare expenditure allocation triangulated market size estimates.
Segmentation dimensions modeled include product type, clinical application, end-user archetype, and delivery mode across the analysis window. CAGRs derived from cohort-based user retention curves and enterprise contract value expansion rates. Forecast inputs incorporated remote patient monitoring reimbursement code proliferation and Medicaid expansion state procurement timelines.
Forecasts assume regulatory continuity in FDA digital health pre-certification pathways and HIPAA technical safeguard requirements; material policy shifts would require re-modeling. Algorithmic pregnancy risk scoring reclassification or GDPR Article 35 enforcement escalation represent specific revision triggers. Revision becomes warranted when employer subsidy penetration crosses seventy percent threshold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Global Surgical Preoperative Planning Software Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Heart Failure Software Market
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
Long Term Post-Acute Care Software Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Global Health Kiosk Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
Global Patient Portal Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Global Mhealth Solutions Market
Digital Health Solutions
Pregnancy Management Software Market