
 Aged Care Software Market | 2026-2036
Aged Care Software Market Size, Share, and Industry Trends Forecast 2026-2036
Aged Care Software Market Insights
ONC Cures Act Final Rule certification is unwinding competitive access for vendors lacking interoperability credentials. PointClickCare leverages its cloud-native architecture to sustain dominance across North American skilled nursing facilities. Netsmart Technologies anchors its position through specialized behavioral health and post-acute integration layers.
Aged care software denotes specialized health information technology designed for elder care settings, incorporating real-time medication tracking, care plan orchestration, and regulatory reporting modules that interface with federal reimbursement systems. Its primary commercial purpose centers on operational compliance, workforce coordination, and quality outcome documentation for reimbursed care delivery. Cloud-based deployment leads structural growth due to lower capital barriers for mid-sized nursing homes and assisted living facilities, while on-premise installations retain margin concentration among large multi-site operators with dedicated IT infrastructure. Electronic Health Records technology commands the deepest integration requirements, though AI Solutions represent the fastest-expanding investment category as predictive analytics reshape fall prevention and readmission risk protocols.
The ONC Cures Act Final Rule, HIPAA, and state-level Medicaid Management Information Systems collectively shape product roadmaps and procurement eligibility across the United States. Australia's Aged Care Quality and Safety Commission and the United Kingdom's Care Quality Commission enforce comparable digital accountability standards that filter vendor participation. Stakeholders must weigh interoperability investment against the pace of regulatory harmonization as procurement criteria tighten across jurisdictions.
Market Dynamics
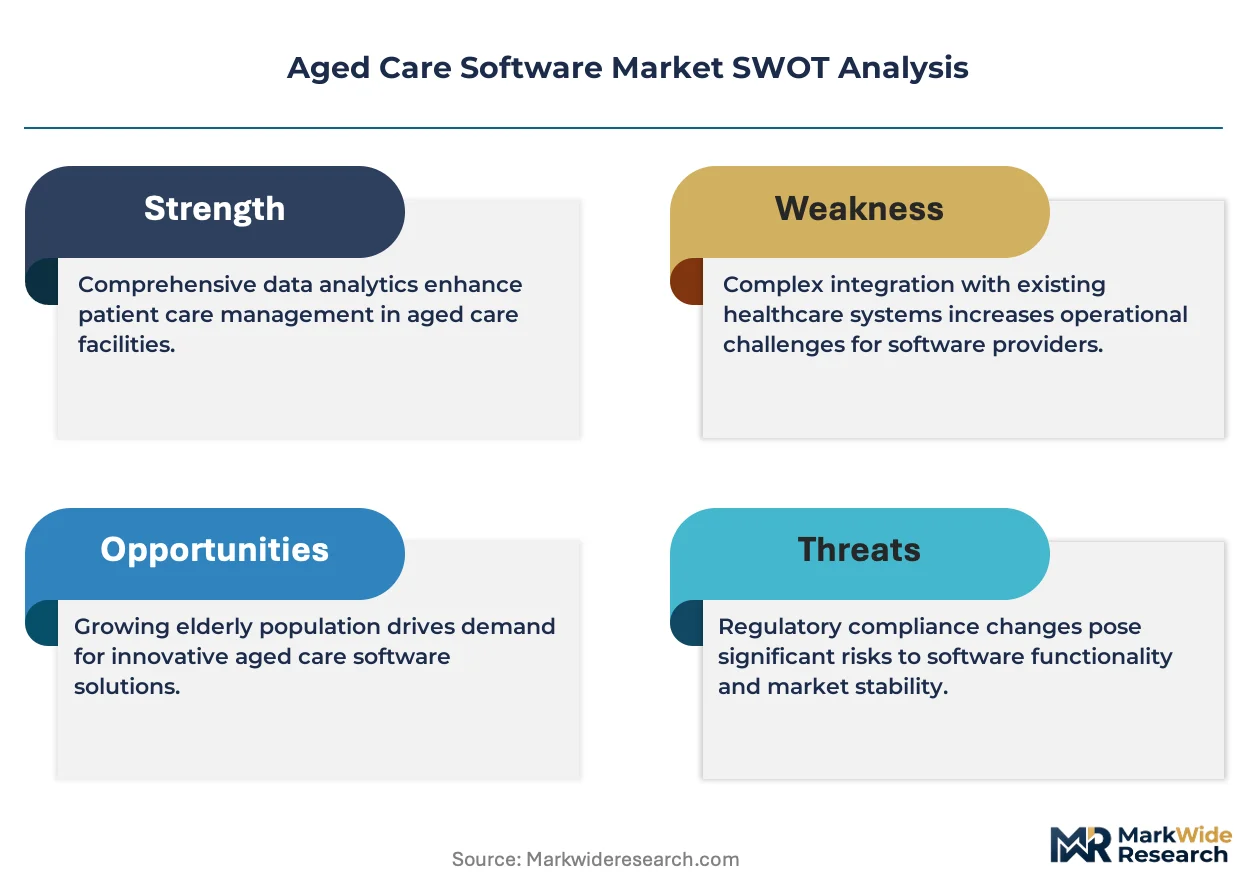
Interoperability mandates from the ONC Cures Act Final Rule are compressing vendor access and forcing consolidation around certified platforms that can exchange data across acute and post-acute settings.
Growth Catalysts
- Cloud-native architecture migration:Mid-sized nursing homes and assisted living facilities are abandoning capital-intensive on-premise systems for subscription-based deployment models that lower entry barriers and accelerate feature parity with large operators.
- Australia's Aged Care Quality and Safety Commission enforcement:Strict digital compliance timelines are compelling aged care providers to replace legacy paper workflows with integrated electronic health record platforms that automate regulatory reporting.
- HIPAA-aligned data exchange requirements:Post-acute care networks in the United States are procuring only software vendors that demonstrate bidirectional data flow with hospital systems, filtering out non-compliant suppliers.
Market Restraints
- Specialized workforce scarcity:Implementation of predictive analytics modules requires clinical informaticists with geriatric care expertise, a talent pool concentrated in urban hospital systems rather than rural nursing facilities.
- Legacy system entrenchment:Large multi-site operators with dedicated IT infrastructure face sunk-cost barriers when evaluating cloud migration, delaying refresh cycles and fragmenting vendor addressable market.
- Medicaid reimbursement variability:State-level Medicaid Management Information Systems impose divergent documentation requirements that force software vendors to maintain jurisdiction-specific code bases, elevating development overhead.
Strategic Opportunities
- Behavioral health-post-acute convergence:Integration layers that connect dementia care protocols with psychiatric medication management represent an underserved white space as comorbidity rates rise among elderly populations.
- AI-driven fall prevention analytics:Machine learning models that predict patient mobility risk before incidents occur are attracting investment from liability-conscious facility operators seeking to reduce workers compensation exposure.
- United Kingdom Care Quality Commission alignment:Vendors that pre-certify against CQC digital accountability standards can accelerate procurement cycles with English and Welsh aged care providers facing inspection modernization.
Industry Challenges
- Interoperability certification timeline compression:Vendors must complete ONC Cures Act testing and validation within narrowing windows to maintain eligibility for federal reimbursement-linked procurement.
- Multi-generational staff technology adoption:Care facilities employ nursing aides with varying digital literacy levels, complicating training standardization and threatening user engagement metrics that determine contract renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aged Care Software Market |
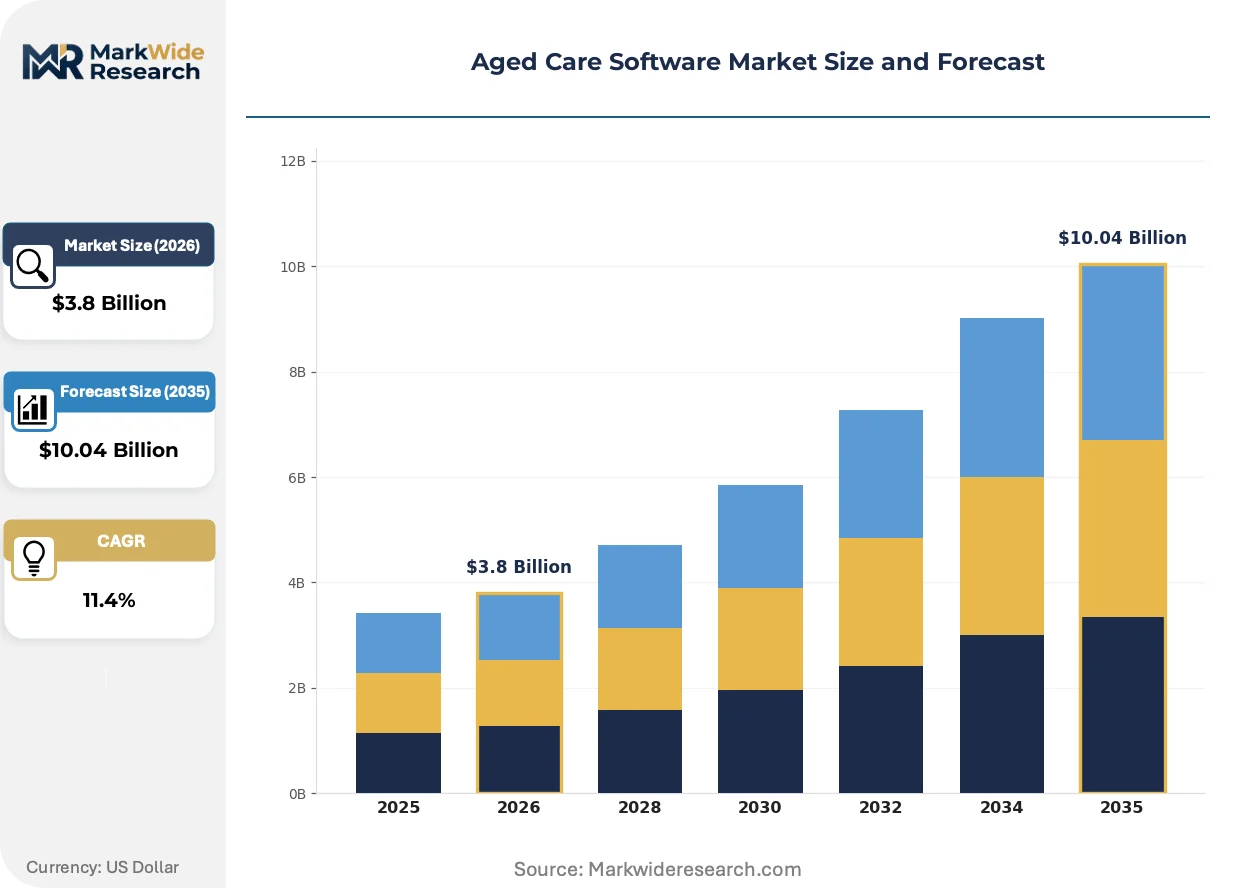
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Care Management, Billing Software, Medication Management, Reporting Tools End User: Nursing Homes, Assisted Living Facilities, Home Care Providers, Rehabilitation Centers Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Technology: AI Solutions, Telehealth, IoT Devices, Electronic Health Records |
| Companies Covered | PointClickCare, MatrixCare (ResMed), Netsmart Technologies, Oracle Cerner, Epic Systems Corporation, WellSky, Veradigm, Yardi Systems, AlayaCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aged Care Software Market Trends and Innovations
Artificial intelligence capabilities are penetrating medication management and predictive risk stratification, while regulatory pressure accelerates platform consolidation and data exchange standardization.
Predictive analytics engines are bifurcating the competitive landscape between vendors with native AI development capacity and those dependent on third-party algorithm licensing. Skilled nursing facilities with above-average readmission rates are adopting these tools fastest. The technology is bifurcating vendor tiers by compressing margins for rule-based systems while rewarding platforms with proprietary training data from longitudinal patient records.
The ONC Cures Act Final Rule mandates standardized application programming interfaces for patient data access, compelling software vendors to expose core functionality through interoperable endpoints. Post-acute care networks are disqualifying vendors lacking certification from procurement shortlists. Home care providers expanding into skilled nursing are most affected, as their legacy platforms require fundamental re-architecture to meet attestation requirements.
Subscription-based procurement is displacing perpetual license arrangements across mid-sized assisted living chains and independent nursing homes. Channel partners specializing in elder care IT consulting are capturing implementation revenue previously retained by software vendors. This pattern is most visible in Australia, where the Aged Care Quality and Safety Commission's digital compliance deadlines are compressing decision cycles and favoring consultative sales models over direct enterprise contracts.
Aged Care Software Market Segmentation
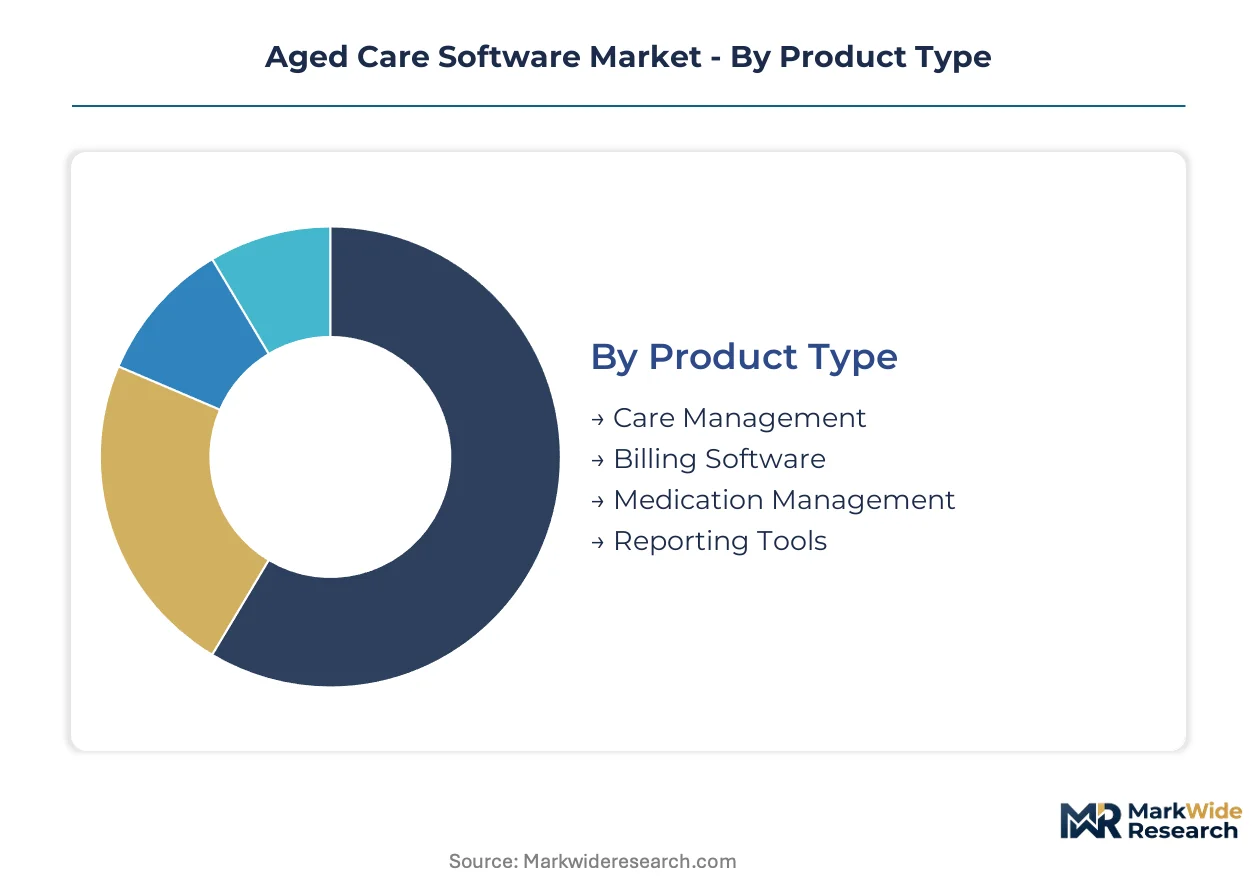
Segmentation in aged care software reveals where procurement budgets concentrate and which capability bundles command premium pricing. Providers select platforms based on reimbursement complexity, regulatory exposure, and workforce digital literacy rather than feature checklists alone.
Product Type:
Margin pools concentrate in modules that automate compliance documentation and interface directly with federal reimbursement systems.
- Care Management:Orchestrates care plans, shift scheduling, and family communication portals through unified dashboards. Nursing homes in Australia prioritize these platforms as the Aged Care Quality and Safety Commission tightens digital accountability timelines for residential facilities.
- Medication Management:Integrates pharmacy dispensing systems with bedside barcode verification and allergy cross-checking. Home care providers expanding into skilled nursing procurement demand these modules to reduce liability exposure from polypharmacy errors in elderly populations.
- Billing Software:Automates Medicaid and Medicare claims submission with jurisdiction-specific code libraries.
- Reporting Tools:Generates regulatory submission packages for ONC Cures Act attestation and state survey readiness.
Care Management holds installed capacity. Medication Management is rotating up the share rankings.
End User:
Customer archetypes diverge sharply in IT infrastructure maturity and procurement decision speed.
- Nursing Homes:Operate under the highest regulatory scrutiny with mandatory interoperability certification for federal reimbursement eligibility. Skilled nursing facilities in the United States are replacing legacy systems ahead of ONC Cures Act deadlines, compressing vendor sales cycles.
- Home Care Providers:Deliver services across dispersed patient locations requiring mobile-first platforms with offline synchronization. Australian providers face Aged Care Quality and Safety Commission mandates to digitize care documentation previously recorded on paper visit logs.
- Assisted Living Facilities:Balance hospitality operations with clinical oversight, favoring lighter EHR footprints.
- Rehabilitation Centers:Prioritize therapy documentation modules that capture functional improvement metrics for insurance authorization.
Nursing Homes anchor procurement volume. Home Care Providers are gaining share fastest as aging-in-place preferences reshape service delivery models.
Deployment:
Capital availability and IT staffing levels determine deployment model selection across facility tiers.
- Cloud-Based:Delivers subscription-priced access to enterprise-grade functionality without server infrastructure. Mid-sized assisted living chains in the United States are abandoning capital-intensive on-premise systems as HIPAA-aligned data exchange requirements favor vendors with certified interoperability architectures.
- On-Premise:Retains data sovereignty and customization depth for large multi-site operators with dedicated IT infrastructure. These installations persist where state Medicaid Management Information Systems impose idiosyncratic documentation requirements that cloud-native platforms accommodate slowly.
- Hybrid:Combines local data processing with cloud backup and analytics layers.
- Mobile:Extends core platform functionality to tablets and smartphones for bedside documentation.
On-Premise retains margin concentration. Cloud-Based is climbing the fastest as subscription economics displace perpetual licenses.
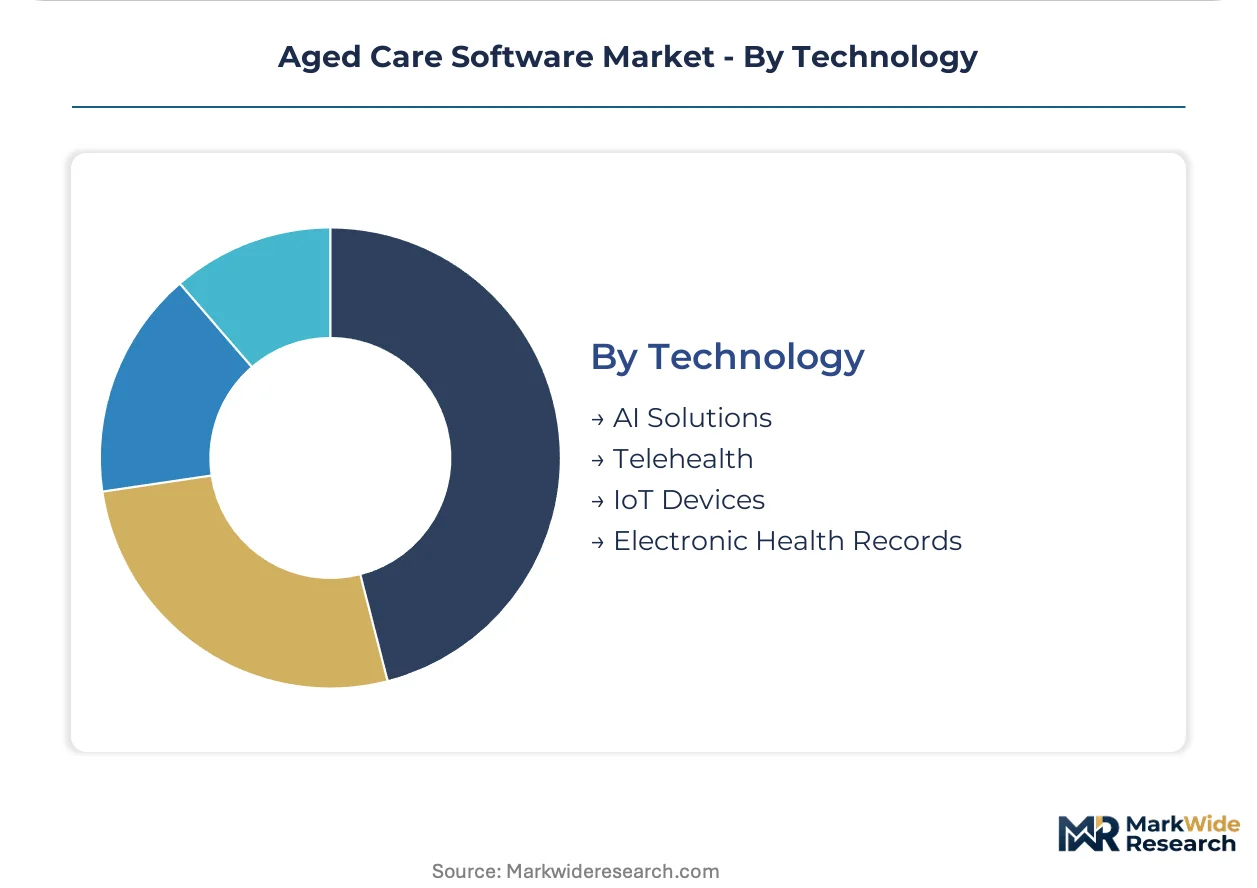
Technology:
Investment intensity separates commodity documentation tools from predictive capability platforms.
- Electronic Health Records:Forms the foundational data layer for all other modules, requiring deep integration with pharmacy, laboratory, and hospital admission systems. Post-acute care networks in the United States disqualify vendors lacking ONC Cures Act certification from procurement shortlists.
- AI Solutions:Deploys machine learning models for fall risk prediction, readmission forecasting, and staffing optimization. Skilled nursing facilities with above-average liability exposure are adopting these tools to reduce workers compensation claims and insurance premiums.
- Telehealth:Enables remote physician consultations and specialist access for rural facilities.
- IoT Devices:Captures continuous vital signs and mobility data through wearable sensors and room-based monitors.
Electronic Health Records holds installed capacity. AI Solutions is expanding most quickly as predictive analytics reshape quality outcome documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ONC Cures Act Final Rule certification requirements and Australia's Aged Care Quality and Safety Commission digital compliance mandates are redirecting procurement budgets toward interoperable platforms across major healthcare economies.
United States
Skilled nursing facilities and post-acute care networks are replacing legacy systems ahead of ONC Cures Act interoperability deadlines. HIPAA-aligned data exchange requirements now filter vendor shortlists to certified platforms capable of bidirectional hospital data flow. The Southeast region, particularly Florida and Georgia, concentrates facility expansion as elderly population migration accelerates cloud procurement cycles.
Australia
The Aged Care Quality and Safety Commission enforcement of strict digital documentation timelines is compelling residential aged care providers to abandon paper workflows. New South Wales and Victoria host the densest concentration of facility operators modernizing EHR infrastructure under federal compliance pressure. Sydney-based provider networks are driving fastest adoption of integrated medication management modules.
Germany
Long-term care insurance funds are tightening digital reporting requirements for nursing home reimbursement eligibility. The country's national health technology regulator evaluates software platforms for interoperability with hospital information systems. Bavaria and North Rhine-Westphalia concentrate the largest multi-site operators negotiating enterprise cloud migrations.
United Kingdom
The Care Quality Commission inspection modernization program is elevating digital accountability standards across English and Welsh aged care providers. NHS England interoperability frameworks are pressuring post-acute software vendors to demonstrate standardized API capabilities. London and Southeast England clusters dominate procurement volume as private equity consolidates facility ownership.
Canada
Provincial health authorities are harmonizing long-term care documentation requirements with federal interoperability standards. Health Canada oversight of medical device software classification is reshaping vendor certification pathways. Ontario and Quebec concentrate the majority of multi-facility operators evaluating cloud-native replacements for aging on-premise installations.
Aged Care Software Market Competitive Landscape
Player mix skews toward established health IT incumbents with post-acute specialization, creating a tiered structure where interoperability certification separates contract-eligible vendors from disqualification. The competitive landscape concentrates around three strategic archetypes: cloud-native specialists with skilled nursing focus, diversified enterprise health IT platforms, and behavioral health-post-acute integrators. Consolidation momentum is accelerating through strategic acquisitions of compliance-ready platforms and technology licensing partnerships that embed predictive analytics capabilities.
Within the cloud-native specialist tier, PointClickCare and AlayaCare exemplify vendors sustaining dominance through architecture purpose-built for post-acute regulatory complexity. MatrixCare, operating under ResMed ownership, occupies a position bridging sleep therapy data streams with long-term care documentation workflows. Netsmart Technologies anchors the behavioral health-post-acute convergence archetype, representing the integration layer strategy as dementia-psychiatric comorbidity protocols gain procurement priority.
| Leading Market Players |
|---|
| PointClickCare |
| MatrixCare (ResMed) |
| Netsmart Technologies |
| Oracle Cerner |
| Epic Systems Corporation |
| WellSky |
| Veradigm |
| Yardi Systems |
| AlayaCare |
| Others |
Pricing and Supply Chain Analysis
Thirty-to-ninety-day implementation timelines for cloud-native platforms concentrate pricing power with vendors holding ONC Cures Act certification, while subscription renewal cycles tether facility operators to incumbent suppliers. Australia's Aged Care Quality and Safety Commission deadlines compress procurement decision windows, amplifying vendor leverage in contract negotiations.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ONC Cures Act attestation commanding substantial premiums over uncertified alternatives. Subscription-based SaaS pricing dominates, though large multi-site operators negotiate enterprise licensing with customization bundles. Price differentiation rests on interoperability credentials and AI module depth, with home care providers exhibiting highest sensitivity due to thinner margins. Cost compression in mid-tier offerings intensifies as channel partners capture implementation revenue previously retained by vendors.
Supply Chain Analysis
Just-in-time deployment preferences dominate as facilities prioritize rapid onboarding over strategic stockpiling of legacy system alternatives. Cloud infrastructure concentrates supply in the United States, Ireland, and Singapore through hyperscaler data center networks. Raw material dependencies center on semiconductor components for IoT devices, API middleware licensing, and clinical content databases. Single-source vulnerability runs through dominant EHR platform providers whose certification status gates federal reimbursement eligibility. Distribution runs through specialized elder care IT consultancies rather than direct vendor sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aged care software market functions as a defensive-moat story where regulatory entrenchment creates structural switching costs that cement incumbent positions. ONC Cures Act certification requirements and Australia's Aged Care Quality and Safety Commission mandates erect barriers that compound over successive contract renewals.
For Market Incumbents: Secure interoperability certification maintenance as the priority defensive lever, investing in bi-directional hospital data exchange capabilities before attestation windows narrow. Acquire specialized behavioral health integration layers to capture dementia-psychiatric comorbidity workflows emerging as procurement priorities. Channel control through IT consultancy partnerships defends against cloud-native challengers targeting mid-sized facility segments.
For New Entrants and Emerging Players: Differentiate on AI-native fall prevention analytics where proprietary training data from longitudinal patient records creates sustainable advantage. Target home care providers expanding into skilled nursing as the most penetrable segment, where legacy platform re-architecture burdens incumbents. Pursue consultative sales models through Australian channel partners facing compressed decision cycles under federal compliance deadlines.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because certification requirements compound switching costs and consolidate procurement around compliant vendors. Prioritize acquisition targets with established ONC Cures Act credentials and installed bases in Southeast United States growth corridors. Watch Medicaid reimbursement harmonization progress as the signal indicating whether jurisdiction-specific code base maintenance costs will compress margins or sustain fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| ONC Cures Act Certification Investment | Federal reimbursement eligibility gates procurement shortlists to attested platforms. |
| Behavioral Health Integration Layer Acquisition | Dementia-psychiatric comorbidity protocols gain priority as elderly populations age. |
| AI Fall Prevention Module Development | Predictive analytics reduce workers compensation exposure for liability-conscious operators. |
| Australian Channel Partnership Expansion | Aged Care Quality and Safety Commission deadlines compress decision cycles favoring consultative sales. |
| Cloud-Native Architecture Migration | Subscription economics displace perpetual licenses across mid-sized assisted living chains. |
Research Methodology
A spread of perspectives from aged care facility CIOs, clinical informaticists, GPO contracts managers, and IT procurement officers converged on the working assumptions driving segmentation and growth estimates. Primary interviews with post-acute care network executives and home care provider operations directors combined with secondary validation against CMS Medicare data, hospital procurement databases, and ONC certification registries. Bottom-up facility counts and top-down reimbursement flow analysis triangulated market sizing across deployment models and technology categories.
Segmentation dimensions modeled include care setting type, organization size tier, integration complexity level, and regional regulatory cluster across the projection horizon. CAGRs derive from facility expansion trajectories, cloud migration velocity, and AI module attach rate assumptions. Forecast inputs incorporate ONC Cures Act compliance timeline acceleration, Australia's digital accountability enforcement intensity, and Medicaid Management Information Systems harmonization progress.
The analysis sits within stated boundaries; outcomes outside sustained regulatory pressure or accelerated interoperability standardization would require recalibration. Forecasts reflect documented assumptions about certification timeline adherence and reimbursement policy continuity. Practitioners should keep alternative scenarios live as HIPAA alignment depth and state-level Medicaid system convergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
E-Prescribing Market
Healthcare IT
Europe Healthcare Information Technology (IT) Market
Healthcare IT
Global Electronic Trial Master File (ETMF) Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Healthcare IT Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Patient Referral Management Software Market
Healthcare IT
Non-Clinical Homecare Software Market