
 Live Laser-Based Training and Simulation Platforms Market | 2026-2036
Live Laser-Based Training and Simulation Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Live Laser-Based Training and Simulation Platforms Market Foresight
ISO 9001 certification for defense subcontractors is reorganizing vendor eligibility across NATO procurement frameworks, filtering out smaller optical component suppliers that lack documented quality management systems. Rheinmetall AG leverages its integrated electro-optics division to sustain captive production of infrared laser emitters for small-arms simulators. Elbit Systems Ltd. anchors its position through backward integration into gallium arsenide laser diode manufacturing, reducing dependency on Asian semiconductor foundries.
Live laser-based training and simulation platforms employ eye-safe infrared laser transmitters mounted on actual weapons or replicas, coupled with body-worn sensor harnesses that register hit detection with positional accuracy below 10 centimeters; these systems replicate ballistic trajectories without live ammunition, enabling force-on-force exercises in confined urban training facilities. Military Training occupies the dominant margin pool given multi-year procurement cycles and classified performance requirements, while Augmented Reality segments compete for fastest expansion as head-mounted displays integrate with existing laser-based infrastructure rather than requiring full simulator replacement. Data Analytics capabilities represent an emerging attach rate opportunity, with after-action review software layering performance metrics onto raw engagement logs.
FDA laser product performance standards govern commercial eye-safety certification for training devices sold to civilian law enforcement and emergency services markets, while FCC Part 15 regulations constrain radio-frequency emissions from wireless target-response systems used in dense urban training centers. NATO STANAG 4694 and equivalent national military qualification protocols create bilateral testing burdens that favor established suppliers with dedicated certification engineering staff. Stakeholders must monitor divergence between U.S. DoD Synthetic Training Environment standards and European Permanent Structured Cooperation requirements, as misalignment threatens interoperability premiums in cross-border joint exercise contracts.
Market Dynamics
NATO STANAG standardization for laser-based tactical engagement systems is compressing procurement timelines while disqualifying vendors lacking certified quality management frameworks.
Growth Catalysts
- NATO STANAG 4694:Interoperability mandates across allied forces are accelerating platform refresh cycles and locking in multi-year procurement commitments.
- Eye-safe infrared laser transmitters:Advances in gallium arsenide diode manufacturing are reducing unit costs while maintaining sub-10-centimeter positional accuracy for hit detection.
- Urban warfare training centers:Confined facility requirements in the United States and Germany are displacing live-fire exercises with repeatable force-on-force simulation protocols.
Market Restraints
- Asian semiconductor foundry concentration:Backward integration into laser diode production remains capital-intensive, creating supply vulnerability for non-integrated vendors.
- FCC Part 15 compliance:Radio-frequency emission constraints for wireless target-response systems add certification engineering costs and extend development timelines.
- Live ammunition substitution ceiling:Certain ballistic trauma and weapons handling skills resist full simulation, preserving minimum live-fire quotas in military qualification pipelines.
Strategic Opportunities
- Data analytics attach rates:After-action review software layering performance metrics onto raw engagement logs represents an emerging recurring revenue stream.
- Civilian law enforcement expansion:FDA laser product performance standards for eye-safety certification are opening adjacent markets beyond military end-users.
- Augmented reality convergence:Head-mounted display integration with existing laser-based infrastructure avoids full simulator replacement costs for training facilities.
Industry Challenges
- ISO 9001 documentation gaps:Defense subcontractors lacking quality management system certification face exclusion from NATO procurement frameworks.
- Cross-border standardization friction:Divergence between U.S. DoD Synthetic Training Environment requirements and European Permanent Structured Cooperation protocols threatens interoperability premiums in joint exercise contracts.
- Optical component talent scarcity:Specialized electro-optics engineering expertise concentrates within integrated defense primes, constraining vendor base expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Live Laser-Based Training and Simulation Platforms Market |
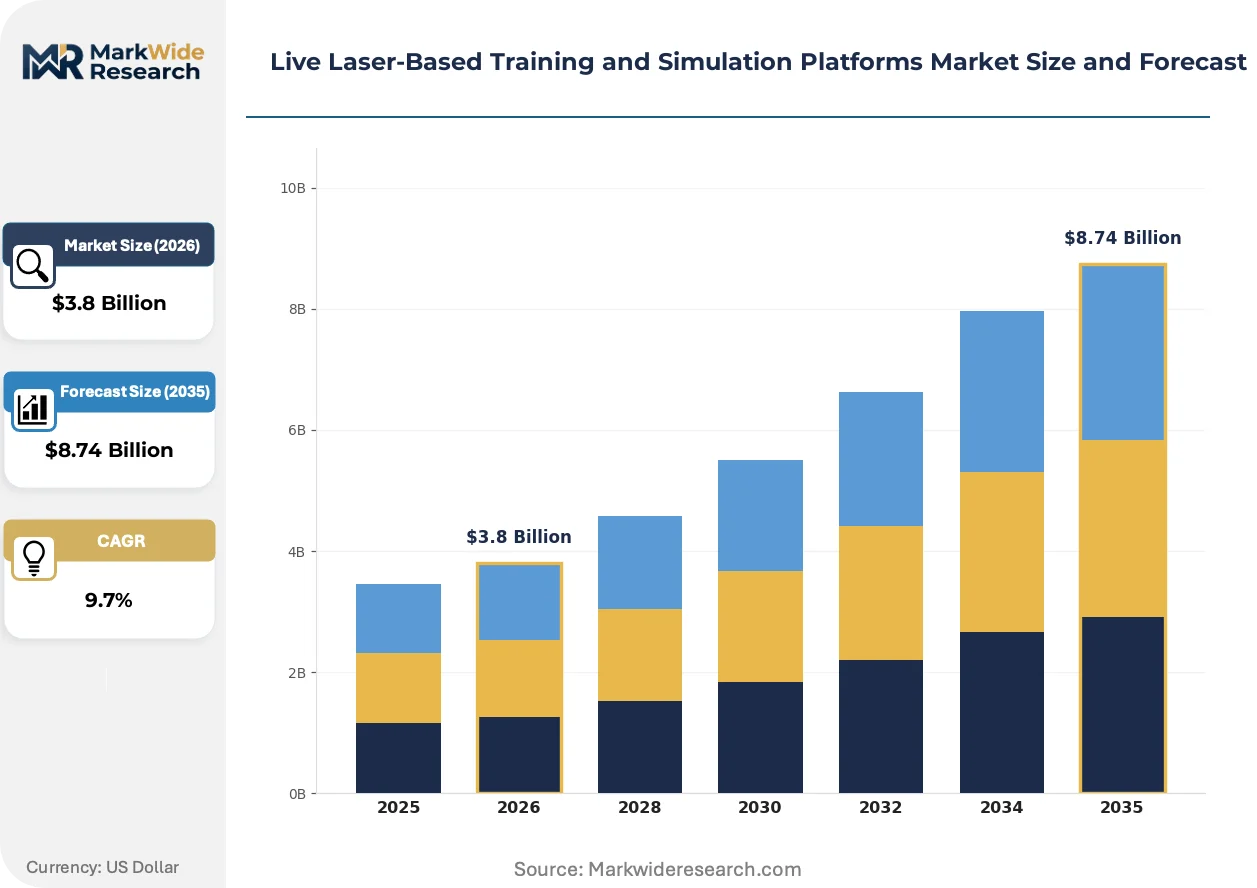
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Simulators, Feedback Systems, Training Software, Scenario Generators Use Case: Military Training, Emergency Services, Educational Institutes, Corporate Training Technology: Augmented Reality, Virtual Reality, Real-Time Feedback, Data Analytics End User: Defense Forces, Fire Departments, Universities, Corporate Entities |
| Companies Covered | Cubic Corporation, BAE Systems, Lockheed Martin Corporation, L3Harris Technologies, Inc., General Dynamics Corporation, Rheinmetall AG, Elbit Systems Ltd., Northrop Grumman, Laser Shot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Live Laser-Based Training and Simulation Platforms Market Shifts & Advancements
Synthetic training environments are fragmenting hardware-centric procurement models into modular, software-upgradable platform architectures.
Eye-safe infrared laser transmitters mounted on actual weapons or high-fidelity replicas are decomposing the traditional distinction between live-fire and simulated training. Military training commands in the United States and Germany are adopting these systems at procurement cycle compression rates that favor vendors with backward-integrated diode manufacturing. This technology is decomposing capital expenditure patterns by enabling incremental capability upgrades rather than full platform replacement.
EU CSRD disclosure requirements are mandating documented supply chain environmental footprints for defense subcontractors seeking European procurement eligibility. ISO 9001 certification has become a binary filter for vendor qualification, with optical component suppliers lacking quality management documentation facing systematic exclusion. Civilian law enforcement segments are responding by demanding pre-certified training devices that satisfy both FDA laser safety standards and emerging sustainability disclosure frameworks.
Buyer concentration within defense ministries is compressing vendor negotiation leverage while extending payment terms. Training facility operators are unbundling after-action review software from hardware procurement, creating discrete purchasing decisions for analytics capabilities. This pattern is most visible in the United States, where the Department of Defense's program of record for synthetic training environments is segmenting procurement into separately competed hardware, software, and sustainment contracts.
Live Laser-Based Training and Simulation Platforms Market Segmentation
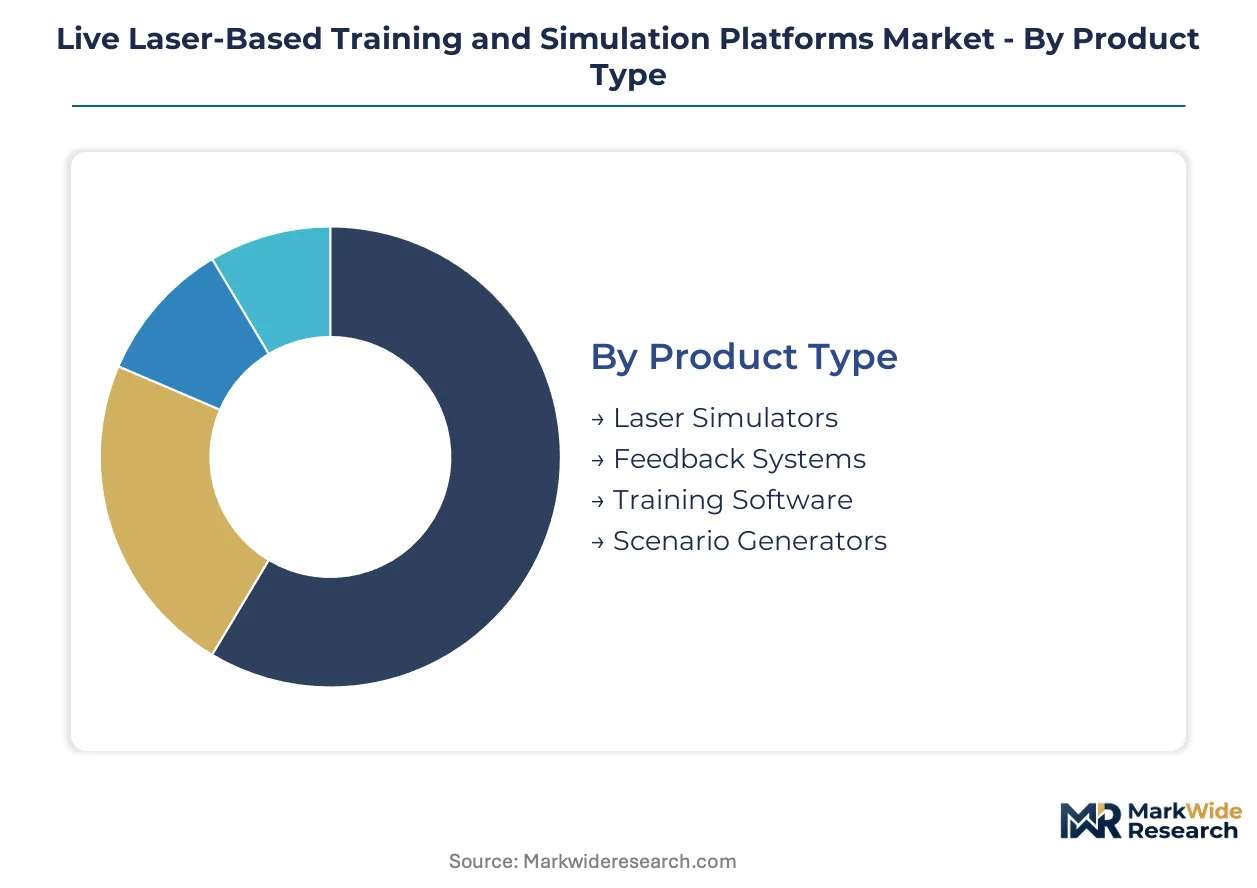
Segmentation in live laser-based training platforms reveals how procurement budgets fragment across hardware, software, and service layers. Defense ministries prioritize systems with NATO STANAG interoperability, while civilian buyers emphasize FDA eye-safety certification and modular upgrade paths.
Product Type:
Margin pools concentrate in integrated systems where laser emitters and sensor harnesses ship as unified platforms rather than discrete components.
- Laser Simulators:Eye-safe infrared transmitters mount on actual weapons or high-fidelity replicas, replicating ballistic trajectories without live ammunition. Defense ministries in the United States and Germany dominate procurement, driven by urban warfare training center requirements that displace live-fire exercises in confined facilities.
- Training Software:After-action review platforms layer performance metrics onto raw engagement logs, creating recurring revenue streams through subscription licensing. Demand concentrates among NATO-aligned forces seeking STANAG 4694-compliant analytics for joint exercise debriefing.
- Feedback Systems:Body-worn sensor harnesses register hit detection with sub-10-centimeter positional accuracy.
- Scenario Generators:Urban terrain libraries and adversary behavior models enable repeatable force-on-force exercises.
Laser Simulators hold installed capacity. Training Software is rotating up the share rankings.
Use Case:
Volume concentrates in multi-year defense contracts, though emergency services procurement cycles compress as FDA certification pathways mature for civilian markets.
- Military Training:Force-on-force exercises in confined urban facilities replace live-fire protocols, with NATO STANAG standardization mandating interoperability across allied forces. Procurement timelines stretch across fiscal year boundaries, locking in vendor relationships through classified performance requirements.
- Corporate Training:Security teams and high-risk facility operators adopt laser-based simulation for active shooter response drills, leveraging pre-certified devices that satisfy both FDA laser safety standards and insurance liability frameworks.
- Emergency Services:Fire departments and tactical medical units require eye-safe training for high-stress scenarios.
- Educational Institutes:Criminal justice and forensic science programs integrate simulation into curriculum.
Military Training holds installed capacity. Corporate Training is rotating up the share rankings.
Technology:
Application intensity varies by integration burden, with head-mounted displays layering onto existing laser infrastructure more quickly than full simulator replacement.
- Augmented Reality:Head-mounted displays integrate with existing laser-based infrastructure, avoiding capital-intensive platform replacement while enhancing situational awareness overlays. German and United States training facilities lead adoption, compressing procurement cycles for incremental capability upgrades.
- Data Analytics:Performance metric engines attach to raw engagement logs, unbundling from hardware procurement as discrete purchasing decisions. The Department of Defense's segmented contracting approach for synthetic training environments accelerates vendor competition in this layer.
- Virtual Reality:Fully immersive environments replace physical training spaces for certain skill domains.
- Real-Time Feedback:Instant hit detection and ballistic correction during live exercises.
Real-Time Feedback holds installed capacity. Augmented Reality is climbing the fastest.
End User:
Customer concentration within defense ministries compresses vendor negotiation leverage while extending payment terms for integrated system vendors.
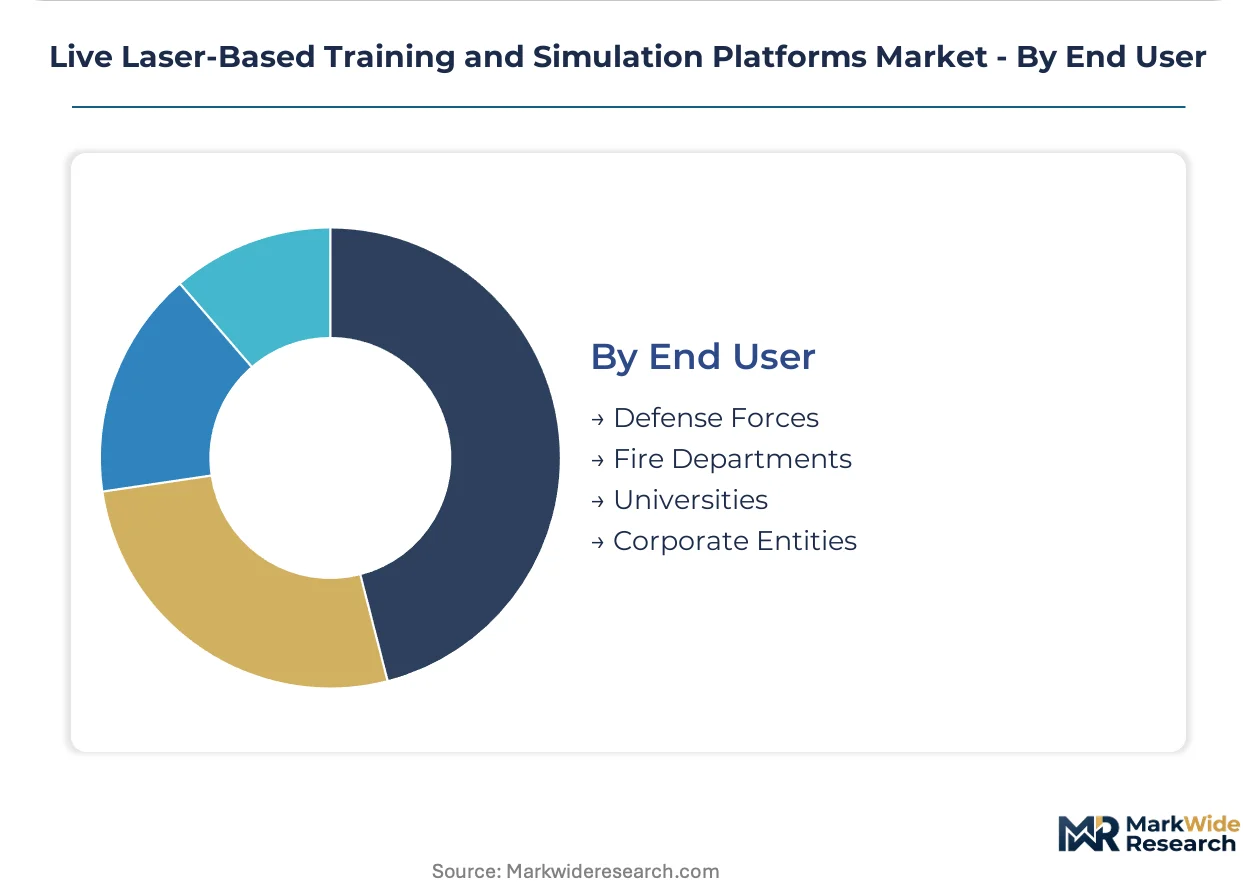
- Defense Forces:The Department of Defense maintains the world's largest program of record for synthetic training environments, segmenting procurement into separately competed hardware, software, and sustainment contracts. NATO STANAG 4694 compliance filters vendor eligibility, favoring suppliers with backward-integrated laser diode manufacturing.
- Corporate Entities:Security-conscious industries including critical infrastructure and financial services adopt pre-certified training devices, with procurement decisions driven by insurance underwriting requirements and regulatory compliance documentation.
- Fire Departments:Tactical emergency response units require force-on-force simulation for high-risk entry scenarios.
- Universities:Criminal justice and military science programs seek cost-effective entry-level systems.
Defense Forces hold installed capacity. Corporate Entities is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement frameworks and NATO interoperability mandates are redistributing platform demand across allied territories. Fiscal commitments to synthetic training infrastructure vary sharply by national security posture and urban warfare facility density.
United States
The Department of Defense maintains the world's largest program of record for synthetic training environments, segmenting procurement into separately competed hardware, software, and sustainment contracts. FCC Part 15 regulations constrain radio-frequency emissions from wireless target-response systems used in dense urban training centers. Installation concentration clusters around Fort Irwin's National Training Center in California and the Joint Readiness Training Center at Fort Polk, Louisiana.
Germany
Confined urban warfare training facility requirements are displacing live-fire exercises with repeatable force-on-force simulation protocols across Bundeswehr commands. EU CSRD disclosure requirements mandate documented supply chain environmental footprints for defense subcontractors seeking European procurement eligibility. Industrial capability concentrates in Bavaria and North Rhine-Westphalia, where electro-optics engineering expertise supports integrated system production.
United Kingdom
Ministry of Defence procurement timelines stretch across fiscal year boundaries, locking in vendor relationships through classified performance requirements for tactical engagement systems. NATO STANAG 4694 compliance filters vendor eligibility for joint exercise participation with allied forces. Defense technology development clusters in the Southwest England corridor around Bristol and Bath.
Israel
Domestic security requirements drive demand for eye-safe training devices that satisfy both military qualification protocols and civilian law enforcement certification pathways. The country's national pharmaceutical regulator enforces laser product performance standards for commercial eye-safety certification. Technology development concentrates in Tel Aviv and Haifa metropolitan corridors.
Australia
Defence Department investment in synthetic training infrastructure follows NATO interoperability commitments for regional joint exercise participation. TGA standards influence procurement specifications for medical and emergency services training device acquisitions. Capability development clusters in Victoria and New South Wales around Melbourne and Sydney defense technology corridors.
Live Laser-Based Training and Simulation Platforms Market Competitive Landscape
Listed leaders compete with private specialists across certification engineering capacity and backward-integrated component manufacturing. Market structure tilts toward consolidated prime contractors with dedicated quality management frameworks and in-house electro-optics divisions. Two strategic archetypes dominate: integrated defense conglomerates with captive laser diode production, and specialized training system vendors with modular software architectures. Competitive moves concentrate on M&A for electro-optics talent acquisition and strategic partnerships for NATO STANAG certification acceleration.
Within the integrated prime tier, Rheinmetall AG and Elbit Systems Ltd. exemplify backward-integrated positioning through in-house production of infrared laser emitters and gallium arsenide laser diode manufacturing respectively. Cubic Corporation represents the specialized systems archetype with modular platform architectures. L3Harris Technologies, Inc. occupies a position spanning both integration models through diversified defense electronics portfolios.
| Leading Market Players |
|---|
| Cubic Corporation |
| BAE Systems |
| Lockheed Martin Corporation |
| L3Harris Technologies, Inc. |
| General Dynamics Corporation |
| Rheinmetall AG |
| Elbit Systems Ltd. |
| Northrop Grumman |
| Laser Shot |
| Others |
Supply & Pricing Matrix
Capacity utilization at gallium arsenide foundries in Asia determines price floors for infrared laser emitters, compressing margins for non-integrated vendors while rewarding primes with captive diode production. This scale dynamic concentrates procurement leverage among defense ministries that negotiate multi-year hardware contracts.
Pricing Analysis
Certification level creates the primary spread between NATO STANAG-qualified systems and commercial-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9001 documentation depth and FDA eye-safety clearance status. Cost compression in mid-tier systems is intensifying because Asian semiconductor foundry concentration limits supply alternatives. Corporate security buyers exhibit highest price sensitivity, while defense procurement officers prioritize interoperability premiums over unit economics.
Supply Chain Analysis
Strategic stockpiling of gallium arsenide substrates and infrared optical components dominates inventory strategy, with primes maintaining six-to-nine-month safety buffers against foundry allocation shocks. Supply concentrates in Taiwan, South Korea, and Germany for laser diode fabrication and precision optical assembly. Production rests on specialized gallium arsenide wafers, eye-safe wavelength filters, and body-worn sensor microcontrollers. Single-source vulnerability in epitaxial wafer supply threatens platform delivery schedules. Distribution runs through defense prime contractor channels with direct ministry relationships rather than open market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against VR-based training platforms that bypass laser infrastructure entirely. Incumbents must demonstrate irreplaceable force-on-force fidelity to preserve procurement relevance.
For Market Incumbents: Consolidate electro-optics engineering talent through targeted acquisition of specialized diode manufacturers in Israel and Germany. Lock in NATO STANAG certification acceleration by embedding liaison engineers with national qualification authorities. Vertical integration into gallium arsenide production insulates against foundry allocation shocks that threaten delivery commitments to the Department of Defense.
For New Entrants and Emerging Players: Anchor in civilian law enforcement segments where FDA certification pathways mature faster than military qualification timelines. Target corporate security training facilities in financial services and critical infrastructure sectors that demand pre-certified devices without classified performance requirements. Pursue modular software attach-rate strategies that layer analytics onto existing laser infrastructure rather than competing for hardware replacement cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors primes with backward-integrated component manufacturing and established NATO qualification relationships. Long-term viability hinges on recurring software revenue attach rates rather than transactional hardware sales. Acquisition targets should demonstrate captive laser diode production or dedicated certification engineering staff. Watch for divergence between U.S. DoD Synthetic Training Environment standards and European Permanent Structured Cooperation protocols as inflection signal for interoperability premium erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Diode Manufacturing | Captive gallium arsenide production insulates Rheinmetall and Elbit from Asian foundry concentration risks. |
| NATO STANAG Certification Acceleration | Dedicated liaison engineering with national qualification authorities compresses vendor eligibility timelines for joint exercise contracts. |
| Modular Software Architecture Development | Cubic Corporation's platform approach enables incremental capability upgrades without full simulator replacement. |
| Civilian Market FDA Certification Pathway | Pre-certified eye-safe devices open adjacent revenue streams beyond defense procurement cycles. |
| Data Analytics Subscription Layering | After-action review software unbundles from hardware to create recurring revenue attach rates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, electro-optics engineering directors, and training facility operators; and secondary validation against NATO STANAG documentation, FDA laser product performance standards, FCC Part 15 regulatory filings, and defense ministry budget appropriations. Bottom-up triangulation across vendor shipment records and top-down reconciliation against national synthetic training environment investments anchored market sizing.
Across the analysis window, the forecast framework modeled volume and value trajectories by product type, use case, technology layer, and end-user concentration. CAGRs derived from segment-level growth rate reconciliation against macro defense spending patterns and urban warfare training facility buildout schedules. Industry-specific inputs included NATO interoperability mandate implementation timelines and gallium arsenide diode manufacturing capacity expansion announcements.
Decision-makers should treat outputs as directional under sustained defense budget commitments and stable semiconductor supply conditions; material deviation would warrant model refresh. Forecasts reflect assumptions of continued NATO STANAG standardization momentum and no acute escalation in Taiwan Strait supply disruptions. Revision becomes warranted when gallium arsenide foundry allocation shocks or trans-Atlantic regulatory divergence crosses thresholds that alter vendor eligibility patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Global Ship Bridge Simulators Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
Satellite Simulator Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Flight Simulator Market
Simulation and Training
Dynamic Flight Training Compartments Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
Simulators Market
Simulation and Training
Civil Aerospace Simulation and Training Market