
 Land-Based Military Electro-Optical and Infrared Systems Market | 2026-2036
Land-Based Military Electro-Optical and Infrared Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Land-Based Military Electro-Optical and Infrared Systems Market Foresight
Skilled electro-optics engineering talent is collapsing across NATO defense industrial bases, constraining production ramp rates for precision gimbal assemblies and cooled infrared detector arrays. BAE Systems plc leverages its British manufacturing footprint to sustain vertical integration in thermal imaging cores for armored fighting vehicles. Elbit Systems Ltd anchors Israeli supply chains through captive production of laser designation modules and night vision systems. L3Harris Technologies dominates U.S. ground force modernization by controlling delivery timelines for integrated soldier vision enhancements.
Land-based military electro-optical and infrared systems encompass stabilized sensor payloads combining infrared detectors, visible-light cameras, and laser rangefinders operating across SWIR through LWIR wavebands, typically mounted on vehicles or tripod platforms for target identification beyond 5 kilometers under degraded visibility conditions. These systems serve primarily to extend ground force engagement ranges while reducing collateral damage through positive identification protocols. Thermal imagers lead product type revenue due to universal vehicle and dismounted soldier adoption, while targeting systems represent the fastest-growing category as artillery precision requirements intensify. MWIR technology occupies the premium tier for long-range detection, though uncooled LWIR formats are displacing legacy cooled architectures in perimeter security applications.
U.S. ITAR export controls and EU dual-use regulations shape cross-border technology transfer permissions for focal plane arrays and laser designators, directly conditioning market access for non-dominated suppliers. India's BIS certification requirements and PLI scheme incentives for defense manufacturing redirect procurement toward local assembly partnerships with foreign OEMs. Stakeholders must monitor evolving classification thresholds for uncooled sensor exports, as regulatory recalibration could abruptly resegment competitive positioning between integrated primes and component specialists.
Market Dynamics
Armored vehicle modernization programs across NATO and Indo-Pacific militaries are compressing development cycles for multi-spectral targeting payloads, forcing integrators to reconcile thermal imager performance thresholds with tightening export control classifications.
Growth Catalysts
- Artillery Precision Mandates:NATO standardization requirements for beyond-line-of-sight targeting are accelerating procurement of stabilized sensor payloads combining laser rangefinders with cooled MWIR detectors.
- India's PLI Scheme:Production-linked incentives for defense manufacturing under the Make in India framework redirect foreign OEM partnerships toward local assembly of night vision devices and thermal cores.
- Uncooled LWIR Maturation:Advances in vanadium oxide microbolometer yields are enabling perimeter security deployments without cryogenic cooling infrastructure, expanding addressable base to border surveillance agencies.
Market Restraints
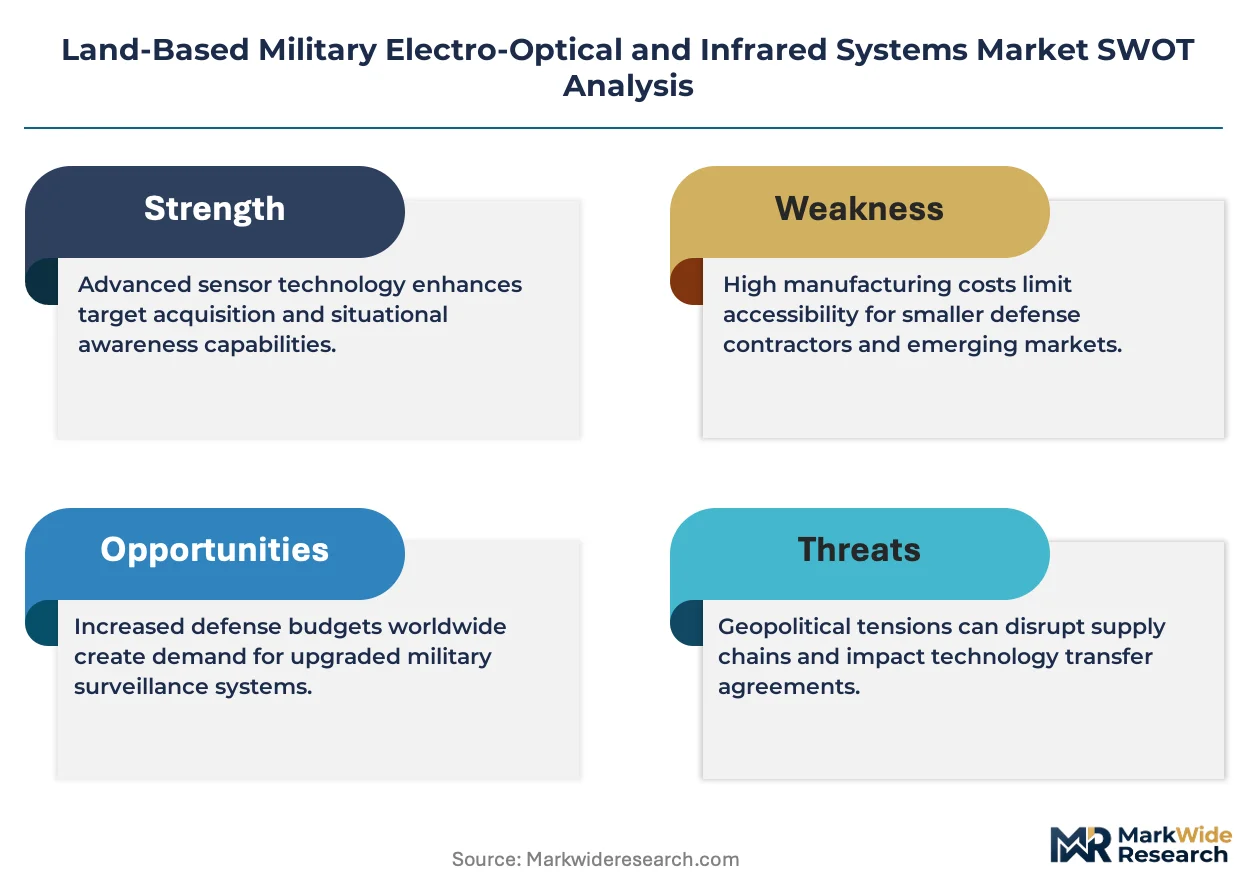
- Indium Antimonide Supply Concentration:Cooled MWIR detector fabrication depends on Chinese-controlled gallium and indium refining capacity, exposing focal plane array production to mineral export restrictions.
- ITAR Classification Thresholds:U.S. State Department regulations treat sub-25 micron pixel pitch arrays as munitions, blocking technology transfer to non-ally assembly partners regardless of end-use civilian designation.
- Skilled Electro-Optics Labor Scarcity:NATO defense industrial bases face collapsing pipelines of precision gimbal assembly technicians and infrared detector packaging engineers, constraining production ramp rates.
Strategic Opportunities
- SWIR-LWIR Sensor Fusion:Convergence of short-wave infrared imagers with long-wave thermal cores enables positive identification through obscurants, opening artillery forward observer applications previously served by single-band systems.
- Indigenous Indian Manufacturing:Bharat Electronics and Tata Advanced Systems are establishing captive supply chains for laser designation modules, creating white space for component specialists willing to transfer packaging technology under offset agreements.
- EU Dual-Use Recalibration:Proposed revisions to the EU dual-use regulation may reclassify uncooled thermal imagers below specific resolution thresholds, potentially liberalizing cross-border component flows to African and Southeast Asian border security programs.
Industry Challenges
- Cryogenic Cooler Reliability Certification:Stirling cycle cooler mean-time-between-failure validation for military environmental standards extends qualification timelines by 18-24 months, compressing available contract delivery windows.
- Legacy Vehicle Integration Complexity:Retrofitting digital sensor outputs onto analog fire-control architectures in Cold War-era armored platforms requires custom signal conditioning hardware that fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Land-Based Military Electro-Optical and Infrared Systems Market |
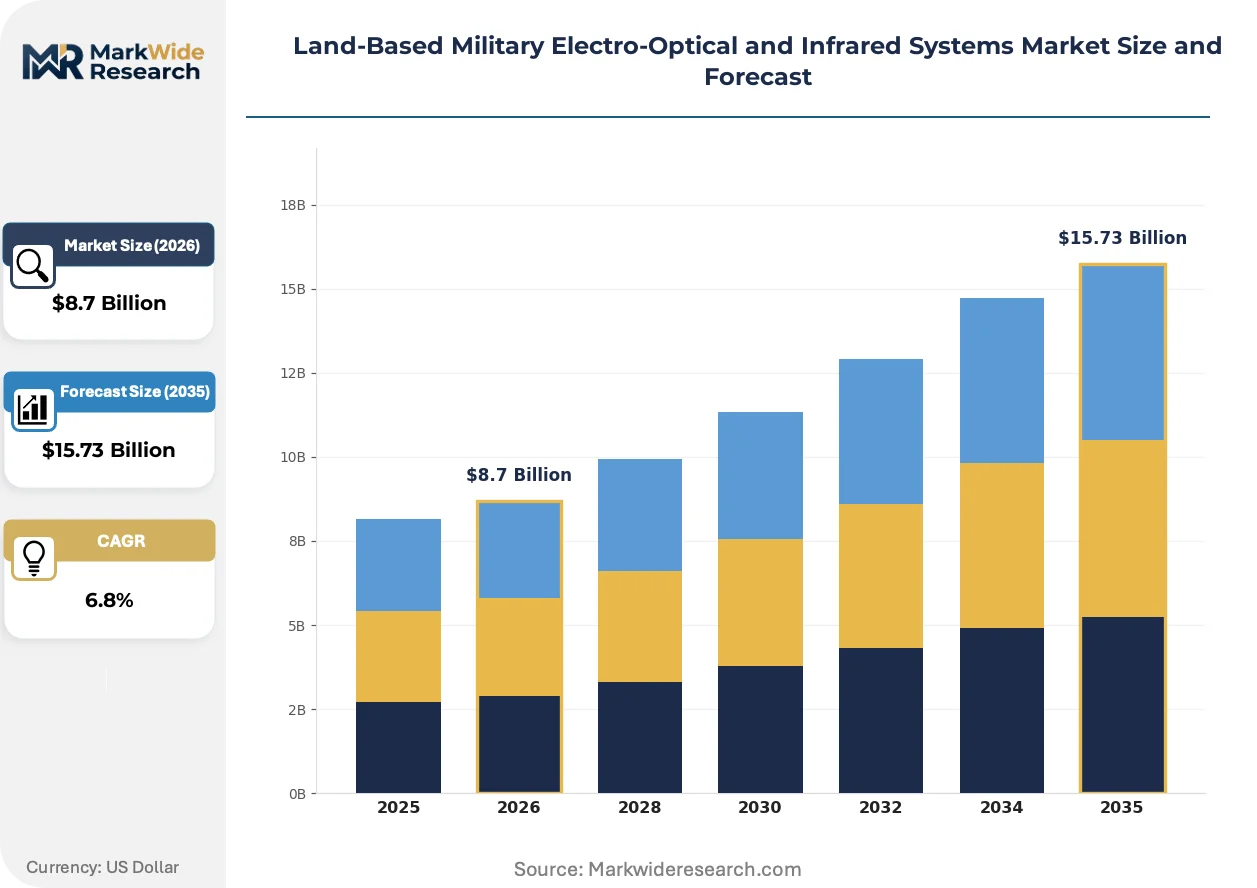
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Imagers, Night Vision Goggles, Targeting Systems, Laser Rangefinders Technology: SWIR, MWIR, LWIR, CCD End User: Military Forces, Defense Contractors, Government Agencies, Security Services Application: Surveillance, Reconnaissance, Target Acquisition, Navigation |
| Companies Covered | BAE Systems plc, Elbit Systems Ltd, L3Harris Technologies, Israel Aerospace Industries Ltd, Rheinmetall AG, Thales Group, HENSOLDT AG, Lockheed Martin Corporation, RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Land-Based Military Electro-Optical and Infrared Systems Market Shifts & Advancements
Stabilized payload architectures are converging around software-defined sensor fusion, replacing discrete hardware modules with unified processing layers that compress size, weight, and power constraints for dismounted and vehicle-mounted applications alike.
Uncooled vanadium oxide microbolometers is supplanting legacy indium antimonide cooled arrays in perimeter security and short-range targeting roles. Indian paramilitary forces and European border agencies are adopting these sensors for tripod-mounted surveillance at volume procurement scales previously reserved for military programs. This transition is supplanting the traditional premium tier structure of the detector market, forcing cooled-array specialists to retreat toward long-range airborne and maritime applications where resolution and sensitivity thresholds remain uncompromisable.
Updated U.S. ITAR Category XII controls and pending EU dual-use regulation amendments are recalibrating technology transfer permissions for focal plane arrays and laser designators. The industrial consequence is a bifurcation of supply chains: ally-accessible component flows versus restricted-path prime integrator relationships. Cooled MWIR detector procurement for non-NATO militaries is most affected, with Indian and Israeli suppliers accelerating indigenous alternatives to circumvent Washington and Brussels licensing bottlenecks.
Defense procurement offices are consolidating vendor relationships around full-spectrum system integrators capable of delivering soldier vision enhancements, vehicle sights, and targeting pods under unified logistics frameworks. Traditional component specialists face disintermediation unless they reposition as captive suppliers to these primes. This concentration is most visible in U.S. Army and Marine Corps ground force modernization programs, where L3Harris and BAE Systems are absorbing subsystem selection authority previously exercised by platform OEMs.
Land-Based Military Electro-Optical and Infrared Systems Market Segmentation
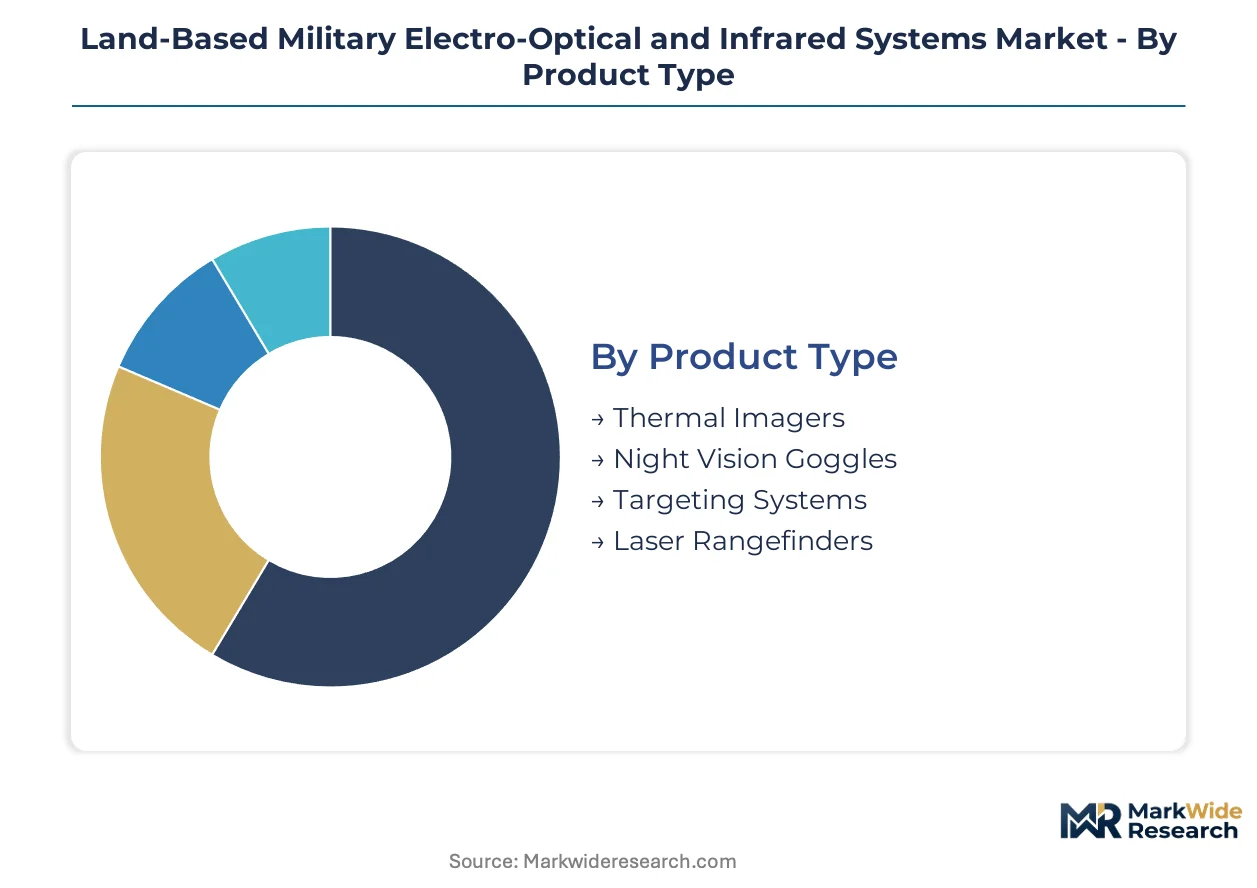
Segmentation in land-based military EO/IR systems reveals how procurement authority concentrates around specific performance thresholds and regulatory classifications. Product type and technology choices determine export licensing pathways, while end-user categories dictate maintenance infrastructure requirements and operational doctrine integration.
Product Type:
Regulatory differentiation separates munitions-classified laser designators from dual-use thermal cores, reshaping supplier eligibility across procurement channels.
- Thermal Imagers:These systems combine vanadium oxide or indium antimonide detector arrays with stabilized gimbal assemblies for vehicle-mounted and dismounted soldier applications. Armored vehicle modernization programs across NATO militaries drive procurement of multi-spectral variants integrating SWIR through LWIR wavebands. Established volume favors thermal imagers; emerging adoption favors targeting systems.
- Night Vision Goggles:Image intensification devices using gallium arsenide photocathodes provide dismounted infantry with ambient light amplification for close-quarters navigation. India's PLI scheme incentives redirect foreign OEM partnerships toward local assembly of these devices under Make in India frameworks.
- Targeting Systems:Stabilized sensor payloads integrating laser rangefinders with cooled MWIR detectors for beyond-line-of-sight artillery coordination.
- Laser Rangefinders:Eye-safe and non-eye-safe variants subject to ITAR Category XII controls for precision targeting applications.
Component specialists face disintermediation unless they reposition as captive suppliers to full-spectrum integrators controlling subsystem selection authority.
Technology:
Cost tier separation distinguishes cryogenically cooled premium formats from uncooled perimeter security alternatives, fragmenting supplier competitive sets.
- MWIR:Cooled indium antimonide focal plane arrays deliver superior sensitivity for long-range detection beyond 5 kilometers under degraded atmospheric conditions. Chinese-controlled gallium and indium refining capacity exposes production to mineral export restrictions, constraining supply security for NATO defense industrial bases.
- LWIR:Uncooled vanadium oxide microbolometers eliminate Stirling cycle cooler maintenance requirements for border surveillance and perimeter security deployments. European border agencies and Indian paramilitary forces adopt these sensors at volume procurement scales previously reserved for military programs.
- SWIR:Short-wave infrared imagers enable positive identification through obscurants when fused with thermal cores, gaining share fastest in artillery forward observer applications.
- CCD:Charge-coupled device visible-light cameras provide daytime target identification in legacy fire-control architectures requiring analog signal conditioning.
Resolution thresholds determine ITAR classification stringency, with sub-25 micron pixel pitch arrays treated as munitions regardless of end-use designation.
End User:
Customer type dictates maintenance infrastructure depth, with military forces requiring depot-level support unavailable to security services.
- Military Forces:Ground force modernization programs consolidate vendor relationships around integrators capable of delivering soldier vision enhancements, vehicle sights, and targeting pods under unified logistics frameworks. U.S. Army and Marine Corps programs absorb subsystem selection authority previously exercised by platform OEMs.
- Defense Contractors:System integrators and subsystem suppliers serving as intermediaries in offset agreements and technology transfer arrangements.
- Government Agencies:Border surveillance and critical infrastructure protection programs with procurement autonomy outside defense ministry channels.
- Security Services:Paramilitary and law enforcement units adopting commercial-derivative thermal imagers below ITAR threshold specifications.
Procurement authority concentrates in military forces; flexibility in vendor selection characterizes security services.
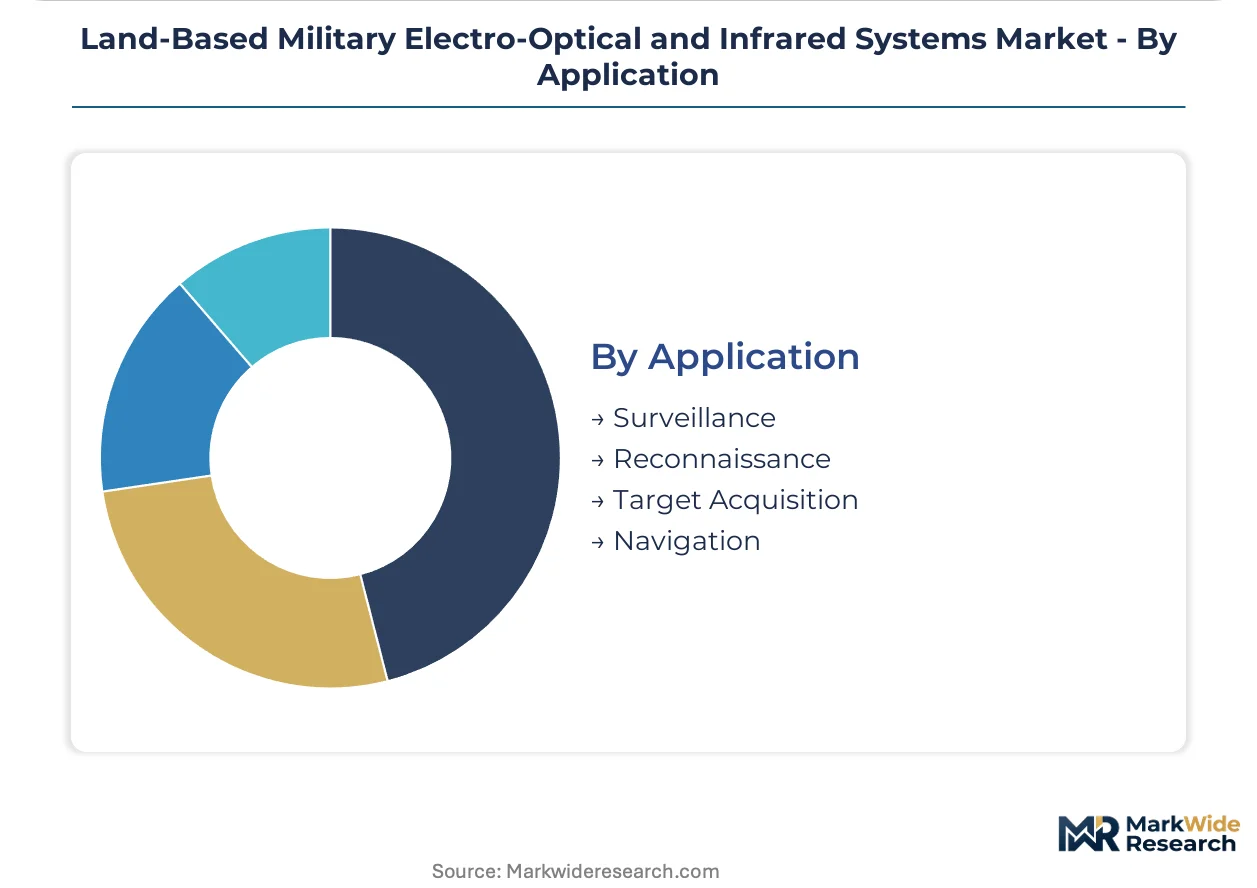
Application:
Operational maturity separates legacy navigation aids from precision targeting architectures reshaping artillery engagement doctrines.
- Target Acquisition:Multi-spectral sensor fusion for positive identification protocols reducing collateral damage in beyond-line-of-sight engagements. NATO standardization requirements accelerate procurement of stabilized payloads combining laser rangefinders with cooled MWIR detectors.
- Surveillance:Tripod-mounted and vehicle-integrated observation posts for border monitoring and perimeter security. Uncooled LWIR formats displace legacy cooled architectures as vanadium oxide microbolometer yields mature.
- Reconnaissance:Dismounted and vehicle-mounted forward observation for intelligence collection and battle damage assessment.
- Navigation:Night vision and thermal driving aids for armored vehicle crews in zero-illumination environments.
Artillery precision mandates elevate target acquisition priority; perimeter security applications drive volume scaling in uncooled technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
U.S. ITAR regulations anchor the dominant geography, conditioning technology transfer permissions for focal plane arrays and laser designators across allied and non-allied procurement channels.
United States
Ground force modernization programs compress development cycles for multi-spectral targeting payloads. State Department ITAR Category XII controls treat sub-25 micron pixel pitch arrays as munitions, blocking transfers regardless of civilian end-use designation. Huntsville, Alabama and Orlando, Florida clusters concentrate prime integrator engineering for soldier vision enhancements and vehicle sights.
India
Border surveillance modernization and expanding indigenous manufacturing reshape procurement toward local assembly partnerships. BIS certification requirements and PLI scheme incentives redirect foreign OEM relationships under Make in India frameworks. Hyderabad and Bengaluru industrial corridors establish captive supply chains for laser designation modules through Bharat Electronics and Tata Advanced Systems partnerships.
Germany
Armored vehicle modernization across NATO standardization requirements accelerates procurement of stabilized sensor payloads. EU dual-use regulation amendments recalibrate technology transfer permissions for uncooled thermal imagers below specific resolution thresholds. Munich and Oberkochen precision optics clusters sustain vertical integration in thermal imaging cores for armored fighting vehicles.
Israel
Indigenous alternatives to circumvent Washington and Brussels licensing bottlenecks accelerate cooled MWIR detector development. Captive production of laser designation modules and night vision systems anchors supply chain security. Haifa and Beersheba defense technology corridors concentrate electro-optics engineering for multi-spectral targeting systems.
United Kingdom
Precision gimbal assembly technician scarcity constrains production ramp rates across NATO defense industrial bases. British manufacturing footprints sustain vertical integration in thermal imaging cores through established prime relationships. Glasgow and Portsmouth shipbuilding-adjacent clusters pivot toward land-based vehicle sight production for export markets.
Land-Based Military Electro-Optical and Infrared Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressure intensifying around full-spectrum system integrators capable of unified logistics frameworks. Prime contractors absorb subsystem selection authority previously exercised by platform OEMs, forcing component specialists toward captive supplier repositioning. Three archetypes dominate: vertically integrated defense primes controlling delivery timelines, regional champions leveraging indigenous manufacturing policies, and component specialists retreating toward premium long-range applications. Competitive moves center on strategic partnerships for local assembly under offset agreements and technology licensing to circumvent export control bottlenecks.
Among British- and American-based integrated primes, BAE Systems plc and L3Harris Technologies exemplify the consolidated tier absorbing subsystem authority, while Elbit Systems Ltd occupies a position representing Israeli supply chain anchoring through captive electro-optics production. These three illustrate how geographic regulatory exposure shapes competitive archetype selection, with U.S. ITAR exposure favoring domestic integrators and Israeli indigenous development circumventing licensing constraints.
| Leading Market Players |
|---|
| BAE Systems plc |
| Elbit Systems Ltd |
| L3Harris Technologies |
| Israel Aerospace Industries Ltd |
| Rheinmetall AG |
| Thales Group |
| HENSOLDT AG |
| Lockheed Martin Corporation |
| RTX Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for indium antimonide focal plane arrays lock in supply access for NATO prime integrators while insulating pricing from spot mineral volatility. These arrangements transfer gallium and indium refining risk to contract holders, compressing margin exposure for cooled MWIR detector procurement.
Pricing Analysis
U.S. ITAR-controlled systems command substantial premiums over EU dual-use tier equivalents, with price spreads widening for sub-25 micron pixel pitch arrays classified as munitions. Three-tier pricing structure across ITAR-restricted, EU dual-use, and commercial-derivative levels segments buyer access by regulatory clearance. Cost compression in uncooled LWIR tiers is intensifying because vanadium oxide microbolometer yields are maturing, forcing cooled-array specialists toward premium long-range applications. Security services exhibit highest price sensitivity, while military forces prioritize performance thresholds over unit economics.
Supply Chain Analysis
Strategic stockpiling of gallium and indium feedstock dominates over just-in-time preferences given Chinese mineral export restriction risks. Detector fabrication concentrates in the United States, Israel, and India, with each jurisdiction developing indigenous capacity to circumvent Washington and Brussels licensing bottlenecks. Supply chains rest on Chinese-controlled rare earth refining, germanium substrate production, and precision gimbal machining capabilities concentrated in British and German industrial clusters. Single-source vulnerability in Stirling cycle cooler manufacturing extends qualification timelines. Distribution runs through prime integrator channels that absorb subsystem selection authority previously held by platform OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Uncooled LWIR maturation is disrupting traditional premium-tier detector economics, compressing margins for cooled-array specialists while opening volume procurement pathways for perimeter security applications.
For Market Incumbents: Secure captive supply agreements for indium antimonide focal plane arrays before Chinese mineral export restrictions tighten further. Deepen backward integration into precision gimbal assembly to offset collapsing electro-optics engineering talent pipelines across NATO defense industrial bases. For New Entrants and Emerging Players: Differentiate on software-defined sensor fusion architectures that compress size, weight, and power constraints for dismounted soldier applications. Target Indian paramilitary and border surveillance procurement channels where PLI scheme incentives favor local assembly partnerships with foreign OEMs willing to transfer packaging technology. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors component specialists with uncooled microbolometer packaging expertise over legacy cooled-array manufacturers. Acquisition focus should center on firms with established BIS certification and offset agreement experience in Indian industrial corridors. Watch for EU dual-use regulation recalibration as the signal indicating liberalized cross-border component flow timing.| Strategic Initiative | Industry Significance |
|---|---|
| Indigenous Detector Manufacturing Partnership | Bharat Electronics and Tata Advanced Systems partnerships circumvent ITAR licensing bottlenecks for Indian procurement. |
| Software-Defined Sensor Fusion Development | Unified processing layers replace discrete hardware modules, compressing SWaP constraints for vehicle-mounted applications. |
| Strategic Mineral Stockpile Accumulation | Gallium and indium feedstock reserves buffer NATO defense industrial bases against Chinese export restrictions. |
| Laser Designation Module Technology Transfer | Offset agreements with Israeli suppliers enable local assembly under Make in India framework incentives. |
| Uncooled LWIR Volume Scale-Up | Vanadium oxide microbolometer yield improvements open border surveillance procurement previously reserved for military programs. |
Research Methodology
The analysis maps thermal imaging cores, targeting systems, night vision devices, and laser rangefinder sub-sectors, each validated through defense procurement officers, prime integrator program managers, focal plane array packaging engineers, and export control compliance specialists. Primary interview insights triangulate against ITAR classification databases, EU dual-use regulation amendments, Indian PLI scheme documentation, and customs trade records for rare earth mineral flows. Bottom-up segment sizing reconciles with top-down defense budget allocation analysis.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models technology type, product format, end-user category, and application mission profile as segmentation dimensions. CAGRs derive from defense procurement pipeline visibility, armored vehicle modernization program schedules, and indigenous manufacturing policy implementation trajectories. Forecast inputs incorporate mineral export restriction probability assessments and electro-optics engineering labor supply elasticity estimates.
Decision-makers should treat outputs as directional under assumptions of sustained ITAR classification stringency and PLI scheme continuity; material deviation would warrant model refresh. Revision becomes warranted when Chinese gallium and indium export restrictions cross thresholds that trigger NATO defense industrial base supply security responses.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Military Radar Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Infrared Anti-Sniper Detection Software Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
UXO Detection Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Europe Intelligence Surveillance and Reconnaissance Market
Military Surveillance
Military Body-Worn Camera Market