
 Loitering Munition System Market | 2026-2036
Loitering Munition System Market Size, Share, and Industry Trends Forecast 2026-2036
Loitering Munition System Market Analytics
The capability gap between vertically integrated primes and component-dependent suppliers is collapsing. Rheinmetall AG leverages captive propulsion and warhead production lines to compress development cycles. Elbit Systems Ltd. anchors its position through persistent R&D spending on autonomous target recognition. AeroVironment Inc. specializes in miniaturized platforms for dismounted infantry units, competing on deployment speed rather than payload mass.
A loitering munition system is an aerial weapon platform designed to orbit a target area for extended durations before executing precision strikes, typically incorporating electric propulsion, collapsible wings, and real-time data links for man-in-the-loop or autonomous engagement decisions. These systems serve military end users requiring discriminate firepower without risking manned aircraft or exposing forward artillery positions. Tactical munition and precision guided munition segments command the dominant margin pools due to higher unit values and integrated sensor packages. Mini UAV configurations represent the fastest-expanding category as platoon-level units demand portable, backpack-deployable strike assets. Deployment mode segmentation tilts toward ground-based launch systems, which reduce logistical footprints compared to airborne or naval alternatives.
The US Department of Defense operates under FAA and NHTSA coordination for domestic airspace integration testing, while export-controlled platforms face International Traffic in Arms Regulations licensing through the State Department. Israel's national defense regulator imposes strict end-use monitoring on systems from Israel Aerospace Industries and UVision, shaping regional transfer protocols. Stakeholders must monitor how evolving autonomous weapons conventions at the United Nations constrain rules-of-engagement software architectures and cross-border sales eligibility.
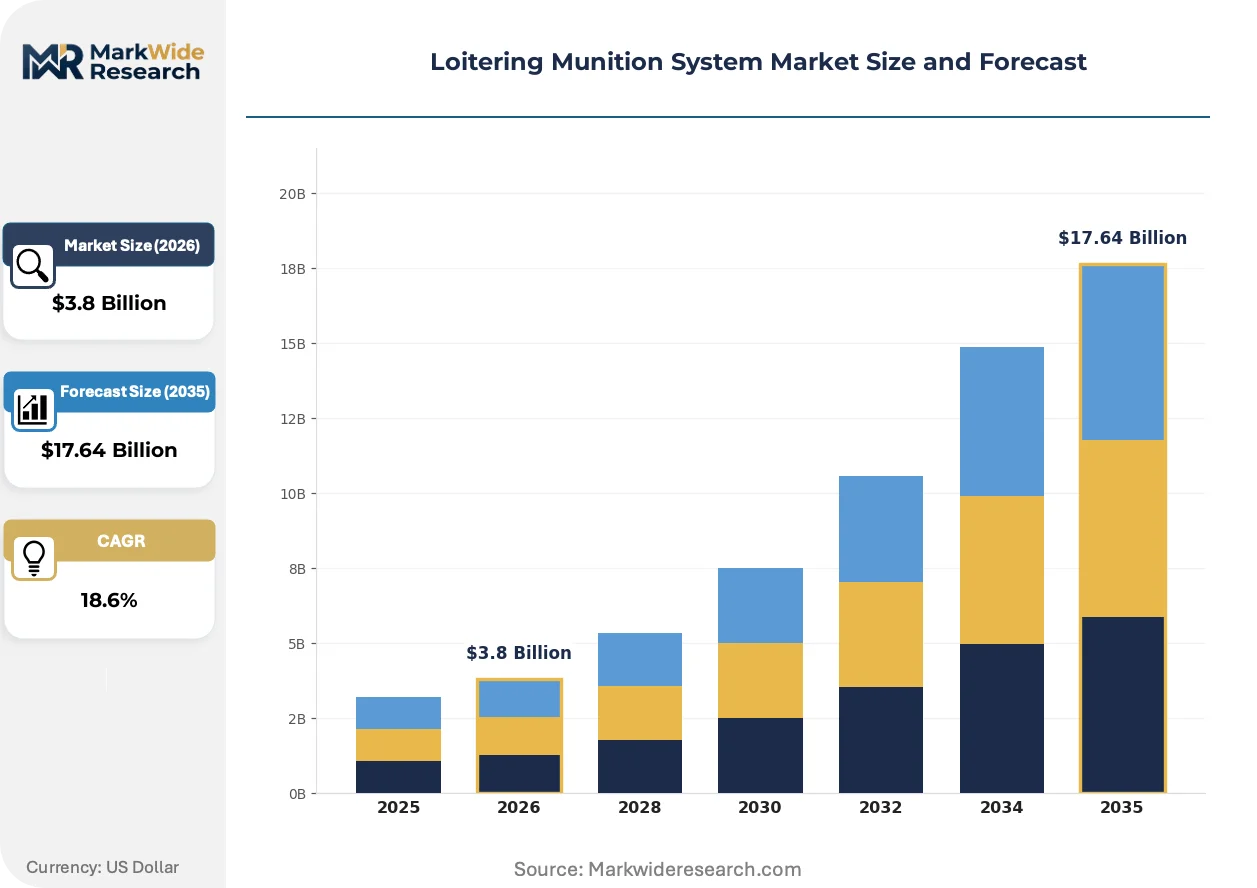
Market Dynamics
The loitering munition system market is being restructured by autonomous weapons governance frameworks that are rewriting certification requirements and cross-border transfer protocols faster than product development cycles can adapt.
Growth Catalysts
- EU AI Act compliance mandates:The European Union's risk-based AI classification system is accelerating investment in explainable target-recognition algorithms for systems exported to NATO allies.
- Battery energy density improvements:Solid-state lithium-sulfur cell chemistry is extending loiter times for electric-propulsion platforms beyond four hours in contested electromagnetic environments.
- Israeli defense cluster concentration:Tel Aviv-area engineering ecosystems maintain captive expertise in miniaturized seeker heads and collapsible wing structures, compressing prototype-to-deployment timelines.
Market Restraints
- Semiconductor supply concentration:Gallium nitride power amplifiers and radiation-hardened system-on-chip processors depend on single-source foundries in Taiwan and South Korea, creating chokepoint vulnerability.
- ITAR licensing friction:US State Department export controls impose multi-month review cycles on platforms with autonomous engagement capabilities, delaying allied procurement schedules.
- Substitute platform competition:Low-cost fixed-wing strike drones and precision-guided artillery shells compete for the same mission profiles at lower per-unit acquisition cost.
Strategic Opportunities
- Underpenetrated Southeast Asian procurement:Indonesia, Vietnam, and the Philippines lack indigenous loitering munition production and face maritime territorial disputes requiring distributed strike assets.
- Dual-use agricultural surveillance conversion:Crop-monitoring UAV airframes from commercial manufacturers can be adapted for military loitering roles with modular warhead integration kits.
- US Inflation Reduction Act domestic content incentives:Battery cell and electric motor production tax credits are enabling captive supply chain buildout for platforms assembled in Arizona and Texas.
Industry Challenges
- Autonomous systems ethics certification:Man-in-the-loop verification protocols and rules-of-engagement software auditing require specialized AI safety engineers in short supply across defense sectors.
- Legacy command-and-control integration:NATO STANAG 4586 interoperability standards demand costly middleware development to connect new loitering platforms with existing battlefield management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loitering Munition System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini UAV, Tactical Munition, Precision Guided Munition, Reconnaissance Drone Deployment Mode: Airborne, Ground-Based, Naval, Hybrid End User: Military, Defense Contractors, Security Agencies, Governmental Organizations Technology: Autonomous Navigation, Remote Control, AI Integration, Sensor Fusion |
| Companies Covered | Rheinmetall AG, Northrop Grumman Corporation, AeroVironment Inc., WB Group, Lockheed Martin, Elbit Systems Ltd., UVision, BAE Systems plc, Israel Aerospace Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loitering Munition System Market Evolving Landscape
Three converging forces are reshaping loitering munition architecture: distributed swarm coordination algorithms, hardened communication protocols for denied environments, and modular payload interfaces that decouple airframe from mission-specific sensor packages.
Swarm autonomy software is fragmenting the traditional single-operator-per-platform control model. Battalion-level units now field six-to-twelve vehicle formations coordinated through mesh networking protocols. Israeli and Australian forces have operationalized this approach in urban warfare training, compressing target engagement timelines from minutes to seconds while reducing electromagnetic signature exposure.
The EU AI Act's high-risk system classification is forcing architecture redesigns across European suppliers. Automated target classification algorithms must now maintain human-verifiable decision logs, adding firmware overhead but creating competitive differentiation for firms that achieve notified body certification first. German and French defense ministries are prioritizing compliant platforms in their procurement scoring matrices.
Buyer procurement patterns are consolidating around performance-based logistics contracts rather than discrete platform purchases. Middle Eastern and East Asian militaries now demand flight-hour guarantees and software update subscriptions bundled into multi-year agreements. This shift transfers operational risk to manufacturers while locking in recurring revenue streams and captive upgrade pathways.
Loitering Munition System Market Segmentation
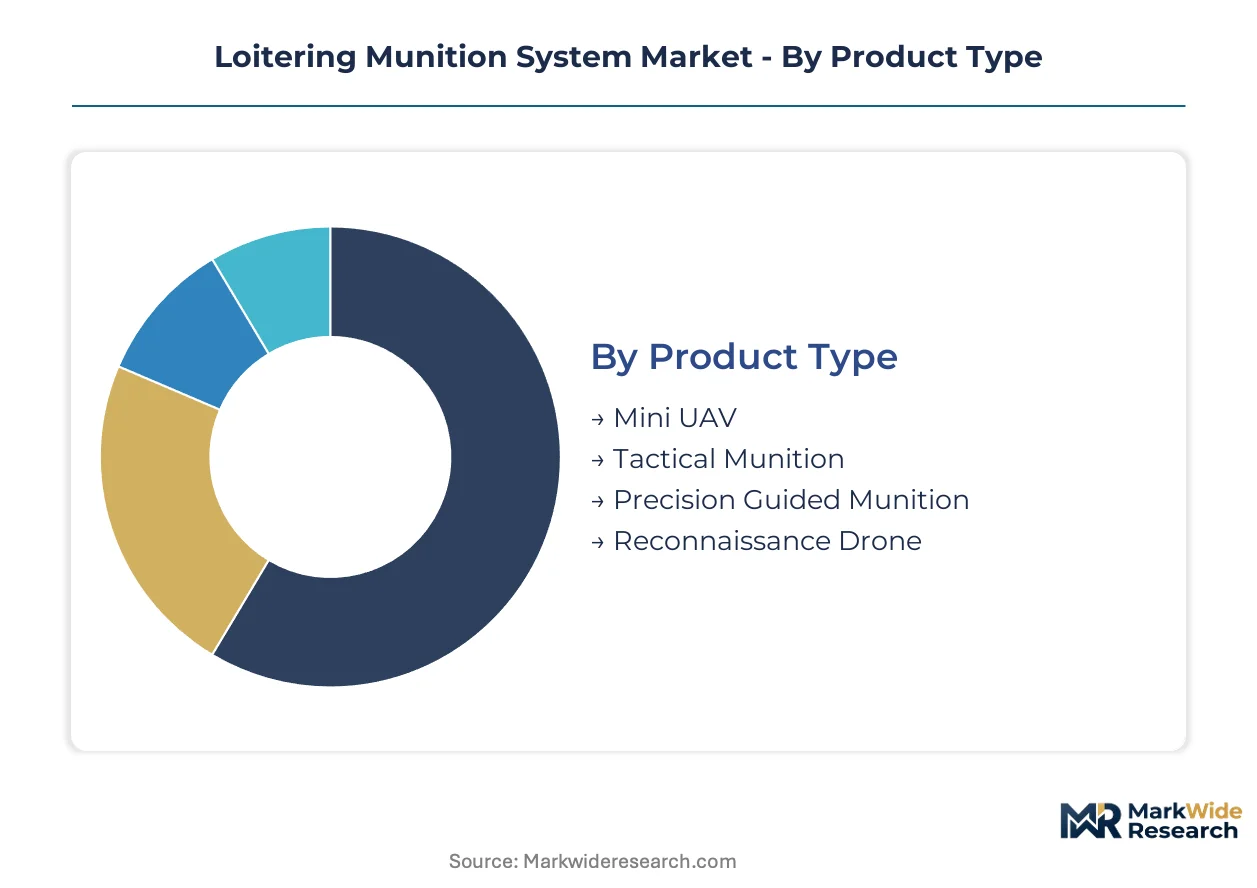
Segmentation in loitering munition systems reveals how procurement priorities diverge between mass-deployable infantry assets and integrated theater-level strike platforms. Margin distribution follows payload sophistication rather than unit volume, compressing supplier economics for commoditized categories.
Product Type:
Military procurement budgets concentrate value in platforms combining extended loiter endurance with discriminate warhead delivery, leaving reconnaissance-only configurations to compete on sensor integration contracts.
- Tactical Munition:Mid-range platforms carry unitary warheads between 5-15kg with electro-optical/infrared seekers for armored vehicle prosecution. Israel and US Marine expeditionary units drive procurement through distributed lethality doctrines requiring platoon-level fire support without artillery coordination delays.
- Precision Guided Munition:Heavy-class systems integrate synthetic aperture radar and laser designator compatibility for fixed-site interdiction. Air force procurement offices in Saudi Arabia and South Korea prioritize these for suppression of enemy air defense missions where collateral damage constraints apply.
- Mini UAV:Backpack-deployable systems under 15kg enable dismounted infantry to prosecute beyond-line-of-sight targets. Australian and Estonian land forces field these for urban reconnaissance-strike pairing.
- Reconnaissance Drone:Non-kinetic platforms optimized for target designation and battle damage assessment. Intelligence agencies in the Netherlands and Poland acquire these under separate sensor platform budgets.
Tactical Munition holds installed capacity. Precision Guided Munition is rotating up the share rankings.
Deployment Mode:
Logistics footprint and electromagnetic signature exposure determine deployment mode selection, with ground-based systems commanding procurement preference in contested access environments.
- Ground-Based:Vehicle-mounted or dismounted launchers using compressed air or solid-fuel boosters minimize forward operating base infrastructure. Ukrainian and Taiwanese ground forces prioritize these for rapid repositioning under counter-battery threat.
- Hybrid:Multi-domain launch compatibility from ground, rotary-wing, or small naval platforms. French and British expeditionary procurement offices specify these for littoral and amphibious operations.
- Airborne:Fixed-wing or rotary-wing launch integration extends range through parent aircraft kinematics. US Air Force Special Operations Command contracts dominate this niche.
- Naval:Ship-deck or submarine vertical launch integration for maritime strike. Japanese and Italian naval procurement maintains limited programs given deck space competition with defensive systems.
Ground-Based deployment holds installed capacity. Hybrid systems are climbing the fastest.
End User:
Contracting authority and operational risk tolerance segment end user demand, with military services capturing platform ownership while security agencies procure through service-level agreements.
- Military:Army, air force, and marine corps units with organic maintenance capabilities and rules-of-engagement authority. German, Norwegian, and Spanish defense ministries centralize procurement through national armaments directors.
- Defense Contractors:Private military companies and training support organizations acquiring under government lease arrangements. UAE and Nigerian security frameworks permit contractor-operated loitering coverage for critical infrastructure.
- Security Agencies:Border patrol and coast guard services with law enforcement constraints on lethal engagement. Finnish and Romanian agencies operate modified reconnaissance variants.
- Governmental Organizations:Civil protection and disaster response units repurposing commercial UAV airframes. Portuguese and Greek emergency management directorates maintain limited dual-use fleets.
Military end users hold installed capacity. Defense Contractors are gaining share fastest.
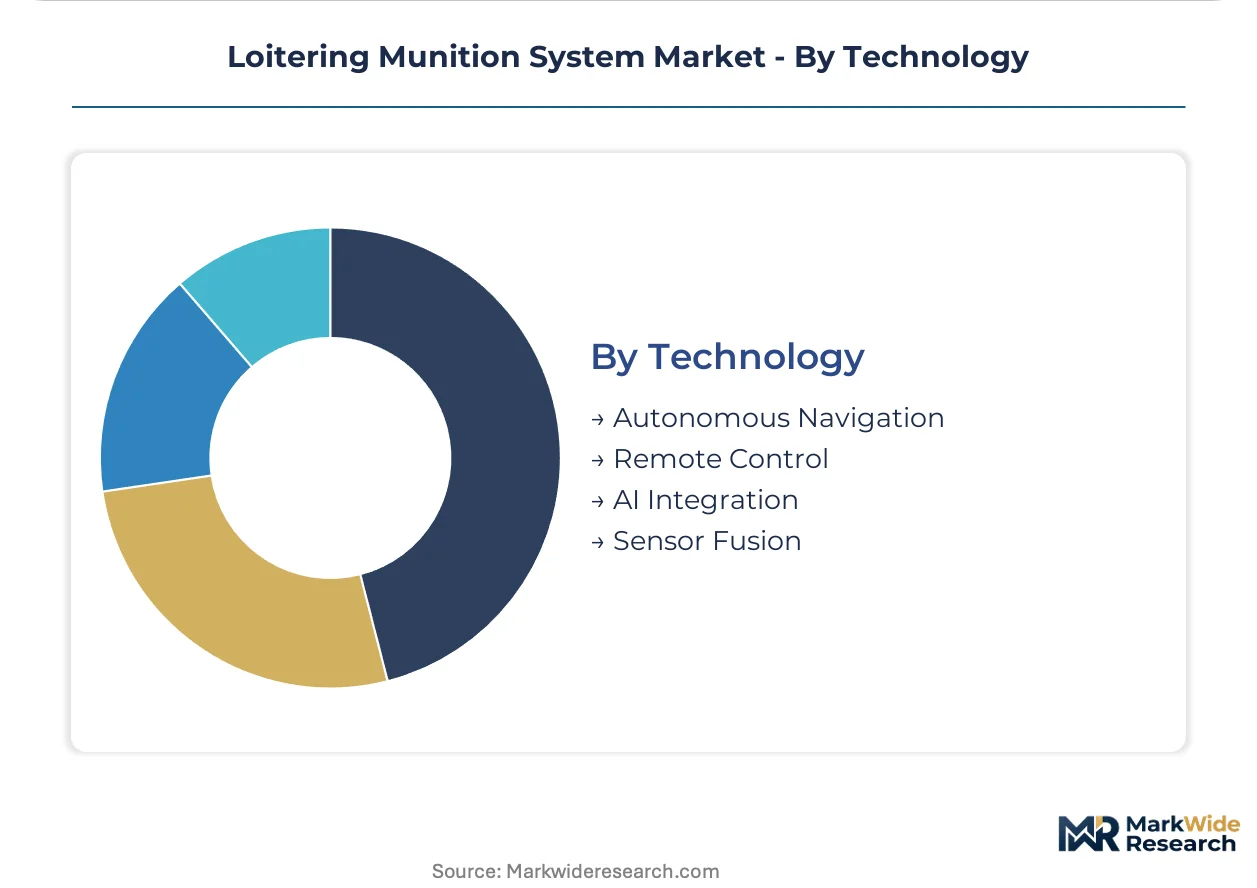
Technology:
Autonomy architecture sophistication determines certification pathway and export eligibility, with EU AI Act compliance creating tiered market access for European versus non-European suppliers.
- AI Integration:Machine learning-based target classification with human-verifiable decision logging for high-risk system certification. Rheinmetall and Saab development programs prioritize EU notified body approval.
- Sensor Fusion:Multi-spectral correlation across electro-optical, infrared, and signals intelligence feeds. Israeli and Australian forces operationalize these for denied-environment engagement.
- Autonomous Navigation:GPS-denied positioning through visual-inertial odometry and terrain-relative navigation. NATO STANAG 4661 compliance drives middleware requirements.
- Remote Control:Man-in-the-loop command retention with manual override protocols. Legacy platforms in Southeast Asian inventories rely on this architecture for regulatory simplicity.
Autonomous Navigation holds installed capacity. AI Integration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel deploys loitering munitions as primary precision-strike instruments for urban operations, whereas the United States integrates them as supplementary assets within layered air-ground task forces. Germany and South Korea emphasize man-in-the-loop retention for ethical compliance, while Australia prioritizes swarm-coordination for dispersed maritime scenarios.
United States
US Marine expeditionary units drive platoon-level procurement through distributed lethality doctrines requiring organic fire support without artillery coordination delays. The FAA and NHTSA coordinate domestic airspace integration testing under evolving unmanned systems guidelines. Arizona and Texas host emerging battery cell and electric motor production clusters capitalizing on Inflation Reduction Act tax credits.
Germany
The German defense ministry prioritizes EU AI Act-compliant platforms in procurement scoring matrices, demanding explainable target-recognition algorithms and human-verifiable decision logs. Rheinmetall AG leverages captive propulsion and warhead production lines in Düsseldorf-area facilities to compress development cycles. The national armaments director centralizes acquisition through performance-based logistics contracts.
Israel
Israeli ground forces operationalize swarm-coordination algorithms in urban warfare training, compressing target engagement timelines from minutes to seconds. The national defense regulator imposes strict end-use monitoring on systems from Tel Aviv-area engineering clusters, shaping regional transfer protocols. UVision and Israel Aerospace Industries anchor supply from established defense clusters supplying allied militaries.
Australia
Australian land forces field backpack-deployable mini UAV systems for urban reconnaissance-strike pairing in littoral operations. The national defense regulator mandates NATO STANAG 4586 interoperability standards for battlefield management system integration. Melbourne and Canberra host emerging middleware development clusters for command-and-control connectivity.
South Korea
South Korean air force procurement offices prioritize heavy-class precision guided munitions for suppression of enemy air defense missions with collateral damage constraints. The MFDS and national defense procurement agency coordinate certification requirements for autonomous engagement capabilities. Seoul-area engineering ecosystems concentrate expertise in miniaturized seeker heads and hardened communication protocols.
Loitering Munition System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the loitering munition system market. Vertically integrated primes with captive propulsion and warhead production lines compress development cycles faster than component-dependent suppliers can adapt. Two strategic archetypes dominate: established defense conglomerates with multi-domain portfolios, and focused specialists in miniaturized platforms or autonomous software architectures. Competitive moves concentrate on strategic partnerships for middleware development and portfolio diversification into performance-based logistics contracts.
Among Israeli specialists, UVision and Elbit Systems Ltd. exemplify the focused archetype with concentrated expertise in autonomous target recognition and collapsible wing structures. Rheinmetall AG represents the integrated European tier, leveraging in-house production capabilities across propulsion and warhead lines. AeroVironment Inc. occupies a position within the miniaturized platform segment, competing on deployment speed for dismounted infantry applications.
| Leading Market Players |
|---|
| Rheinmetall AG |
| Northrop Grumman Corporation |
| AeroVironment Inc. |
| WB Group |
| Lockheed Martin |
| Elbit Systems Ltd. |
| UVision |
| BAE Systems plc |
| Israel Aerospace Industries |
| Others |
Value Network & Pricing Analysis
Performance-based logistics contracts with multi-year flight-hour guarantees lock in supply access for prime contractors while compressing price visibility for component-dependent suppliers. Israeli and German defense ministries anchor these arrangements through national armaments directors, tethering battery cell and seeker head procurement to captive production lines in Tel Aviv-area and Düsseldorf-area facilities.
Pricing Analysis
Long-term offtake agreements dominate procurement between NATO defense ministries and vertically integrated primes. Price differentiation separates EU AI Act-certified platforms with explainable target-recognition algorithms from legacy man-in-the-loop systems. Cost compression in mini UAV tiers intensifies because commercial agricultural UAV manufacturers compete for military adaptation contracts. Security agencies exhibit highest price sensitivity due to law enforcement budget constraints, while air force procurement offices tolerate premium pricing for synthetic aperture radar integration.
Supply Chain Analysis
Inventory buffers for gallium nitride power amplifiers and radiation-hardened system-on-chip processors extend lead times beyond standard defense procurement cycles. Manufacturing concentrates in Taiwan, South Korea, and Israel for semiconductor components, with Germany and the United States hosting final assembly. Solid-state lithium-sulfur cell chemistry and collapsible wing structures feed from single-source foundries and captive engineering clusters. Single-source vulnerability in Taiwanese foundry capacity exposes platforms to electromagnetic component shortages. Distribution runs through government-to-government foreign military sales channels and direct commercial sales with ITAR licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
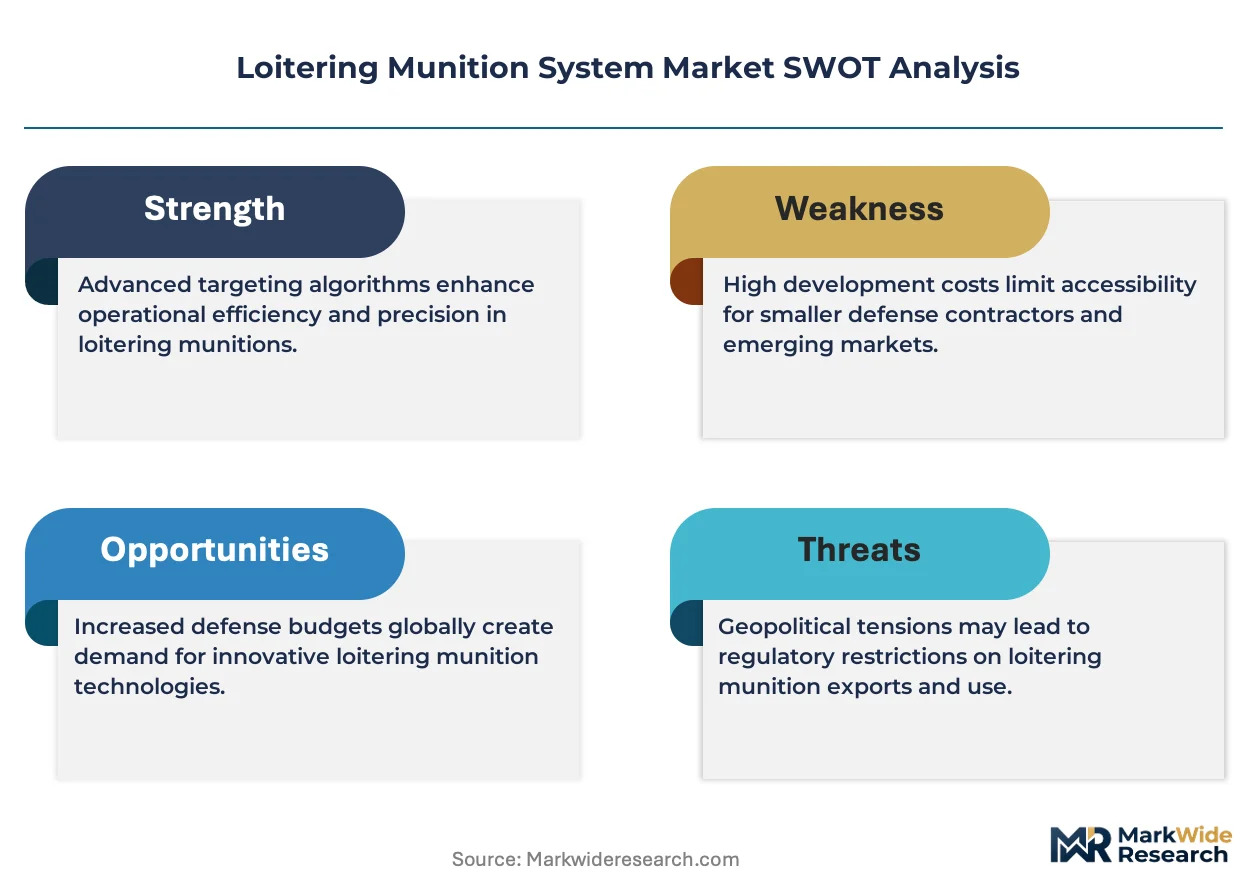
Precision-guided artillery shells and low-cost fixed-wing strike drones threaten loitering munition incumbents by competing for identical mission profiles at lower acquisition cost. Incumbents must navigate this substitution pressure through capability differentiation and supply chain control.
For Market Incumbents: Shield market position by deepening captive production of solid-state battery cells and miniaturized seeker heads in Arizona and Texas facilities capitalizing on IRA tax credits. Secure EU AI Act notified body certification ahead of competitors to lock in NATO procurement scoring advantages. Counter precision artillery substitution threats through bundled software update subscriptions that fixed-shell systems cannot replicate.
For New Entrants and Emerging Players: Lead with dual-use agricultural surveillance conversion kits targeting Indonesian, Vietnamese, and Philippine maritime security forces lacking indigenous production. Penetrate the underdeveloped Southeast Asian procurement corridor through modular warhead integration partnerships with established UAV airframe manufacturers. Position against Israeli and US primes by offering faster delivery timelines unencumbered by ITAR licensing friction.
For Investors and Strategic Acquirers: Focused autonomous software architects with STANAG 4586 middleware capabilities present acquisition targets with defensible moats. Long-term viability hinges on regulatory compliance differentiation as autonomous weapons conventions tighten. Watch for EU AI Act certification timelines as inflection indicators separating compliant platforms from export-restricted alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Explainable target-recognition algorithms unlock NATO procurement scoring advantages for Rheinmetall and Saab. |
| Captive Battery Supply Buildout | IRA tax credits enable in-house lithium-sulfur cell production in Arizona and Texas assembly clusters. |
| Middleware Development Partnership | STANAG 4586 interoperability standards demand costly battlefield management system integration for Australian forces. |
| Dual-Use Agricultural Conversion | Commercial crop-monitoring UAV airframes adapt for military roles through modular warhead kits for Southeast Asian markets. |
| Performance-Based Logistics Contracts | Multi-year flight-hour guarantees transfer operational risk to manufacturers while locking recurring revenue for Israeli primes. |
Research Methodology
Cross-validation between defense procurement officer interviews and ITAR licensing database analysis anchors the qualitative findings in documented regulatory constraints. Primary discussions with program managers at national armaments directorates, autonomous systems ethics certification engineers, battlefield management system integration specialists, and foreign military sales compliance officers combined with secondary validation through FAA unmanned systems guidelines, EU AI Act regulatory texts, NATO STANAG documentation, and State Department export control filings. Bottom-up platform deployment estimates and top-down defense budget allocation triangulation ensure methodological rigor.
Sensitivity analysis around autonomous weapons convention adoption timelines and semiconductor supply disruption scenarios tests forecast robustness across the projection horizon. Segmentation modeling incorporates platform weight class, deployment mode logistics footprint, end-user contracting authority, and autonomy architecture sophistication. CAGRs derive from deployment trajectory analysis and procurement pipeline visibility. Solid-state battery energy density improvement curves and swarm-coordination algorithm maturation serve as key technology input variables.
The analysis sits within stated boundaries; outcomes outside ITAR licensing reform or EU AI Act enforcement intensity would require recalibration. Forecasts reflect assumptions about regulatory stability and allied procurement continuity. Classification algorithm auditing requirements and gallium nitride foundry capacity constraints represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Rotary-Wing Lidar Drone Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
Unmanned Systems Market