
 Middle East and Africa Unmanned Surface Vehicle (USV) Market | 2026-2036
Middle East and Africa Unmanned Surface Vehicle (USV) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Unmanned Surface Vehicle (USV) Market Foresight
Naval engineering talent pools across the Arabian Peninsula are rotating toward autonomous maritime systems as defense budgets realign from crewed patrol craft. Rafael Advanced Defense Systems leverages its combat-proven unmanned platforms to anchor Israeli naval dominance in the Eastern Mediterranean. Elbit Systems sustains technology leadership through integrated sensor-to-shooter architectures for littoral missions. ECA Group competes aggressively in North African waters with mine-countermeasure USV configurations tailored to regional naval requirements.
An unmanned surface vehicle operates as a self-propelled craft traversing water without embarked human operators, typically spanning two to twelve meters in hull length and integrating gyro-stabilized sensor masts with satellite communication relays for beyond-line-of-sight command. These platforms execute military reconnaissance, hydrographic survey, and environmental monitoring missions where crew exposure to hostile or hazardous conditions proves unacceptable. The autonomous product type dominates procurement pipelines across Middle Eastern naval forces, while AI-based technology segments attract disproportionate R&D allocation as machine-learning collision avoidance and swarm coordination capabilities mature from experimental to operational status. Research applications within the application dimension remain nascent but command premium pricing due to specialized payload integration requirements.
Israel's Ministry of Defense and South Africa's National Regulator for Compulsory Specifications shape operational certification pathways, with the former mandating cybersecurity hardening for networked unmanned fleets and the latter drafting seaworthiness standards for commercial survey deployments. The UAE's General Civil Aviation Authority and telecommunications regulators coordinate spectrum allocation for maritime control links, creating de facto entry barriers for non-compliant platform vendors. Stakeholders must monitor evolving sovereign data-localization requirements that could fragment cloud-based fleet management architectures across Red Sea and Gulf jurisdictions.
Market Dynamics
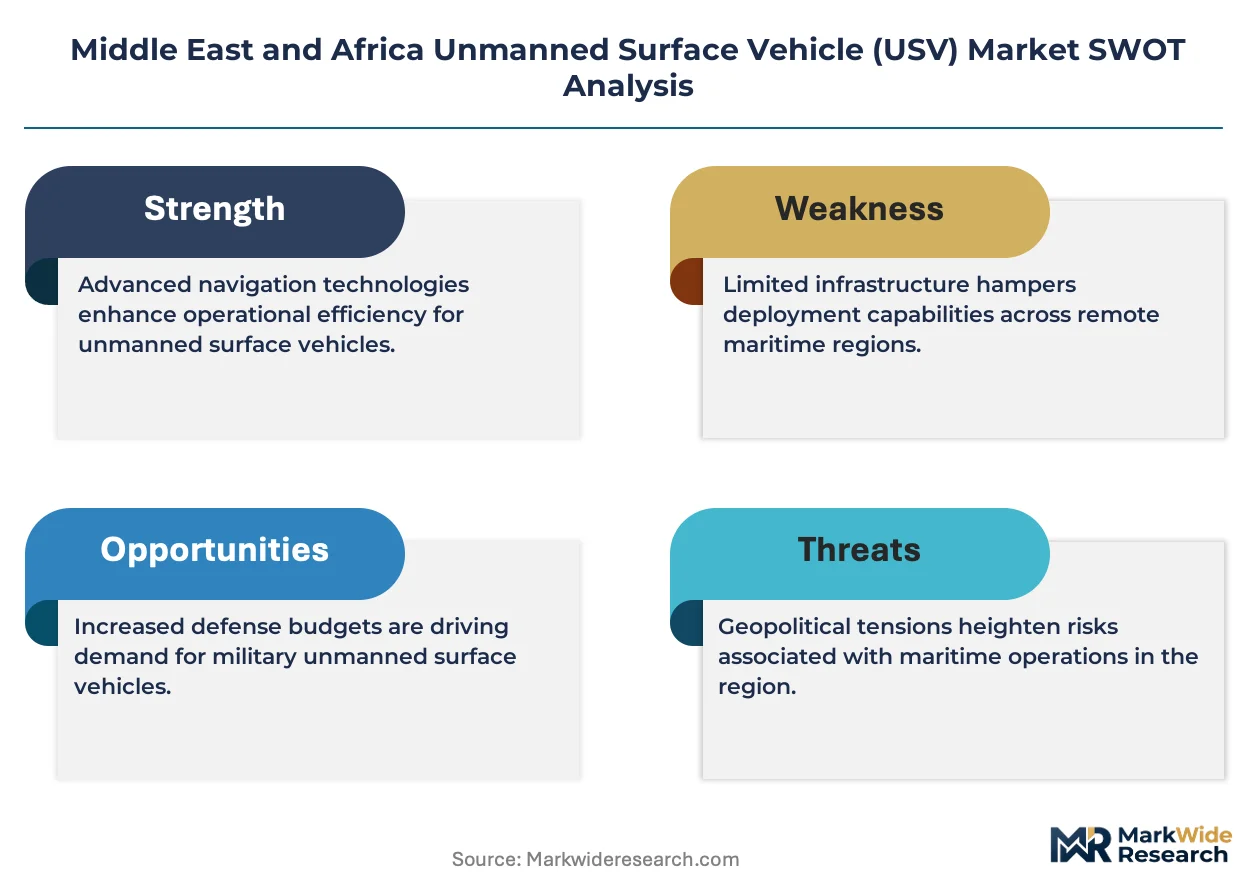
Autonomous collision-avoidance algorithms are compressing procurement cycles for Gulf naval forces, forcing legacy platform vendors to re-architect control systems or exit contested tenders. This technological inflection is redistributing contract awards toward systems integrators with proven AI validation pipelines.
Growth Catalysts
- Gulf naval modernization mandates:Saudi Arabia's General Authority for Defense Development prioritizes unmanned patrol craft in coastal security frameworks, creating sustained demand pull for autonomous surface platforms with integrated electronic warfare suites.
- Anti-submarine warfare automation:Hull-mounted sonar arrays coupled with machine-learning target classification are displacing crewed corvettes for shallow-water acoustic surveillance across Red Sea chokepoints.
- Environmental monitoring directives:South Africa's Department of Forestry, Fisheries and the Environment funds Benguela Current ecosystem mapping using long-endurance USV swarms, expanding civilian application pipelines.
Market Restraints
- Lithium-ion battery supply concentration:Cell production for maritime energy storage clusters in East Asian manufacturing hubs, exposing African and Middle Eastern integrators to input cost volatility and extended lead times.
- Spectrum allocation fragmentation:The UAE's telecommunications regulator and Israel's Ministry of Defense maintain incompatible frequency bands for beyond-line-of-sight command links, complicating cross-border fleet operations.
- Crewed vessel substitution economics:Manned patrol craft with amortized hulls and established maintenance networks retain cost advantages for low-intensity missions, slowing autonomous replacement cycles.
Strategic Opportunities
- Mine countermeasure modernization:North African navies lacking dedicated mine warfare vessels present white-space demand for towed-array USV configurations with synthetic aperture sonar.
- Dual-use hydrographic survey:Convergence of multibeam bathymetry payloads with autonomous navigation enables oil and gas operators to repurpose naval-specification platforms for subsea infrastructure inspection.
- Data localization requirements:Saudi Arabia's cloud computing regulations mandate sovereign fleet data storage, creating first-mover advantage for domestic platform-as-a-service providers with compliant ground stations.
Industry Challenges
- Maritime autonomy software certification:Israel's Ministry of Defense and South Africa's National Regulator for Compulsory Specifications maintain divergent validation protocols for collision-avoidance algorithms, forcing vendors to maintain parallel codebases.
- Sensor-to-shooter integration complexity:Naval customers demand seamless handoff between USV-collected intelligence and crewed firing platforms, requiring proprietary data link architectures that resist interoperability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Unmanned Surface Vehicle (USV) Market |
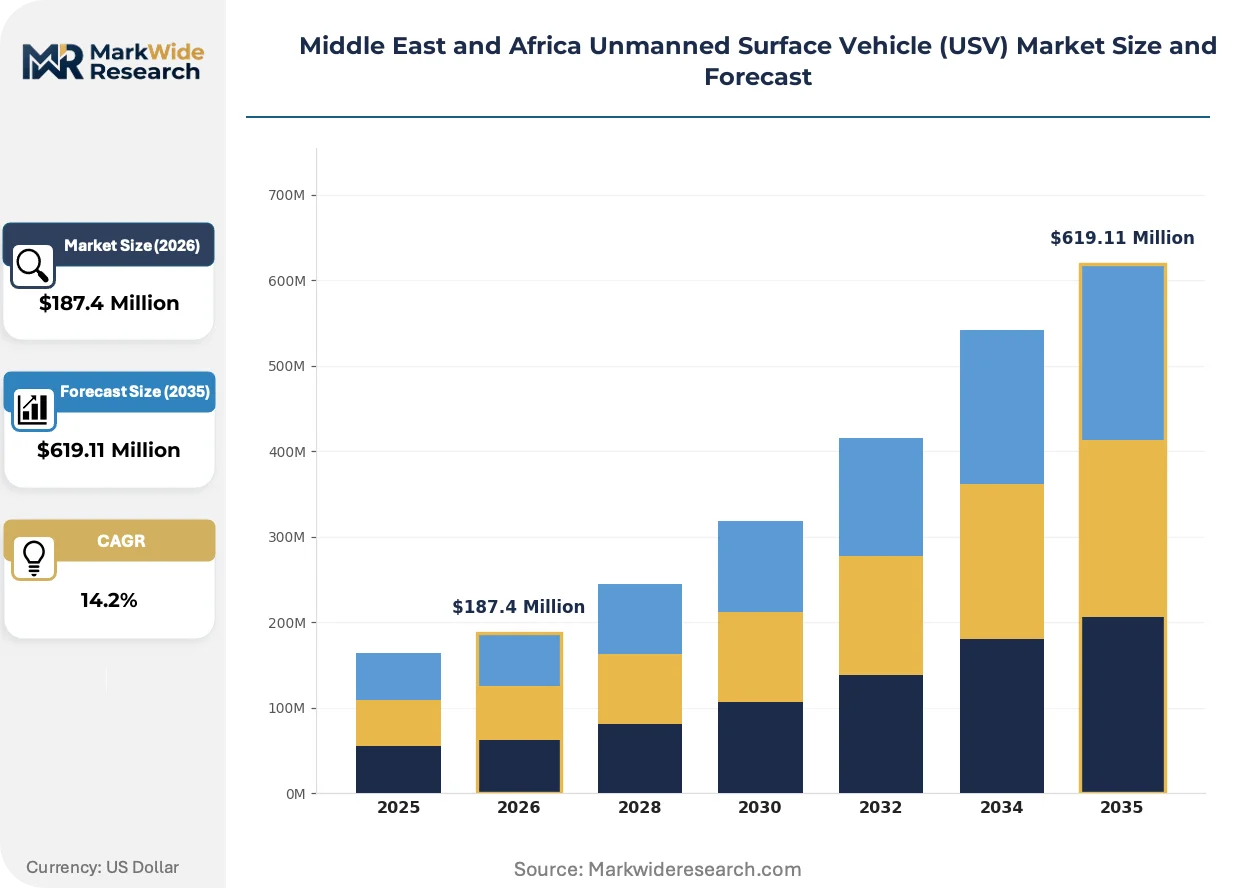
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous, Remote-Controlled, Hybrid, Security Application: Surveillance, Research, Defense, Transportation End User: Military, Commercial, Government, Research Institutions Technology: Navigation, Communication, Sensor Integration, AI-Based |
| Companies Covered | Teledyne Marine, ECA Group, L3Harris Technologies, OceanAlpha Group Limited, Sea Machines Robotics, Rafael Advanced Defense Systems, Elbit Systems, Maritime Robotics AS, ASV Global, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Unmanned Surface Vehicle (USV) Market Shifts & Advancements
Artificial intelligence architectures are fragmenting traditional platform hierarchies, compressing development timelines and enabling mission-specific payload reconfiguration without hull redesign. This shift is redrawing competitive boundaries between hardware fabricators and software-centric systems integrators.
Modular payload architectures are decomposing the monolithic USV procurement model that dominated early adoption phases. Israeli naval forces now specify containerized sensor suites that swap between mine-hunting, signals intelligence, and surface warfare configurations within port maintenance windows. This flexibility is compressing vendor margins on dedicated hull production while expanding recurring revenue from software-defined mission modules.
South Africa's National Regulator for Compulsory Specifications is finalifying seaworthiness certification pathways for autonomous surface craft operating beyond visual line of sight. The framework mandates redundant propulsion systems and failsafe return-to-base protocols for commercial survey deployments. Environmental monitoring contractors operating in Benguela Current zones are accelerating platform qualification to secure research funding tranches tied to regulatory compliance deadlines.
Leasing structures for autonomous maritime assets are displacing capital purchase models among African oceanographic institutions with constrained procurement budgets. South Africa's Council for Scientific and Industrial Research now contracts platform-hours rather than acquiring hulls, transferring obsolescence risk to operators with fleet-scale maintenance capabilities. This consumption pattern is most visible in Cape Town's marine technology cluster, where shared-asset pools reduce individual research unit capital commitments by over sixty percent.
Middle East and Africa Unmanned Surface Vehicle (USV) Market Segmentation
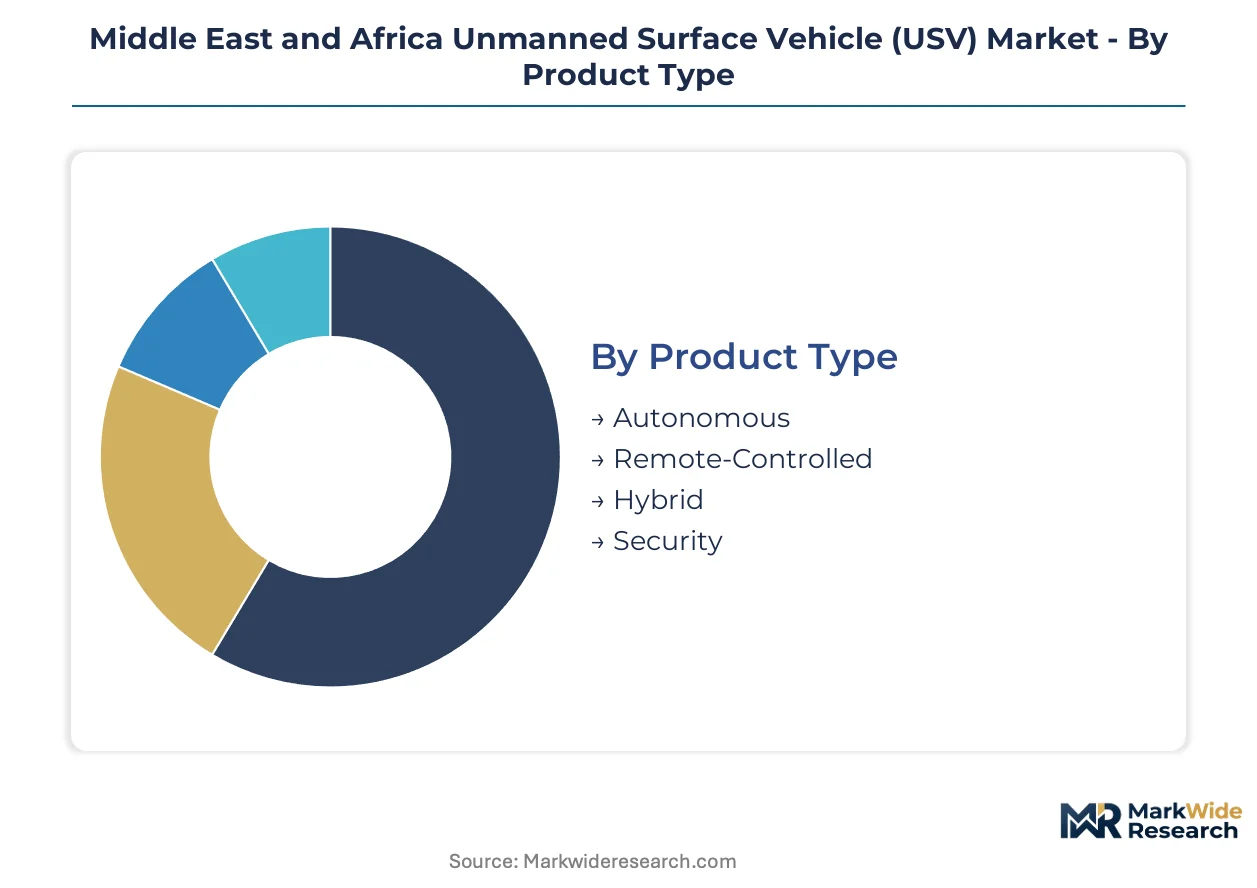
USV procurement patterns across Middle Eastern and African waters fragment sharply by operational autonomy level and mission payload, with defense budgets favoring systems that reduce crew exposure in contested maritime zones. Commercial operators prioritize modular architectures that pivot between hydrographic survey and subsea infrastructure inspection without hull redesign.
Product Type:
Autonomous platforms face intensifying substitution pressure from hybrid configurations that retain manual override for contested littoral operations where electronic warfare degrades machine-learning navigation.
- Autonomous:Self-directed vessels execute collision-avoidance maneuvers through onboard sensor fusion without human intervention. Gulf naval forces concentrate procurement for Red Sea chokepoint patrol, though Israel's Ministry of Defense mandates cybersecurity hardening that extends validation timelines.
- Remote-Controlled:Operator-tethered craft traverse water under continuous beyond-line-of-sight command via satellite relay links. South Africa's oceanographic institutions dominate demand for Benguela Current ecosystem monitoring where failsafe human judgment trumps algorithmic decision-making.
- Hybrid:Dual-mode architectures toggle between autonomous waypoint navigation and manual override for harbor approaches. Oil and gas operators in UAE waters favor this flexibility for subsea pipeline inspection where regulatory compliance demands human accountability.
- Security:Hardened hull configurations with integrated electronic warfare suites patrol coastal perimeters against asymmetric threats. Saudi Arabia's General Authority for Defense Development prioritizes these platforms for critical infrastructure protection.
Remote-Controlled anchors the volume base while Autonomous gains share at the steepest rate.
Application:
Defense missions command premium pricing per hull, yet research contracts generate recurring revenue through long-term platform leasing that transfers obsolescence risk to fleet-scale operators.
- Surveillance:Persistent maritime domain awareness missions integrate gyro-stabilized electro-optical masts with automatic identification system correlation. GCC coastal security frameworks drive procurement for 24-hour patrol coverage without crew fatigue limitations.
- Research:Environmental monitoring deployments carry multibeam bathymetry and water-column sampling payloads. South Africa's Council for Scientific and Industrial Research contracts platform-hours rather than acquiring hulls, reducing capital commitments through shared-asset pools.
- Defense:Mine countermeasure and anti-submarine warfare configurations deploy towed-array sonar with machine-learning target classification. North African navies lacking dedicated mine warfare vessels present white-space demand for synthetic aperture sonar integration.
- Transportation:Cargo-carrying surface craft experiment with last-mile logistics for offshore platforms. Commercial viability remains constrained by payload-to-range ratios and regulatory uncertainty over autonomous shipping lanes.
Defense commands the highest unit economics while Research expands most quickly through consumption-based contracting models.
End User:
Military procurement cycles stretch 18-36 months with stringent certification requirements, whereas commercial operators prioritize rapid deployment through leasing structures that bypass capital approval processes.
- Military:Naval forces specify integrated sensor-to-shooter architectures for littoral dominance. Rafael Advanced Defense Systems and Elbit Systems anchor Israeli naval procurement with combat-proven platforms validated for Eastern Mediterranean operations.
- Commercial:Oil and gas operators repurpose naval-specification hulls for subsea infrastructure inspection. UAE-based energy majors demand seamless handoff between survey data and maintenance scheduling systems.
- Government:Coast guard and border security agencies patrol exclusive economic zones with medium-endurance craft. Saudi Arabia's cloud computing regulations mandate sovereign fleet data storage, favoring domestic platform-as-a-service providers.
- Research Institutions:Academic and oceanographic organizations map marine ecosystems with long-endurance swarms. South Africa's National Regulator for Compulsory Specifications finalizes seaworthiness certification for beyond-visual-line-of-sight operations.
Military absorbs the largest absolute investment while Research Institutions achieve the steepest adoption curve through regulatory compliance deadlines tied to funding tranches.
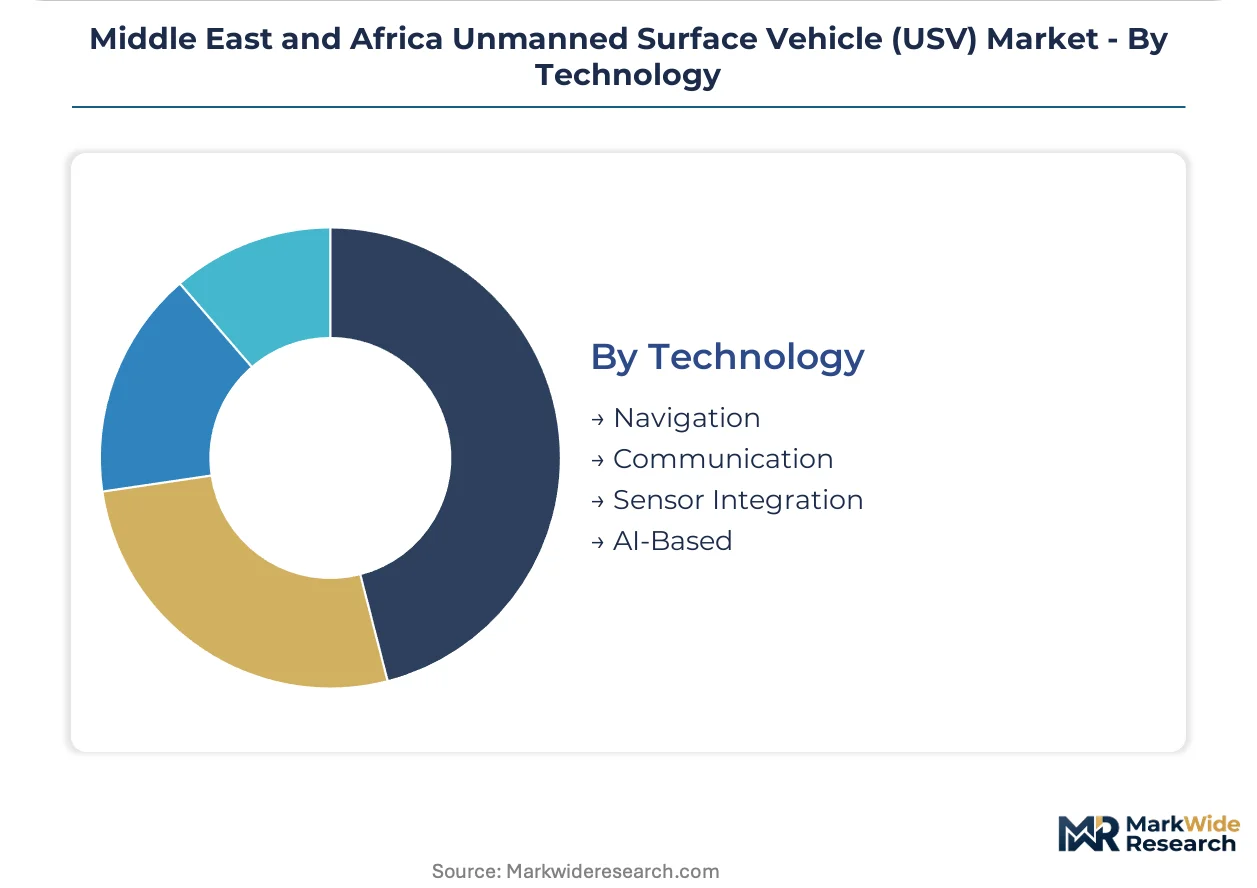
Technology:
AI-Based architectures redistribute competitive advantage toward software-centric integrators, compressing margins for hardware fabricators unable to validate machine-learning pipelines.
- Navigation:Inertial measurement units fused with GNSS correction enable precise station-keeping in GPS-denied environments. Israel's Ministry of Defense mandates redundant positioning for networked unmanned fleets.
- Communication:Satellite relay links and mesh networking protocols maintain command continuity across Red Sea and Gulf jurisdictions. Spectrum allocation fragmentation between UAE and Israeli regulators complicates cross-border fleet operations.
- Sensor Integration:Modular payload architectures swap mine-hunting, signals intelligence, and surface warfare configurations within port maintenance windows. Israeli naval forces specify containerized sensor suites that compress vendor margins on dedicated hull production.
- AI-Based:Machine-learning collision avoidance and swarm coordination capabilities mature from experimental to operational status. Gulf naval modernization mandates prioritize validated AI pipelines that displace legacy control systems in contested tenders.
Navigation provides the foundational capability layer while AI-Based climbs the fastest as procurement cycles compress for algorithmically-enabled platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Israeli and UAE procurement channels while South African research institutions negotiate from constrained budget positions. Gulf naval modernization programs absorb premium hull configurations at rates unavailable to African oceanographic operators. This asymmetry fragments vendor go-to-market strategies across the analysis window.
Israel
Rafael Advanced Defense Systems and Elbit Systems anchor domestic production for Eastern Mediterranean patrol missions. The Ministry of Defense mandates cybersecurity hardening for networked unmanned fleets, extending validation timelines for AI-based collision avoidance. Haifa's naval technology cluster concentrates combat-proven platform development with integrated sensor-to-shooter architectures.
United Arab Emirates
Oil and gas operators repurpose naval-specification hulls for subsea pipeline inspection in UAE waters. The General Civil Aviation Authority coordinates spectrum allocation for maritime control links with telecommunications regulators, creating de facto entry barriers for non-compliant vendors. Abu Dhabi's energy corridor drives dual-use procurement that converges defense and commercial survey requirements.
Saudi Arabia
The General Authority for Defense Development prioritizes unmanned patrol craft for coastal security frameworks and critical infrastructure protection. Cloud computing regulations mandate sovereign fleet data storage, favoring domestic platform-as-a-service providers with compliant ground stations. Riyadh's defense procurement complex channels sustained demand for autonomous surface platforms with electronic warfare suites.
South Africa
The Council for Scientific and Industrial Research contracts platform-hours rather than acquiring hulls, reducing capital commitments through shared-asset pools in Cape Town's marine technology cluster. The National Regulator for Compulsory Specifications finalizes seaworthiness certification for beyond-visual-line-of-sight operations, tying funding tranches to regulatory compliance deadlines. Benguela Current ecosystem monitoring drives civilian application pipelines with long-endurance USV swarms.
Egypt
North African navies lacking dedicated mine warfare vessels present white-space demand for towed-array USV configurations with synthetic aperture sonar. Maritime security partnerships with Gulf Cooperation Council members influence procurement specifications for Red Sea chokepoint patrol. Alexandria's naval base complex hosts evaluation programs for mine-countermeasure platforms tailored to regional shallow-water requirements.
Middle East and Africa Unmanned Surface Vehicle (USV) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa USV market. Israeli and European systems integrators dominate premium defense procurement with validated AI pipelines, while Asian fabricators compete on hull production economics for commercial survey deployments. The vendor base stratifies into three tiers: combat-proven defense specialists, modular payload integrators, and scale-driven hull manufacturers. Competitive moves concentrate on strategic partnerships for local assembly rights and technology licensing to satisfy data-localization mandates.
Among defense-centric specialists, Rafael Advanced Defense Systems and Elbit Systems exemplify the technology-leadership archetype with combat validation in Eastern Mediterranean operations. ECA Group occupies a position within the modular payload tier, competing aggressively in North African waters with mine-countermeasure configurations. These three anchors represent divergent strategic positioning: Israeli firms leverage integrated sensor-to-shooter architectures, while the French specialist pursues regional customization for navies lacking dedicated mine warfare vessels.
| Leading Market Players |
|---|
| Teledyne Marine |
| ECA Group |
| L3Harris Technologies |
| OceanAlpha Group Limited |
| Sea Machines Robotics |
| Rafael Advanced Defense Systems |
| Elbit Systems |
| Maritime Robotics AS |
| ASV Global |
| Others |
Supply & Pricing Matrix
Israel's Ministry of Defense cybersecurity hardening mandates for networked unmanned fleets simultaneously gate supply qualification and create price differentiation between compliant and non-compliant platform vendors. This regulatory architecture concentrates pricing power among systems integrators with validated AI pipelines while compressing margins for hardware fabricators lacking certification infrastructure.
Pricing Analysis
Gulf naval procurement channels command premium hull configurations at rates unavailable to South African research institutions negotiating from constrained budget positions. Three-tier pricing structure across premium, standard, and economy levels separates combat-validated defense platforms from commercial survey configurations and basic remote-controlled craft. Cost compression in the standard tier is intensifying because Asian fabricators compete aggressively on hull production economics. Commercial oil and gas operators exhibit highest price sensitivity, while military end-users prioritize capability over unit cost.
Supply Chain Analysis
Strategic stockpiling of lithium-ion battery cells dominates inventory strategy as maritime energy storage production clusters in China, South Korea, and Japan. USV manufacturing draws from East Asian cell suppliers, European sensor integrators, and Israeli software validation specialists. Single-source vulnerability in battery supply exposes African and Middle Eastern integrators to input cost volatility. Distribution runs through defense procurement complexes in Riyadh and Abu Dhabi for military platforms, and through shared-asset pools in Cape Town for research deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined mission modules and platform-as-a-service contracting expand faster than hardware sales, transforming vendor economics toward recurring revenue architectures. This service-attach opportunity rewards operators with fleet-scale maintenance capabilities and compliant ground station infrastructure.
For Market Incumbents: Compound technology leadership through integrated sensor-to-shooter architectures that resist interoperability standards demanded by naval customers. Invest in redundant certification pipelines for Israel's Ministry of Defense and South Africa's National Regulator for Compulsory Specifications to preempt parallel codebase maintenance. Capacity addition in compliant ground stations within Saudi Arabia satisfies data-localization mandates before domestic competitors establish platform-as-a-service dominance.
For New Entrants and Emerging Players: After-sales software maintenance gaps among legacy platform vendors present white-space demand for AI validation and cybersecurity hardening services. North African navies lacking dedicated mine warfare vessels offer the most penetrable defense segment for towed-array USV configurations. Pursue technology licensing partnerships with established systems integrators to bypass extended procurement cycles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular payload specialists with regional customization capabilities but limited AI validation infrastructure. Long-term viability hinges on software-centric competitive positioning as hardware margins compress. The signal to watch is Gulf naval tender awards shifting toward algorithmically-enabled platforms with proven collision-avoidance validation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Validation Pipeline Investment | Israel's Ministry of Defense mandates compress procurement cycles toward algorithmically-proven platforms. |
| Domestic Ground Station Buildout | Saudi cloud computing regulations favor platform-as-a-service providers with sovereign data storage. |
| Mine-Countermeasure Configuration Licensing | Egypt's naval base complex evaluates towed-array platforms for Red Sea chokepoint requirements. |
| Shared-Asset Pool Partnership | South Africa's Council for Scientific and Industrial Research contracts platform-hours rather than hull acquisitions. |
| Spectrum Allocation Coordination | UAE telecommunications regulators create entry barriers for non-compliant maritime control link vendors. |
Research Methodology
The analysis maps autonomous navigation systems, remote-controlled platforms, hybrid architectures, and security-hardened configurations, each validated through naval procurement officers, defense systems integrators, oceanographic research directors, and maritime regulatory specialists. Primary interviews with platform engineers and fleet operations managers combined with secondary validation from customs trade data, defense procurement disclosures, and telecommunications spectrum allocation records. Bottom-up hull deployment counts triangulate against top-down defense budget allocations across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs through cross-referencing with national defense modernization programs and research funding tranches. The analytical framework models product type, application mission, end-user category, and technology architecture throughout the forecast period. CAGRs derive from deployment trajectory analysis and procurement cycle compression patterns, incorporating AI maturation timelines and regulatory compliance deadlines as industry-specific inputs.
Forecasts assume regulatory continuity in Israeli cybersecurity mandates, South African seaworthiness certification pathways, and Saudi data-localization requirements; material policy shifts would require re-modeling. Specific risks include spectrum allocation fragmentation between UAE and Israeli regulators, lithium-ion supply concentration disruptions, and crewed vessel substitution economics slowing autonomous replacement cycles. Revision becomes warranted when AI validation timelines compress or diverge across certification regimes beyond modeled thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Armored Unmanned Underwater Vehicle Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
Military Autonomous Robot Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Asia-Pacific Unmanned Systems Market
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
Subsea Navigation and Tracking Market
Unmanned Systems
Drone Battery System Market