
 Unmanned Systems Market | 2026-2036
Unmanned Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Systems Market Analytics
Israeli defense contractors is repositioning unmanned aerial platform production toward NATO-standard interoperability. Northrop Grumman Corporation leverages advanced autonomous flight systems for high-altitude surveillance missions. Lockheed Martin Corporation anchors its portfolio in integrated command-and-control architectures for multi-domain operations. General Atomics Aeronautical Systems specializes in turboprop-powered persistent ISR platforms with satellite communications relay.
Unmanned systems encompass autonomous or remotely piloted vehicles operating without human occupants, typically integrating airframes with sensor payloads, data links, and ground control stations achieving flight endurance exceeding 24 hours for certain classes. These platforms perform intelligence collection, precision strike, cargo delivery, and infrastructure inspection across contested and civilian environments. UAV product types currently dominate procurement volumes while UGV segments gain traction in explosive ordnance disposal and perimeter security applications. AI technology layers are attracting disproportionate R&D investment as navigation and communication modules mature into commoditized subsystems. Military end users command the largest budget allocation though commercial logistics applications show the steepest trajectory change.
The FAA regulates civil unmanned operations through Part 107 and emerging beyond-visual-line-of-sight frameworks that determine commercial market access timelines. The Department of Defense mandates MIL-STD-810 environmental testing and STANAG interoperability protocols for allied platform integration. The EPA and OSHA impose operational constraints on industrial UAV deployment for facility inspection and emissions monitoring. Stakeholders must track regulatory divergence between civilian certification pathways and defense procurement standards as dual-use platform architectures reshape supplier qualification requirements.
Market Dynamics
The FAA's beyond-visual-line-of-sight rulemaking is compressing commercial UAV corridor deployment timelines while NATO defense procurement accelerates platform standardization demands, creating dual-track pressure on supplier qualification systems.
Growth Catalysts
- STANAG Interoperability Mandates:NATO allies now require unified command-and-control protocols for allied fleet integration, forcing defense contractors toward modular open architectures.
- AI-Enabled Autonomy Layers:Machine vision and edge computing integration reduces operator burden for persistent ISR missions, expanding mission endurance thresholds.
- Industrial Facility Inspection:OSHA-permitted UAV deployment for emissions monitoring and stack inspection opens regulated utility end-uses previously blocked by safety protocols.
Market Restraints
- Sensor Payload Cost Concentration:Electro-optical and synthetic aperture radar modules constitute disproportionate platform cost, with supply concentrated among specialized defense subcontractors.
- Dual-Use Export Control Friction:ITAR and MTCR restrictions complicate cross-border component flows for turboprop propulsion and encrypted data link systems.
- Satellite Bandwidth Bottlenecks:Beyond-line-of-sight operations depend on contested Ku-band and Ka-band relay capacity, limiting concurrent mission density.
Strategic Opportunities
- Urban Air Mobility Corridors:FAA-designated commercial UAV routes in Dallas-Fort Worth and Reno create testbed infrastructure for cargo delivery scaling.
- Explosive Ordnance Disposal Ground Vehicles:UGV platforms for route clearance and perimeter security remain underpenetrated relative to aerial system procurement volumes.
- EU Green Deal Inspection Mandates:CSRD-aligned emissions verification requirements accelerate industrial UAV adoption for flare stack and pipeline monitoring across member states.
Industry Challenges
- Autonomy Software Certification:DO-178C and equivalent airworthiness standards for AI-driven flight control impose 18-36 month validation timelines.
- Multi-Domain Integration Complexity:Army Futures Command requirements for seamless handoff between aerial and ground unmanned assets strain legacy C2 architecture compatibility.
- Supply Chain Reconfiguration:Rare earth magnet and lithium-thionyl chloride battery sourcing constraints force redesign of propulsion and power subsystem specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Systems Market |
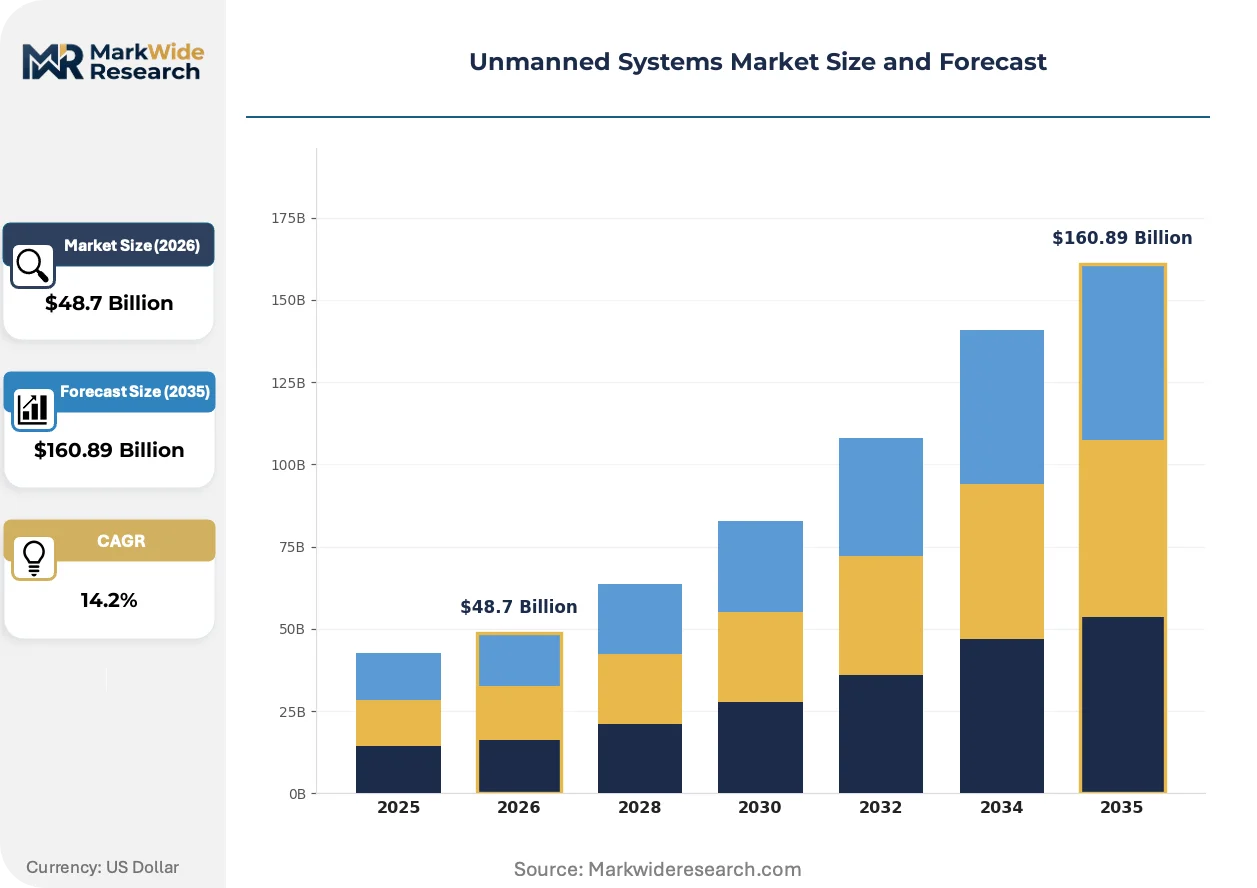
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UAV, UGV, USV, Hybrid Systems Technology: AI, Sensors, Navigation, Communication Industry Vertical: Aerospace, Defense, Agriculture, Logistics End User: Military, Commercial, Government, Research |
| Companies Covered | Northrop Grumman Corporation, Lockheed Martin Corporation, The Boeing Company, BAE Systems, General Atomics Aeronautical Systems, Teledyne Technologies, Israel Aerospace Industries, Textron Systems, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Systems Market Evolving Landscape
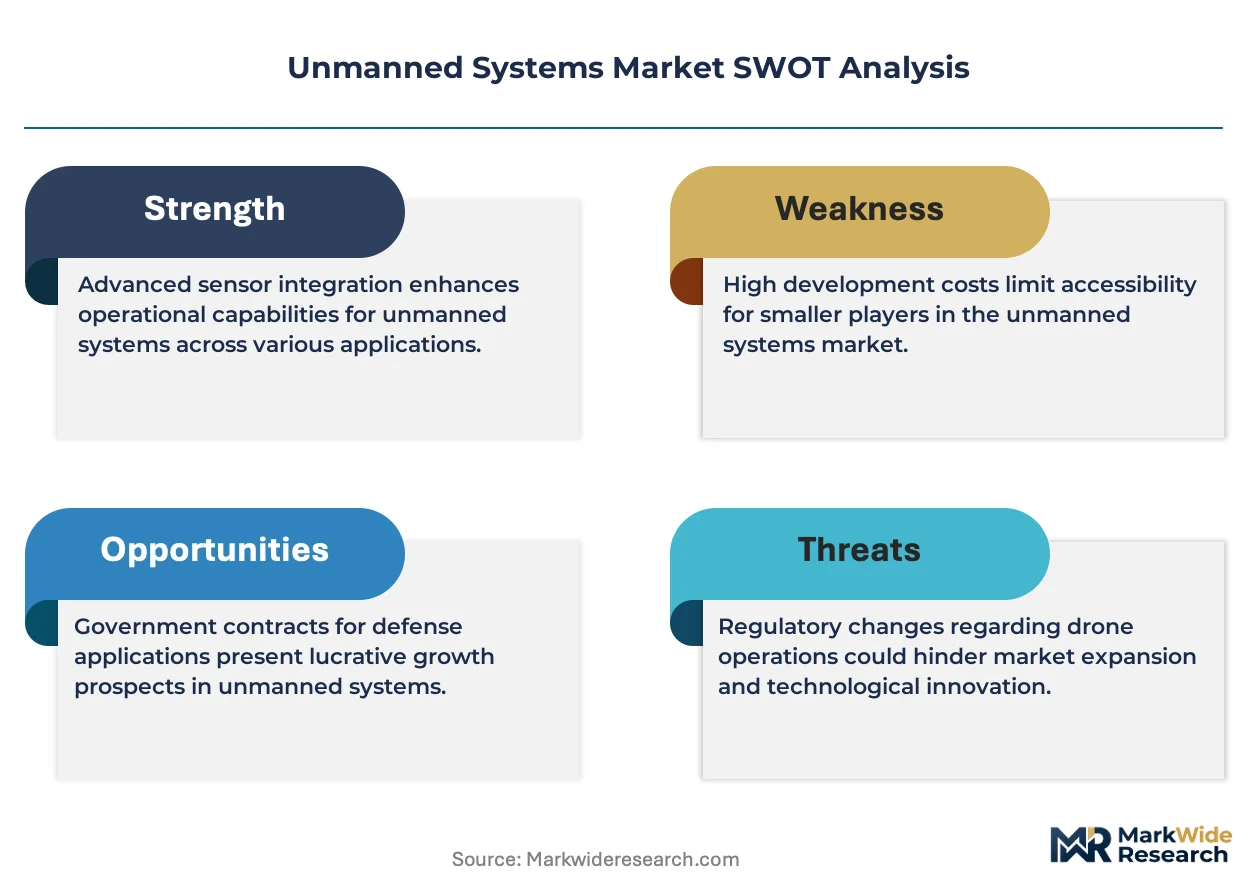
Autonomous navigation architectures are compressing the value chain between sensor manufacturers and platform integrators, while regulatory fragmentation between civilian certification and defense procurement creates parallel qualification tracks.
Edge-based artificial intelligence is consolidating flight control and mission planning functions onto single-board computing modules. Defense primes and commercial logistics operators are adopting these integrated stacks to reduce payload weight and power draw. This consolidation is eliminating discrete avionics supplier tiers and shifting margin capture toward semiconductor and software houses.
The EU AI Act's high-risk system classification now captures autonomous navigation algorithms operating in civilian airspace. Manufacturers must demonstrate conformity with transparency and human-oversight requirements before CE marking. Commercial UAV segments serving infrastructure inspection are restructuring development pipelines to accommodate these pre-market conformity obligations.
Defense procurement patterns now favor indefinite-delivery vehicle contracts with multi-year platform sustainment bundled into initial awards. Traditional spot-buying of spare airframes and ground control stations is contracting. The United States Army's approach to Group 1-3 UAV acquisition exemplifies this shift toward total-cost-of-ownership contracting structures.
Unmanned Systems Market Segmentation
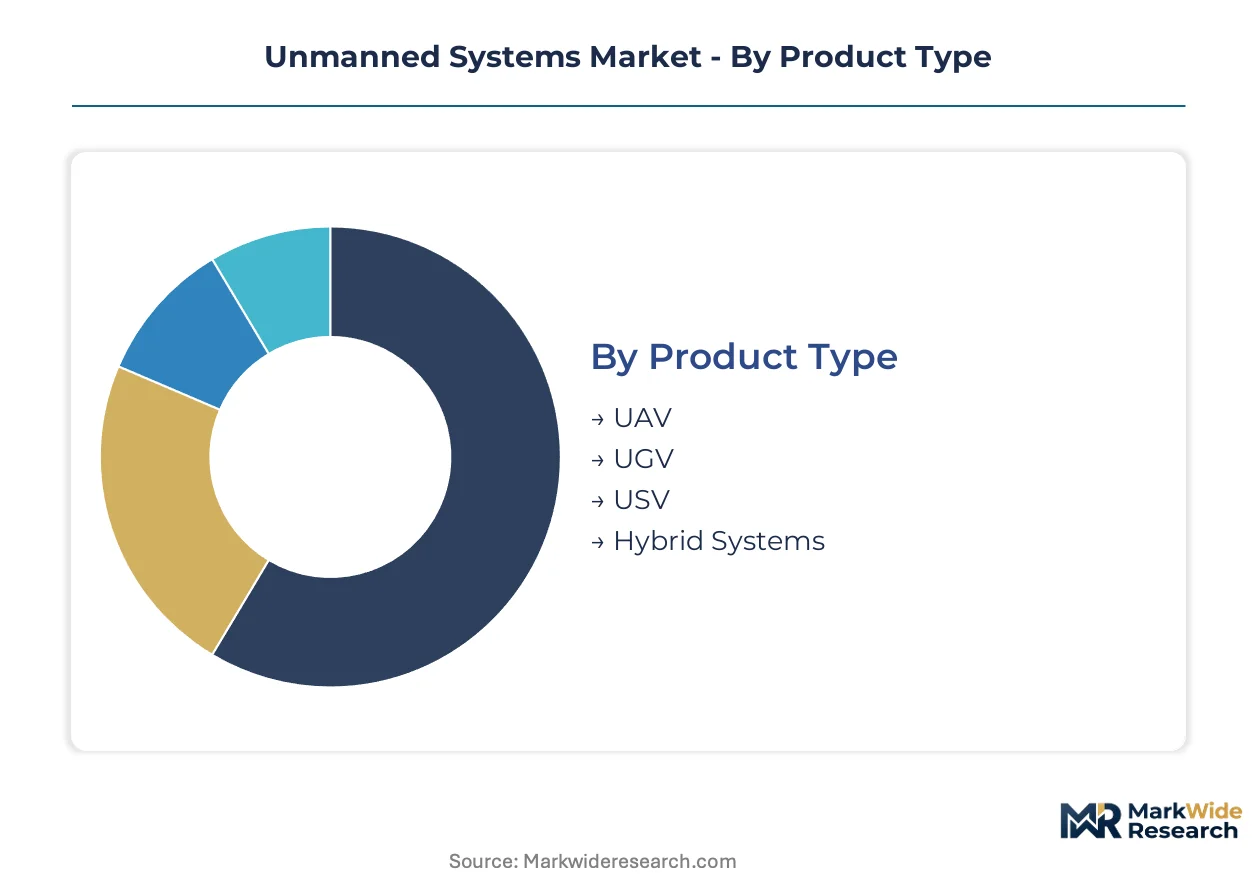
Unmanned systems procurement splits across divergent certification pathways, with defense and commercial buyers imposing incompatible qualification requirements on shared platform architectures. Segmentation clarity determines which supplier capabilities transfer across end-use boundaries.
Product Type:
Platform supply concentrates among turboprop specialists for persistent missions and electric multicopter integrators for short-range logistics.
- UAV:Fixed-wing and rotary-wing configurations dominate procurement volumes, with Group 4-5 platforms integrating satellite communications relays for beyond-line-of-sight operations. Pentagon program budgets and FAA commercial corridor authorizations in the United States concentrate demand for certified airframes.
- UGV:Wheeled and tracked ground platforms execute explosive ordnance disposal, perimeter security, and logistics transport in denied environments. Route clearance applications across NATO member states are climbing the fastest as allied procurement standardizes on STANAG interoperability protocols.
- USV:Surface vessels perform mine countermeasures and maritime domain awareness in contested littorals.
- Hybrid Systems:Multi-domain platforms transition between aerial and surface modes for amphibious operations.
Today's leader: UAV. Tomorrow's challenger: UGV.
Technology:
Cost tier stratification separates commoditized navigation modules from premium AI autonomy layers attracting disproportionate R&D investment.
- AI:Edge-based machine vision and autonomous decision architectures compress operator burden for persistent ISR missions. EU AI Act conformity requirements for civilian high-risk systems impose pre-market validation timelines distinct from defense procurement pathways.
- Sensors:Electro-optical, infrared, and synthetic aperture radar payloads constitute disproportionate platform cost concentration. Military end users in the United States drive demand for multi-spectral fusion systems with encrypted data links.
- Navigation:GPS-denied positioning using inertial measurement units and visual odometry matures into standardized subsystems.
- Communication:Beyond-line-of-sight relay systems depend on contested Ku-band and Ka-band satellite capacity.
Margin capture shifts upstream: AI and sensors claim premium pricing; navigation and communication commoditize.
Industry Vertical:
Application maturity varies sharply, with defense contracting structures now favoring total-cost-of-ownership models over discrete platform purchases.
- Aerospace:Commercial aviation inspection and urban air mobility infrastructure development attract FAA-designated corridor investment in Dallas-Fort Worth and Reno.
- Defense:Multi-domain operations mandate integrated command-and-control architectures with allied interoperability. Indefinite-delivery vehicle contracts with bundled sustainment now dominate United States Army Group 1-3 acquisition patterns.
- Agriculture:Precision crop monitoring and spraying applications face seasonal utilization constraints.
- Logistics:Last-mile delivery and warehouse inventory management show steepest trajectory change among commercial end uses.
Contracting innovation originates in Defense; volume scaling potential concentrates in Logistics.
End User:
Customer type determines regulatory jurisdiction, with military procurement exempt from FAA Part 107 constraints governing commercial operations.
- Military:Intelligence collection, precision strike, and persistent ISR missions command the largest budget allocation. MIL-STD-810 environmental testing and STANAG protocols qualify platforms for allied fleet integration.
- Commercial:Industrial facility inspection, emissions monitoring, and cargo delivery operate under OSHA-permitted and EPA-constrained deployment frameworks. OSHA-permitted UAV deployment for stack inspection opens utility end uses previously blocked by safety protocols.
- Government:Border patrol, disaster response, and infrastructure survey applications span civilian and paramilitary mission profiles.
- Research:Academic and test range operations drive early-stage autonomy algorithm validation outside certification pathways.
Procurement concentration: Military. Regulatory complexity: Commercial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting unmanned systems production toward jurisdictions where defense procurement timelines outpace civilian certification burdens. Manufacturers now site final assembly where FAA, EASA, or national military standards offer the fastest path to revenue.
United States
Pentagon unmanned program budgets and FAA beyond-visual-line-of-sight corridor designations in Dallas-Fort Worth and Reno concentrate platform demand. The Department of Defense mandates MIL-STD-810 environmental testing and STANAG interoperability protocols for allied fleet integration. California and Texas host the densest clusters of defense primes and commercial drone operators scaling urban air mobility infrastructure.
Germany
Bundeswehr procurement standardization on NATO-compatible command-and-control architectures drives platform orders from Rheinmetall and Krauss-Maffei Wegmann suppliers. The EU AI Act's high-risk system classification for autonomous navigation imposes pre-market conformity obligations distinct from defense procurement pathways. Bavaria and Baden-Württemberg concentrate sensor payload and ground control station manufacturing for allied export.
Israel
Israeli defense contractors reposition aerial platform production toward NATO-standard interoperability as allied procurement accelerates. The country's national defense regulator maintains streamlined qualification pathways for dual-use technologies under export control frameworks. Tel Aviv and Haifa metropolitan areas anchor autonomous flight software development and persistent ISR platform integration for European and Asian buyers.
United Kingdom
Ministry of Defence Future Combat Air System requirements and Royal Navy autonomous surface vessel programs expand procurement volumes. UK defense procurement now favors indefinite-delivery vehicle contracts with multi-year sustainment bundled into initial awards. Scotland and South West England host emerging clusters for maritime unmanned systems and explosive ordnance disposal ground vehicle testing.
Japan
Japan's Ministry of Defense accelerates counter-UAV and reconnaissance platform acquisition under revised national security guidelines. METI promotes industrial UAV deployment for infrastructure inspection through streamlined type certification pathways. Tokyo-Osaka corridor manufacturers integrate American and Israeli subsystem suppliers for domestic defense and commercial logistics applications.
Unmanned Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enabled autonomy layers and modular open architectures. The vendor base stratifies between defense primes with bundled sustainment contracts and commercial specialists scaling FAA-certified platforms. Three archetypes dominate: turboprop persistent-ISR integrators, electric multicopter logistics operators, and multi-domain command-and-control architects. Competitive moves concentrate on indefinite-delivery vehicle contract capture and satellite communications relay capacity acquisition.
Within the defense prime tier, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify integrated command-and-control positioning for multi-domain operations. General Atomics Aeronautical Systems occupies a specialist position in turboprop-powered persistent ISR. These three entities anchor the United States-based supplier cluster where Pentagon procurement patterns and FAA commercial corridor timelines now set global supply chain pace.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| The Boeing Company |
| BAE Systems |
| General Atomics Aeronautical Systems |
| Teledyne Technologies |
| Israel Aerospace Industries |
| Textron Systems |
| L3Harris Technologies |
| Others |
Value Network & Pricing Analysis
STANAG interoperability mandates from NATO allies are compressing supplier qualification timelines and forcing platform integrators toward modular open architectures, which fragments pricing power across sensor manufacturers, autonomy software houses, and final assembly contractors rather than concentrating it with traditional airframe primes.
Pricing Analysis
Defense prime direct-to-military contracts capture 60-70 point margins through bundled sustainment, while commercial UAV channels absorb distributor markups of 15-25 points for FAA-certified platforms. Three-tier pricing structure across MIL-STD-810 qualified, STANAG-compliant, and uncertified commercial tiers separates defense procurement from logistics applications. Pricing pressure stems from electro-optical payload cost concentration among specialized subcontractors. Commercial logistics operators show highest price sensitivity; defense end users prioritize mission assurance over unit economics.
Supply Chain Analysis
Freight costs for lithium-thionyl chloride battery cells and rare earth magnet shipments from China amplify landed costs for propulsion subsystems at United States and Israeli assembly plants. Manufacturing concentrates in the United States, Israel, and Germany for platform integration, with China and South Korea feeding semiconductor and battery inputs. Single-source vulnerability sits with Ku-band satellite relay capacity for beyond-line-of-sight operations. Distribution runs through defense prime direct sales for military end users and commercial UAV distributors for civilian logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage favors situating final assembly where FAA beyond-visual-line-of-sight corridor designations outpace EU AI Act pre-market conformity burdens, exploiting the 12-18 month regulatory gap between United States commercial deployment and European high-risk system certification.
For Market Incumbents: To counter modular open architecture mandates fragmenting integrated command-and-control margins, Northrop Grumman and Lockheed Martin must deepen backward integration into AI-enabled autonomy layers while adding sustainment capacity in Texas and California to capture indefinite-delivery vehicle contract bundles. For New Entrants and Emerging Players: The 40-50 point margin gap between premium turboprop ISR platforms and economy electric multicopters offers entry at the UGV route clearance tier where STANAG standardization is climbing fastest. Target NATO allied procurement through modular payload interfaces rather than full-platform competition. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor houses capturing flight control consolidation and edge computing module suppliers. The five-to-ten year viability window favors autonomy algorithm developers with EU AI Act conformity pathways already validated. Watch FAA commercial corridor authorization velocity as the signal distinguishing scalable logistics plays from defense-dependent revenue concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Open Architecture Adoption | Enables NATO allied fleet integration and multi-domain handoff compatibility for defense primes. |
| Beyond-Visual-Line-of-Sight Certification | Unlocks FAA-designated commercial corridors in Dallas-Fort Worth and Reno for logistics scaling. |
| AI Act Conformity Investment | Positions civilian platforms for EU infrastructure inspection mandates under CSRD-aligned emissions verification. |
| Satellite Communications Relay Acquisition | Secures contested Ku-band and Ka-band capacity for concurrent beyond-line-of-sight mission density. |
| UGV Route Clearance Specialization | Captures underpenetrated NATO procurement standardizing on STANAG interoperability protocols. |
Research Methodology
Multiple input streams — defense procurement officer interviews, commercial UAV operator panels, and regulatory filing analysis — were reconciled against secondary validation from FAA rulemaking dockets, Pentagon program budget justifications, and NATO standardization agreements. Primary fieldwork engaged platform integration engineers, autonomy software developers, sensor payload procurement leads, and ground control station manufacturing heads. Bottom-up triangulation across component supplier interviews and top-down demand modeling from end-user budget allocations were cross-referenced for convergence.
Historical defense contracting patterns were cross-referenced against expert panel inputs on FAA commercial corridor deployment timelines. Segmentation modeling spanned product type, technology layer, industry vertical, and end-user regulatory jurisdiction across the projection horizon. CAGRs were derived from platform order flow analysis and sustainment contract value capture. Industry-specific inputs included STANAG interoperability adoption curves and EU AI Act pre-market validation timelines.
Caveats apply where FAA beyond-visual-line-of-sight rulemaking delays or NATO defense procurement reprioritization could materially shift the outlook. Forecasts reflect assumptions on satellite bandwidth availability and rare earth supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Brazil ROV Market
Unmanned Systems
United States ROV Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
Drone Docking Station Market
Unmanned Systems
Military Robots Market
Unmanned Systems
Aerostat System Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Drone Tethered Stations Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Autonomous Pods Market