
 Global Battlefield Management System Market | 2026-2036
Global Battlefield Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Battlefield Management System Market Intelligence
The shift towards performance-based logistics and 'system-as-a-service' procurement models is reconfiguring the competitive landscape for long-term support contracts. This structure favors large, established integrators like Thales Group, which leverages its extensive portfolio for comprehensive solutions. General Dynamics Corporation specializes in ground combat systems integration, while Elbit Systems Ltd. differentiates through its expertise in unmanned systems and C4I technologies.
A Battlefield Management System is a networked command and control platform that provides a common operational picture to military units. These systems integrate disparate sensor data through secure, high-bandwidth data-links to enable real-time decision-making. Within technology segments, Artificial Intelligence and satellite communication are experiencing the most significant investment for predictive capabilities. Tactical Operations and Reconnaissance applications represent the largest share of system deployments, driven by force modernization priorities.
Interoperability standards are critical, with NATO's Standardization Agreements (STANAGs) and the U.S. Department of Defense's MIL-STD specifications dictating system architecture. Export control regimes implemented by bodies like the U.S. Department of State also shape market access for international sales. Future system viability will depend on a vendor's ability to develop open-architecture platforms that can integrate third-party technologies and counter evolving cyber threats.
Market Dynamics
The imperative for decision dominance on a multi-domain battlefield is the central force shaping system development. This pressure compels the integration of artificial intelligence and secure, high-bandwidth communications to fuse disparate sensor data into a coherent, real-time operational picture for commanders.
Growth Catalysts
- Force Modernization Programs:National defense initiatives, particularly in India and Poland, are allocating significant budgets to upgrade or replace legacy command and control systems, creating concentrated pockets of demand for advanced BMS platforms.
- Interoperability Mandates:Adherence to standards like NATO's STANAGs is essential for joint operations. This requirement drives the adoption of systems built on common protocols, ensuring seamless data exchange between allied forces and different military branches.
- Sensor Proliferation:The increasing number of sensors on soldiers, vehicles, and unmanned systems generates a massive volume of data, necessitating sophisticated BMS platforms to process, analyze, and display this information effectively for situational awareness.
Market Restraints
- Export Control Regimes:Strict regulations, including the U.S. International Traffic in Arms Regulations (ITAR), create significant barriers to international sales, limiting market access for vendors and complicating procurement for non-allied nations.
- High System Complexity and Cost:The extensive research, development, and integration costs associated with creating a secure and reliable BMS place these systems beyond the reach of nations with smaller defense budgets, constraining the total addressable market.
- Legacy System Integration:Integrating modern, open-architecture BMS with decades-old military hardware and communication infrastructure presents a major technical and financial hurdle, often delaying deployment and increasing project risks.
Strategic Opportunities
- Unmanned Systems Integration:Developing specialized BMS modules to control and process data from swarms of autonomous air and ground vehicles represents a significant growth area, especially for reconnaissance and logistics applications.
- Commercial Technology Adaptation:Leveraging advancements in commercial satellite communications and 5G networks offers a pathway to provide more resilient, high-bandwidth connectivity at a lower cost than purely military-specific solutions.
- Dual-Use Applications:Adapting BMS platforms for civilian agencies involved in emergency management, border security, and large-scale disaster response opens new, non-military revenue streams for established defense contractors.
Industry Challenges
- Cybersecurity Vulnerabilities:Networked command systems are high-value targets for state-sponsored cyber attacks and electronic warfare, requiring continuous and costly investment in hardening defenses against evolving threats.
- Data Interoperability Gaps:Despite standards, achieving seamless data exchange between systems from different vendors or across different military services remains a persistent challenge, hindering the creation of a truly unified common operational picture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Battlefield Management System Market |
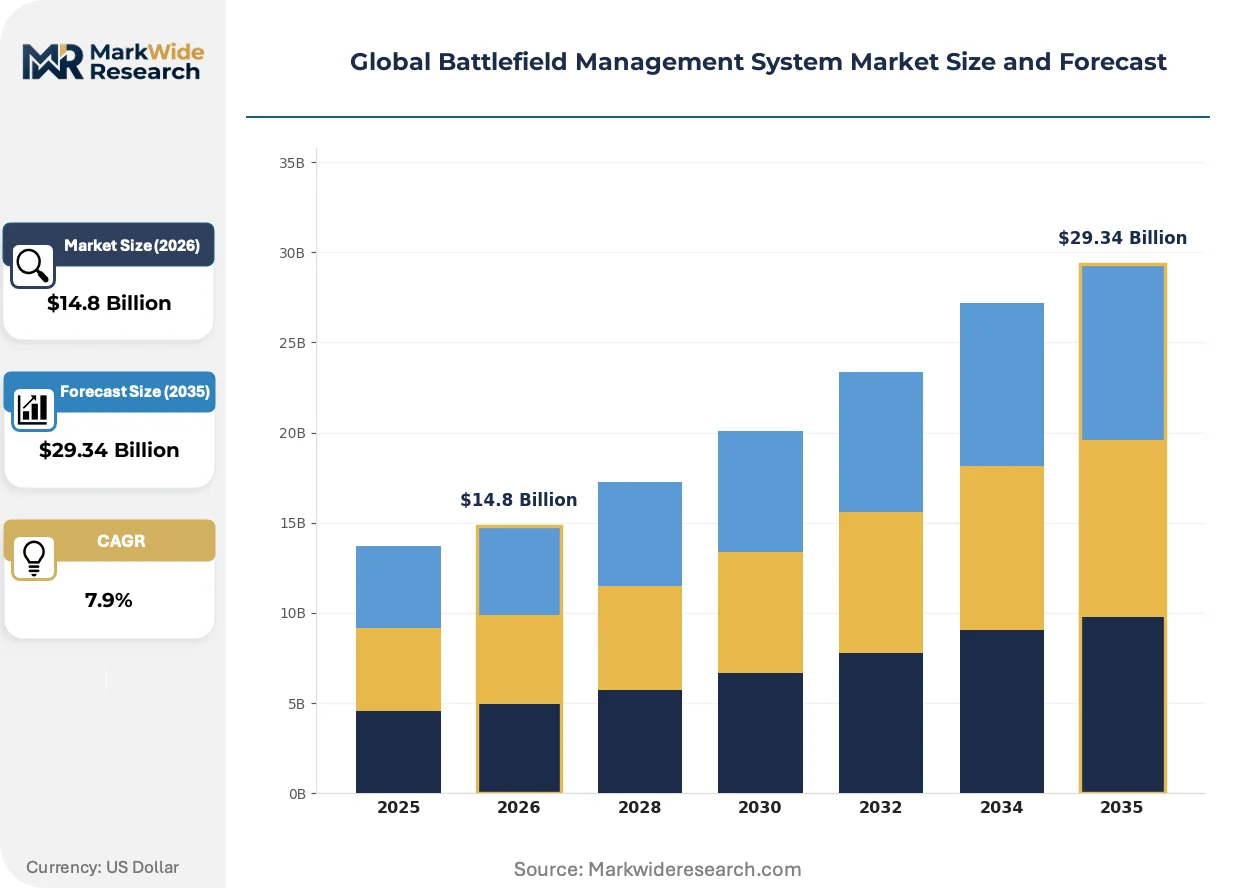
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $29.34 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Command & Control Systems, Communication Equipment, Surveillance Tools, Navigation Devices, Data-Link Solutions Technology: Satellite Communication, Radio Frequency, Infrared Imaging, Artificial Intelligence, Cloud Computing Application: Tactical Operations, Reconnaissance, Target Acquisition, Logistics Coordination, Cyber Defense End User: Defense Forces, Special Operations Units, Border Security, Intelligence Agencies, Peacekeeping Troops |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems plc, Thales Group, General Dynamics Corporation, Leonardo S.p.A., RTX Corporation, Elbit Systems Ltd., L3Harris Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Battlefield Management System Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from hardware-centric, monolithic systems toward software-defined, open-architecture platforms. This transition enables rapid capability insertion and adaptation to new threats, driven by modularity and artificial intelligence.
Edge computing, embedding processing power directly into tactical devices, is a key product evolution. Special Operations units and forward-deployed infantry are the primary adopters, seeking to reduce reliance on distant command posts. This development is hybridizing centralized data analysis with decentralized, on-the-ground AI processing, which significantly cuts decision latency in contested environments.
Regulatory frameworks are increasingly mandating modularity, exemplified by the U.S. Department of Defense's Modular Open Systems Approach (MOSA). Its enforcement compels vendors to abandon proprietary, closed ecosystems in favor of competitive, component-based architectures. Large system integrators are most impacted, as they must now design platforms that readily accept third-party software and hardware upgrades.
A notable demand-side shift involves the adoption of 'system-as-a-service' procurement models for long-term capability management. This approach replaces traditional, one-time hardware sales with recurring contracts that bundle continuous software updates, support, and technology refreshes. The model is most prominent within NATO member countries looking to manage total lifecycle costs while maintaining a technological edge.
Global Battlefield Management System Market Segmentation
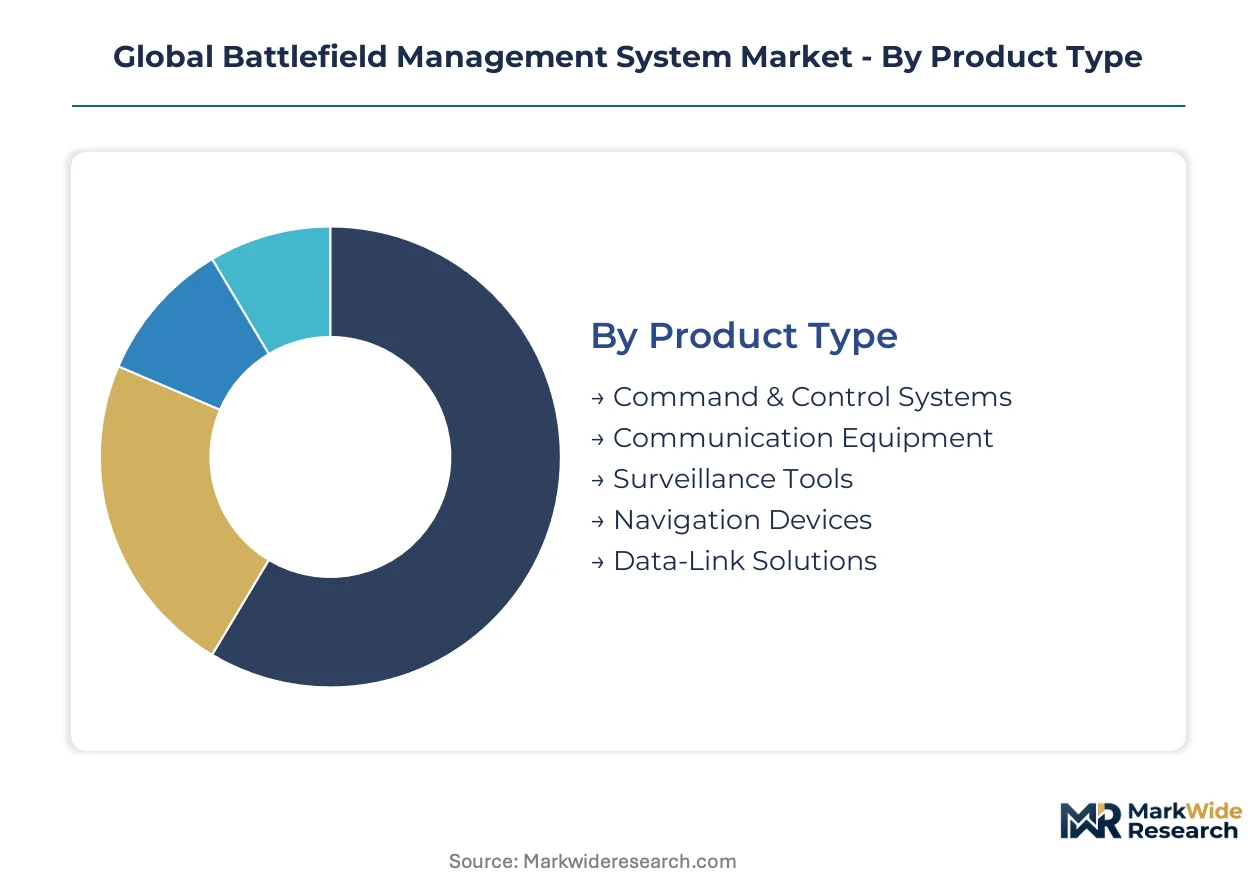
Understanding the Battlefield Management System market through detailed segmentation reveals the specific technological and operational requirements driving procurement decisions. This granular view allows defense contractors to align product development with the evolving needs of military forces globally, optimizing resource allocation for high-impact solutions.
Product Type:
The intensity of after-sales service requirements often dictates the long-term profitability and customer retention for various product types within Battlefield Management Systems.
- Command & Control Systems:These platforms integrate sensor data, intelligence, and operational plans to provide commanders with a unified common operational picture. Their complexity mandates extensive customization and continuous software updates, crucial for maintaining decision dominance across multi-domain battlefields.
- Communication Equipment:This segment encompasses secure, high-bandwidth data-links and radio systems essential for real-time data exchange between disparate military units. The need for resilient, jam-resistant communication is paramount for joint operations, driving significant investment in advanced encryption and frequency-hopping technologies.
- Surveillance Tools:These include various sensors like electro-optical, infrared, and radar systems deployed on ground vehicles, unmanned aerial systems, and soldier-worn devices. Surveillance tools generate massive volumes of data, necessitating sophisticated BMS integration for effective analysis and display.
- Navigation Devices:Precision GPS, inertial navigation systems, and alternative positioning technologies ensure accurate force tracking and target designation. These devices are critical for coordinated maneuvers and fire support, particularly in GPS-denied environments.
- Data-Link Solutions:Specialized hardware and software facilitate the secure and efficient transfer of tactical information between different BMS components and allied systems. Interoperability standards like NATO's STANAGs heavily influence their design and adoption.
By volume, Communication Equipment leads. By growth pace, Command & Control Systems is ahead.
Technology:
The supply concentration for specialized technological components profoundly influences the development cycles and cost structures of Battlefield Management Systems.
- Artificial Intelligence:AI algorithms are integrated for predictive analytics, threat assessment, and autonomous decision support, fusing vast amounts of sensor data. This technology is a critical shift influencing system design, particularly for reducing decision latency in contested environments.
- Satellite Communication:SATCOM provides resilient, global connectivity for deployed forces, enabling high-bandwidth data transfer in remote or austere locations. Leveraging commercial satellite communication offers a pathway to more cost-effective and resilient connectivity.
- Radio Frequency:RF technologies underpin tactical communication networks, providing secure voice and data links for short-to-medium range operations. Modern systems focus on anti-jamming capabilities and cognitive radio functionalities for spectral efficiency.
- Infrared Imaging:Thermal cameras and infrared sensors enable night vision and detection of heat signatures, providing crucial intelligence in low-light conditions. These systems are vital for reconnaissance and target acquisition applications.
- Cloud Computing:Cloud platforms offer scalable data storage and processing capabilities for large-scale BMS deployments, supporting distributed operations and collaborative planning. Edge computing extends these capabilities to the tactical edge, reducing reliance on distant command posts.
Strategic investment in Artificial Intelligence reflects its long-term impact on decision dominance.
Application:
The application of Battlefield Management Systems directly correlates with the specific operational mandates and tactical objectives of military forces.
- Tactical Operations:BMS platforms provide real-time situational awareness and command capabilities for units engaged in direct combat, enabling coordinated maneuvers and rapid response. These applications represent the largest share of system deployments, driven by force modernization priorities.
- Reconnaissance:Systems designed for reconnaissance integrate data from unmanned aerial vehicles, ground sensors, and human intelligence to gather critical information on enemy positions and terrain. This capability is essential for intelligence gathering and target identification.
- Target Acquisition:BMS tools enhance the precision and speed of identifying and engaging targets through integrated sensor-to-shooter links and advanced fire control systems. This application significantly improves the effectiveness of indirect fire and air support.
- Logistics Coordination:These applications optimize the supply chain, resource allocation, and movement of personnel and equipment across the battlefield. Efficient logistics coordination reduces operational costs and enhances force sustainment.
- Cyber Defense:BMS platforms incorporate cybersecurity measures to protect networked systems from cyber threats and electronic warfare attacks. Continuous investment in hardening defenses is required to ensure system integrity and data security.
The operational effectiveness of Tactical Operations is critical for achieving mission objectives.
End User:
The maturity of procurement processes and technological integration varies significantly among different end-user segments, influencing market dynamics.
- Defense Forces:National armed forces constitute the primary end-users, investing in comprehensive BMS solutions for conventional warfare and national defense. Modernization programs in countries like India and Poland are concentrating demand in this segment.
- Special Operations Units:These elite units require highly agile, lightweight, and secure BMS platforms for rapid deployment and clandestine missions. Adoption within Special Operations Units is accelerating due to the need for real-time situational awareness in complex environments.
- Border Security:Agencies responsible for border protection utilize BMS for surveillance, threat detection, and coordinated response to illegal activities. These systems often integrate commercial technologies for cost-effectiveness and rapid deployment.
- Intelligence Agencies:BMS supports intelligence gathering, analysis, and dissemination, providing critical insights for strategic decision-making. These users prioritize advanced analytics and secure data handling capabilities.
- Peacekeeping Troops:International peacekeeping forces deploy BMS to enhance situational awareness, ensure troop safety, and coordinate humanitarian efforts in conflict zones. Interoperability with multinational forces is a key requirement for these systems.
Evolving threat landscapes are shifting procurement priorities towards Special Operations Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Battlefield Management System market demonstrates a complex interplay of national defense priorities and international trade regulations. Nations balance the imperative for advanced capabilities with export control regimes, influencing procurement strategies and the geographic distribution of demand and supply. This dynamic shapes where critical R&D and manufacturing capabilities are concentrated.
United States
Force modernization and the integration of artificial intelligence for predictive analytics drive significant demand for advanced BMS platforms. The U.S. Department of Defense's MIL-STD specifications dictate system architecture, ensuring interoperability across military branches. Major defense contractors in the Washington D.C. area and California's defense tech hubs lead innovation in command and control systems.
India
National defense initiatives and the urgent need to upgrade legacy command and control systems are propelling substantial investment in BMS. India's PLI scheme for defense manufacturing encourages domestic production and technology transfer. Bengaluru and Hyderabad serve as key centers for defense R&D and manufacturing, contributing to indigenous BMS development.
Poland
Adherence to NATO's STANAGs and the ongoing replacement of Soviet-era military equipment are primary demand drivers. National defense procurement laws prioritize systems that enhance interoperability with allied forces. Warsaw and Poznań are emerging hubs for defense industry engagement, focusing on advanced C4I system integration projects.
France
European defense integration and the pursuit of multi-domain battlefield capabilities shape the demand for sophisticated BMS. The EU AI Act considerations for defense applications influence the ethical development of AI-powered systems. The Paris region, home to major integrators like Thales Group, anchors European BMS research and development efforts.
Israel
Advanced C4I technologies and the integration of unmanned systems for border security and tactical intelligence are key areas of focus. Strict export control policies for defense technologies govern international sales. The Tel Aviv area stands as a vibrant hub for defense electronics and software development, specializing in tactical intelligence solutions.
Global Battlefield Management System Market Key Industry Players
On the supply side, the industry is highly consolidated, dominated by a few large, established defense integrators that offer comprehensive solutions. This structure creates a tiered market where specialized technology providers often act as subcontractors or partners. Strategic archetypes include large system integrators, C4I specialists, and unmanned systems experts. Portfolio diversification and strategic partnerships are critical competitive moves for securing complex program bids.
Among the large system integrators, Lockheed Martin Corporation, a prominent U.S.-based entity, represents the extensive scale of American defense contractors. Thales Group, a French S.A., exemplifies a European player providing comprehensive solutions across various defense domains. Elbit Systems Ltd., an Israeli entity, occupies a position as a specialist in advanced C4I and unmanned systems, differentiating through its expertise in these critical areas.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems plc |
| Thales Group |
| General Dynamics Corporation |
| Leonardo S.p.A. |
| RTX Corporation |
| Elbit Systems Ltd. |
| L3Harris Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Export control regimes, particularly the U.S. International Traffic in Arms Regulations (ITAR), determine both pricing tier spreads and the global supply chain shape for Battlefield Management Systems. These strict regulations limit market access for vendors and complicate procurement for non-allied nations, creating distinct pricing structures.
Pricing Analysis
Industrial OEM buyers anchor the project-based pricing structure for Battlefield Management Systems. Pricing stratifies across premium, standard, and economy tiers based on customization level for specific military requirements and the extent of after-sales service bundling. Cost compression in certain segments stems from the technical challenges of integrating modern BMS with decades-old legacy hardware, increasing project risks. Nations with smaller defense budgets are often the most price-sensitive segment, while major defense forces prioritize advanced capability and interoperability over initial cost.
Supply Chain Analysis
Upstream component sourcing for Battlefield Management Systems primarily draws from specialized defense electronics manufacturers concentrated in the United States, France, and Israel. Key raw material and component dependencies include secure communication modules, advanced sensor arrays, and high-performance processors. Single-source vulnerability for highly specialized, export-controlled components represents a critical supply chain risk. Distribution runs through direct sales channels to national defense forces and government agencies, often facilitated by long-term government contracts and strategic partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits as a defensive-moat story, justified by the significant regulatory entrenchment provided by adherence to standards like NATO's STANAGs and U.S. MIL-STD specifications.
For Market Incumbents: Build regulatory compliance moats by actively shaping and adhering to evolving interoperability standards. Invest heavily in open-architecture platforms to counter the threat of vendor lock-in and integrate third-party innovations. Prioritize R&D in advanced cybersecurity defenses to mitigate sophisticated state-sponsored cyber attacks. Consolidate market share through strategic acquisitions of specialized technology providers in AI and unmanned systems integration.
For New Entrants and Emerging Players: Build out specialized modules for unmanned systems integration, targeting reconnaissance and logistics applications as white-space opportunities. Focus on adapting commercial technologies like 5G and satellite communications for military use, offering more cost-effective solutions. The border security and peacekeeping segments represent the most penetrable applications. A go-to-market angle emphasizing modularity and rapid deployment for specific tactical needs can differentiate offerings.
For Investors and Strategic Acquirers: The market sits at a maturing innovation phase that favors specialists in C4I technologies and AI-powered predictive analytics. Long-term viability rests on continuous innovation in cyber resilience and multi-domain integration capabilities. Acquisition targets should include agile software companies with expertise in edge computing and data fusion. The signal to watch is the adoption rates of 'system-as-a-service' procurement models across NATO member countries, indicating a shift towards recurring revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamlessly integrating diverse sensor data into a common operational picture enhances decision-making for commanders. |
| Acquisition of Specialist Firm | Acquiring expertise in AI or cybersecurity strengthens core capabilities against evolving threats and technological shifts. |
| R&D Investment | Developing open-architecture systems ensures future compatibility and reduces total cost of ownership for defense forces. |
| Strategic Partnership | Collaborating with commercial tech providers brings resilient, high-bandwidth connectivity solutions to military applications. |
| Geographic Expansion | Targeting modernization programs in emerging defense markets diversifies revenue streams and reduces dependency on established buyers. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary validation anchors the qualitative findings. This involved discussions with defense procurement officers, systems engineers, military strategists, and technology developers. Secondary sources included government defense budgets, military modernization reports, technology whitepapers, and export control databases, providing a comprehensive view. The analysis utilized both bottom-up and top-down triangulation to ensure data accuracy and consistency.
Iterative calibration of market models informed the forecast framework across the analysis window. The analytical framework integrated demand-side analysis with supply-side capabilities to project market growth. Segmentation dimensions modeled included product type, technology, application, end-user, and regional military spending. Compound Annual Growth Rates (CAGRs) were derived from a weighted average of historical trends and projected technological advancements, incorporating defense R&D budgets and geopolitical conflict indices as key inputs.
Practitioners should monitor geopolitical shifts and new regulatory mandates for early signals of market revision. Forecasts reflect assumptions documented at the time of publication, acknowledging inherent market uncertainties. Cross-checking against national intelligence assessments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Vetronics Market
Defense and Military Systems and Equipment
United States Defense Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Soldier System Market
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Global Military Laser Designator Market
Defense and Military Systems and Equipment
Counter-IED Systems Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Europe Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
Asia-Pacific Digital Battlefield Market
Defense and Military Systems and Equipment
Saudi Arabia Defense Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market