
 Location Analytics Market | 2026-2036
Location Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Location Analytics Market Analysis
The capability gap between cloud-native platform operators and legacy on-premise vendors is bifurcating competitive returns in location analytics. Esri sustains dominance in enterprise-grade spatial analysis through decades of proprietary geodatabase investment. Google LLC leverages its consumer mapping data pipeline to undercut traditional GIS pricing for mid-market accounts. Microsoft Corporation anchors its position through Azure-native integration that bundles location services with enterprise cloud contracts.
Location analytics encompasses the computational processing of geospatial coordinates, movement trajectories, and place-bound attributes to derive operational intelligence for physical-world decisions. The discipline relies on coordinate reference systems, spatial indexing algorithms, and real-time stream processing architectures to transform raw positioning signals into actionable territory intelligence. Cloud-based deployment now leads expansion as organizations abandon capital-intensive server infrastructure for elastic consumption models. The geofencing solution category is capturing disproportionate growth from logistics operators seeking automated perimeter alerting for fleet management. Spatial analysis retains the deepest margin pools because specialized talent scarcity protects pricing power for complex polygon overlay and hotspot detection services.
The Federal Communications Commission shapes US market access through spectrum allocation rules that govern precision positioning infrastructure, while the EU AI Act imposes conformity requirements on automated geospatial decision systems deployed across European member states. ISO 19115 metadata standards further condition interoperability expectations for cross-border spatial data exchange. Stakeholders must weigh regulatory compliance investments against the accelerating shift toward real-time edge analytics before committing to long-term platform architecture decisions.
Market Dynamics
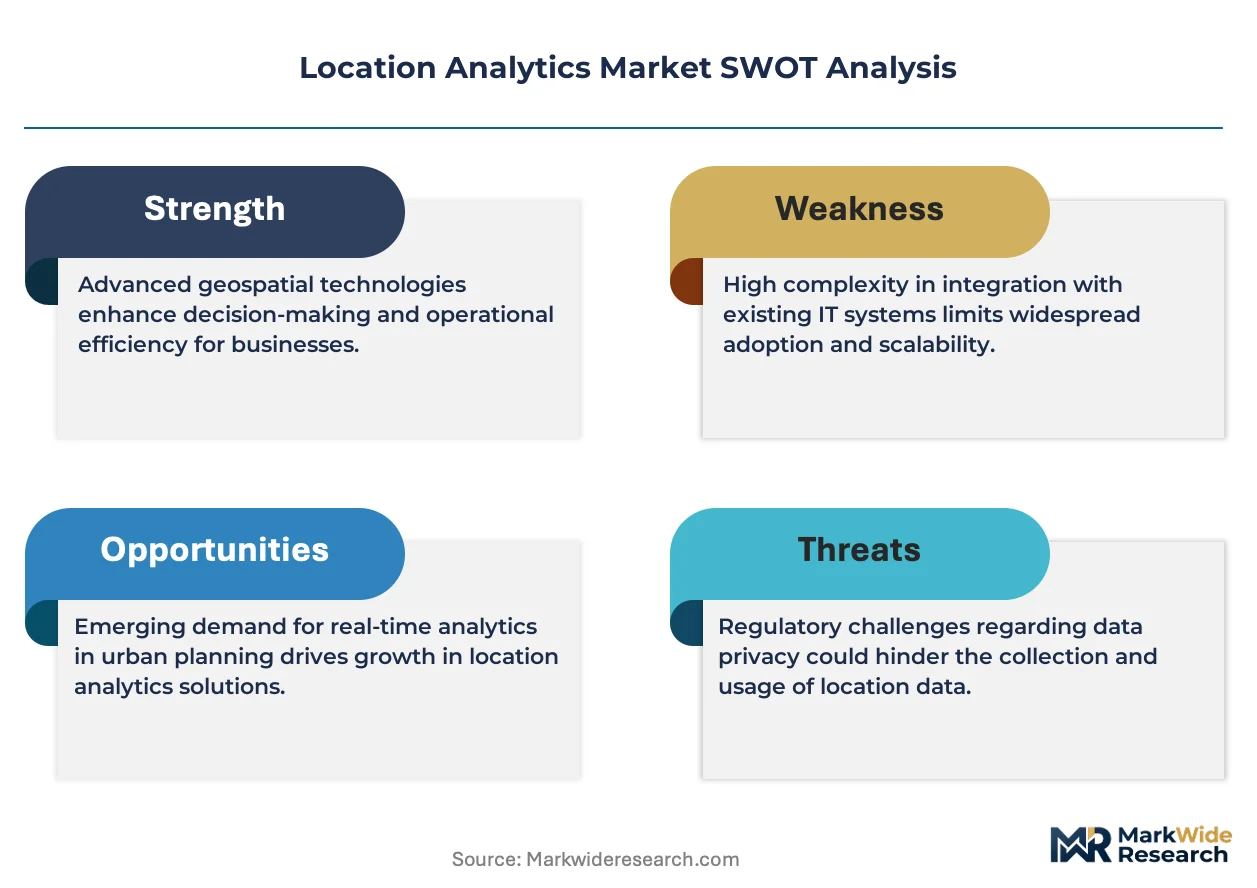
Cloud-native architectures are decomposing traditional GIS vendor lock-in as elastic compute and open-source spatial libraries erode decades of proprietary geodatabase moats. Municipal procurement officers now favor consumption-based pricing over perpetual licenses, forcing incumbents to restructure revenue models.
Growth Catalysts
- EU AI Act conformity requirements:Automated geospatial decision systems deployed across European member states must now demonstrate algorithmic transparency, creating specialized compliance service demand.
- Smart city infrastructure deployment:United States municipal governments are instrumenting urban corridors with sensor networks that feed real-time positioning data into centralized analytics platforms.
- Edge computing architectures:Latency-sensitive fleet management applications are driving geofencing workloads onto roadside and vehicle-embedded processors.
Market Restraints
- Specialized talent scarcity:Complex polygon overlay and hotspot detection services require GIS-trained data scientists, with accredited programs producing insufficient annual graduates.
- Spectrum allocation bottlenecks:Federal Communications Commission licensing delays for precision positioning infrastructure constrain centimeter-accuracy service rollouts.
- Capital intensity of edge hardware:Distributed sensor networks and roadside computing nodes demand upfront hardware investment that conflicts with municipal budget cycles.
Strategic Opportunities
- India smart city mission:Urban local bodies are tendering integrated command-and-control centers with embedded location intelligence modules.
- Convergence of computer vision and LiDAR:Autonomous vehicle perception stacks are generating training datasets that enhance pedestrian flow prediction accuracy.
- Subscription-based platform licensing:Mid-market retailers are abandoning perpetual GIS licenses for monthly SaaS arrangements with embedded footfall analytics.
Industry Challenges
- Legacy system integration friction:Enterprise ERP and warehouse management systems require custom API development to ingest real-time coordinate streams.
- ISO 19115 metadata standardization delays:Cross-border spatial data exchange remains hampered by inconsistent attribution schemas across national mapping agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Location Analytics Market |
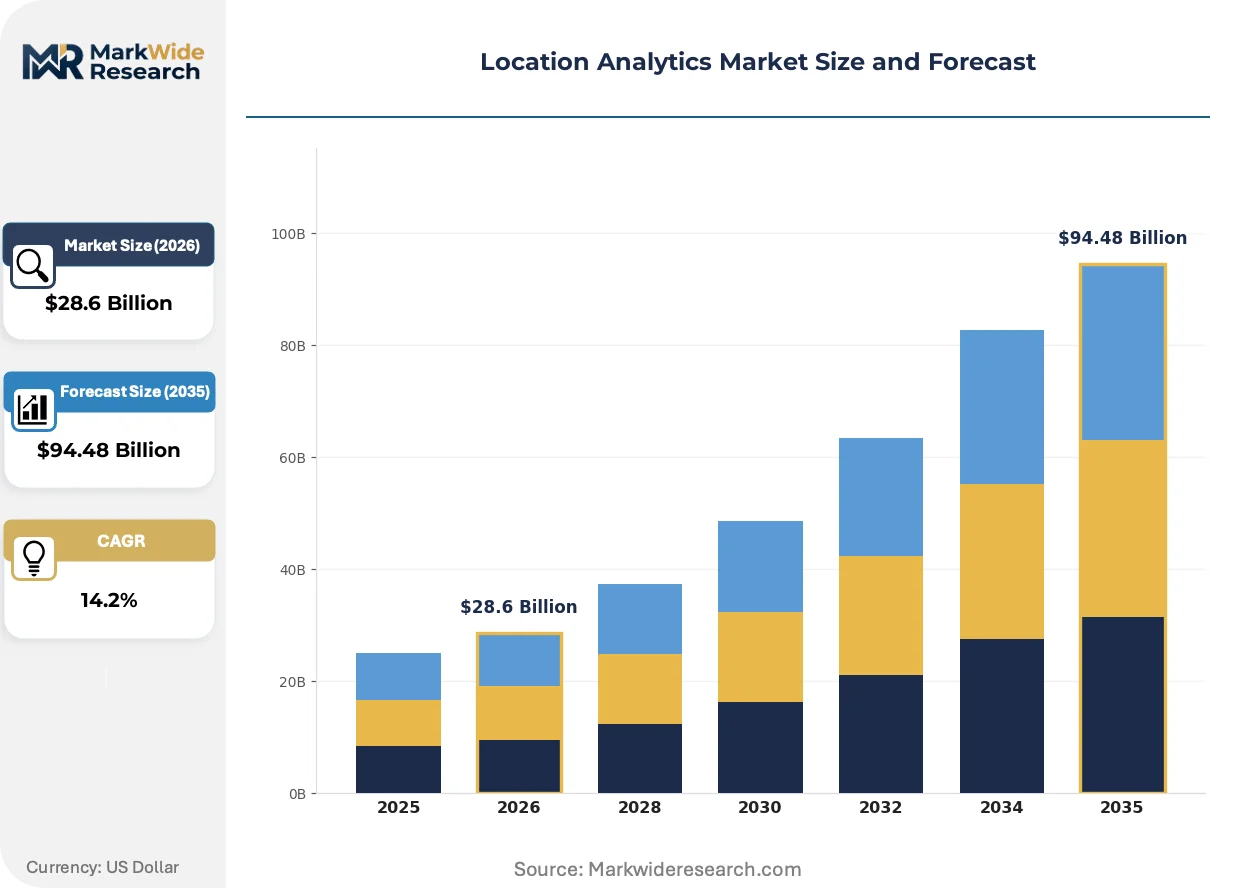
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Retail, Transportation, Healthcare, Government Solution: Mapping, Geofencing, Spatial Analysis, Visualization Industry Vertical: Real Estate, Logistics, Marketing, Entertainment |
| Companies Covered | Esri, Google LLC, Microsoft Corporation, IBM Corporation, SAS Institute, Cisco Systems, Oracle Corporation, TomTom, HERE Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Location Analytics Market Emerging Trajectories
Real-time stream processing architectures are displacing batch-oriented spatial analysis, compressing insight latency from hours to seconds. This shift demands fundamental redesign of indexing algorithms and memory hierarchies.
Digital twin environments for urban corridors are decomposing traditional static mapping business models. City planning departments in Singapore and Dubai are deploying persistent virtual replicas that synchronize with live traffic and pedestrian feeds. These implementations compress the feedback loop between infrastructure modification and impact assessment, reducing reliance on expensive physical pilot programs.
The EU AI Act risk classification framework is forcing geospatial AI vendors to document training data provenance and decision logic for high-risk applications. Automated credit scoring and emergency dispatch routing systems face mandatory conformity assessments before European deployment. Vendors are responding by partitioning product architectures to isolate explainable components from black-box prediction modules.
Retailers are consolidating vendor relationships around integrated location intelligence suites rather than assembling point solutions. Department store chains and quick-service restaurant operators now expect footfall analytics, competitive benchmarking, and site selection tools within unified platforms. This preference consolidation is most visible in United States and United Kingdom markets where procurement teams hold concentrated negotiating leverage.
Location Analytics Market Segmentation
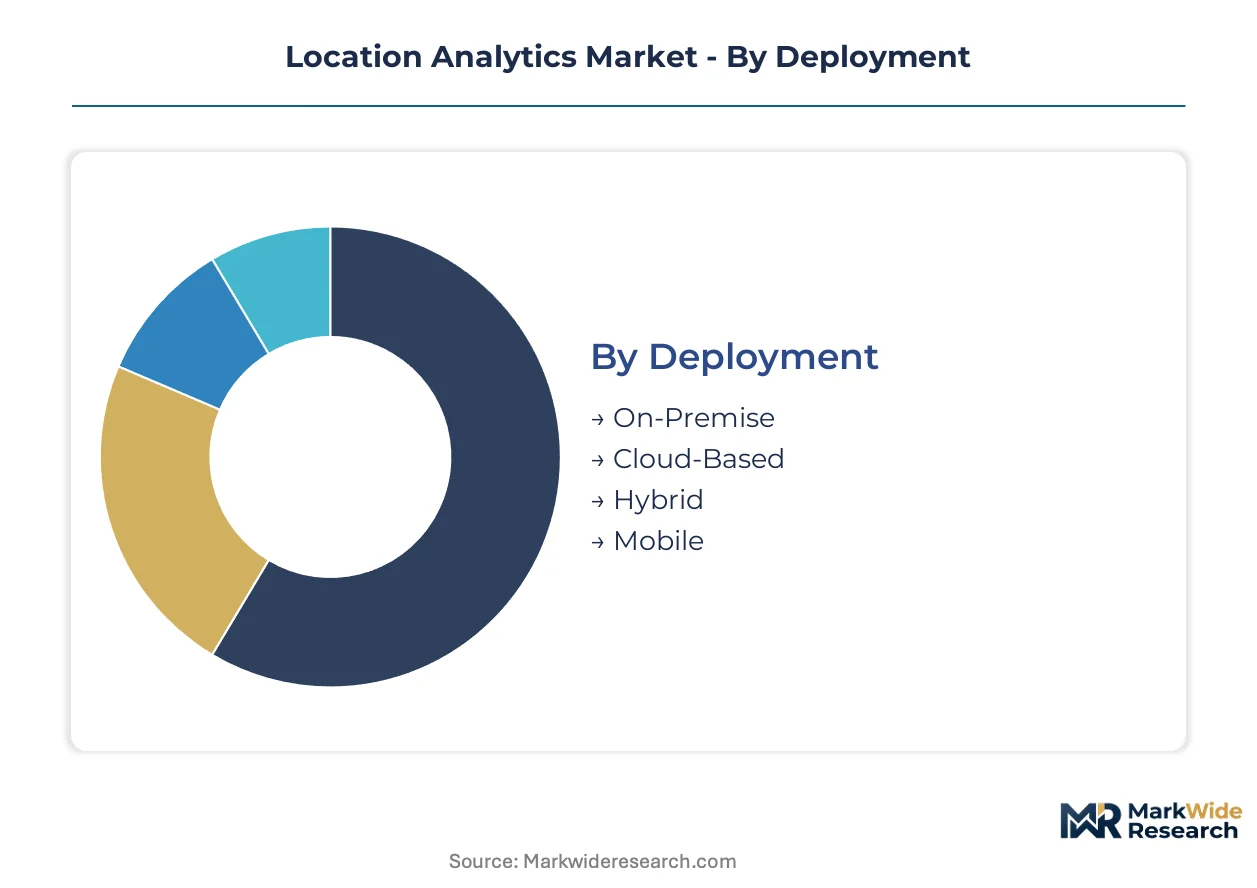
Deployment architecture determines pricing elasticity and customer lifetime value in location analytics procurement. End-user concentration shapes feature roadmaps and sales channel investments. Solution type and vertical focus dictate talent requirements and partnership ecosystems.
Deployment:
Cloud-based deployments dominate North American and Western European adoption curves, while on-premise retains preference in regulated Asian and Middle Eastern jurisdictions with data sovereignty constraints.
- On-Premise:Organizations in Saudi Arabia and the UAE mandate local server infrastructure for sensitive geospatial intelligence under national cybersecurity frameworks. Defense contractors and critical infrastructure operators in these markets absorb capital intensity to maintain air-gapped positioning systems.
- Cloud-Based:Elastic consumption models now capture mid-market retail chains and municipal governments across the United States, Germany, and Australia. Microsoft Azure and Amazon Web Services native integrations accelerate procurement cycles by bundling location services with existing enterprise cloud contracts.
- Hybrid:German automotive manufacturers and Japanese logistics conglomerates partition workloads—sensitive fleet data remains on-premise while crowd-sourced traffic analytics shift to cloud.
- Mobile:Field service management applications in Brazil and Indonesia drive smartphone-embedded geofencing for distributed workforces with limited desktop access.
Cloud-based holds the largest share; momentum sits with hybrid architectures bridging sovereignty and scalability demands.
End User:
Retail and transportation sectors concentrate procurement volume, while healthcare and government segments command premium pricing through compliance complexity.
- Retail:United States department store chains and quick-service restaurant operators deploy footfall pattern analysis for site selection and layout optimization. Real-time competitive benchmarking tools now standard in procurement specifications for national rollouts.
- Transportation:European logistics operators under EU AI Act jurisdiction require algorithmic transparency documentation for automated routing decisions. Fleet management platforms integrate roadside edge processors to compress geofencing alert latency below 100 milliseconds.
- Healthcare:Hospital systems in the United Kingdom and Canada track patient flow and equipment positioning to reduce emergency department bottlenecks. HIPAA and PIPEDA compliance requirements extend procurement cycles but protect incumbent vendor relationships.
- Government:Indian urban local bodies tender integrated command-and-control centers through the Smart Cities Mission. Singapore and Dubai planning departments deploy persistent digital twin environments synchronized with live pedestrian and traffic feeds.
Retail commands the deepest vendor relationships; healthcare represents the steepest expansion trajectory as compliance frameworks mature.
Solution:
Specialized talent scarcity protects margin pools in spatial analysis, while geofencing commoditization accelerates through open-source libraries.
- Mapping:Base layer visualization now standard in enterprise software suites, compressing standalone procurement. Esri maintains pricing power in United States federal and defense accounts through decades of proprietary geodatabase investment.
- Geofencing:Automated perimeter alerting captures disproportionate growth from logistics operators managing cross-border fleet movements. European carriers face EU AI Act conformity requirements for automated detention and route deviation decisions.
- Spatial Analysis:Complex polygon overlay and hotspot detection services require GIS-accredited data scientists. University programs in the United States, Netherlands, and Australia produce insufficient annual graduates to meet commercial and government demand.
- Visualization:Self-service dashboard adoption spreads among mid-market retailers in the United Kingdom and France, reducing dependency on specialized analytics teams.
Spatial analysis retains the highest margin structure; geofencing is gaining share fastest through logistics automation mandates.
Industry Vertical:
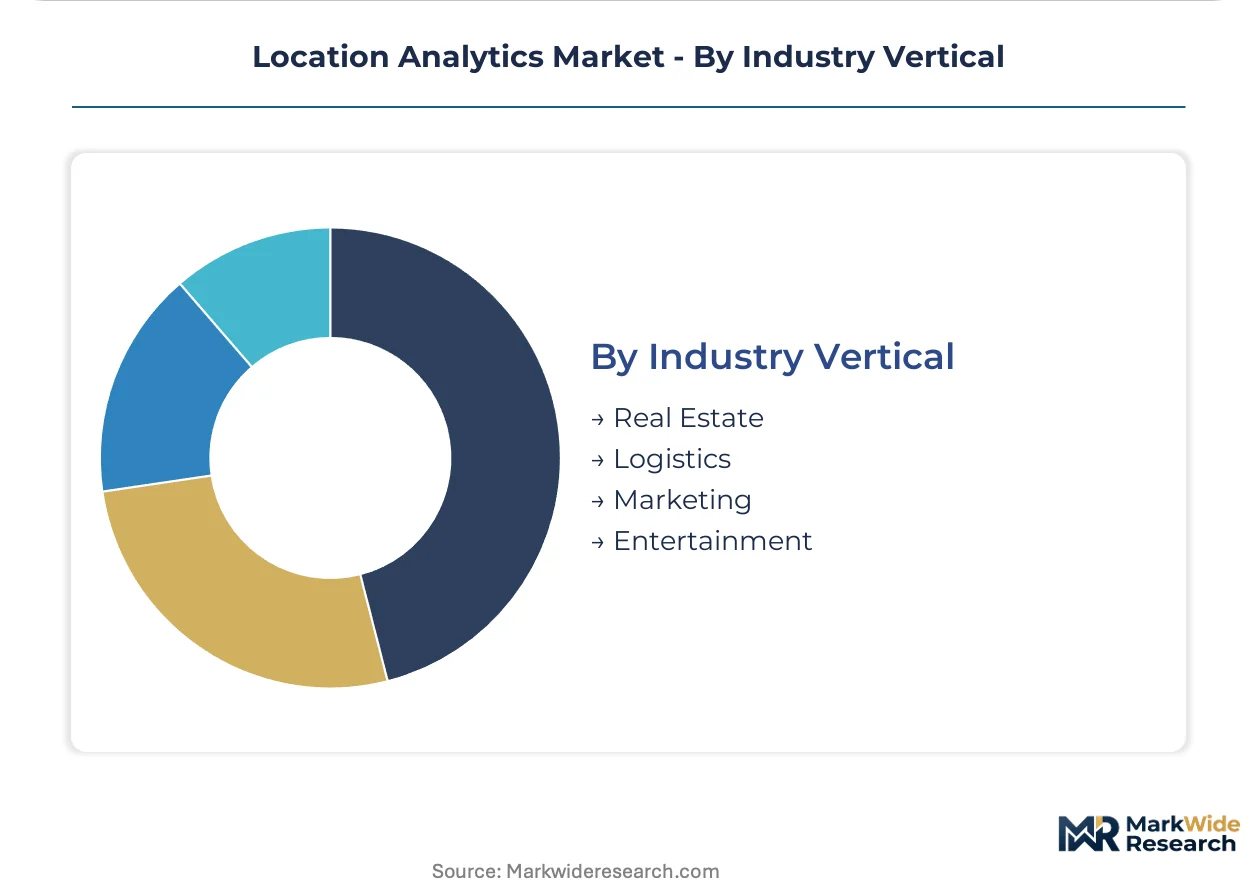
Logistics and real estate concentrate procurement scale, while marketing and entertainment segments drive innovation in consumer-facing applications.
- Real Estate:Investment trusts and development firms in the United States and United Kingdom integrate demographic migration patterns with construction pipeline data. Singapore sovereign wealth funds deploy location intelligence for portfolio diversification across Asian emerging markets.
- Logistics:Third-party providers in Germany and the Netherlands optimize last-mile routing through real-time traffic ingestion and predictive demand clustering. Edge computing investments at distribution hubs reduce cloud egress costs for high-frequency coordinate streams.
- Marketing:Consumer brands in Brazil and Mexico leverage anonymized mobile location signals for competitive store visit analysis. Privacy regulations in European markets constrain equivalent deployment.
- Entertainment:Theme park operators in Florida and California synchronize queue management with dynamic pricing algorithms. Venue operators in Las Vegas deploy guest flow prediction to optimize concession and gaming floor layouts.
Real estate anchors procurement volume; marketing climbs fastest as privacy-preserving signal processing matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net services exports concentrate in the United States and Germany, while import dependency for positioning infrastructure components shapes procurement strategies across emerging markets. Municipal digitization programs and automotive manufacturing clusters drive differential growth trajectories. Regulatory fragmentation around data sovereignty and AI governance fragments vendor standardization efforts.
United States
Municipal governments in Chicago and Los Angeles deploy sensor networks for traffic optimization and emergency response routing. FCC spectrum allocation rules govern precision positioning infrastructure for centimeter-accuracy services. Silicon Valley cloud providers anchor platform development, bundling location services with federal and enterprise contracts.
Germany
Automotive manufacturers in Stuttgart and Wolfsburg integrate real-time fleet analytics with predictive maintenance systems. EU AI Act conformity requirements mandate algorithmic transparency documentation for automated routing decisions. Bavarian logistics operators invest in edge computing nodes to compress geofencing latency below regulatory thresholds.
India
Urban local bodies in Mumbai and Bengaluru tender integrated command-and-control centers through the Smart Cities Mission. BIS standards condition interoperability for cross-municipal spatial data exchange. Telangana's Hyderabad cluster concentrates SaaS platform development for footfall analytics serving retail expansion.
Singapore
Planning departments deploy persistent digital twin environments synchronized with live pedestrian and traffic feeds. National cybersecurity frameworks mandate local data residency for sensitive geospatial intelligence. The Jurong Lake District serves as testbed for autonomous vehicle perception stack integration with pedestrian flow prediction.
United Arab Emirates
NEOM and Dubai South integrate location intelligence into master planning for logistics corridors and entertainment districts. MOHAP and national cybersecurity frameworks require air-gapped server infrastructure for defense and critical infrastructure operators. Abu Dhabi's Masdar City anchors smart district implementations with embedded spatial analysis modules.
Location Analytics Market Vendor Landscape
Concentration sits with enterprise-grade platform operators possessing decades of proprietary geodatabase investment. The vendor base stratifies across three tiers: cloud-native hyperscalers leveraging consumer data pipelines, specialized GIS incumbents defending federal and defense accounts, and mid-market SaaS providers assembling integrated location intelligence suites. Dominant competitive moves include strategic partnerships bundling location services with enterprise cloud contracts and portfolio diversification into real-time edge analytics.
Within the enterprise GIS tier, Esri and HERE Technologies represent archetypes of proprietary spatial database investment and automotive mapping data aggregation respectively. Google LLC exemplifies the hyperscaler approach, converting consumer mapping infrastructure into mid-market platform offerings. Microsoft Corporation anchors the cloud-native integration vector, embedding location services within Azure-native enterprise contracts.
| Leading Market Players |
|---|
| Esri |
| Google LLC |
| Microsoft Corporation |
| IBM Corporation |
| SAS Institute |
| Cisco Systems |
| Oracle Corporation |
| TomTom |
| HERE Technologies |
| Others |
Supply Flow & Price Mechanics
Consumption-based SaaS contracts lock in multi-year revenue visibility for location analytics vendors while ceding pricing power to municipal procurement officers and retail chain CIOs who aggregate demand across hundreds of sites. These arrangements bundle geofencing, spatial analysis, and visualization modules into single platform subscriptions, compressing standalone solution margins.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structures across premium, standard, and economy levels. Premium tiers command certification-grade algorithmic transparency documentation for EU AI Act compliance, while standard tiers serve mid-market retailers with pre-configured footfall dashboards. Price differentiation rests on ISO 19115 metadata standardization and vertical integration depth. Cost compression in economy tiers is intensifying because open-source spatial libraries erode proprietary geodatabase moats. Municipal governments exhibit highest price sensitivity due to budget cycle constraints, whereas defense contractors absorb premium pricing for air-gapped sovereignty compliance.
Supply Chain Analysis
Strategic stockpiling of precision positioning chipsets and LiDAR sensor arrays dominates procurement behavior among German automotive manufacturers and Singaporean smart city authorities. Hardware supply concentrates in Taiwan, South Korea, and the United States for semiconductor-dependent edge processors. Raw material dependencies span rare earth elements for magnetometers, optical-grade silicon for photonic sensors, and high-purity germanium for thermal imaging. Single-source vulnerability in precision GNSS receiver modules threatens continuity. Distribution runs through hyperscaler cloud marketplaces and specialized GIS channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as United States retail chains consolidate vendor relationships around integrated location intelligence suites, fragmenting procurement across dozens of point-solution providers.
For Market Incumbents: Fortify proprietary geodatabase moats through accelerated ISO 19115 certification investment and backward integration into edge computing hardware production. Esri and HERE Technologies face hyperscaler encroachment on mid-market accounts; channel control through exclusive municipal procurement frameworks remains the critical defensive lever. For New Entrants and Emerging Players: Lead with India Smart Cities Mission tenders for integrated command-and-control centers, where incumbent presence remains underdeveloped. White-space targets include Brazilian field service management applications and Indonesian mobile-first geofencing deployments. A channel partnership with Microsoft Azure or Amazon Web Services accelerates enterprise procurement cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform operators with embedded footfall analytics modules. Long-term viability hinges on regulatory compliance service attach rates as EU AI Act enforcement tightens. Acquisition targets should demonstrate algorithmic transparency documentation capabilities. The signal to watch is FCC spectrum allocation acceleration for centimeter-accuracy positioning infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Algorithmic transparency documentation unlocks European logistics and government procurement. |
| Edge Computing Hardware Integration | Roadside processor deployment compresses geofencing latency below 100 milliseconds for fleet operators. |
| Digital Twin Environment Development | Singapore and Dubai planning departments synchronize live feeds with persistent urban replicas. |
| Hybrid Cloud-Edge Architecture Launch | German automotive manufacturers partition sensitive fleet data on-premise while shifting crowd-sourced analytics to cloud. |
| Strategic Partnership with Hyperscaler | Azure-native integration bundles location services with existing enterprise cloud contracts. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of municipal procurement databases, hyperscaler capex disclosures, and FCC spectrum allocation records. Interviews with smart city planning officers, GIS platform engineers, retail site selection analysts, and logistics fleet managers inform demand-side validation. SEC filings from Esri and HERE Technologies, EU AI Act implementation guidance, and BIS standardization documents provide supply-side triangulation. Bottom-up deployment modeling and top-down market sizing converge across the analysis window.
Segmentation dimensions modeled span deployment architecture, end-user vertical, solution type, and geographic regulatory cluster. CAGRs derive from elasticity-adjusted adoption curves and replacement cycle analysis. Forecast inputs include municipal digitization budget trajectories, precision positioning infrastructure rollout timelines, and EU AI Act enforcement intensity assumptions throughout the forecast period.
The analysis sits within stated boundaries; outcomes outside sustained smart city investment levels or accelerated spectrum allocation would require recalibration. Forecasts reflect documented assumptions on cloud migration velocity and edge hardware cost curves. Revision becomes warranted when EU AI Act conformity assessment backlogs cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Enterprise Data Visualization Platform Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Statistical Analytics Market
Analytics
India Geospatial Analytics Market
Analytics
Germany Geospatial Analytics Market
Analytics
SME Big Data Market
Analytics
Regression Analysis Tool Market
Analytics
Advanced Analytics Market
Analytics
Load (ETL) Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Spain Geospatial Analytics Market
Analytics
Asia-Pacific Edge Analytics Market
Analytics
Face Analytics Market
Analytics
Global Data Fusion Market
Analytics
Middle East and Africa Location Analytics Market