
 Face Analytics Market | 2026-2036
Face Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Face Analytics Market Insights
Enterprise security buyers is collapsing toward cloud-native deployment models as legacy on-premises systems face integration bottlenecks. Amazon Web Services leverages its Rekognition platform to anchor government and commercial contracts through FedRAMP authorization and pre-trained model accessibility. Microsoft competes by embedding face analytics within Azure AI services, sustaining enterprise stickiness through bundled cloud productivity ecosystems. NEC Corporation dominates specialized public safety installations, particularly in transportation hubs where real-time identification throughput requirements exceed generalist platform capabilities.
Face analytics encompasses computer vision systems that extract, encode, and classify human facial features using convolutional neural networks operating on 128-dimensional embedding vectors for identity matching and attribute inference. These systems process visible-spectrum or near-infrared imagery to enable automated verification, emotion classification, age estimation, and gaze tracking across security, retail, and healthcare workflows. Deep learning architectures lead the technology segment due to superior accuracy on unconstrained face datasets, while edge computing deployment is expanding fastest where latency constraints and data sovereignty concerns limit cloud transmission. Emotion recognition applications command premium pricing in customer experience optimization, though facial recognition for access control occupies the largest revenue pool through recurring enterprise licensing.
The EU AI Act imposes conformity assessments and CE marking obligations on high-risk biometric systems, restricting market access for non-compliant vendors across European member states. In the United States, NIST Face Recognition Vendor Test protocols shape procurement standards for federal agencies, while state-level biometric privacy laws in Illinois, Texas, and Washington create fragmented compliance terrain. China's SAMR and cyberspace administration enforce algorithmic recommendation and deep synthesis provisions that govern domestic face analytics deployment. Stakeholders must monitor regulatory divergence between permissive commercial environments and restrictive biometric governance frameworks to anticipate market access constraints and product localization investments.
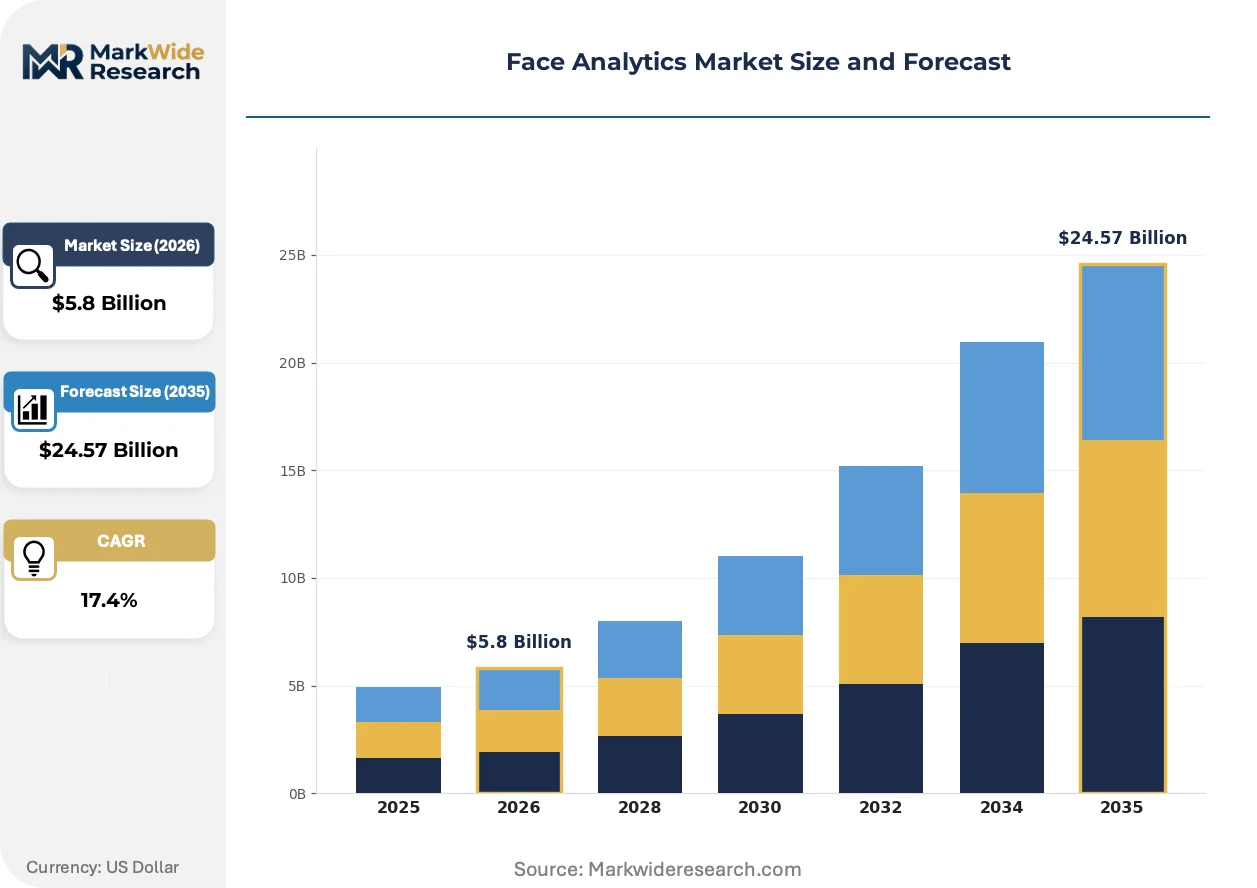
Market Dynamics
Cloud-native deployment architectures are displacing legacy on-premises face analytics infrastructure as enterprise buyers prioritize API accessibility and elastic compute scaling over capital-intensive hardware procurement cycles.
Growth Catalysts
- FedRAMP Authorization:Federal cloud security certification unlocks government procurement pipelines for compliant vendors across United States defense and civilian agencies.
- Edge AI Chipsets:Dedicated neural processing units from semiconductor specialists enable real-time inference at network peripheries without latency-heavy cloud transmission.
- Transportation Security:Airport authorities and mass transit operators deploy biometric boarding gates to accelerate passenger throughput while reducing staffing overhead.
Market Restraints
- GPU Supply Concentration:Training-grade graphics processing unit availability remains bottlenecked by Taiwan-based foundry capacity allocation and export control restrictions.
- Biometric Privacy Litigation:Illinois Biometric Information Privacy Act exposes deployers to statutory damages per violation, chilling retail and commercial adoption.
- Algorithmic Bias Liability:Demographic performance disparities in NIST Face Recognition Vendor Test protocols create legal exposure and procurement disqualification risk.
Strategic Opportunities
- Healthcare Patient Matching:Hospital systems seek face-based identity verification to eliminate duplicate records and reduce medical errors during intake workflows.
- EU AI Act Conformity:Early compliance with high-risk biometric system requirements creates first-mover positioning in European public sector tenders.
- 3D Sensing Convergence:Integration of structured light and time-of-flight depth sensors with convolutional networks enables liveness detection and spoof resistance.
Industry Challenges
- Adversarial ML Expertise:Defending against presentation attacks and deepfake injection requires specialized machine learning security talent in short supply.
- Legacy Access Control Integration:Retrofitting biometric authentication into existing physical security infrastructure demands custom middleware development and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Analytics Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $24.57 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Deep Learning, Machine Learning, Neural Networks, Image Processing End User: Retail, Healthcare, Security, Entertainment Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Application: Emotion Recognition, Facial Recognition, Demographic Analysis, Behavioral Analytics |
| Companies Covered | Amazon Web Services, Microsoft, NEC Corporation, Thales Group, IDEMIA, Megvii, FacePhi, Aware, Inc., Clarifai, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Analytics Market Trends and Innovations
Synthetic data generation and federated learning architectures are reshaping how face analytics systems acquire training diversity without centralized biometric data aggregation.
Transformer-based vision architectures are bifurcating performance benchmarks for unconstrained face recognition, with enterprise security teams adopting self-attention models for low-quality surveillance imagery while consumer applications retain lighter convolutional backbones. Cloud service providers embed these architectures through managed APIs, compressing time-to-deployment for non-specialist development teams. The technology is bifurcating vendor tiers between generalist platform operators and specialized accuracy-optimized solution providers.
The EU AI Act's high-risk biometric system classification imposes conformity assessment and CE marking obligations that reshape European procurement specifications. Vendors must maintain technical documentation, risk management systems, and human oversight protocols to access member state public contracts. French CNIL and German data protection authorities are interpreting these requirements with varying enforcement intensity, creating compliance fragmentation despite harmonized framework text.
Enterprise buyers now unbundle software licensing from hardware procurement, preferring subscription-based consumption models with usage-tiered pricing. Systems integrators and value-added resellers lose margin to direct cloud API relationships as procurement authority consolidates within central IT functions. United States federal agencies exemplify this shift through blanket purchase agreements with authorized cloud marketplaces rather than traditional defense contractor channels.
Face Analytics Market Segmentation
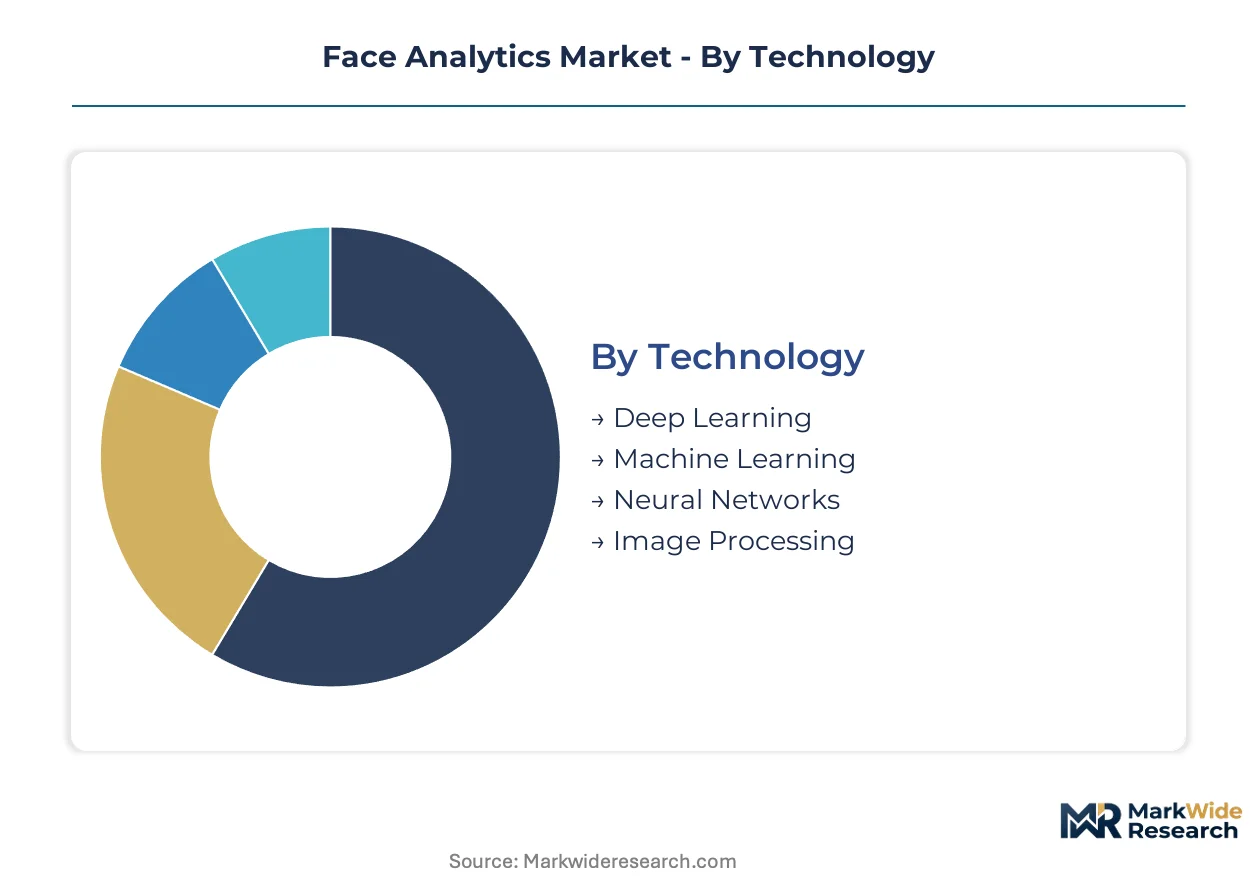
Face analytics vendors configure product architectures around four intersecting dimensions that determine pricing power and integration complexity. Technology selection dictates inference accuracy and computational requirements, while deployment mode shapes data sovereignty compliance and latency performance. Application focus and end-user verticals drive divergent R&D investments and regulatory exposure.
Technology:
Convolutional architectures face substitution pressure from transformer-based vision models in unconstrained imaging scenarios, though hardware optimization constraints preserve incumbent positions in edge deployments.
- Deep Learning:Multi-layer neural architectures extract hierarchical facial features through backpropagation-optimized convolutional filters, enabling state-of-the-art performance on NIST Face Recognition Vendor Test benchmarks. Federal security agencies in the United States concentrate procurement here for surveillance applications where false acceptance rates must fall below 0.1% at scale.
- Neural Networks:Feedforward and recurrent architectures process 128-dimensional embedding vectors for identity matching, with transportation authorities deploying these systems for real-time passenger throughput optimization at airport boarding gates. Training data diversity requirements create compliance friction under EU AI Act high-risk biometric system classifications.
- Machine Learning:Classical statistical methods including support vector machines and random forests persist in resource-constrained environments where model interpretability outweighs accuracy maximization.
- Image Processing:Traditional computer vision techniques without learned representations serve legacy access control retrofits and low-cost consumer applications where hardware limitations preclude deep learning inference.
Deep learning retains volume leadership; neural networks hold the steepest expansion curve.
End User:
Cost tier stratification separates enterprise security budgets from constrained healthcare IT spending, with retail applications commanding intermediate pricing through customer experience ROI metrics.
- Security:Government agencies and border control authorities deploy biometric verification infrastructure for identity assurance and watchlist screening, with FedRAMP authorization gating United States federal procurement pipelines.
- Healthcare:Hospital systems implement face-based patient matching to eliminate duplicate electronic health records and reduce medical errors during intake workflows, though HIPAA compliance constrains cloud transmission architectures.
- Retail:Customer experience optimization drives emotion recognition deployments for sentiment analysis and demographic profiling, with Illinois Biometric Information Privacy Act exposure chilling adoption in the United States.
- Entertainment:Gaming and streaming platforms leverage face analytics for personalized content recommendation and accessibility features, prioritizing low-latency edge inference over cloud-dependent processing.
Security dominates revenue concentration; healthcare is expanding most quickly.
Deployment:
Geography-sensitive data residency requirements fragment procurement patterns, with European enterprises favoring on-premises and hybrid configurations to satisfy GDPR and EU AI Act localization mandates.
- Cloud-Based:API-accessible managed services from hyperscale providers enable elastic compute scaling and rapid deployment for non-specialist development teams, though latency constraints limit real-time surveillance applications.
- Edge Computing:Dedicated neural processing units enable on-device inference without network transmission, serving transportation hubs and healthcare facilities where data sovereignty concerns block cloud architectures.
- Hybrid:Distributed processing splits inference workloads between edge preprocessing and cloud refinement, balancing latency requirements against model complexity demands.
- On-Premises:Self-hosted infrastructure persists in defense and intelligence applications where air-gapped security requirements preclude any external connectivity.
Cloud-based deployments retain volume leadership; edge computing gains share fastest.
Application:
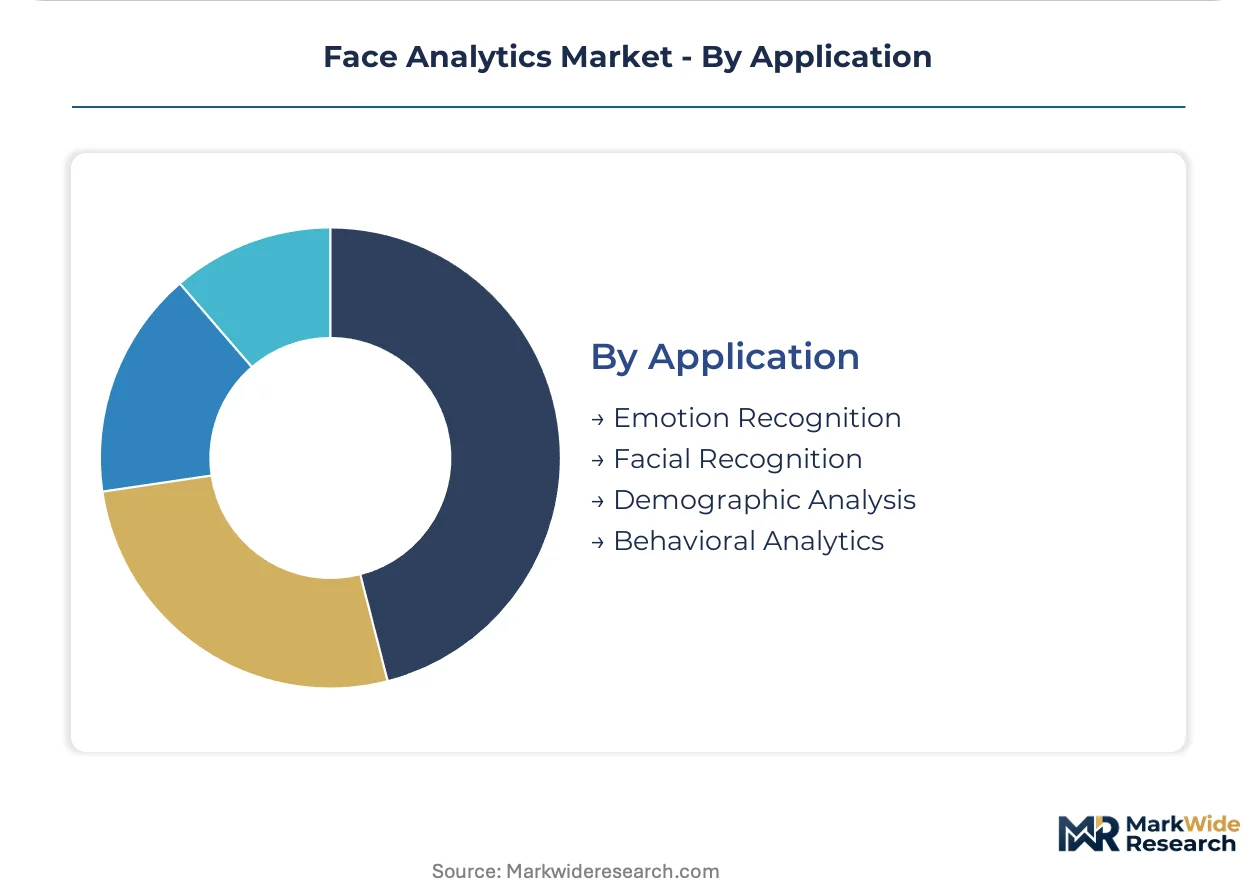
Customer type divergence separates enterprise security buyers seeking identity verification from marketing departments pursuing behavioral analytics, with emotion recognition commanding premium pricing through customer experience optimization value propositions.
- Facial Recognition:One-to-one verification and one-to-many identification systems anchor enterprise security and public safety procurement, generating recurring licensing revenue through access control and surveillance integrations.
- Emotion Recognition:Affective computing classifies facial expressions into discrete emotional states for retail customer experience optimization and healthcare patient monitoring, though algorithmic bias liability creates legal exposure under demographic performance scrutiny.
- Demographic Analysis:Age estimation, gender classification, and ethnicity inference serve marketing analytics and content personalization, facing heightened regulatory restriction in European jurisdictions.
- Behavioral Analytics:Gaze tracking and attention measurement optimize digital signage placement and retail layout design, with 3D sensing convergence enabling liveness detection and presentation attack resistance.
Facial recognition retains volume leadership; emotion recognition holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based cloud providers export face analytics platforms to European and Asia-Pacific enterprise buyers, while Chinese semiconductor foundries supply neural processing units to edge device manufacturers worldwide.
United States
Federal security contracts and commercial retail deployments drive platform investments across defense agencies and Fortune 500 enterprises. NIST Face Recognition Vendor Test protocols shape procurement standards for civilian and intelligence applications. Silicon Valley clusters anchor hyperscale cloud development, with Seattle-based providers capturing government FedRAMP-authorized workloads.
China
Domestic surveillance infrastructure and smart city initiatives absorb substantial face analytics capacity from state-directed technology procurement. SAMR and cyberspace administration enforce algorithmic recommendation and deep synthesis provisions governing deployment. Shenzhen hardware ecosystems integrate neural processing units with camera systems for transportation hub installations.
Germany
Automotive manufacturers and industrial automation buyers deploy face analytics for workforce safety and quality control applications. BSI technical guidelines and state-level data protection authorities interpret GDPR biometric processing restrictions with varying enforcement intensity. Munich security technology clusters develop edge-computing solutions for manufacturing floor deployments.
United Kingdom
Financial services and border control authorities accelerate biometric verification procurement for anti-fraud and passenger processing workflows. Information Commissioner's Office guidance constrains law enforcement deployment of live facial recognition in public spaces. London fintech corridors drive customer onboarding automation demand for digital identity verification.
Japan
Transportation operators and retail chains implement emotion recognition for passenger experience optimization and customer sentiment analysis. METI industrial policy supports AI adoption in service sectors through subsidized pilot programs. Tokyo-Osaka urban corridors concentrate deployment of biometric boarding systems at rail terminals and international airports.
Face Analytics Market Competitive Landscape
Player mix skews toward hyperscale cloud providers with substantial government contracting capabilities. Market structure concentrates around three tiers: infrastructure-as-a-service operators, specialized biometric solution vendors, and regional system integrators. Dominant competitive moves include FedRAMP authorization pursuit for federal pipeline access and edge AI chipset partnerships for latency-sensitive deployments.
Within the hyperscale tier, Amazon Web Services and Microsoft exemplify platform operators leveraging bundled cloud productivity ecosystems to sustain enterprise stickiness. NEC Corporation occupies a specialized position in public safety installations where real-time identification throughput requirements exceed generalist capabilities. Among European-headquartered providers, Thales Group and IDEMIA represent defense-contractor archetypes with established government security clearances and transportation infrastructure relationships.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| NEC Corporation |
| Thales Group |
| IDEMIA |
| Megvii |
| FacePhi |
| Aware, Inc. |
| Clarifai, Inc. |
| Others |
Pricing and Supply Chain Analysis
FedRAMP authorization gates both supply qualification and price differentiation simultaneously in the United States federal procurement pipeline, compressing margins for non-compliant vendors while enabling premium pricing for authorized cloud providers. Cloud-native deployment models accelerate this bifurcation as enterprise buyers abandon capital-intensive hardware procurement for subscription-based consumption.
Pricing Analysis
Next-generation transformer-based vision architectures command substantial premiums over legacy convolutional deployments, while prior-generation image processing solutions face accelerating price erosion in commodity access control retrofits. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized hyperscale platforms from specialized accuracy-optimized vendors and regional system integrators. Cost compression in edge computing hardware intensifies as neural processing unit supply expands from Taiwan-based foundries. Healthcare IT departments exhibit highest price sensitivity due to constrained capital budgets, while defense agencies demonstrate lowest sensitivity given mission-critical throughput requirements.
Supply Chain Analysis
Container availability constraints on Asia-Pacific to North America trade lanes elevate inbound logistics costs for neural processing unit shipments from Taiwan-based foundry clusters. Supply concentrates in Taiwan for advanced semiconductor fabrication, China for camera module assembly, and the United States for cloud infrastructure deployment. Raw material dependencies span silicon wafers, rare earth elements for sensor components, and specialized optical glass. Single-source vulnerability in Taiwan-based GPU foundry capacity creates structural supply chain risk. Distribution runs through authorized cloud marketplaces for federal procurement and systems integrator channels for specialized public safety installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Behavioral biometrics and passwordless authentication architectures threaten substitution for face analytics in customer experience and access control applications, forcing incumbents to defend through accuracy differentiation and regulatory compliance moats.
For Market Incumbents: Secure FedRAMP authorization to maintain federal pipeline access against emerging cloud competitors, while deepening vertical integration into edge AI chipset partnerships to defend latency-sensitive transportation hub deployments. Algorithmic bias liability under NIST Face Recognition Vendor Test protocols threatens disqualification risk for vendors with demographic performance disparities. For New Entrants and Emerging Players: EU AI Act conformity assessment fast-track creates first-mover positioning in European public sector tenders where incumbent compliance documentation remains incomplete. Healthcare patient matching applications represent the most penetrable segment given HIPAA-constrained cloud transmission requirements and incumbent platform inflexibility. Target mid-tier hospital systems through direct API relationships that bypass systems integrator margin extraction. For Investors and Strategic Acquirers: The EU AI Act's high-risk biometric system classification reshapes the acquisition landscape toward vendors with established conformity assessment infrastructure and member state regulatory relationships. Long-term viability centers on platforms with durable government security clearances and transportation infrastructure relationships rather than generalist cloud API providers. Watch NIST Face Recognition Vendor Test protocol updates as signal for federal procurement standard shifts that would elevate acquisition premiums for top-tier accuracy performers.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Pursuit | Unlocks United States federal procurement pipelines for defense and civilian agency contracts. |
| Edge AI Chipset Partnership | Enables real-time inference at transportation hubs without latency-heavy cloud transmission. |
| EU AI Act Conformity Investment | Creates first-mover positioning in European public sector biometric tenders. |
| Healthcare System Integration | Eliminates duplicate electronic health records through face-based patient matching workflows. |
| 3D Sensing Convergence Development | Integrates depth sensors with convolutional networks for liveness detection and spoof resistance. |
Research Methodology
A spread of perspectives from cloud platform engineers, federal procurement officers, hospital IT directors, and transportation authority technology leads converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation from NIST Face Recognition Vendor Test protocols, SEC filings from hyperscale providers, EU AI Act technical documentation, and hospital procurement databases. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across deployment modes and end-user verticals.
Segmentation dimensions modeled span technology generation, deployment architecture, application focus, and end-user vertical across the analysis window. Deep learning adoption curves, edge computing penetration rates, and regulatory compliance cost burdens informed CAGR derivation. Federal contract award patterns and European conformity assessment timelines served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained GPU foundry capacity allocation and stable NIST protocol standards; material deviation would warrant model refresh. Algorithmic bias litigation outcomes, export control expansion, and EU member state enforcement intensity variations constitute specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
App Analytics Market
Analytics
Global Telecom Analytics Market
Analytics
Text Analytics Market
Analytics
Europe Big Data and Business Analytics Market
Analytics
Construction Data Analytics Software Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
Global Mobile BI Market
Analytics
Canada Contact Center Analytics Market
Analytics
Global Operational Analytics Market
Analytics
Global Digital Intelligence Platform Market
Analytics
North America Operational Intelligence Market
Analytics
APAC Retail Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
Sentiment Analytics Market
Analytics
Complex Event Processing Market
Analytics
TV Analytics Solutions Market